Steady hiring, fewer layoffs
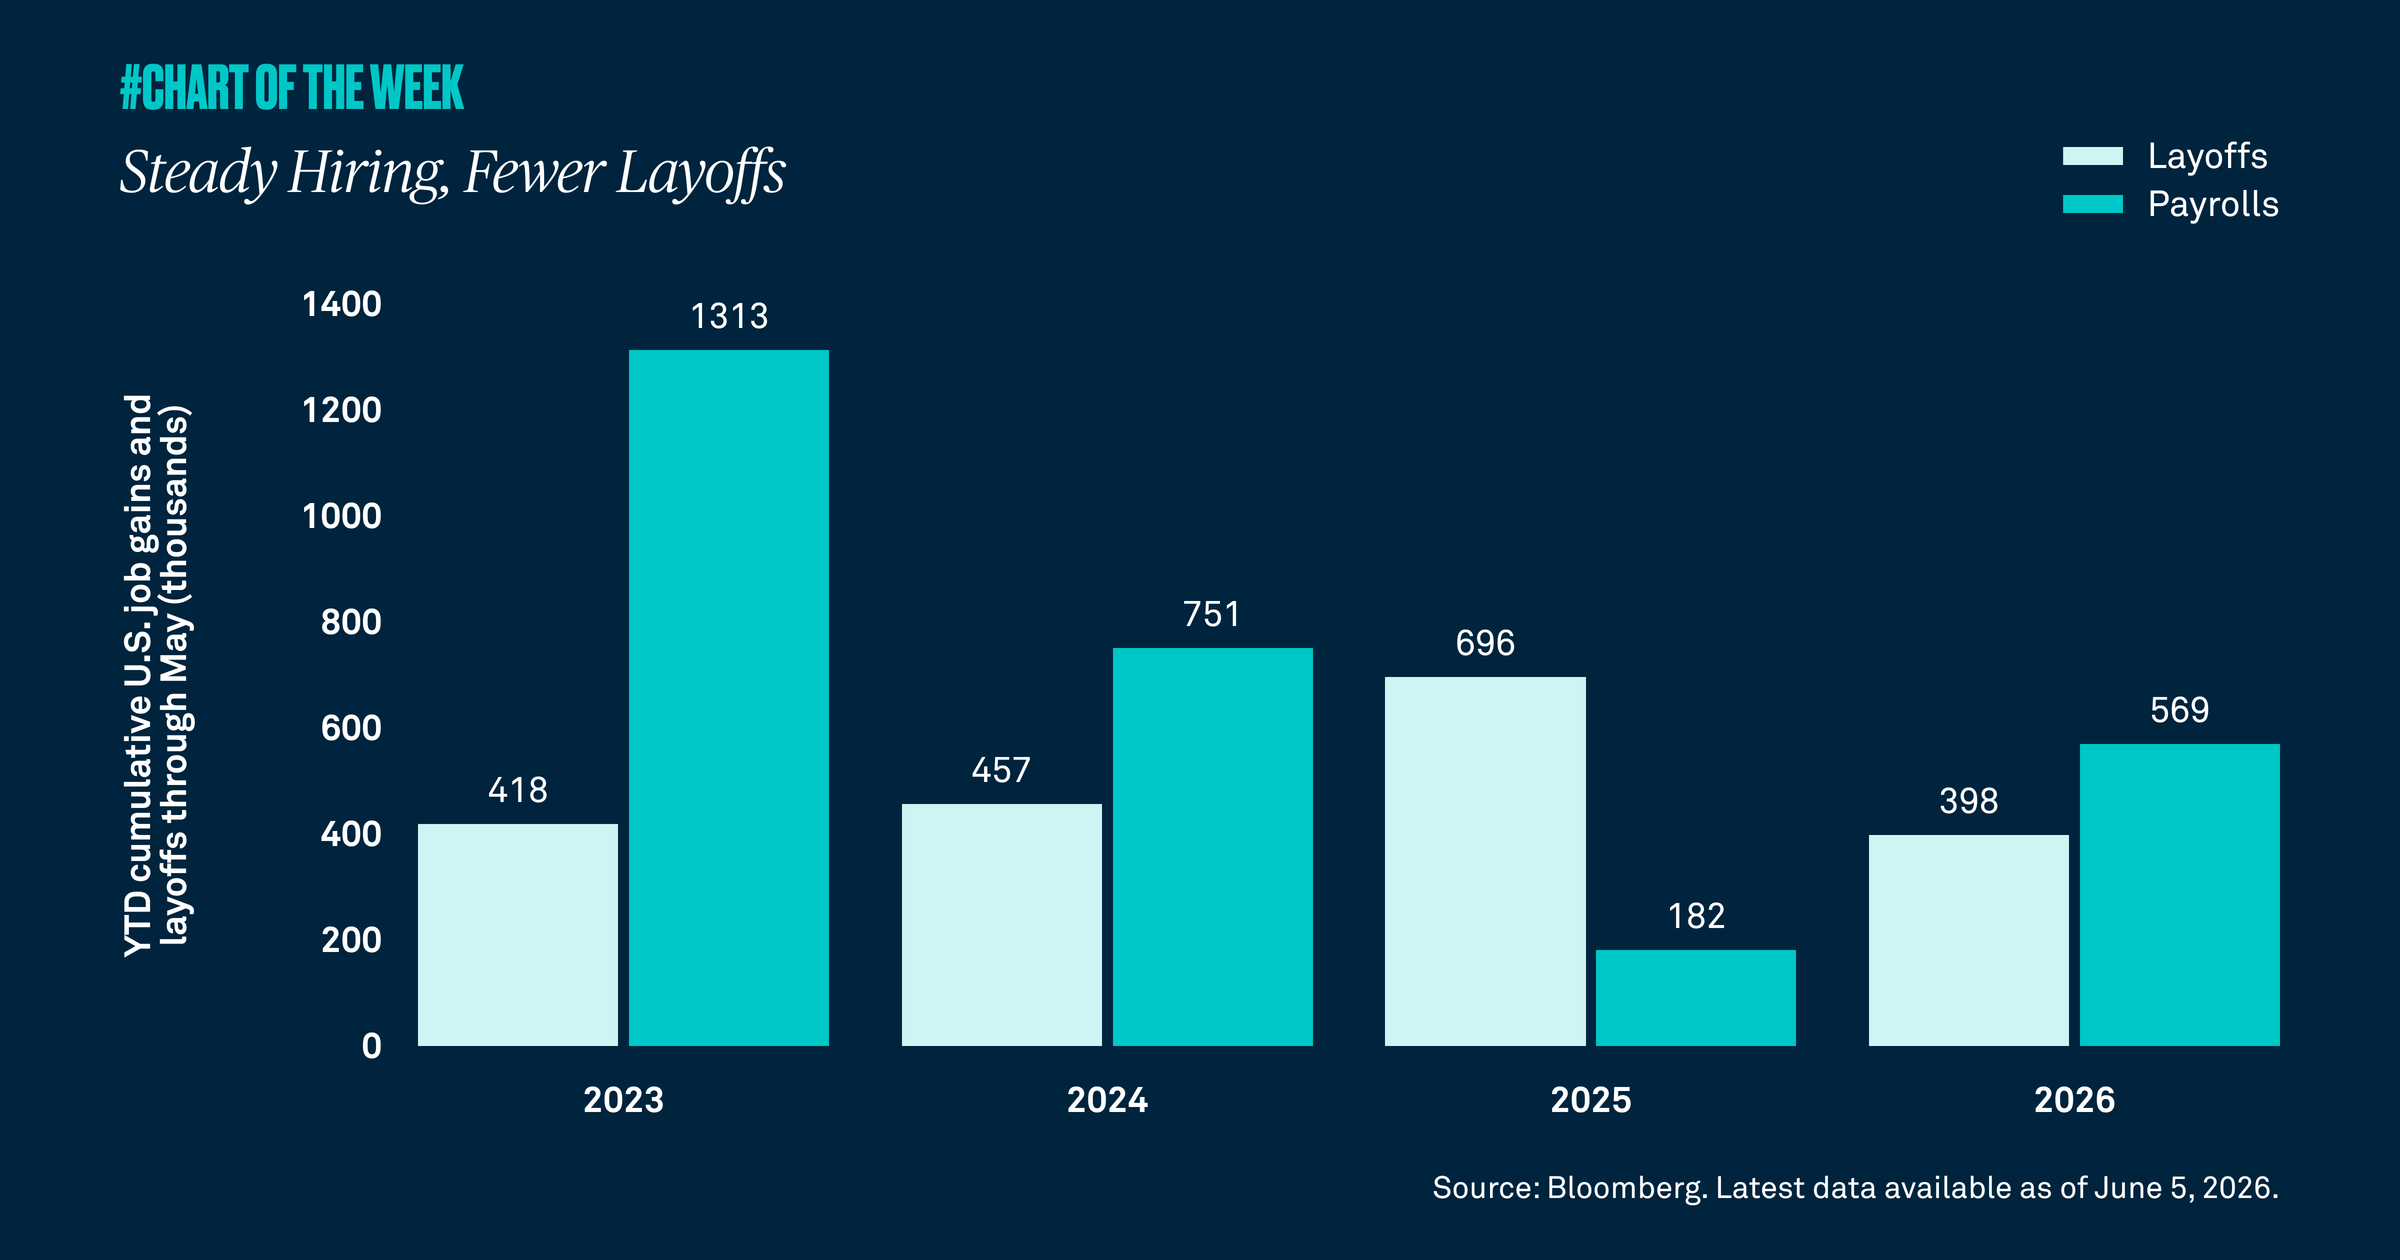
May’s jobs report showed a labor market that is improving, with payroll growth exceeding expectations and layoffs down sharply from last year. Steady hiring and fewer layoffs should continue to support consumer spending and U.S. economic growth.
 3 mins Reading time
Published on 09 June 2026


Last week’s jobs report showed that the U.S. labor market remains more resilient than expected. Nonfarm payrolls rose by 172,000 in May, well above consensus expectations for 88,000. Upward revisions to the prior two months also suggest hiring momentum has been firmer than initially reported, reinforcing the view that labor demand has held up despite ongoing geopolitical uncertainty.
So far, the labor market is better than last year. Year-to-date payroll gains total 569,000, compared with 182,000 over the same period in 2025. Layoffs have also moved in a more constructive direction. Year-to-date layoffs stand at 398,000, down sharply from 696,000 at this point last year.
Looking ahead, job growth is likely to settle into a more moderate range due to aging demographics and lower immigration. Still, as long as hiring continues and layoffs remain contained, consumer spending, the backbone of the U.S. economy, should remain positive.
949316 Exp : 09 June 2027
YOU MIGHT ALSO LIKE
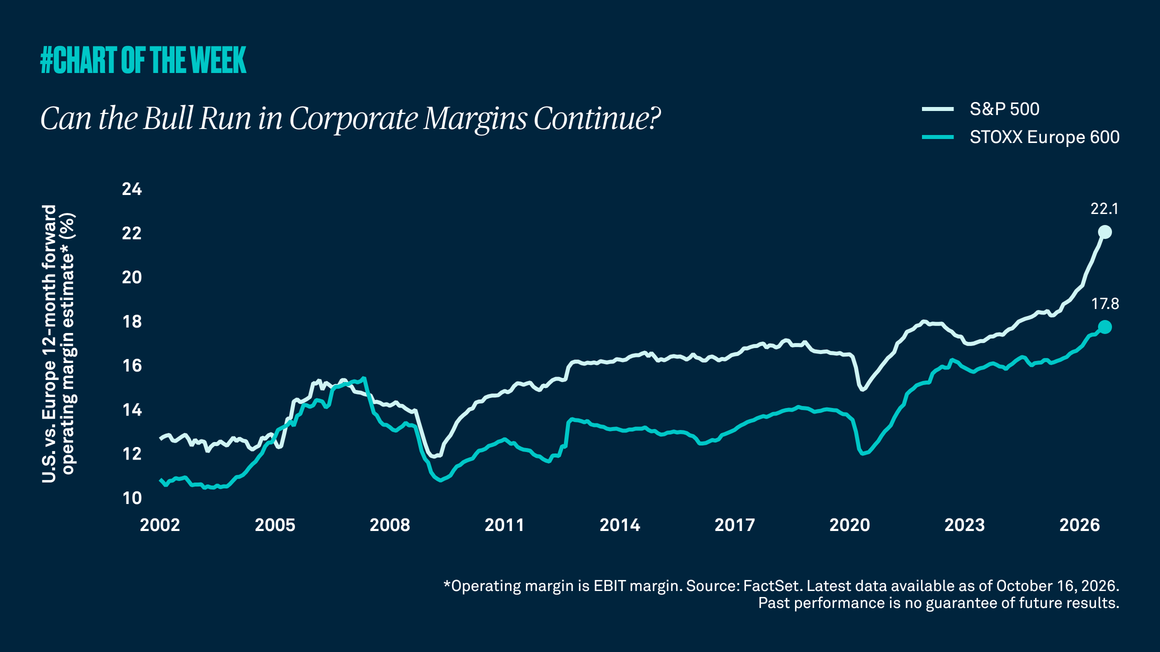
Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?
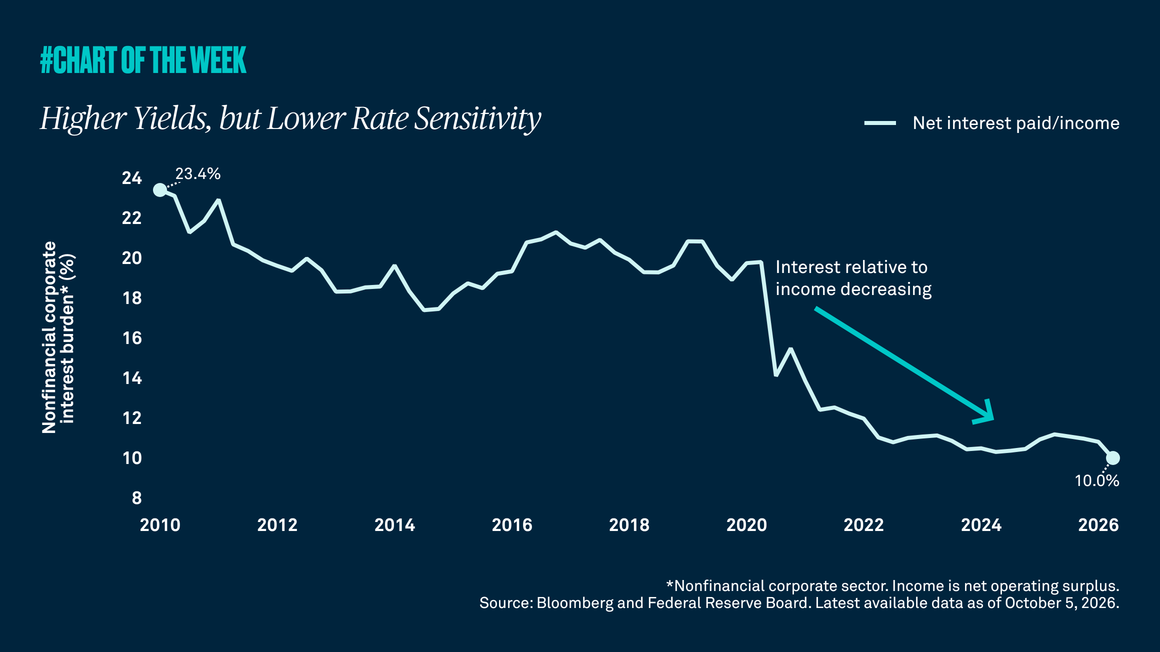
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.
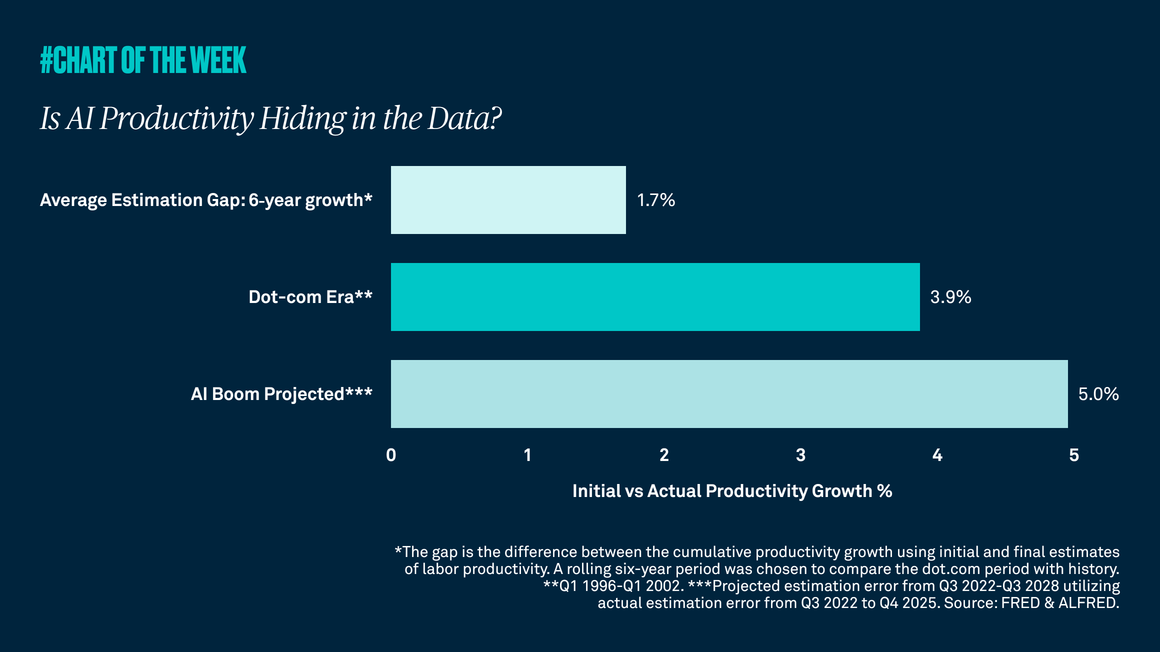
Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.
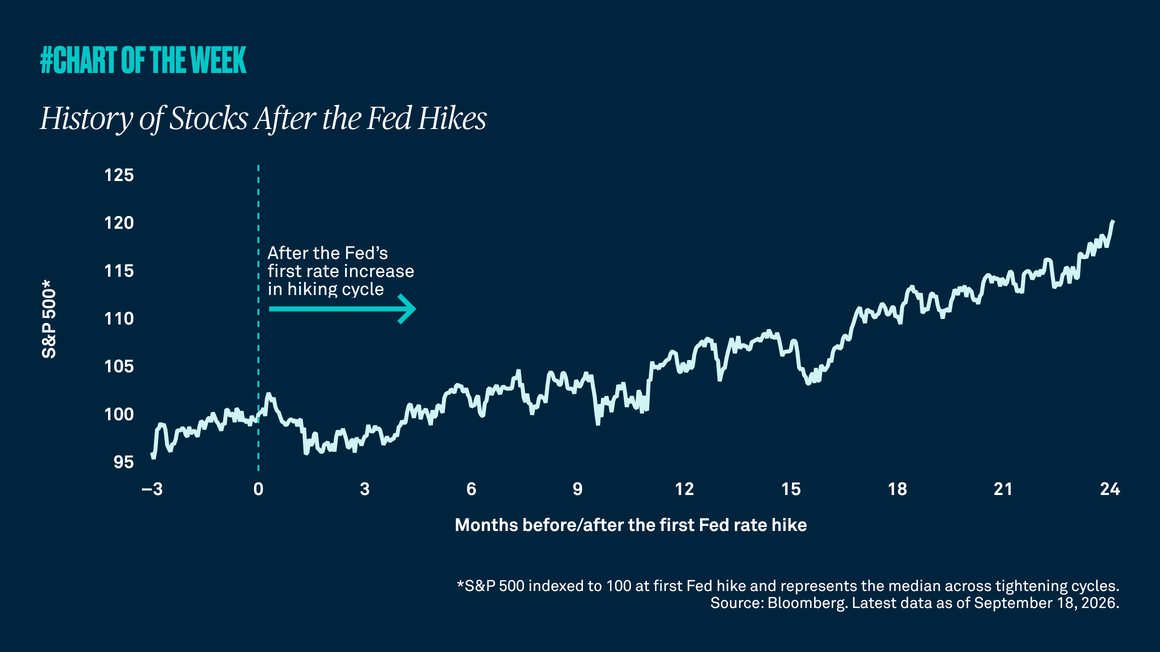
History of stocks after the Fed hikes
History of stocks after the fed hikes
Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.
