In a real regime shift?
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.
 3 mins Reading time
Published on 02 September 2026


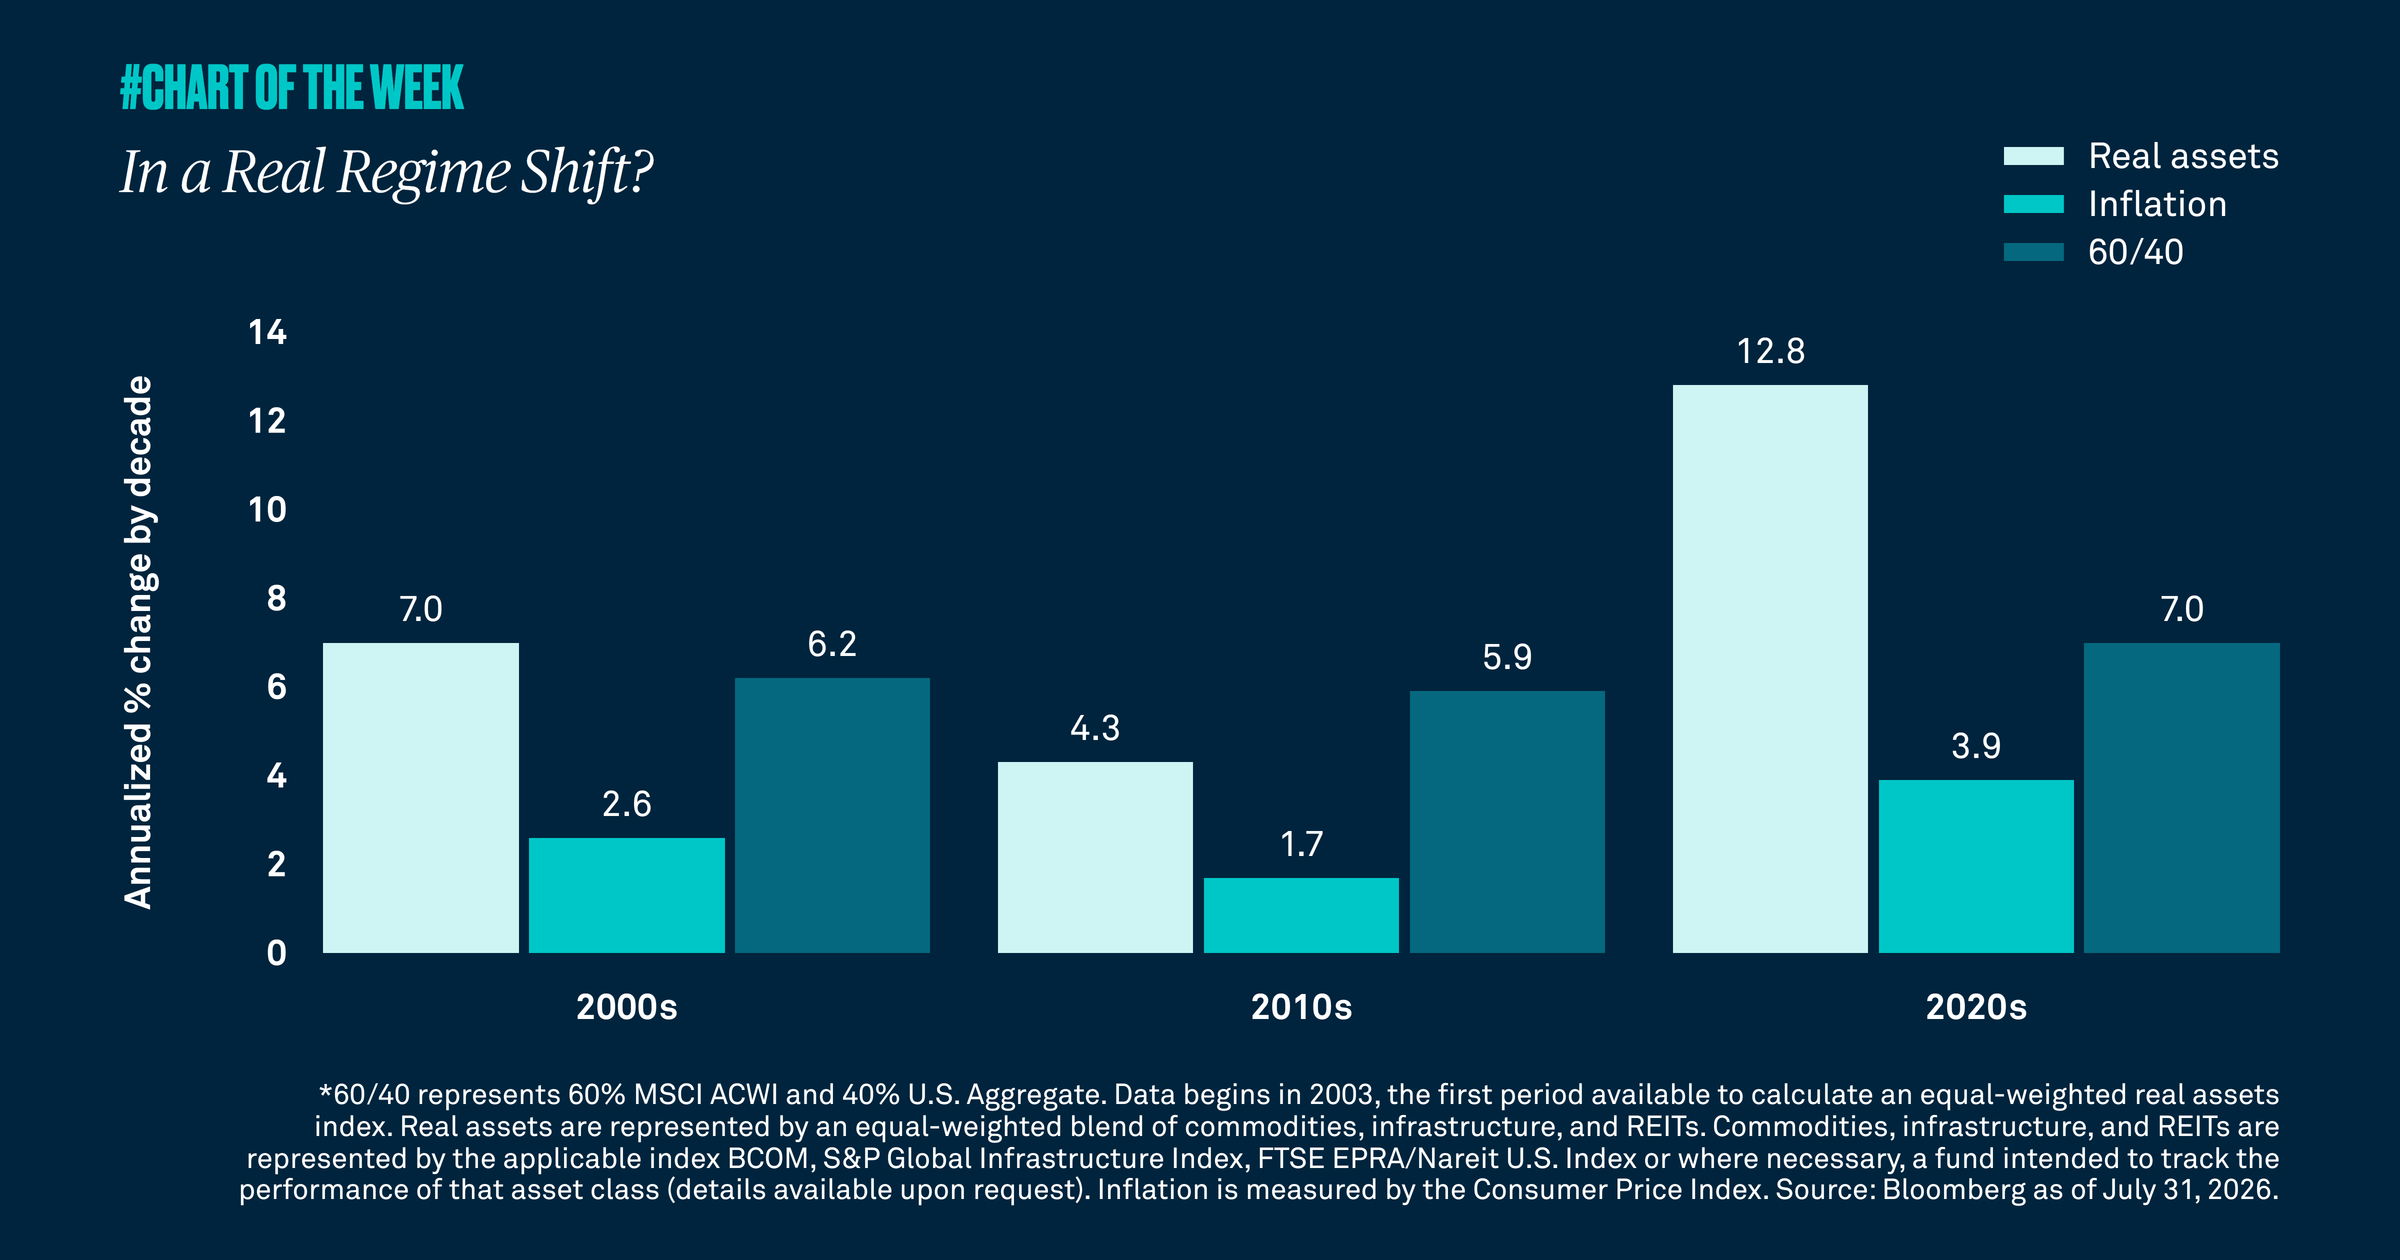
For much of the 2000s, inflation was broadly contained, averaging around 2.6% in the first decade and falling below 2.0% during the 2010s following the global financial crisis. Since the pandemic, however, inflation has shifted into a meaningfully higher range, with annualized inflation running at roughly 4% this decade — more than double the pace of the prior decade. In our view, various factors including event-driven spikes, such as COVID and energy-driven supply shocks, as well as deglobalization, suggest that inflation is likely to remain structurally higher than it was in the years preceding COVID.
As inflation has moved higher, real assets have meaningfully outperformed. Real assets have generated annualized returns of 12.8% this decade, compared with approximately 7% for a traditional 60/40 portfolio, while returns for real assets are roughly three times the level achieved in the 2010s. We believe this relative outperformance reflects more than a short-term cyclical adjustment and instead points to a long-term trend.
Importantly, the case for real assets is not driven by inflation alone. We also see support from a durable capital expenditure cycle reinforced by several powerful secular trends, including infrastructure investment, increased defense spending, onshoring across industries and the continued buildout of artificial intelligence-related capacity.
Given these factors, it’s important for investors to review their portfolio mix and consider including real assets as a way to enhance diversification, improve return potential and position for a structurally higher inflation environment.
994747 Exp : 25 August 2027
YOU MIGHT ALSO LIKE
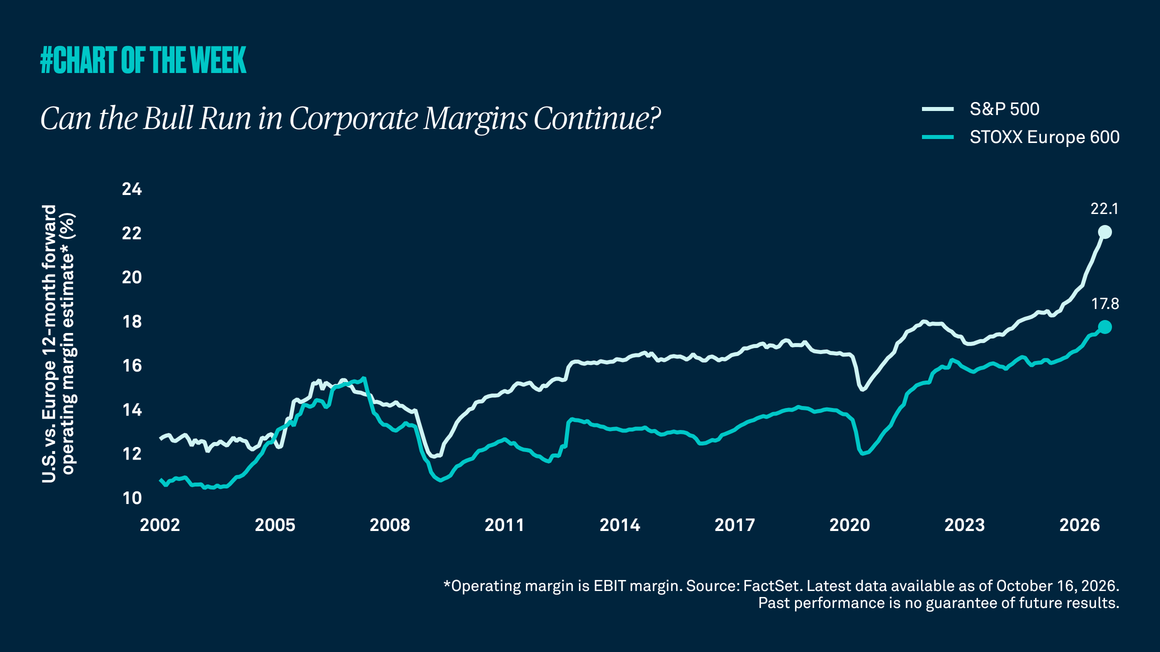
Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?
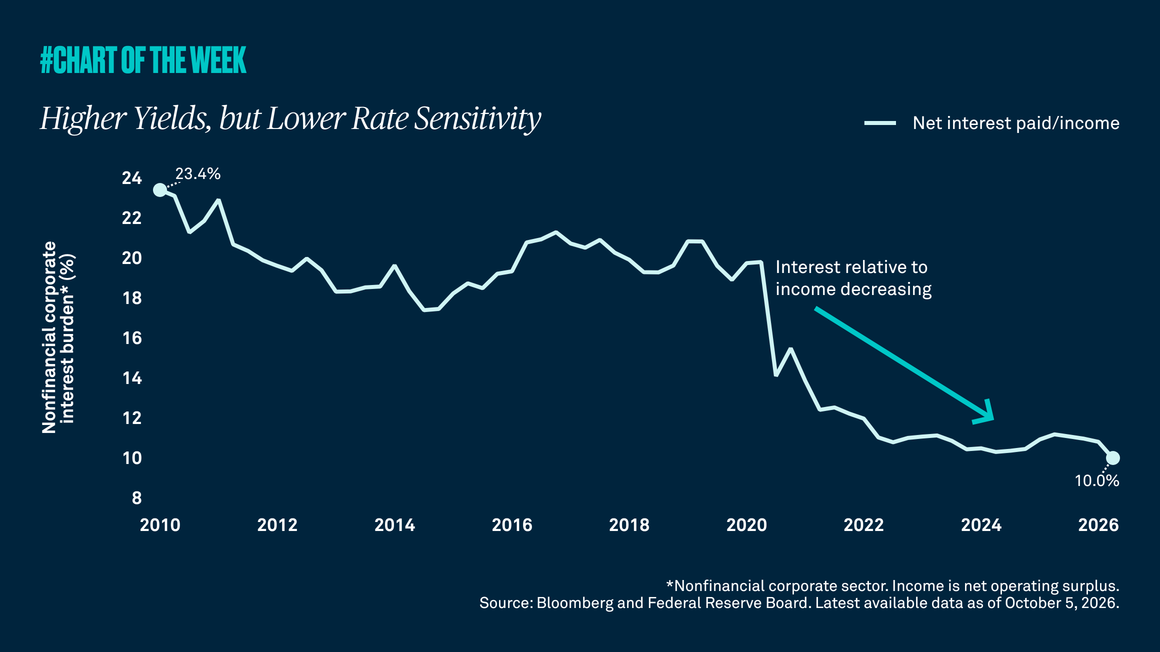
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.
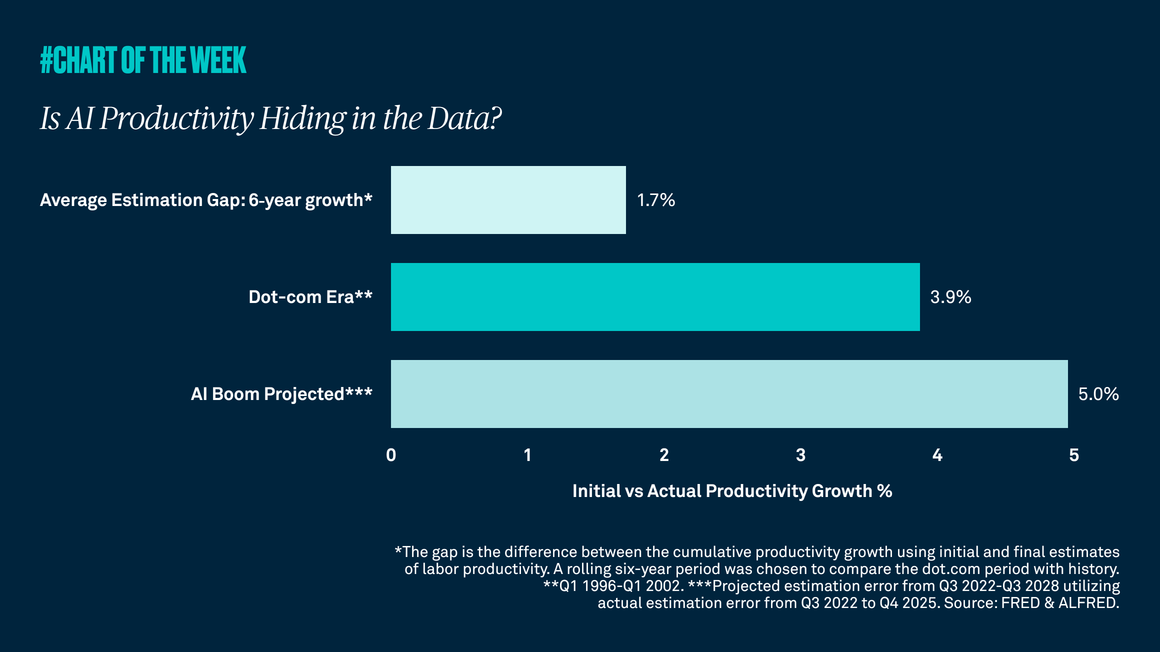
Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.
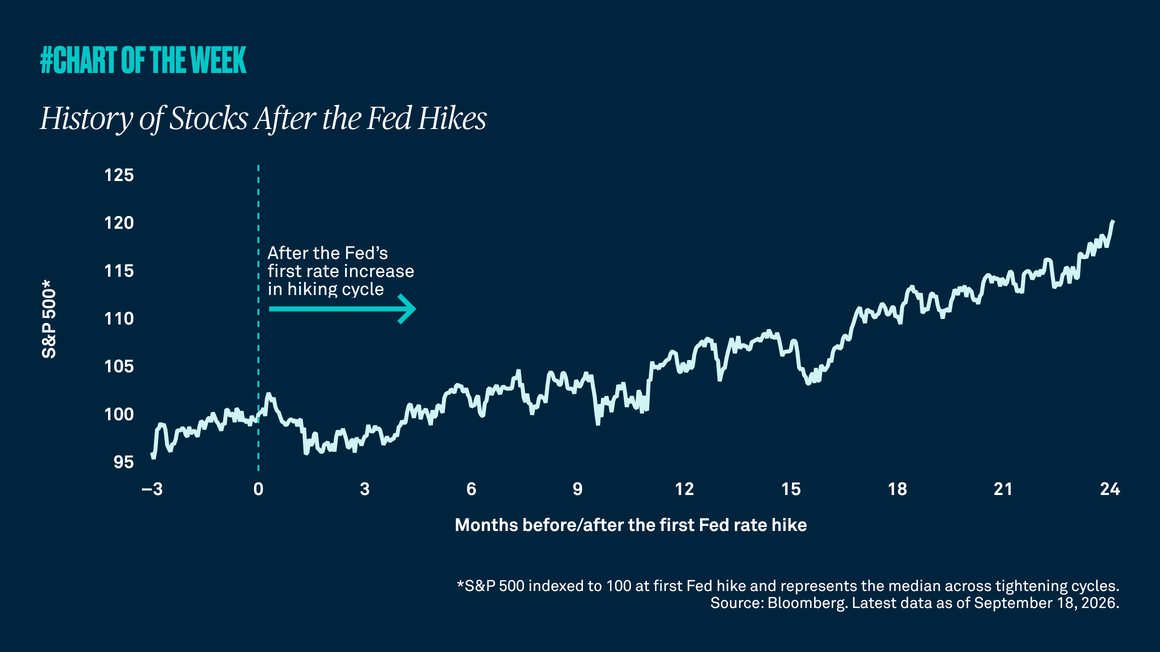
History of stocks after the Fed hikes
History of stocks after the fed hikes
Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.
