A good outlook for global earnings
Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.
 3 mins Reading time
Published on 09 September 2026


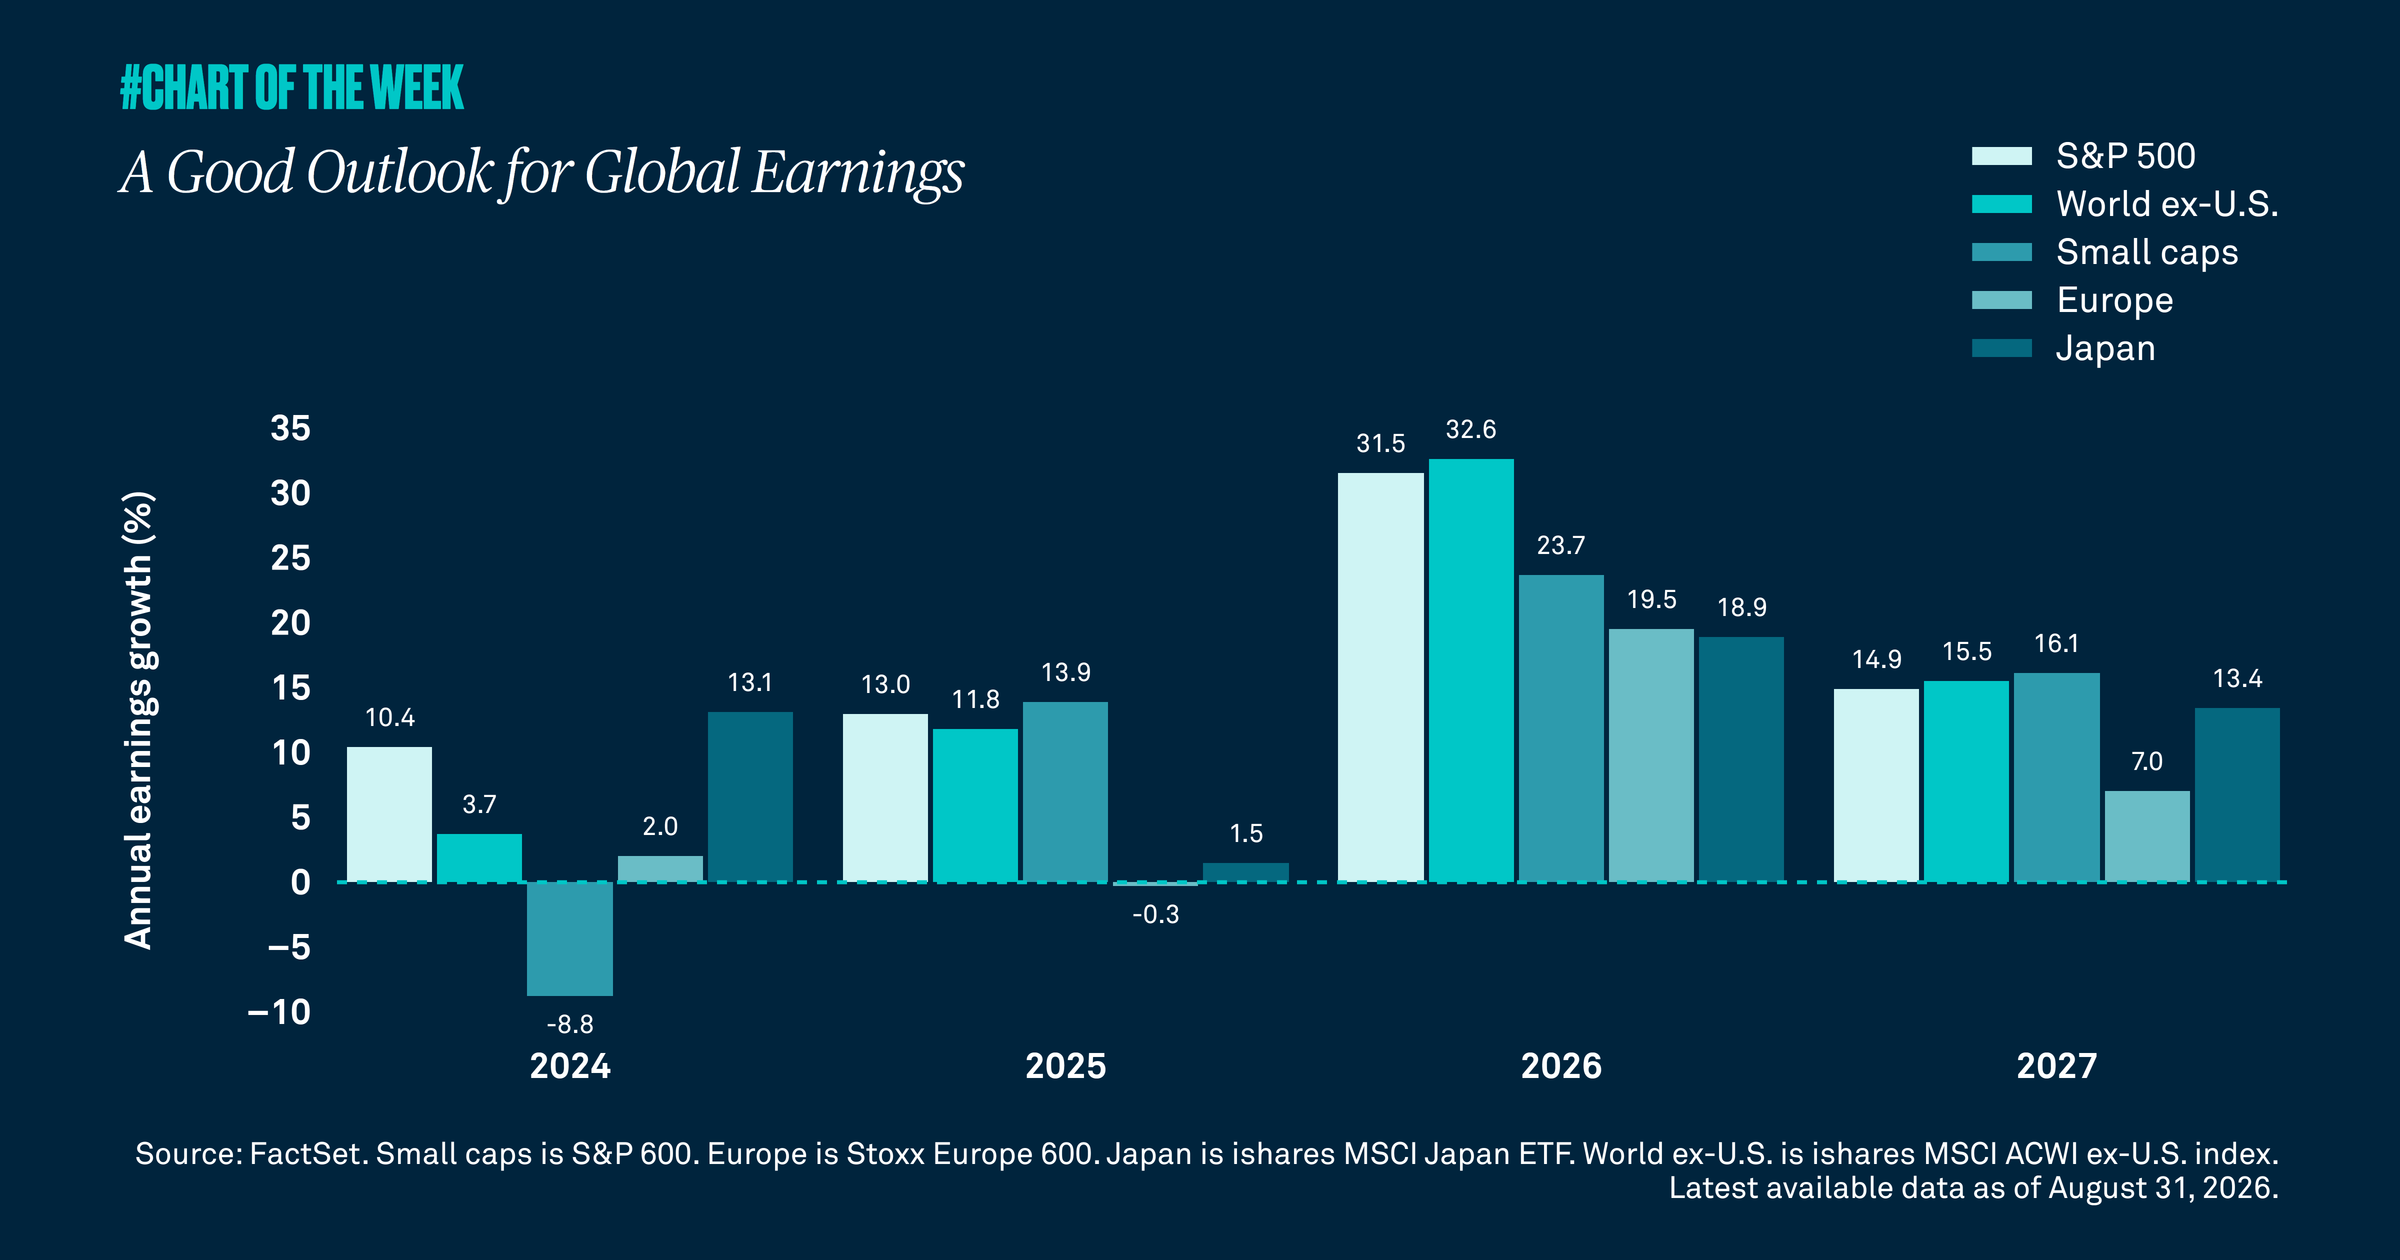
This year has been notable for the strength of global earnings growth. In the U.S., S&P 500 earnings are expected to rise 31.5% in 2026, up sharply from 13% in 2025. The story does not end there. Earnings growth has improved meaningfully across Europe, Japan and other major markets, with each region expected to deliver profit growth well above last year’s pace.
Though global earnings momentum is likely to slow in 2027 from this year’s unusually strong levels, growth may still remain above historical averages. That should matter for markets, especially as the earnings story has broadened beyond a narrow group of U.S. stocks. Corporate margins continue to rise, and while artificial intelligence-related capital spending has been a major driver of growth, the broader market remains fundamentally solid.
We do expect volatility to increase as markets contend with a range of uncertainties, including higher U.S. Treasury yields, the approaching midterm elections and ongoing geopolitical tensions. Still, we view the combination of above-average earnings growth and broad-based global participation as a clear positive for the forward outlook for global equities. After all, earnings growth remains the key driver of long-term market returns. We therefore remain constructive.
998073 Exp : 09 September 2027
YOU MIGHT ALSO LIKE
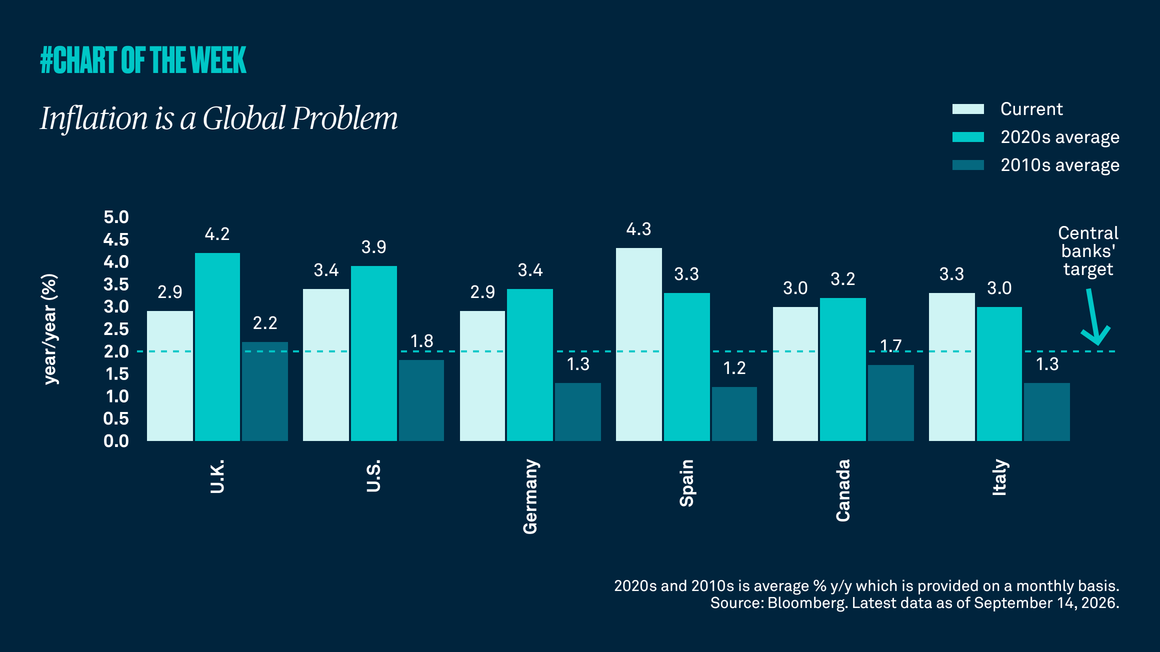
Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.
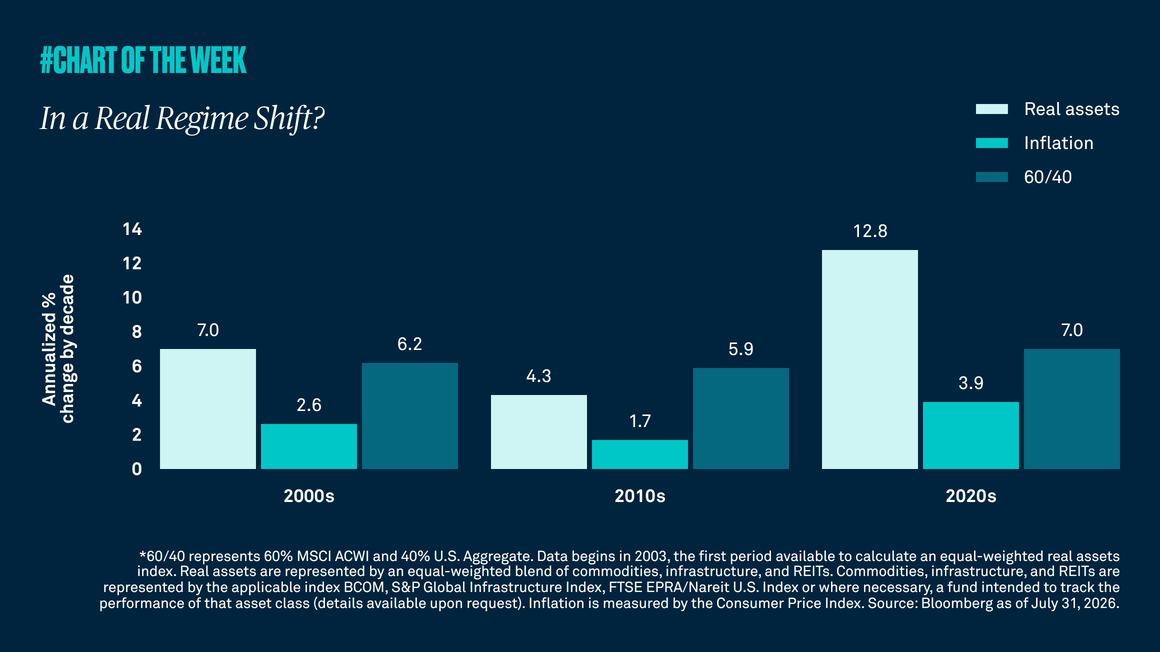
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.
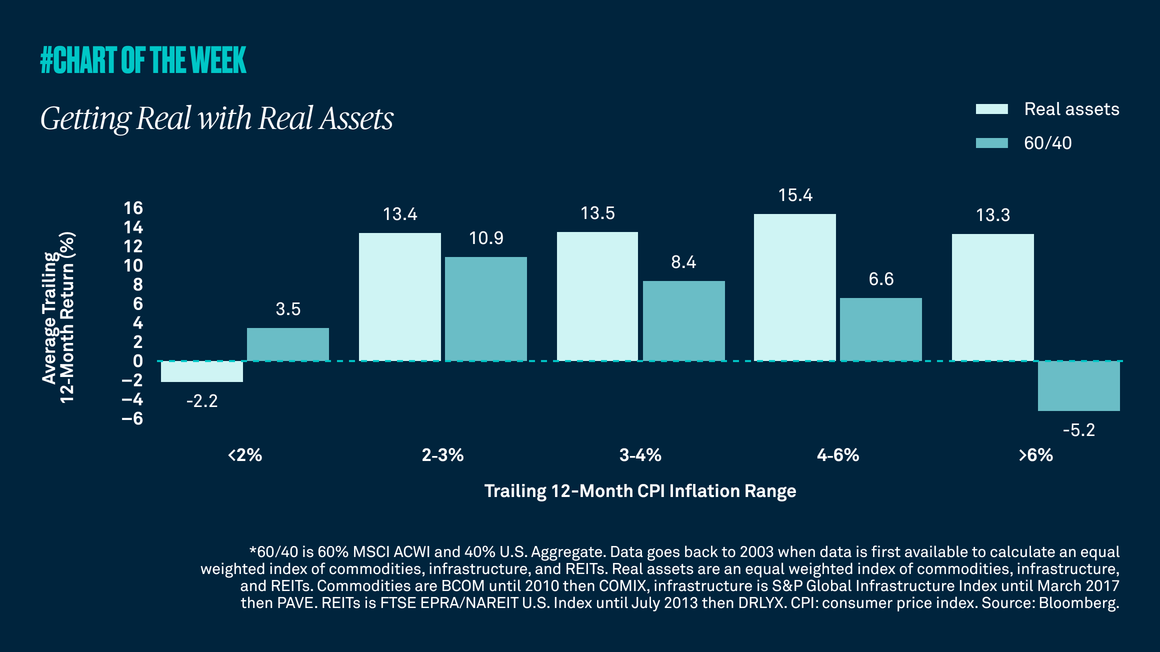
Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.
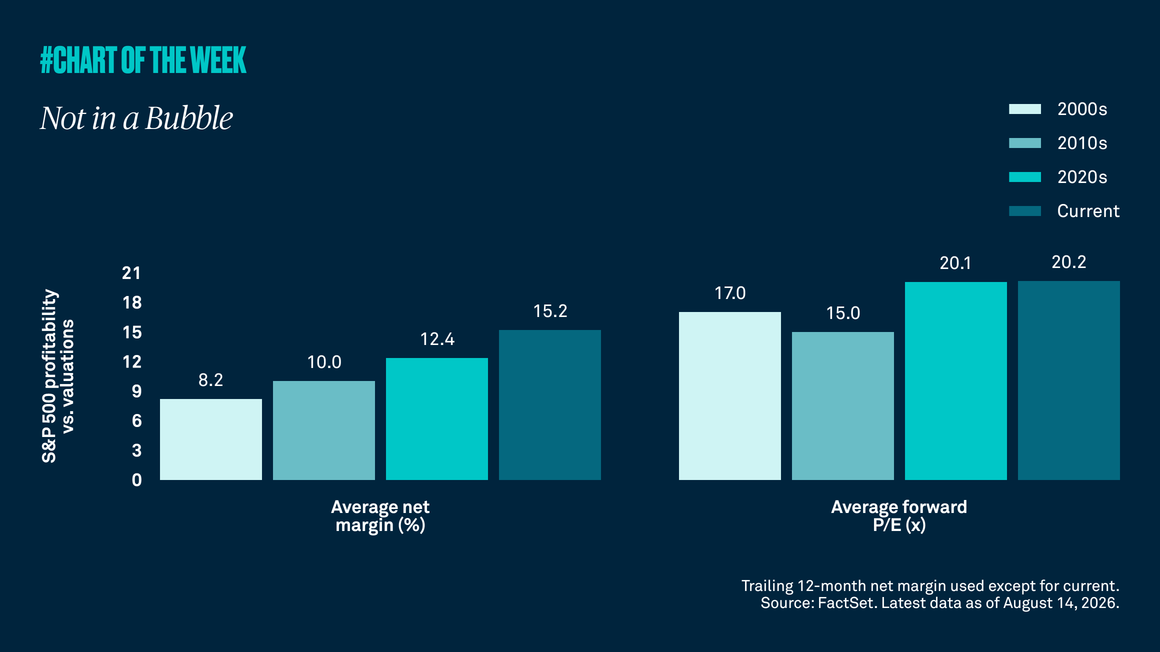
As the S&P 500 approaches all-time highs, there are renewed concerns among investors about elevated valuations. However, historically strong profitability and expected earnings growth appear to support current pricing. In addition, the current S&P 500 price-to-earnings (P/E) ratio is roughly equal to the average since Covid. As a result, we do not view U.S. equities as being in bubble territory and we remain constructive on the asset class.
