Will markets remain resilient?
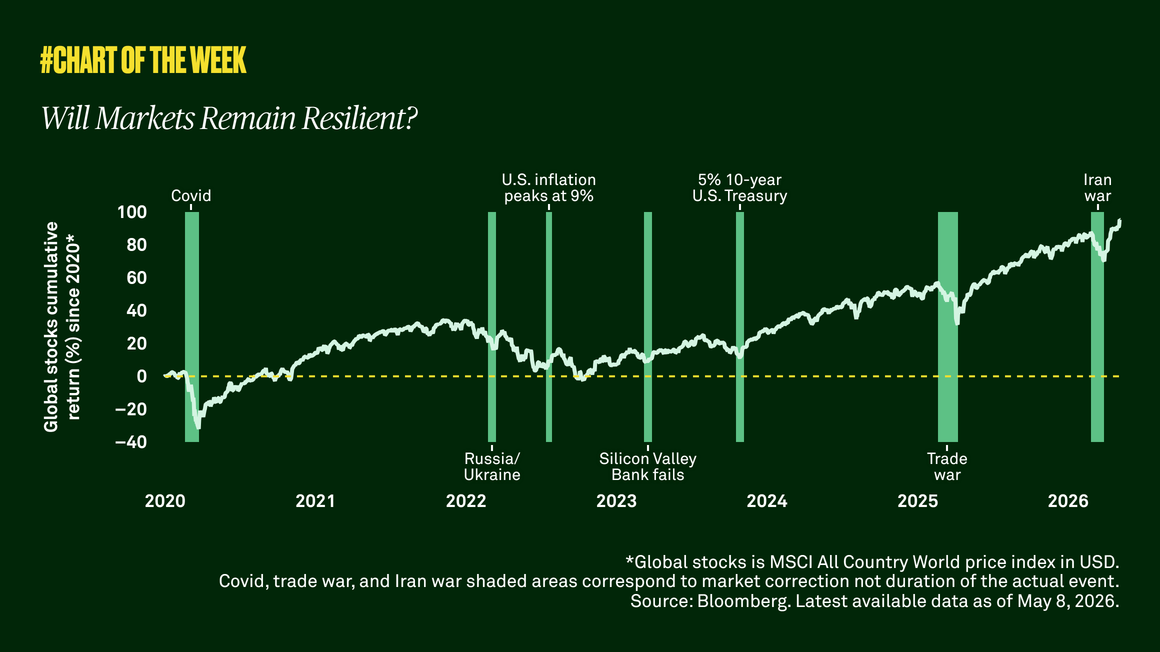
Global equities have risen an annualized 11% since 2020 despite repeated shocks, as resilient growth and earnings have helped markets recover from periods of volatility. While the U.S.-Iran conflict poses near-term inflation and growth risks, markets remain constructive as earnings expectations continue to improve.
 3 mins Reading time
Published on 12 May 2026


Since 2020, global equities have delivered strong gains of an annualized 11% even after absorbing a series of shocks, including the pandemic, the Russia-Ukraine war, inflation spikes, aggressive central bank rate hikes, and tariffs. Each of these events drove volatility and selloffs, but markets repeatedly recovered as growth proved more durable than anticipated and investors continued to look through near-term turbulence.
Now, with the U.S. entangled in conflict with Iran, investors face a geopolitical shock that could push energy prices higher, reignite inflation and weigh on global growth in the near term. Even so, markets appear to be pricing this as a temporary event rather than the start of something associated with a longer downturn.
In the U.S., resilient economic growth and stronger-than-expected earnings are supporting higher equity prices this year despite these risks. A renewed inflation wave or disappointing returns on AI-related capital spending could still pressure profits and growth, but for now, earnings expectations are increasing. As a result, we believe risk sentiment in the U.S. and globally remain constructive.
935825 Exp : 12 May 2027
YOU MIGHT ALSO LIKE
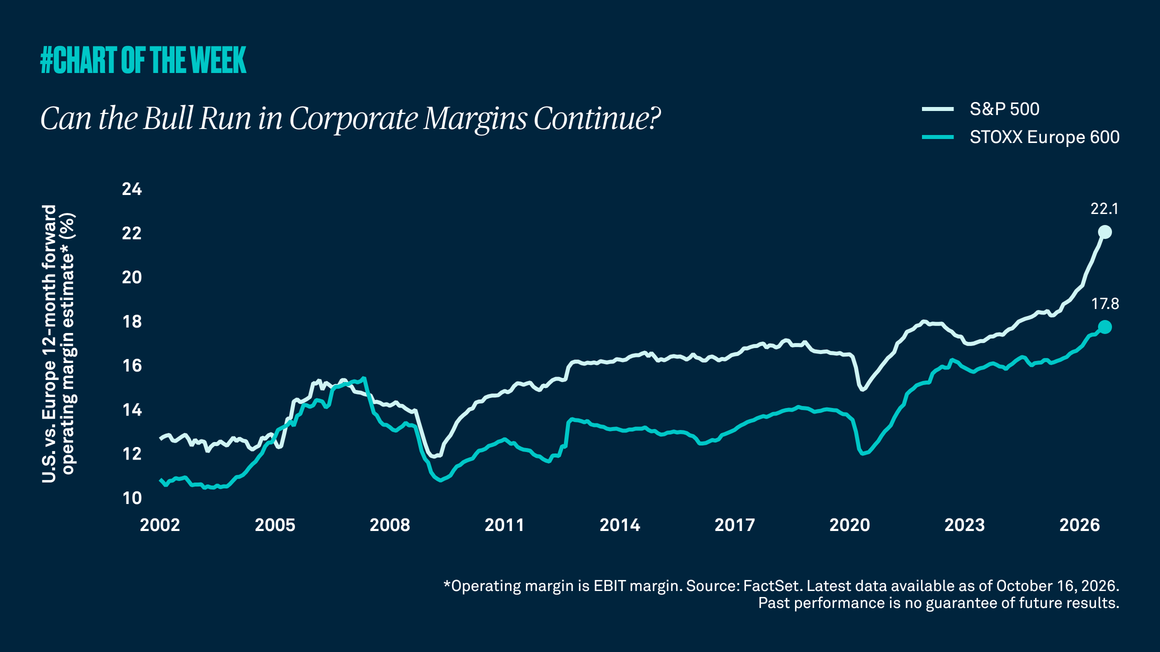
Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?
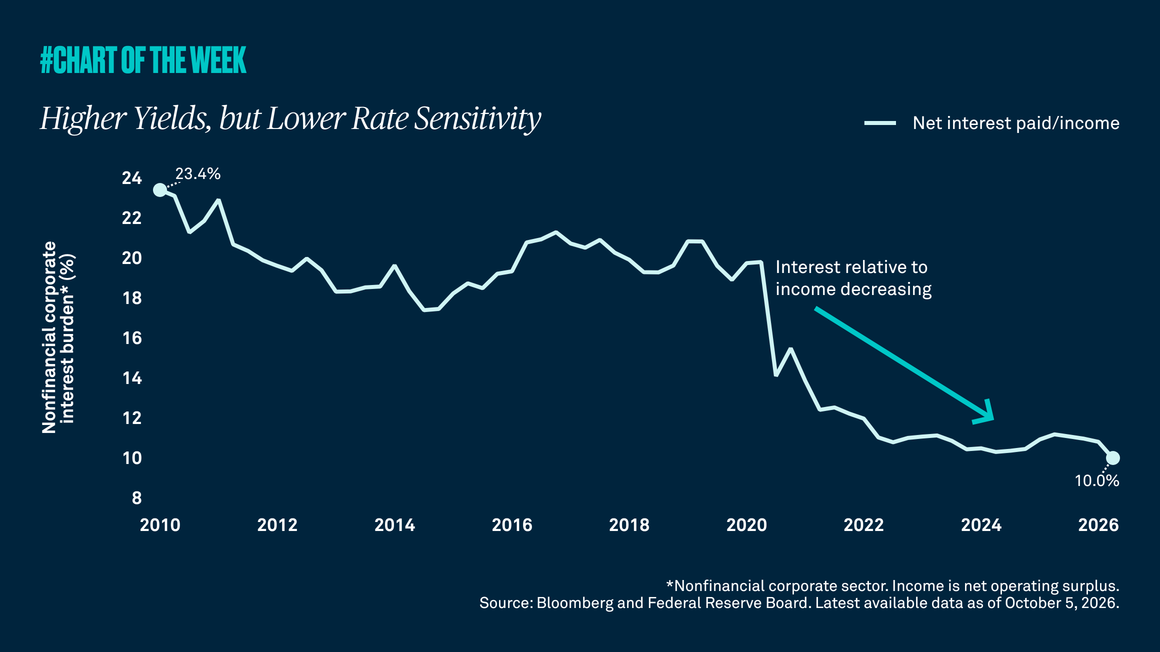
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.
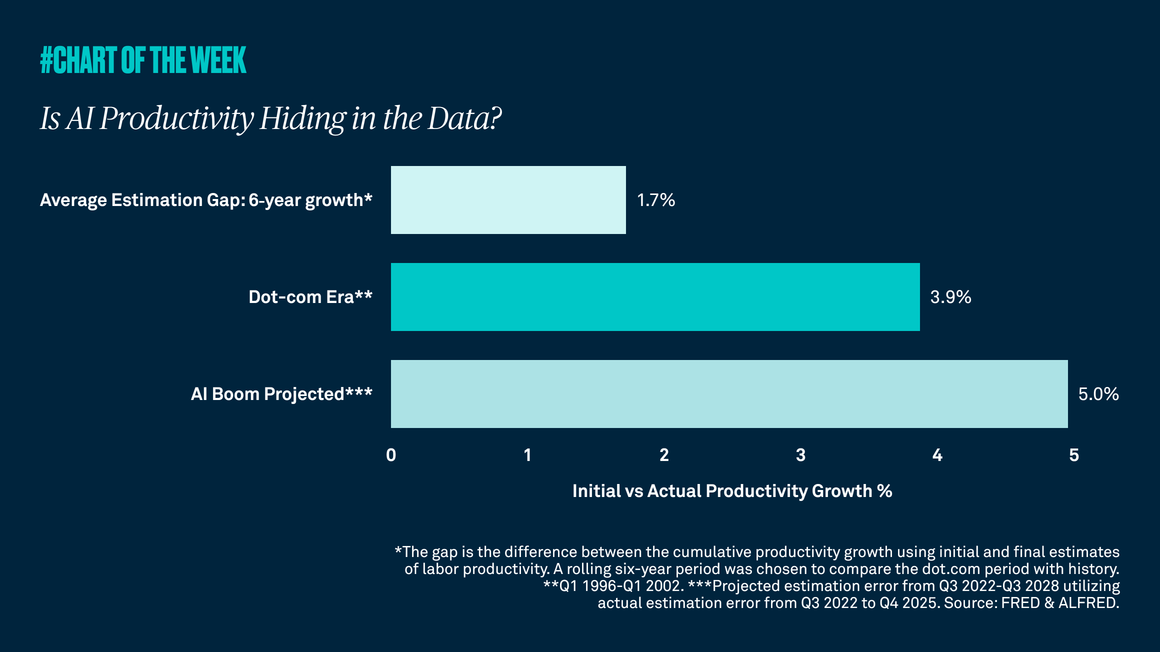
Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.
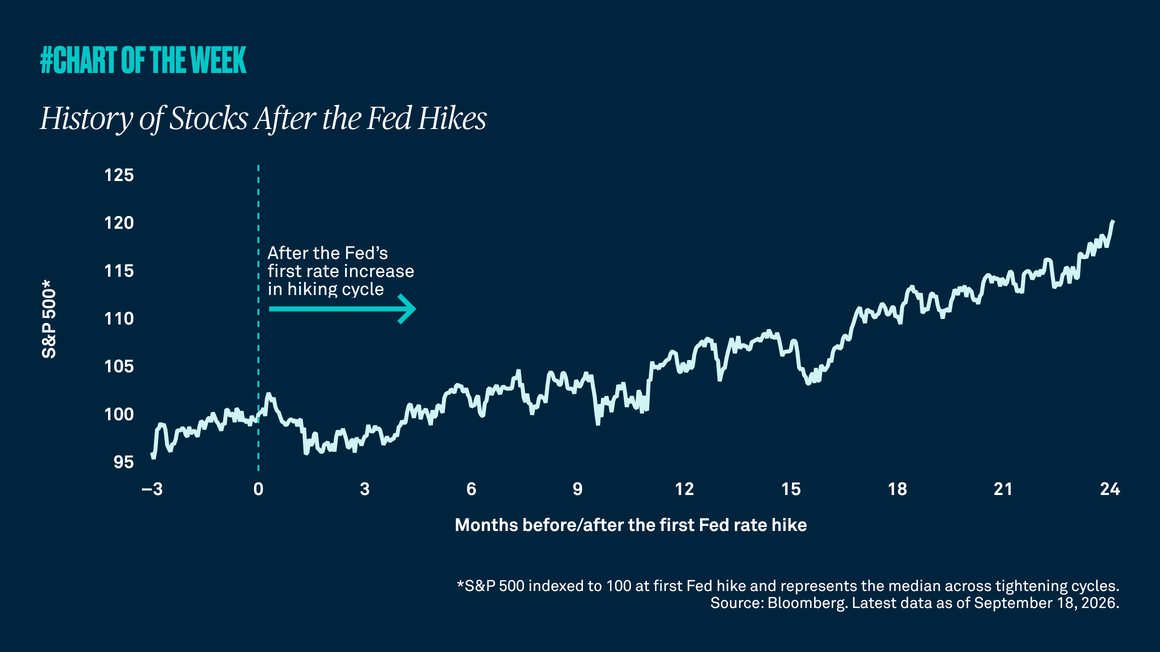
History of stocks after the Fed hikes
History of stocks after the fed hikes
Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.
