Returns after oil spikes
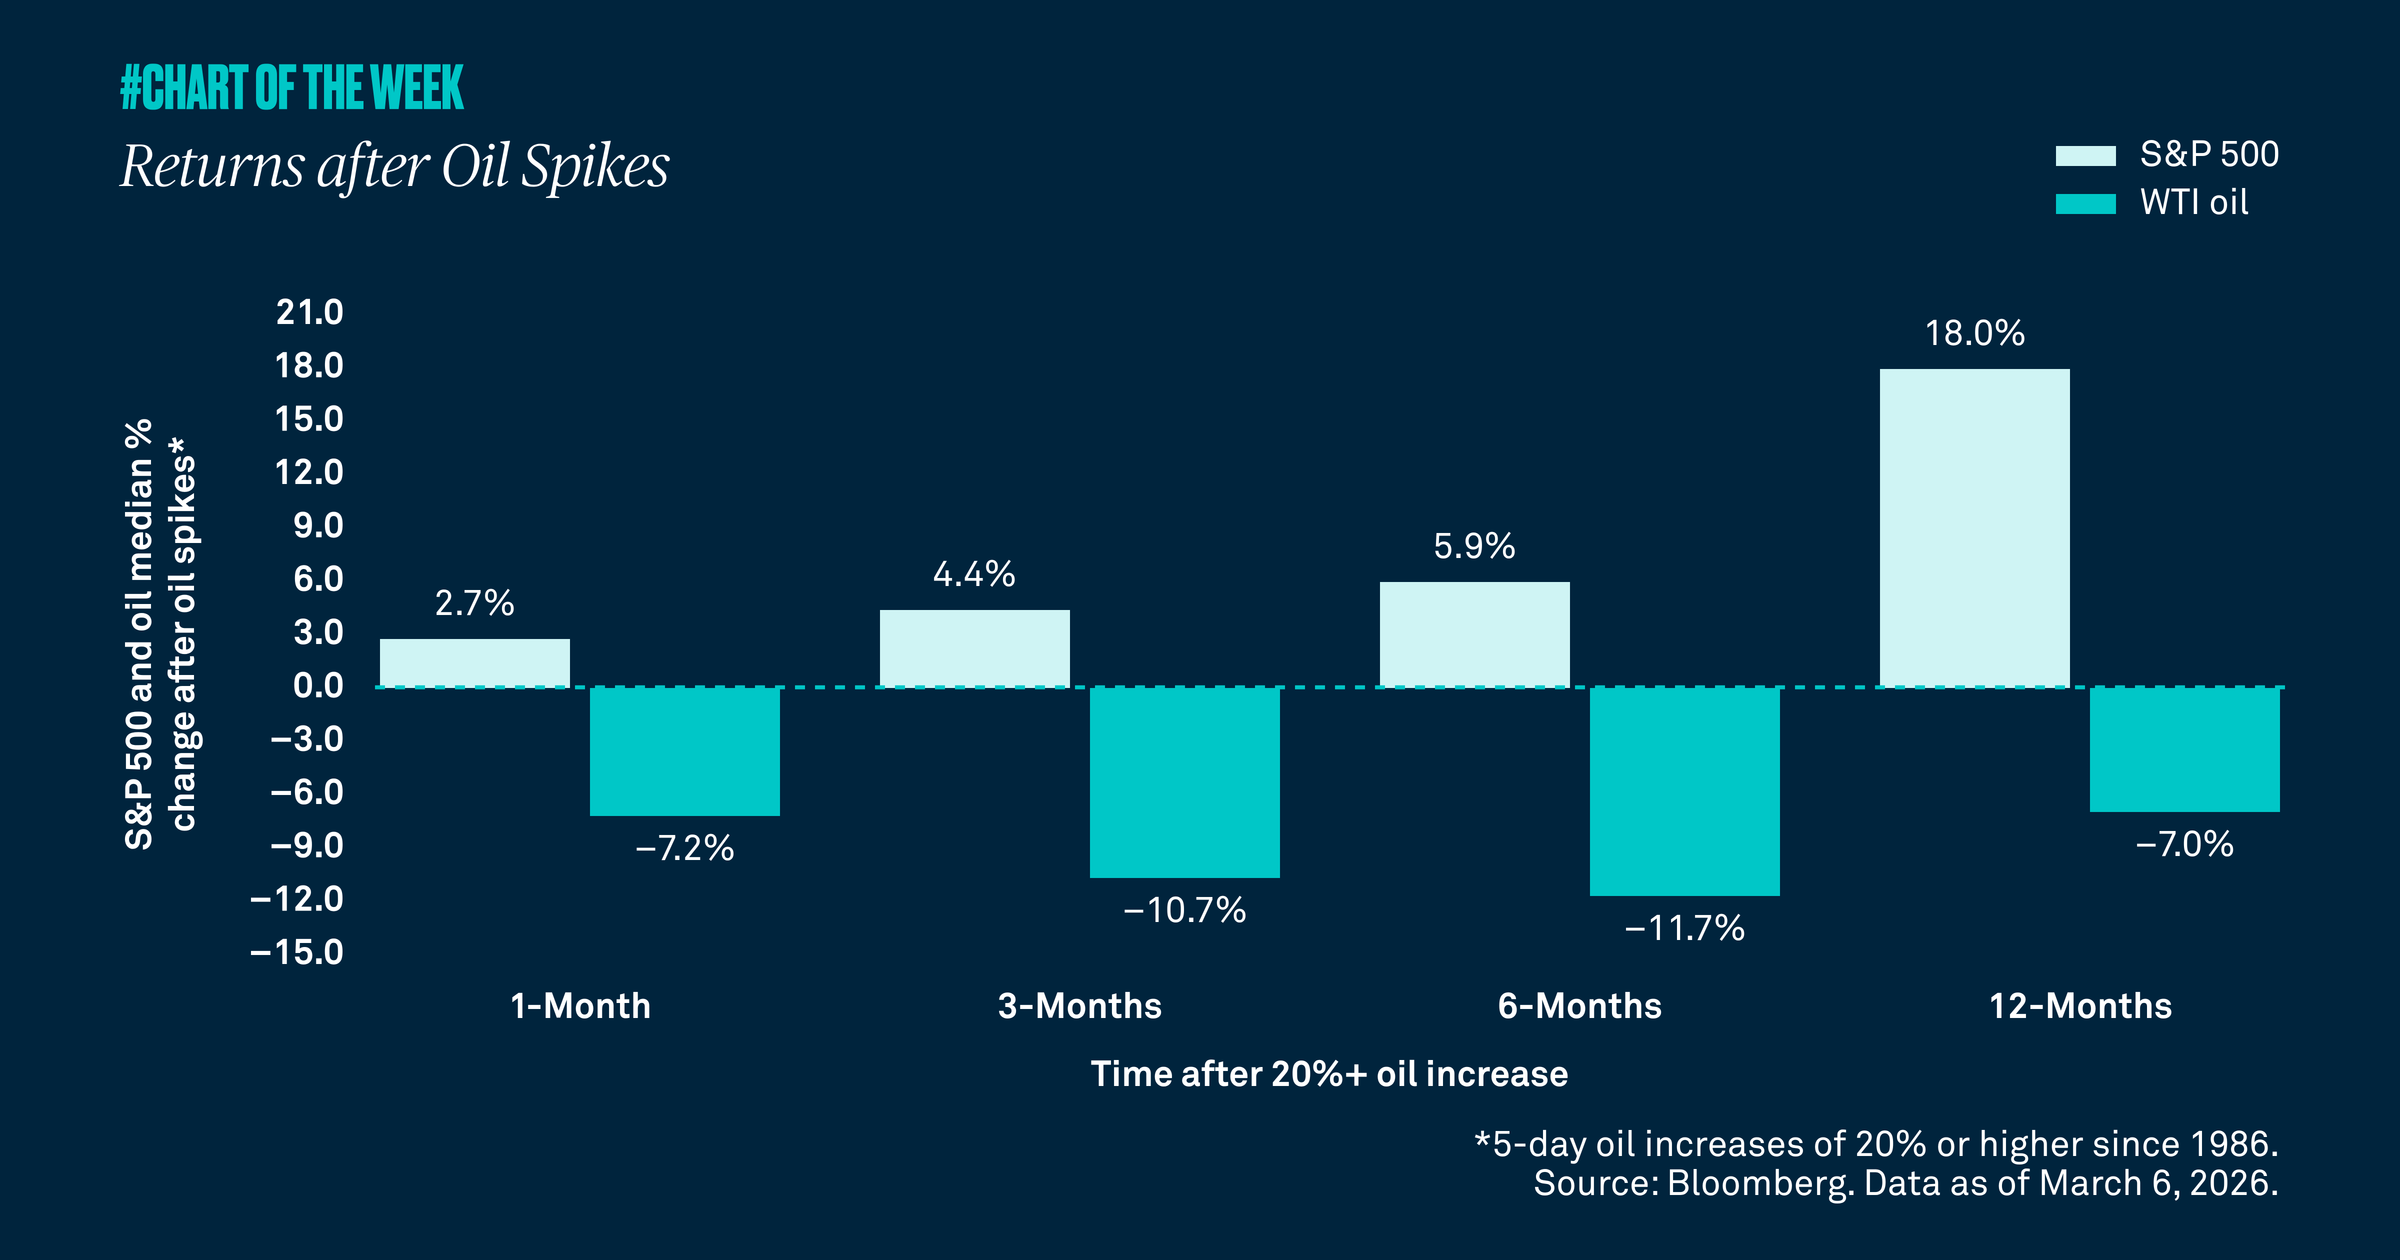
The Strait of Hormuz, which moves about 20% of global oil, has seen many ships that normally travel through it curtail their activity. Consequently, WTI oil was up over 36% in the five days after the oil supply shock began. Yet equities barely budged, signaling a temporary supply shock, not a larger crisis. Historically, after similar price spikes equities tend to move higher while oil prices decline — further evidence for avoiding emotion-driven investing.
 3 mins Reading time
Published on 09 March 2026


The Strait of Hormuz, which links the Persian Gulf to the Indian Ocean, sits at the heart of today’s Middle East tensions. It moves roughly 20% of global oil, yet ships are increasingly skirting the route amid Iranian attack risk. WTI oil surged more than 36% in the five days after the initial shock. Despite the hit to supply, the S&P 500 is down just 2.0% and energy stocks are up only 1.0%. These moves suggest markets see a temporary oil supply shock, not a broader crisis. If it were systemic, equities would sell off more sharply and energy would rally harder.
Our research supports this. After five‑day oil spikes of 20%+, equities have typically risen while oil prices declined. Since the 1980s, the median six‑month S&P 500 gain is about 6% as oil has fallen nearly 12% following such shocks.
Historically, equities have looked right through oil shocks and geopolitics — and we expect the same this year as Middle East shipping normalizes and markets refocus on oversupply combined with softer long‑term demand. It’s a reminder: emotion-driven investing doesn’t pay because markets often tune out oil headlines that tend to rattle investors.
898673 Exp : 09 March 2027
YOU MIGHT ALSO LIKE
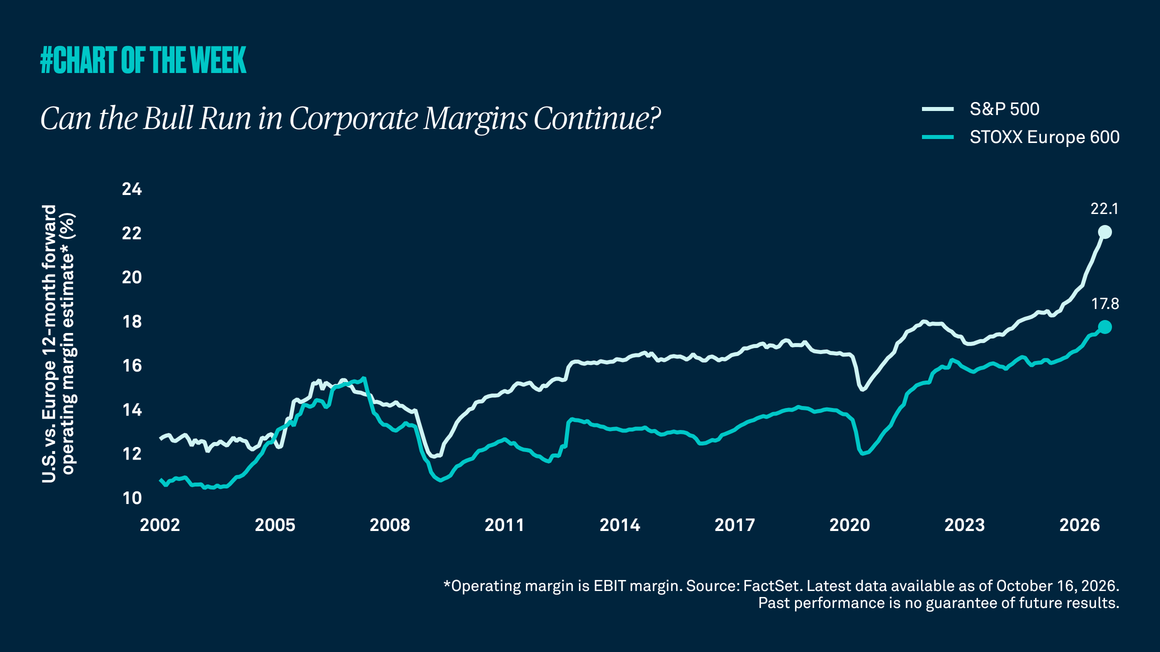
Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?
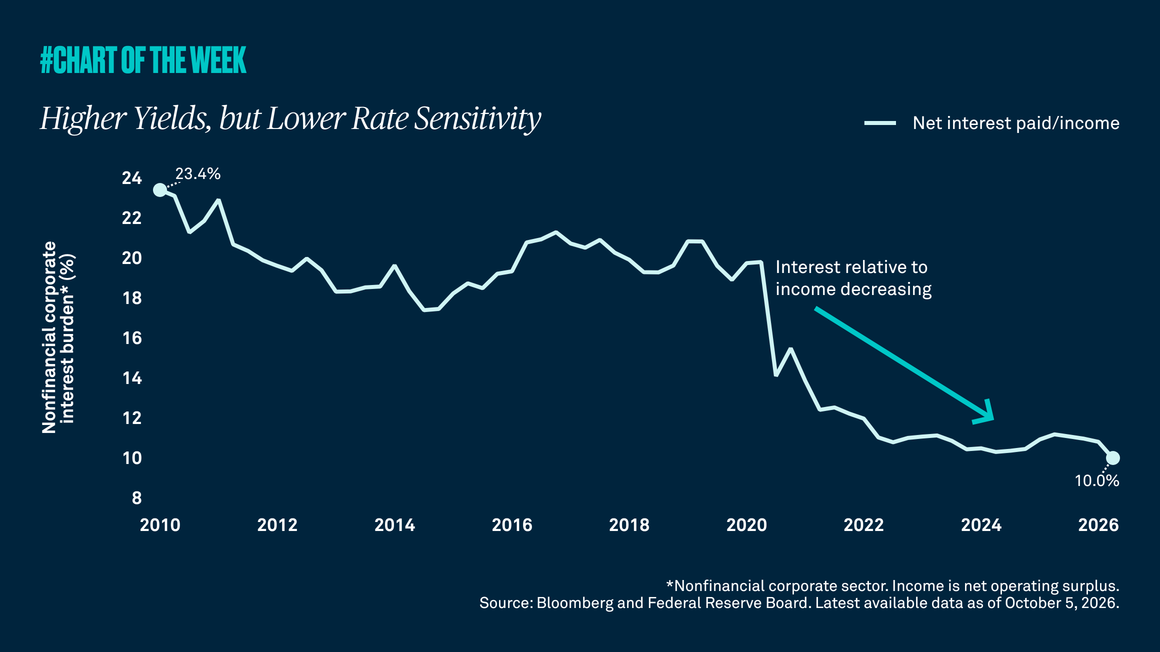
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.
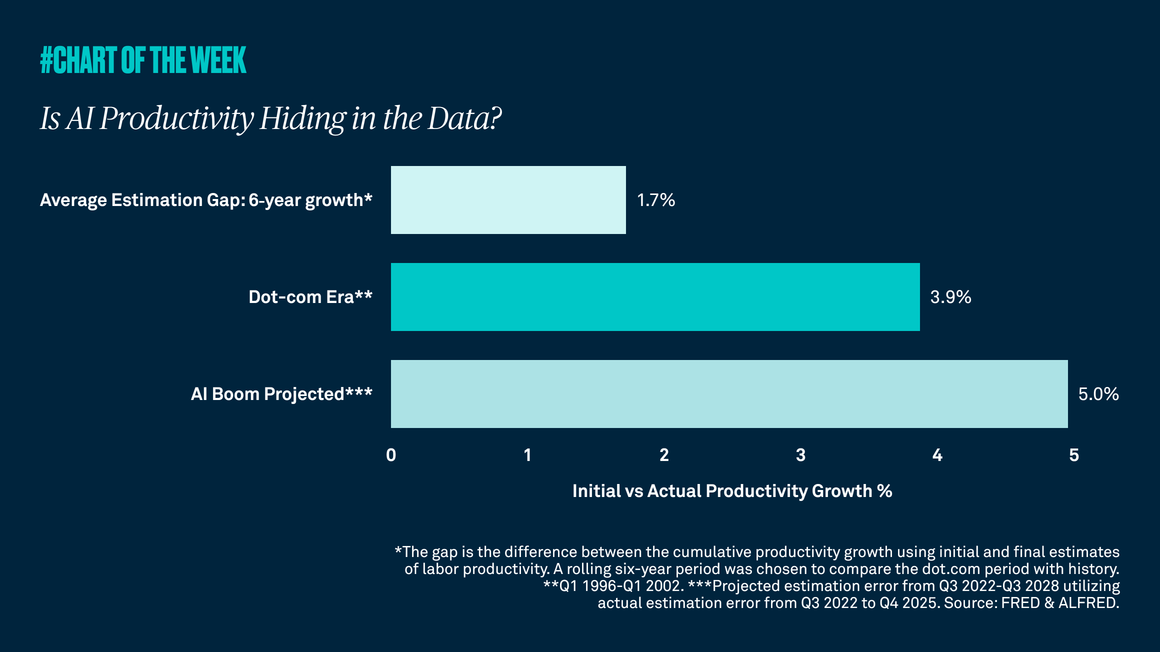
Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.
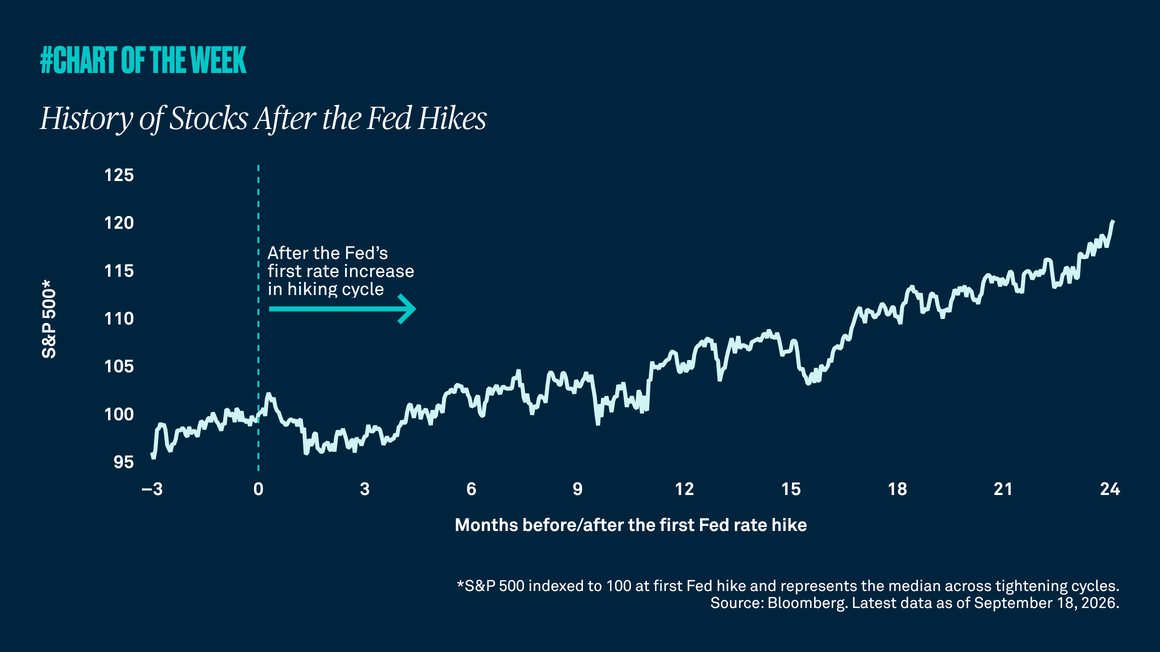
History of stocks after the Fed hikes
History of stocks after the fed hikes
Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.
