Please ensure Javascript is enabled for purposes of website accessibility Capex as a Catalyst
lu
en
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Capex as a catalyst

Capex as a catalyst

Improved business confidence and recent tax legislation are compelling corporations to reinvest their cash flows in their businesses. We believe this is a positive signal for economic growth. 
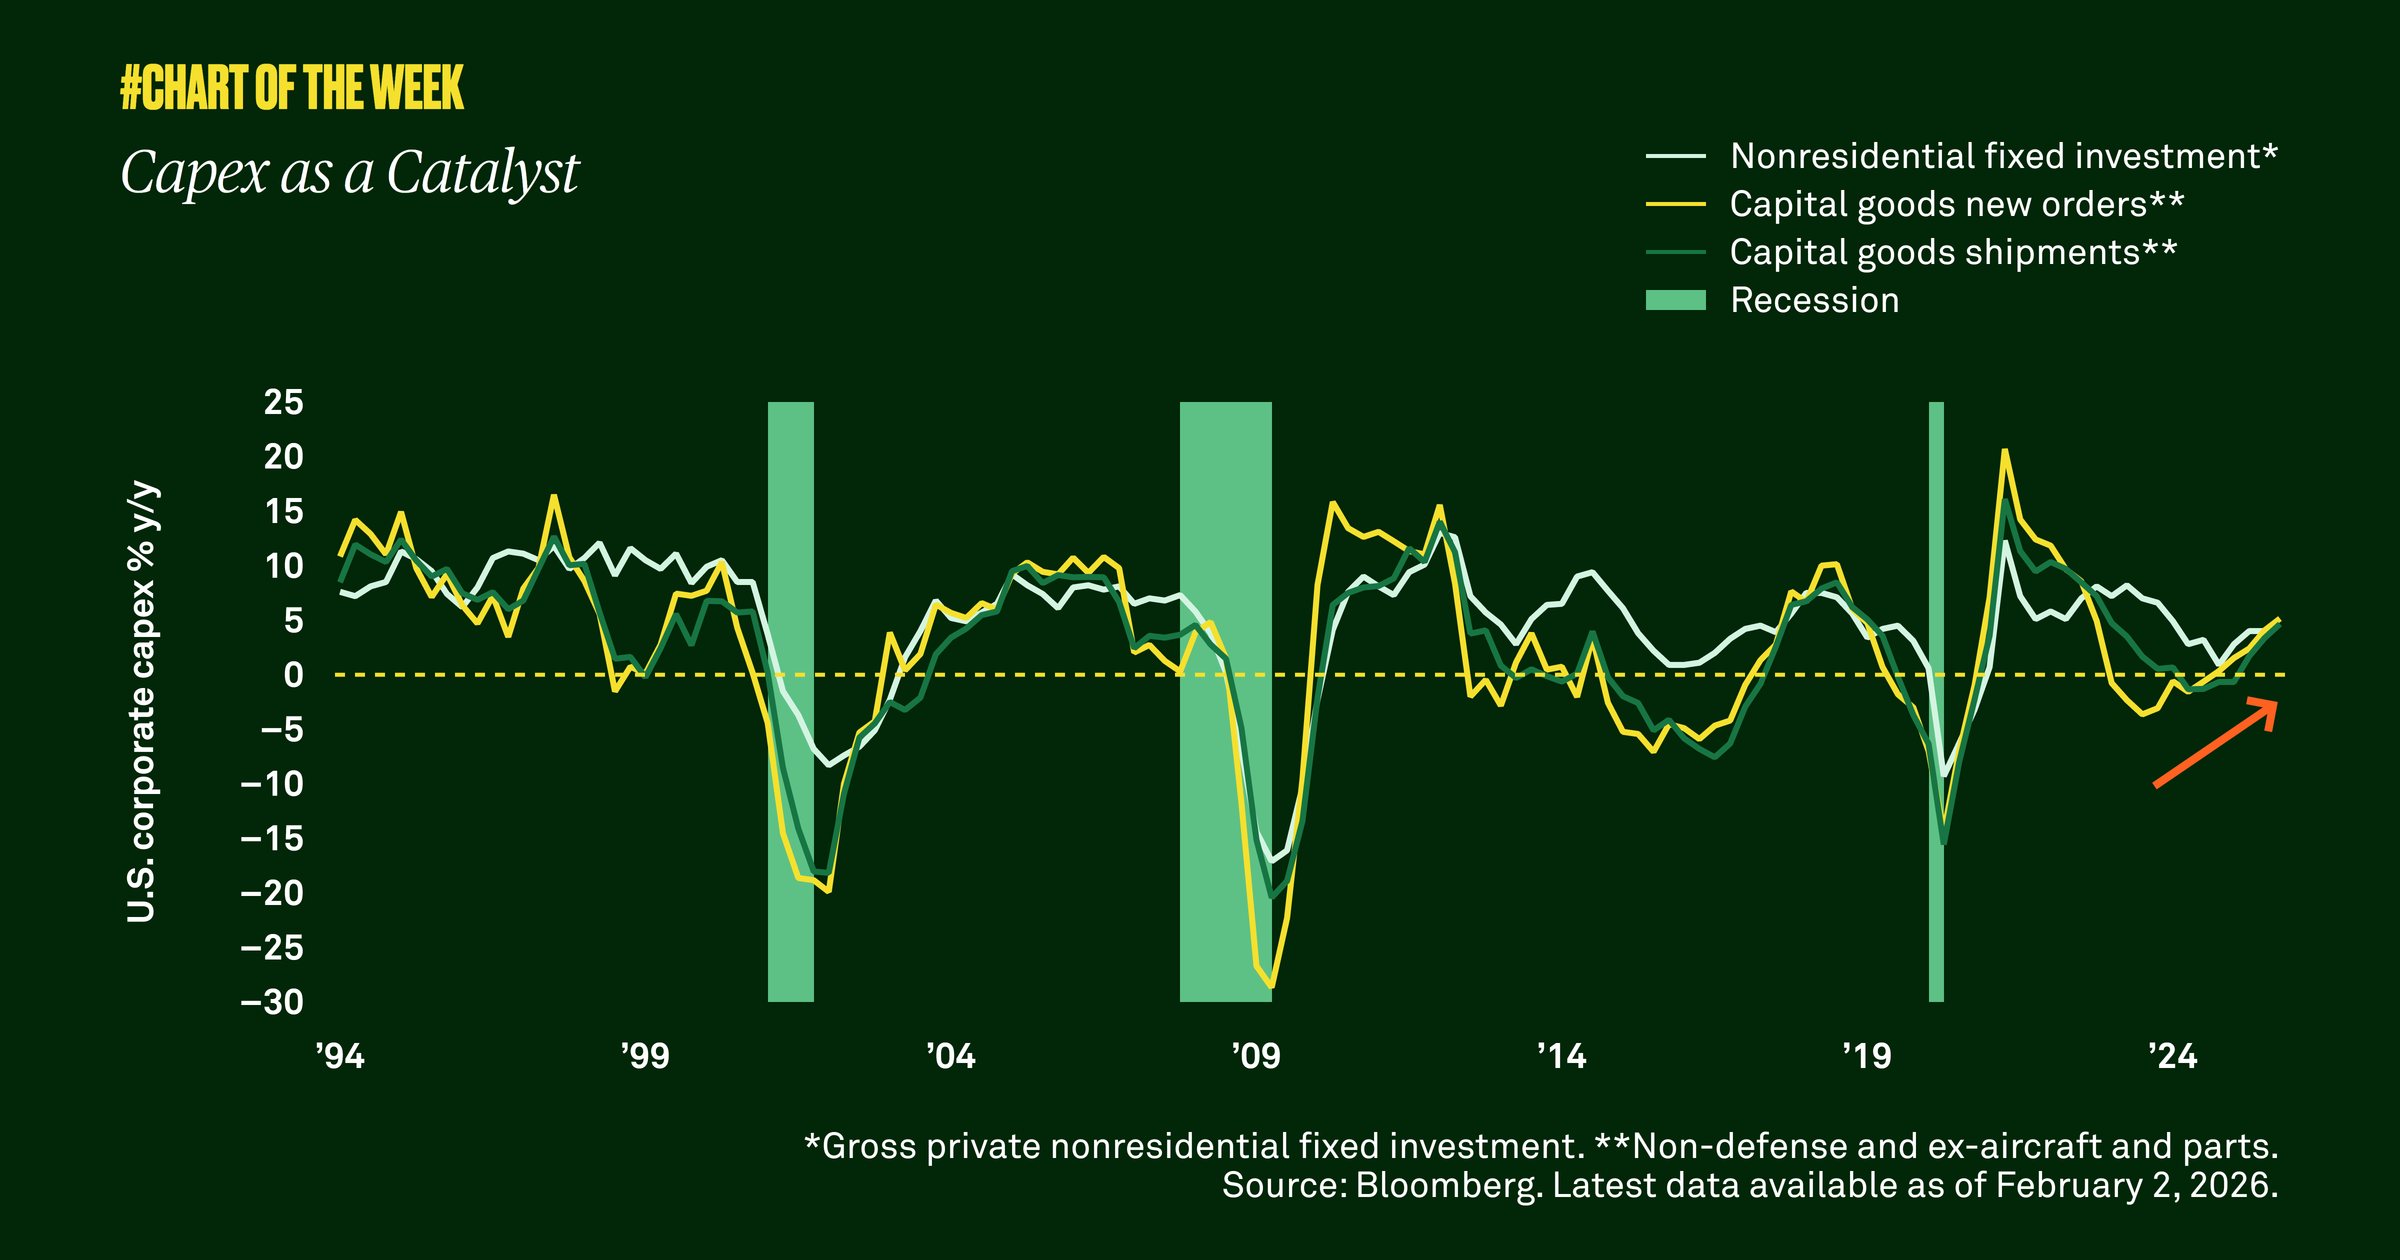

Reinvesting capital is key for U.S. corporations to remain competitive and grow their businesses. But timing these expenditures often depends on the economic cycle and expectations about future business conditions. In the early part of 2025, tariff uncertainty weighed negatively on these decisions. However, since the passage of last year’s pro-growth legislation, which includes the full expensing of capital expenditures (capex), we’ve seen a pickup in capex by U.S. corporations.

While there are many measures of capital investment, nonresidential fixed investment is an important indicator of economic health and business confidence. It represents spending on fixed assets, including structures, equipment and intellectual property products, such as research and development and software. For the first time in four years, we’ve seen this metric increase for three consecutive quarters. Another proxy for capex — capital goods new orders and shipments — is growing at its highest annual rate in three years.

We expect the improving economic outlook to support this strengthening capex trend. While corporate spend has focused on technology given the artificial intelligence race, we believe capex will broaden to include equipment manufacturing of aircraft, auto and power generation. Historically, rising capex has been a catalyst for stronger economic growth, and we expect that pattern to hold in 2026.
RELATED CONTENT
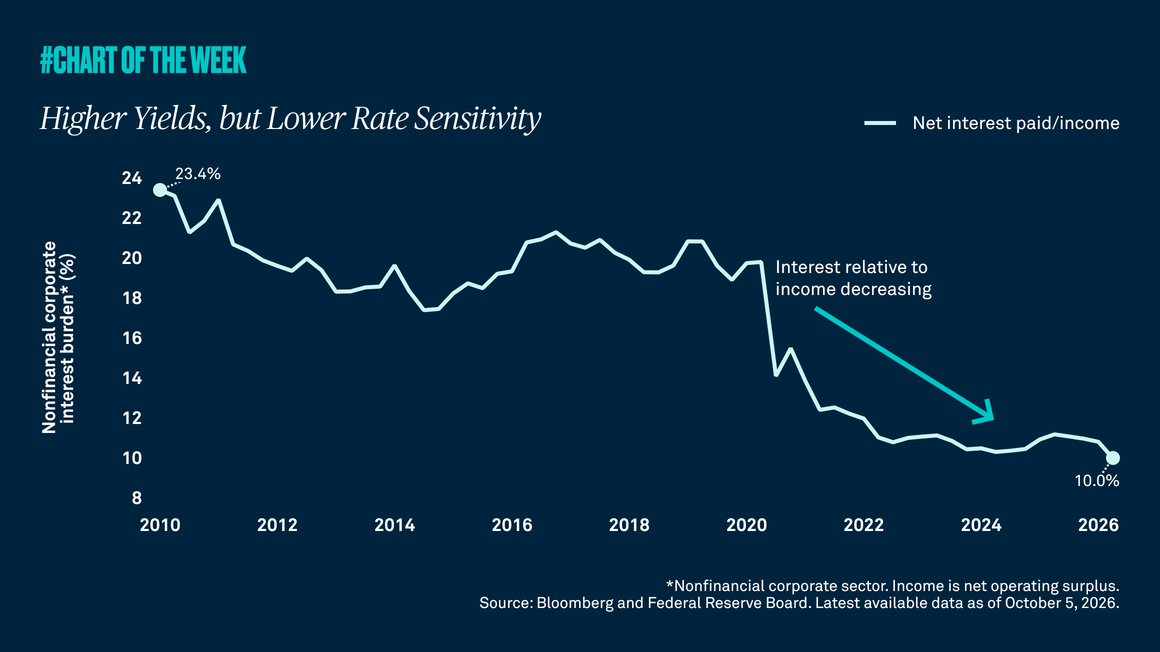
Higher yields, but lower sensitivity
Chart of the Week | Macroeconomic

Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.

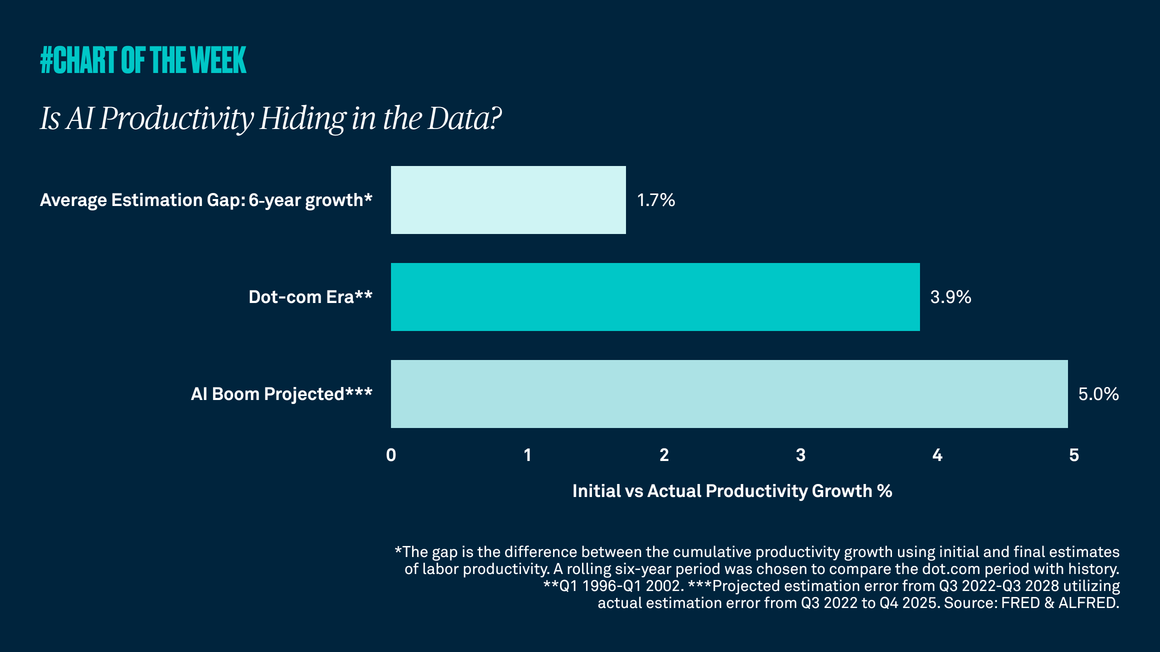
Is AI productivity hiding in the data?
Chart of the Week | Macroeconomic

Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.

History of stocks after the fed hikes
Chart of the Week | Macroeconomic

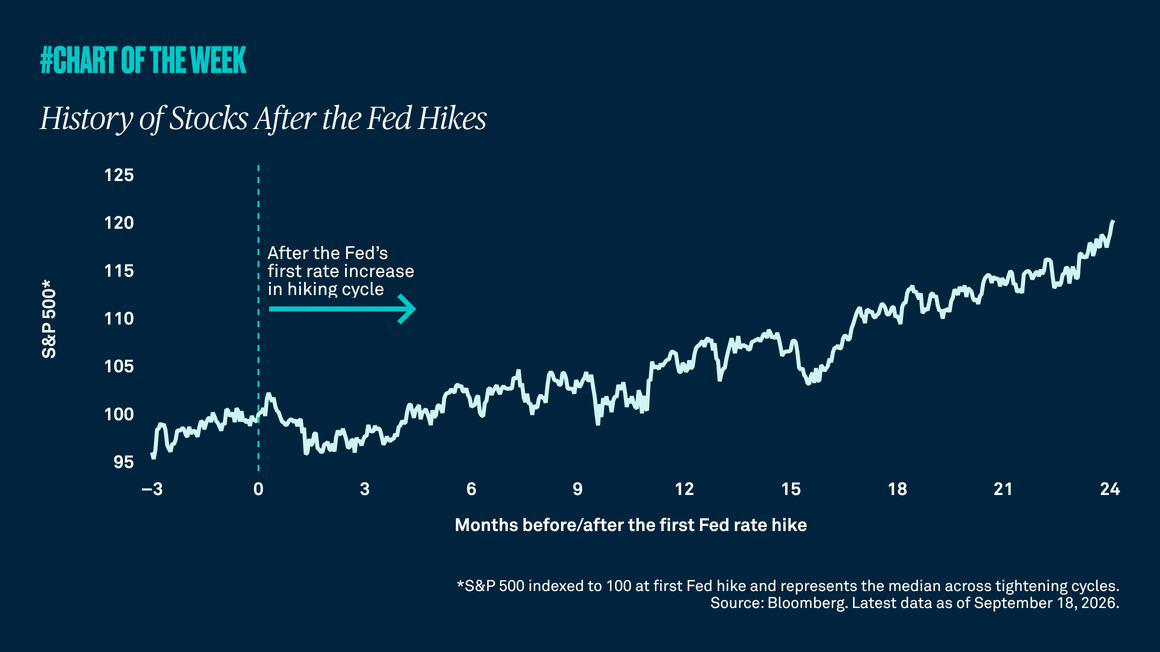
Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.

Inflation is a global problem
Chart of the Week | Macroeconomic

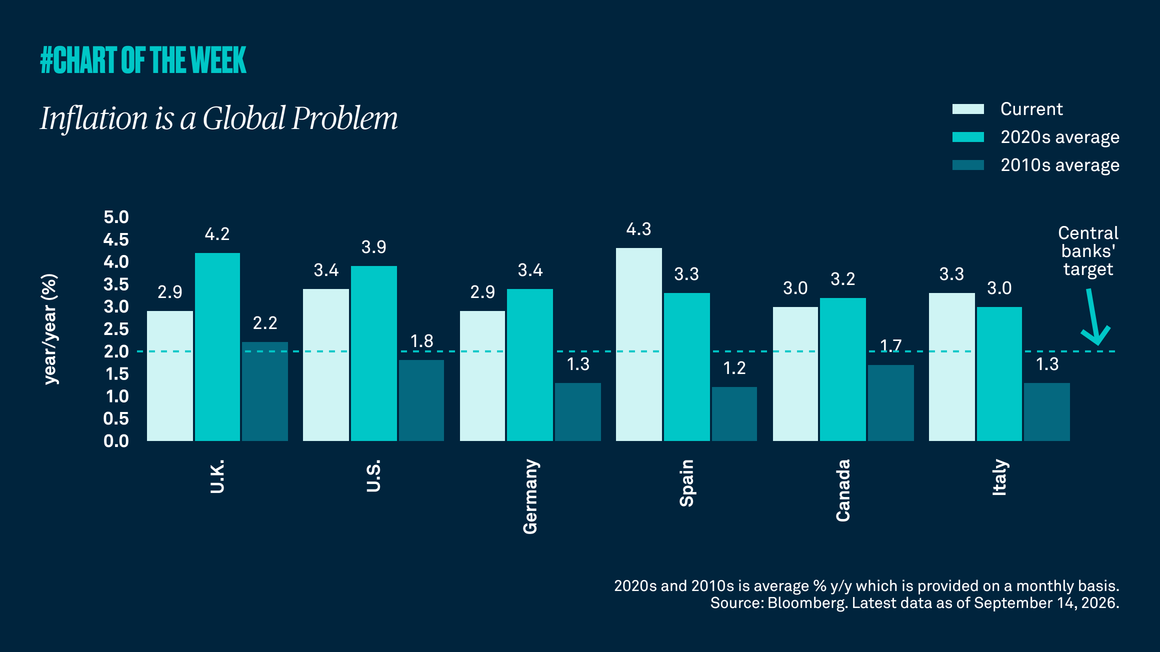
Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.

Gathering data
Disclaimer Not Available

This is a marketing communication