Please ensure Javascript is enabled for purposes of website accessibility Will markets remain resilient?
ch
de
intermediary
intermediary
false
true
Gathering data
Disclaimer Not Available

Will markets remain resilient?

Will markets remain resilient?

Global equities have risen an annualized 11% since 2020 despite repeated shocks, as resilient growth and earnings have helped markets recover from periods of volatility. While the U.S.-Iran conflict poses near-term inflation and growth risks, markets remain constructive as earnings expectations continue to improve.
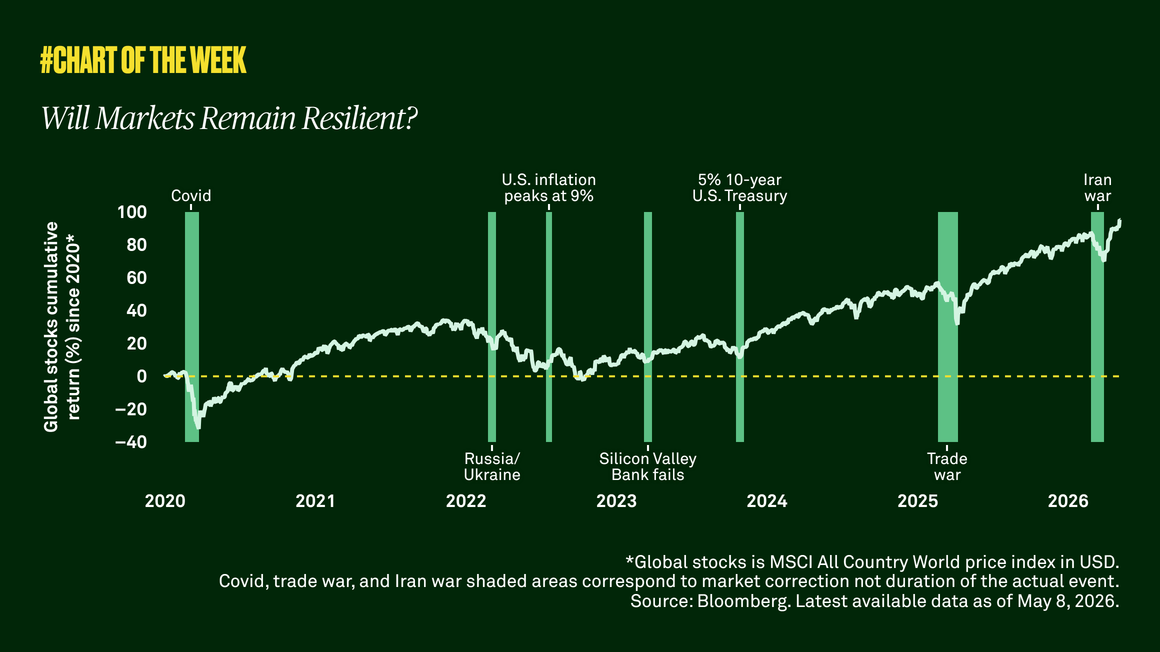

Since 2020, global equities have delivered strong gains of an annualized 11% even after absorbing a series of shocks, including the pandemic, the Russia-Ukraine war, inflation spikes, aggressive central bank rate hikes, and tariffs. Each of these events drove volatility and selloffs, but markets repeatedly recovered as growth proved more durable than anticipated and investors continued to look through near-term turbulence.

Now, with the U.S. entangled in conflict with Iran, investors face a geopolitical shock that could push energy prices higher, reignite inflation and weigh on global growth in the near term. Even so, markets appear to be pricing this as a temporary event rather than the start of something associated with a longer downturn.

In the U.S., resilient economic growth and stronger-than-expected earnings are supporting higher equity prices this year despite these risks. A renewed inflation wave or disappointing returns on AI-related capital spending could still pressure profits and growth, but for now, earnings expectations are increasing. As a result, we believe risk sentiment in the U.S. and globally remain constructive.
VERWANDTE THEMEN
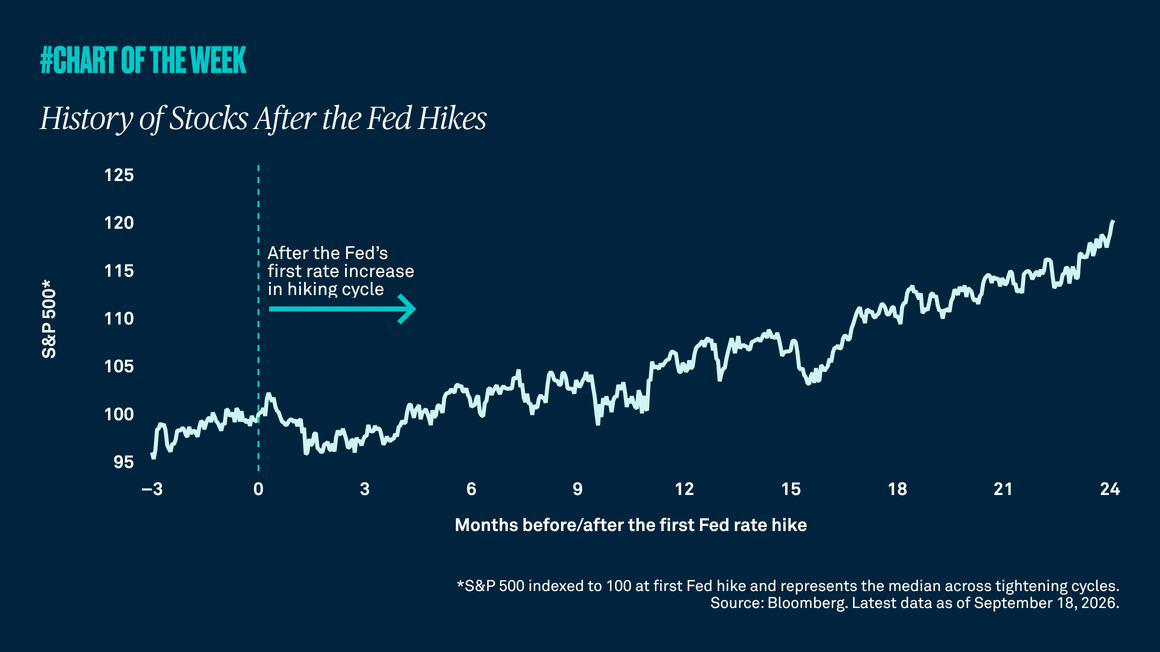
History of stocks after the fed hikes
Chart of the Week | Makroökonomisch

Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.

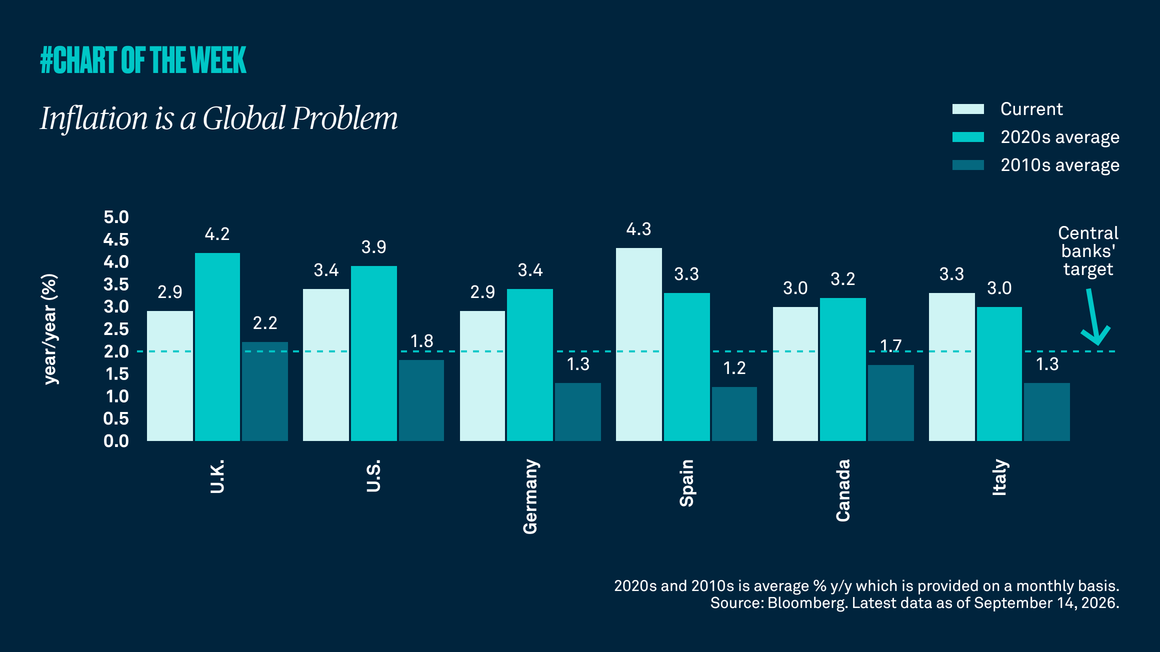
Inflation is a global problem
Chart of the Week | Makroökonomisch

Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.

A good outlook for global earnings
Chart of the Week | Makroökonomisch

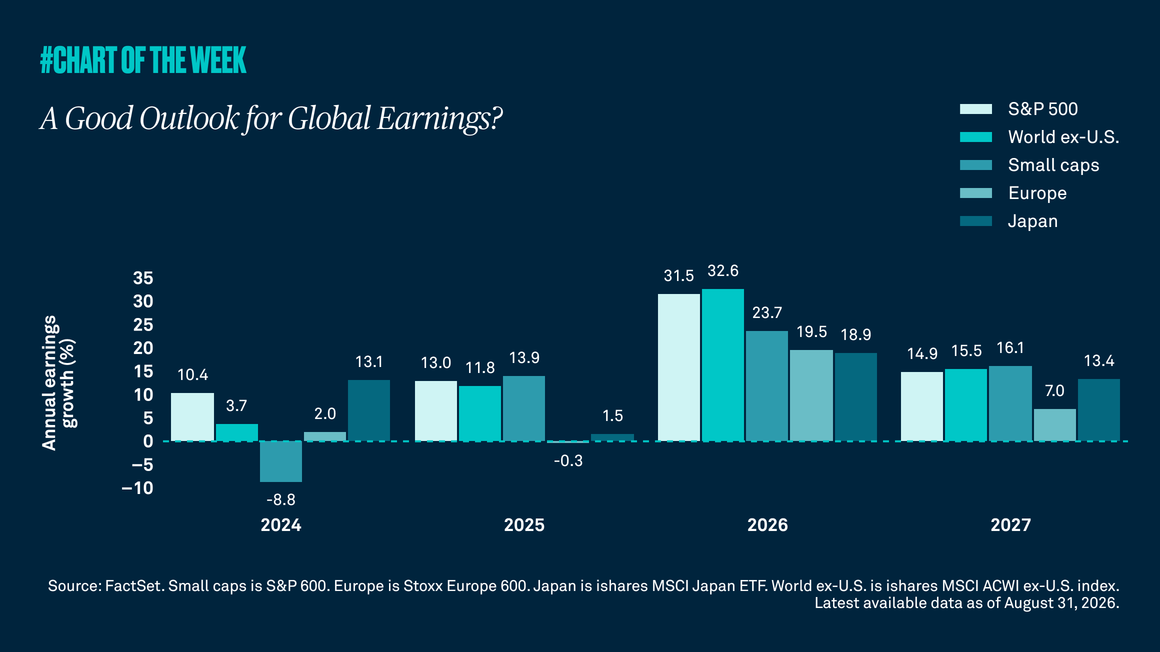
Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

In a real regime shift?
Chart of the Week | Makroökonomisch

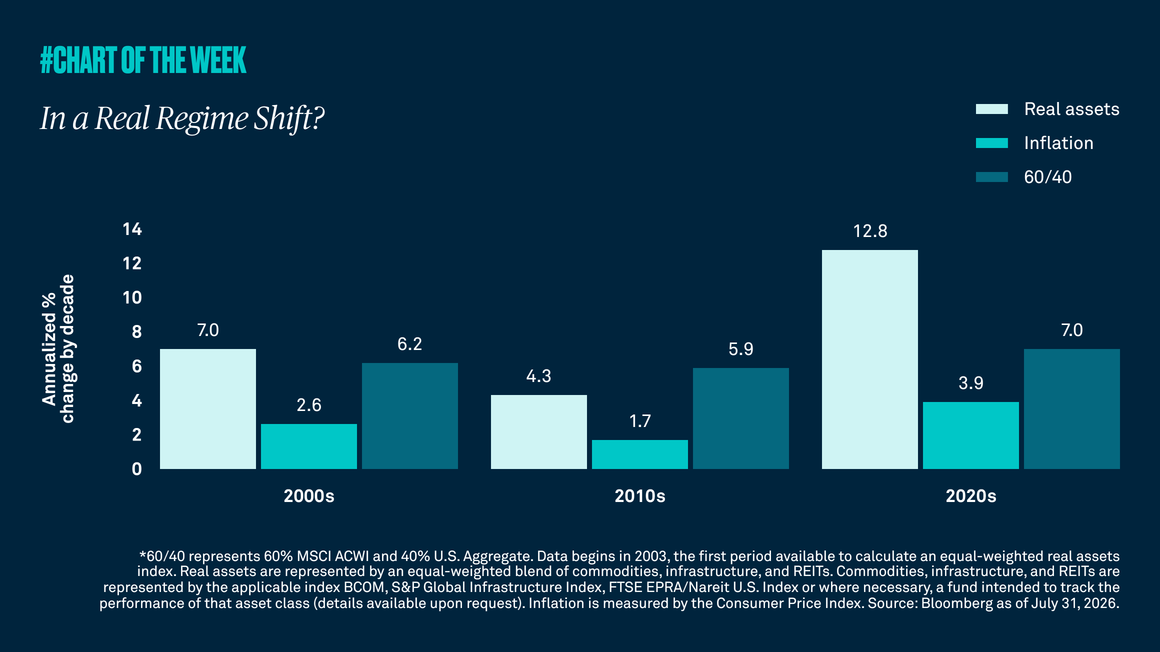
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Gathering data
Disclaimer Not Available

Dies ist eine Marketingkommunikation