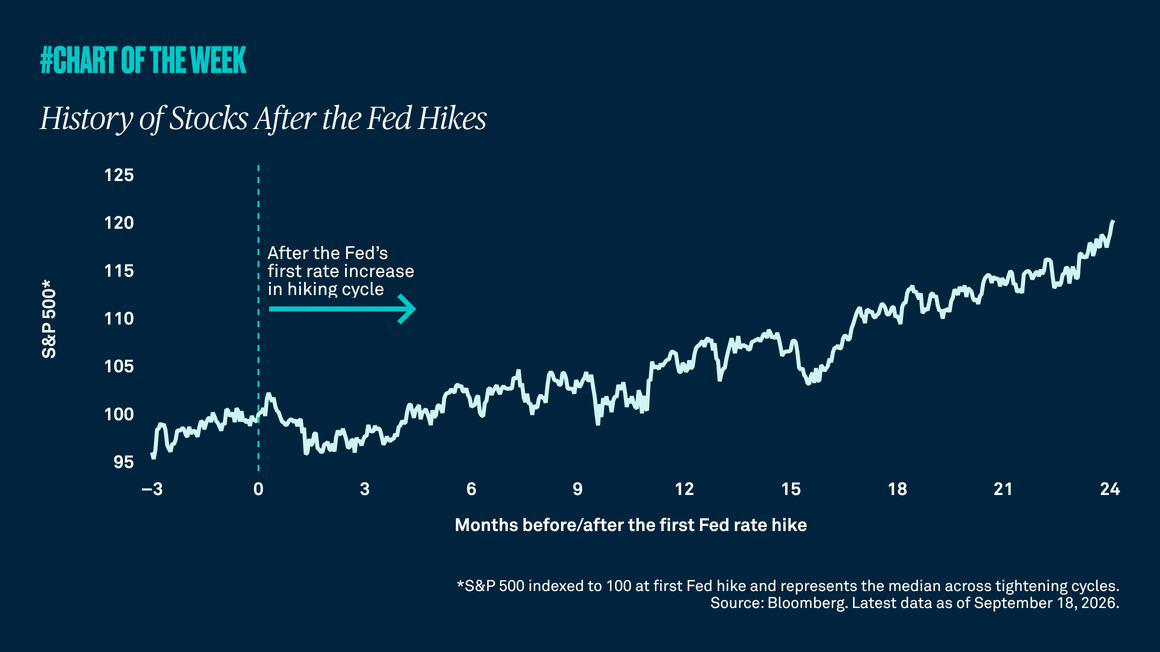
Inflation is no longer behaving like a temporary shock. As policy choices, geopolitical tensions, demographic shifts and deglobalisation reshape the investment backdrop, the assumptions that supported the last decade of portfolio construction may no longer be enough.
If inflation remains structurally higher, investors may need to reassess return expectations, prepare for greater dispersion across markets, and place more emphasis on actively managing inflation risk. In this context, we consider how BNY’s Real Return strategy may be relevant for investors seeking a more flexible approach to navigating persistent inflation and its wider market effects.
How does inflation affect your investment universe?
The inflationary backdrop changes the rules that many portfolios were built around. For much of the last three decades, the 60/40 equity-bond portfolio worked well. Equities drove growth; bonds cushioned returns, typically rallying when equities fell, to provide genuine diversification. The negative correlation between the two asset classes was not a fundamental principle; rather, it reflected the characteristics of a disinflationary, falling interest-rate environment. As inflation has proven stickier than expected, remaining at 3% to 4% in many developed markets rather than near 2%, that relationship has broken down.
We believe we are now in an environment of fiscal dominance, where government spending and borrowing shape financial assets more than monetary policy does. With deficits running at levels that can put government bond markets under pressure, duration can sometimes become a risk rather than a source of protection.
The structural conditions that made broad market exposure effective appear to have shifted in a fundamental way. The opportunity set is changing, and we think that makes active, selective positioning increasingly important, directing capital towards assets more likely to prove resilient in an environment of persistent inflation and fiscal pressure.
Given the current inflationary backdrop, how can absolute-return strategies help?
We believe absolute-return-seeking portfolios like BNY's Real Return strategy may be a relevant option for some investors seeking flexibility in this environment. A portfolio with an absolute-return objective is constructed differently from one designed to track or beat a benchmark over short periods. That perspective matters because it centres the process on client-relevant outcomes, not relative returns that may owe more to benchmark exposure than genuine differentiation. The strategy has a dynamic approach to asset allocation that provides the flexibility to adjust positioning both strategically and tactically to reflect changing economic circumstances.
Given the inflationary backdrop, we have favoured shorter-duration positioning, where carry can be generated without taking on significant duration risk. We also have significant exposure to real assets and selective equities with pricing power, alongside explicit protection against the downside risks that portfolios with index-based exposure may leave unhedged.
The strategy’s approach to diversification is designed to reduce exposure to concentration risk in major global equity indices, where nine stocks represent almost 25% of index exposure.1
The challenge is not simply choosing the right assets but constructing a portfolio that can participate in the upside while withstanding sharp drawdowns. These could include a recession scare, a policy error, or a geopolitical shock that turns out to be deflationary rather than inflationary.
The strategy manages risk without relying on a negative correlation between bonds and equities. Instead, it takes a broader, more diversified approach, using derivatives, safe-haven currencies, precious metals and tail-risk hedges. In some market conditions, explicit tail-risk management, deploying options and convex hedges, can be more efficient than buying index puts.
In a more demanding environment for portfolio construction, active management becomes more valuable.
“The challenge is not simply choosing the right assets but constructing a portfolio that can participate in the upside while withstanding sharp drawdowns.”
Where are you finding the most compelling opportunities right now, and what risks are you watching most closely?
We see the most compelling opportunities in real assets and selective, well-positioned equities. The case for commodities is structural, not tactical: demand is supported by supply-chain rebuilding, industrial capacity expansion, artificial intelligence energy needs, infrastructure spending and the energy transition. Meanwhile, years of underinvestment have left supply constrained. We see potential signs of a more supportive backdrop for commodities, with gold and silver, energy equities and metals such as uranium offering exposure.
Within equities, stock selection matters more in an inflationary environment. Companies with pricing power, international revenues and real-asset exposure are likely to be better placed than asset-light, high-multiple growth stocks. We see banks, healthcare and European defence as favourably positioned.
In fixed income, a short-duration approach leaves room for selective local-currency debt in resource-producing economies with strong external balances, such as Australia, New Zealand, Poland, Sweden and the Czech Republic.
One risk we are watching is the prospect of stagflation, or persistent inflation with slowing growth. Should this take hold, markets may prove to be too heavily positioned in assets vulnerable to that backdrop, notably growth equities and some areas of the bond market. Investors already ahead of that shift could be well placed to benefit.
1Source: MSCI ACWI Index factsheet (msci.com), 31 July 2026
The value of investments and the income received can fall as well as rise and investors may not get back the original amount invested.
Key investment risks: Real Return strategy
Objective/Performance Risk: There is no guarantee that the strategy will achieve its objectives.
Currency Risk: Strategies which invest in international markets may be exposed to changes in currency rates which could affect the value of their portfolios.
Geographic Concentration Risk: Where a strategy invests significantly in a single market, this may have a material impact on the value of its portfolio.
Derivatives Risk: Derivatives are highly sensitive to changes in the value of the asset from which their value is derived. A small movement in the value of the underlying asset can cause a large movement in the value of the derivative. This can increase the sizes of losses and gains, causing the value of your investment to fluctuate. When using derivatives, a strategy can lose significantly more than the amount it has invested in derivatives.
Changes in Interest Rates & Inflation Risk: Investments in bonds/money market securities are affected by interest rates and inflation trends which may negatively affect the value of the strategy.
Credit Ratings and Unrated Securities Risk: Bonds with a low credit rating or unrated bonds have a greater risk of default. These investments may negatively affect the value of the strategy.
Credit Risk: The issuer of a security held by the strategy may not pay income or repay capital to the portfolio when due.
Emerging Markets Risk: Emerging Markets have additional risks due to less-developed market practices.
Liquidity Risk: The strategy may not always find another party willing to purchase an asset that the strategy wants to sell which could impact the strategy’s ability to sell the asset or to sell the asset at its current value.
Shanghai-Hong Kong Stock Connect and/or the Shenzhen-Hong Kong Stock Connect (‘Stock Connect’) Risk: The strategy may invest in China A shares through Stock Connect programmes. These may be subject to regulatory changes and quota limitations. An operational constraint such as a suspension in trading could negatively affect the strategy’s ability to achieve its investment objective.
China Interbank Bond Market and Bond Connect Risk: The strategy may invest in China interbank bond market through connection between the related Mainland and Hong Kong financial infrastructure institutions. These may be subject to regulatory changes, settlement risk and quota limitations. An operational constraint such as a suspension in trading could negatively affect the strategy’s ability to achieve its investment objective.
CoCos Risk: Contingent convertible securities (CoCos) convert from debt to equity when the issuer’s capital drops below a pre-defined level. This may result in the security converting into equities at a discounted share price, the value of the security being written down, temporarily or permanently, and/or coupon payments ceasing or being deferred.
Counterparty Risk: The insolvency of any institutions providing services such as custody of assets or acting as a counterparty to derivatives or other contractual arrangements, may expose the strategy to financial loss.
Investment in Infrastructure Companies Risk: The value of investments in Infrastructure Companies may be negatively impacted by changes in the regulatory, economic or political environment in which they operate.
2035400 Exp: 18 September 2027