Please ensure Javascript is enabled for purposes of website accessibility

In a Real Regime Shift?

In a Real Regime Shift?

Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.
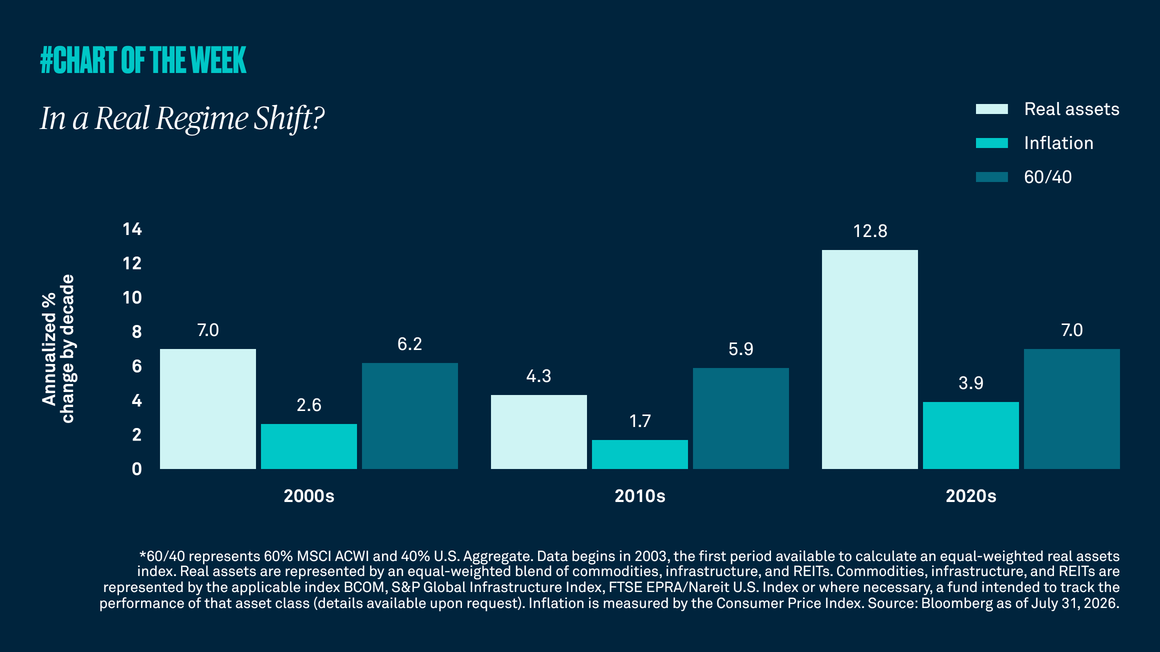
For much of the 2000s, inflation was broadly contained, averaging around 2.6% in the first decade and falling below 2.0% during the 2010s following the global financial crisis. Since the pandemic, however, inflation has shifted into a meaningfully higher range, with annualized inflation running at roughly 4% this decade — more than double the pace of the prior decade. In our view, various factors including event-driven spikes, such as COVID and energy-driven supply shocks, as well as deglobalization, suggest that inflation is likely to remain structurally higher than it was in the years preceding COVID.


As inflation has moved higher, real assets have meaningfully outperformed. Real assets have generated annualized returns of 12.8% this decade, compared to approximately 7% for a traditional 60/40 portfolio, while returns for real assets are roughly three times the level achieved in the 2010s. We believe this relative outperformance reflects more than a short-term cyclical adjustment and instead points to a long-term trend.


Importantly, the case for real assets is not driven by inflation alone. We also see support from a durable capital expenditure cycle reinforced by several powerful secular trends, including infrastructure investment, increased defense spending, onshoring across industries and the continued buildout of artificial intelligence-related capacity.


Given these factors, it’s important for investors to review their portfolio mix and consider including real assets as a way to enhance diversification, improve return potential and position for a structurally higher inflation environment.
  • Chart of the Week
RELATED CONTENT
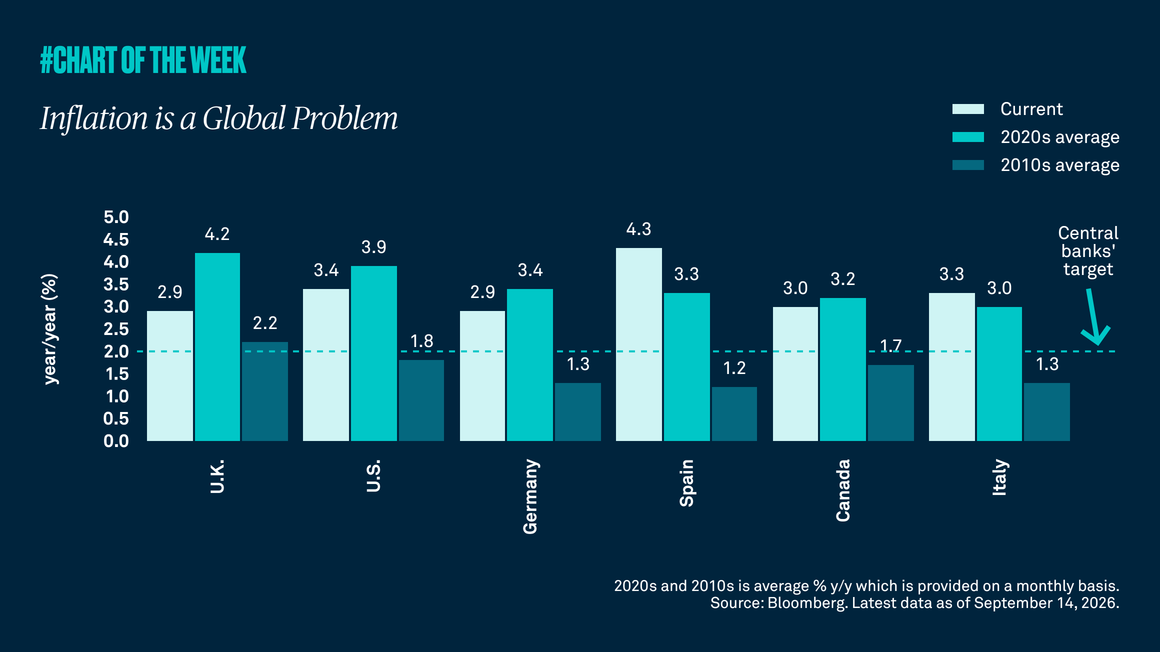
Inflation Is a Global Problem
Article  |  Chart of the Week

Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.

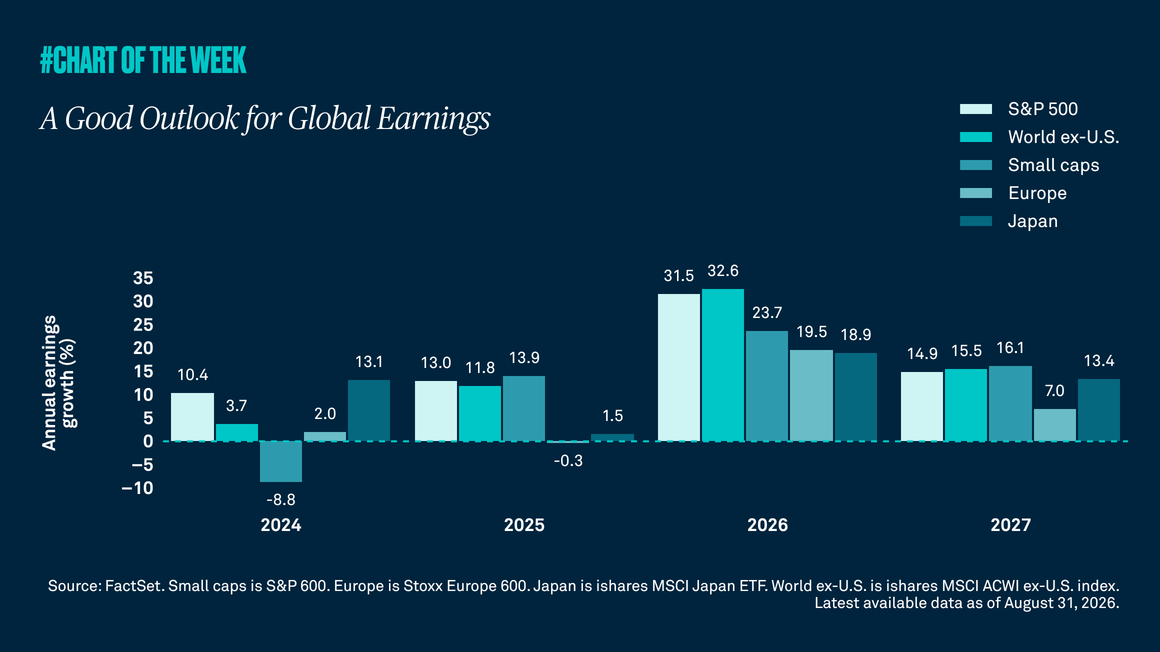
A Good Outlook for Global Earnings
Article  |  Chart of the Week

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

Getting Real with Real Assets
Article  |  Chart of the Week

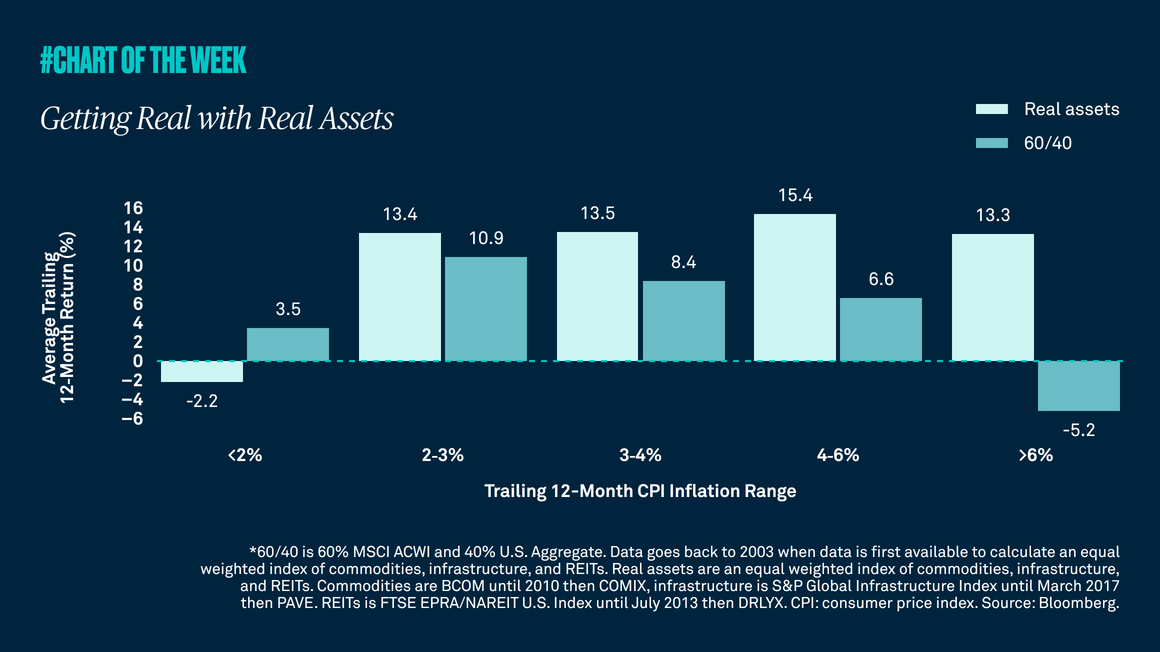
Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Not in a Bubble
Article  |  Chart of the Week

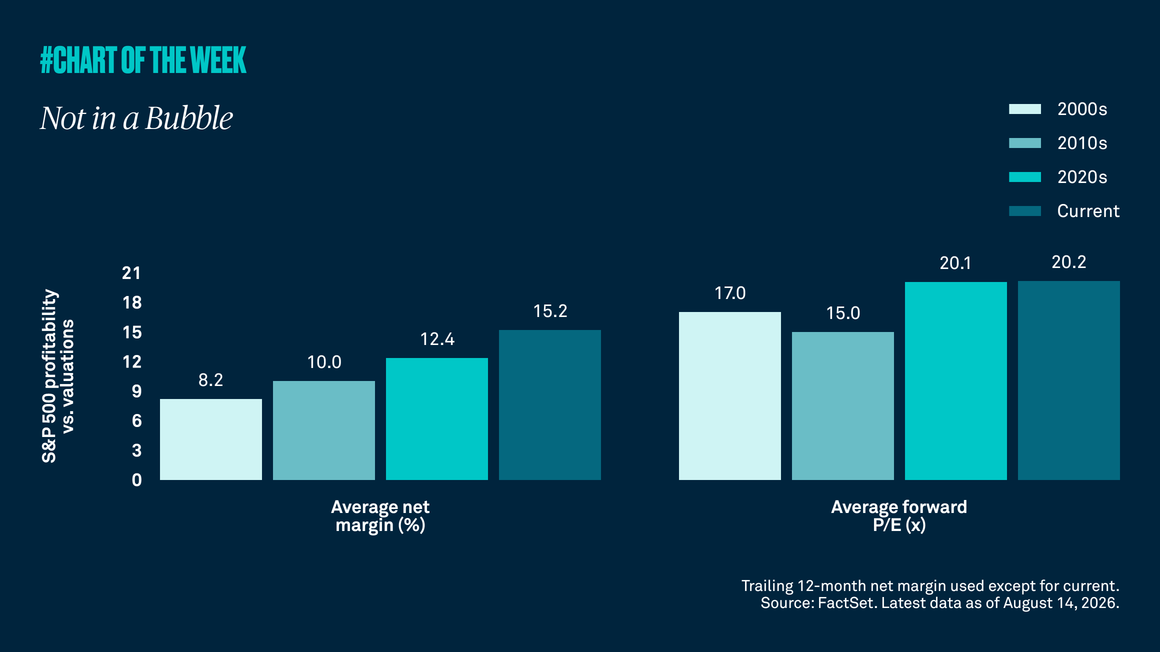
As the S&P 500 approaches all-time highs, there are renewed concerns among investors about elevated valuations. However, historically strong profitability and expected earnings growth appear to support current pricing. In addition, the current S&P 500 price-to-earnings (P/E) ratio is roughly equal to the average since Covid. As a result, we do not view U.S. equities as being in bubble territory and we remain constructive on the asset class.

Past performance is no guarantee of future results. This material is provided for illustrative/educational purposes only. This material is not intended to constitute legal, tax, investment or financial advice. Effort has been made to ensure that the material presented herein is accurate at the time of publication. However, this material is not intended to be a full and exhaustive explanation of the law in any area or of all of the tax, investment or financial options available. The information discussed herein may not be applicable to or appropriate for every investor and should be used only after consultation with professionals who have reviewed your specific situation.


The Bank of New York Mellon, DIFC Branch (the “Authorized Firm”) is communicating these materials on behalf of The Bank of New York Mellon. The Bank of New York Mellon is a wholly owned subsidiary of The Bank of New York Mellon Corporation. This material is intended for Professional Clients only and no other person should act upon it. The Authorized Firm is regulated by the Dubai Financial Services Authority and is located at Dubai International Financial Centre, The Exchange Building 5 North, Level 6, Room 601, P.O. Box 506723, Dubai, UAE.


The Bank of New York Mellon is supervised and regulated by the New York State Department of Financial Services and the Federal Reserve and authorized by the Prudential Regulation Authority. The Bank of New York Mellon London Branch is subject to regulation by the Financial Conduct Authority and limited regulation by the Prudential Regulation Authority. Details about the extent of our regulation by the Prudential Regulation Authority are available from us on request. The Bank of New York Mellon is incorporated with limited liability in the State of New York, USA. Head Office: 240 Greenwich Street, New York, NY, 10286, USA.


In the U.K. a number of the services associated with BNY Wealth’s Family Office Services– International are provided through The Bank of New York Mellon, London Branch, One Canada Square, London, E14 5AL. The London Branch is registered in England and Wales with FC No. 005522 and BR000818.


Investment management services are administered by BNY Mellon Investment Management EMEA Limited, BNY Mellon Centre, 160 Queen Victoria Street, London EC4V 4LA. Registered in England No. 1118580. Authorised and regulated by the Financial Conduct Authority. Offshore trust and administration services are through BNY Trust Company (Cayman) Ltd.


This document is issued in the U.K. by The Bank of New York Mellon. In the United States the information provided within this document is for use by professional investors.


This material is a financial promotion in the U.K. and EMEA. This material, and the statements contained herein, are not an offer or solicitation to buy or sell any products (including financial products) or services or to participate in any particular strategy mentioned and should not be construed as such.


BNY Mellon Fund Services (Ireland) Limited is regulated by the Central Bank of Ireland BNY Mellon Investment Servicing (International) Limited is regulated by the Central Bank of Ireland.


Trademarks and logos belong to their respective owners.


BNY Wealth conducts business through various operating subsidiaries of The Bank of New York Mellon Corporation. BNY is the corporate name of The Bank of New York Mellon Corporation and may be used to reference the corporation as a whole and/or its various subsidiaries generally.


©2026 The Bank of New York Mellon. All rights reserved.

WI-994747-2026-09-01

Let’s start a conversation.

SUBSCRIBE