Energy inflation is no longer just a crude oil story. Crude oil prices have been volatile and elevated since the onset of the Middle East conflict, raising concerns that higher oil prices could keep inflation elevated for longer. But recent moves in energy markets suggest the inflation risk extends beyond crude oil.
An Unusual Divergence
While crude oil prices have eased from April highs, refined fuel prices such as gasoline and diesel have increased. The crack spread, or the margin refiners capture between the cost of crude oil and the price of the refined products they sell, has widened significantly. Historically, crude prices and crack spreads have tended to move together. But recently, that relationship has broken down.
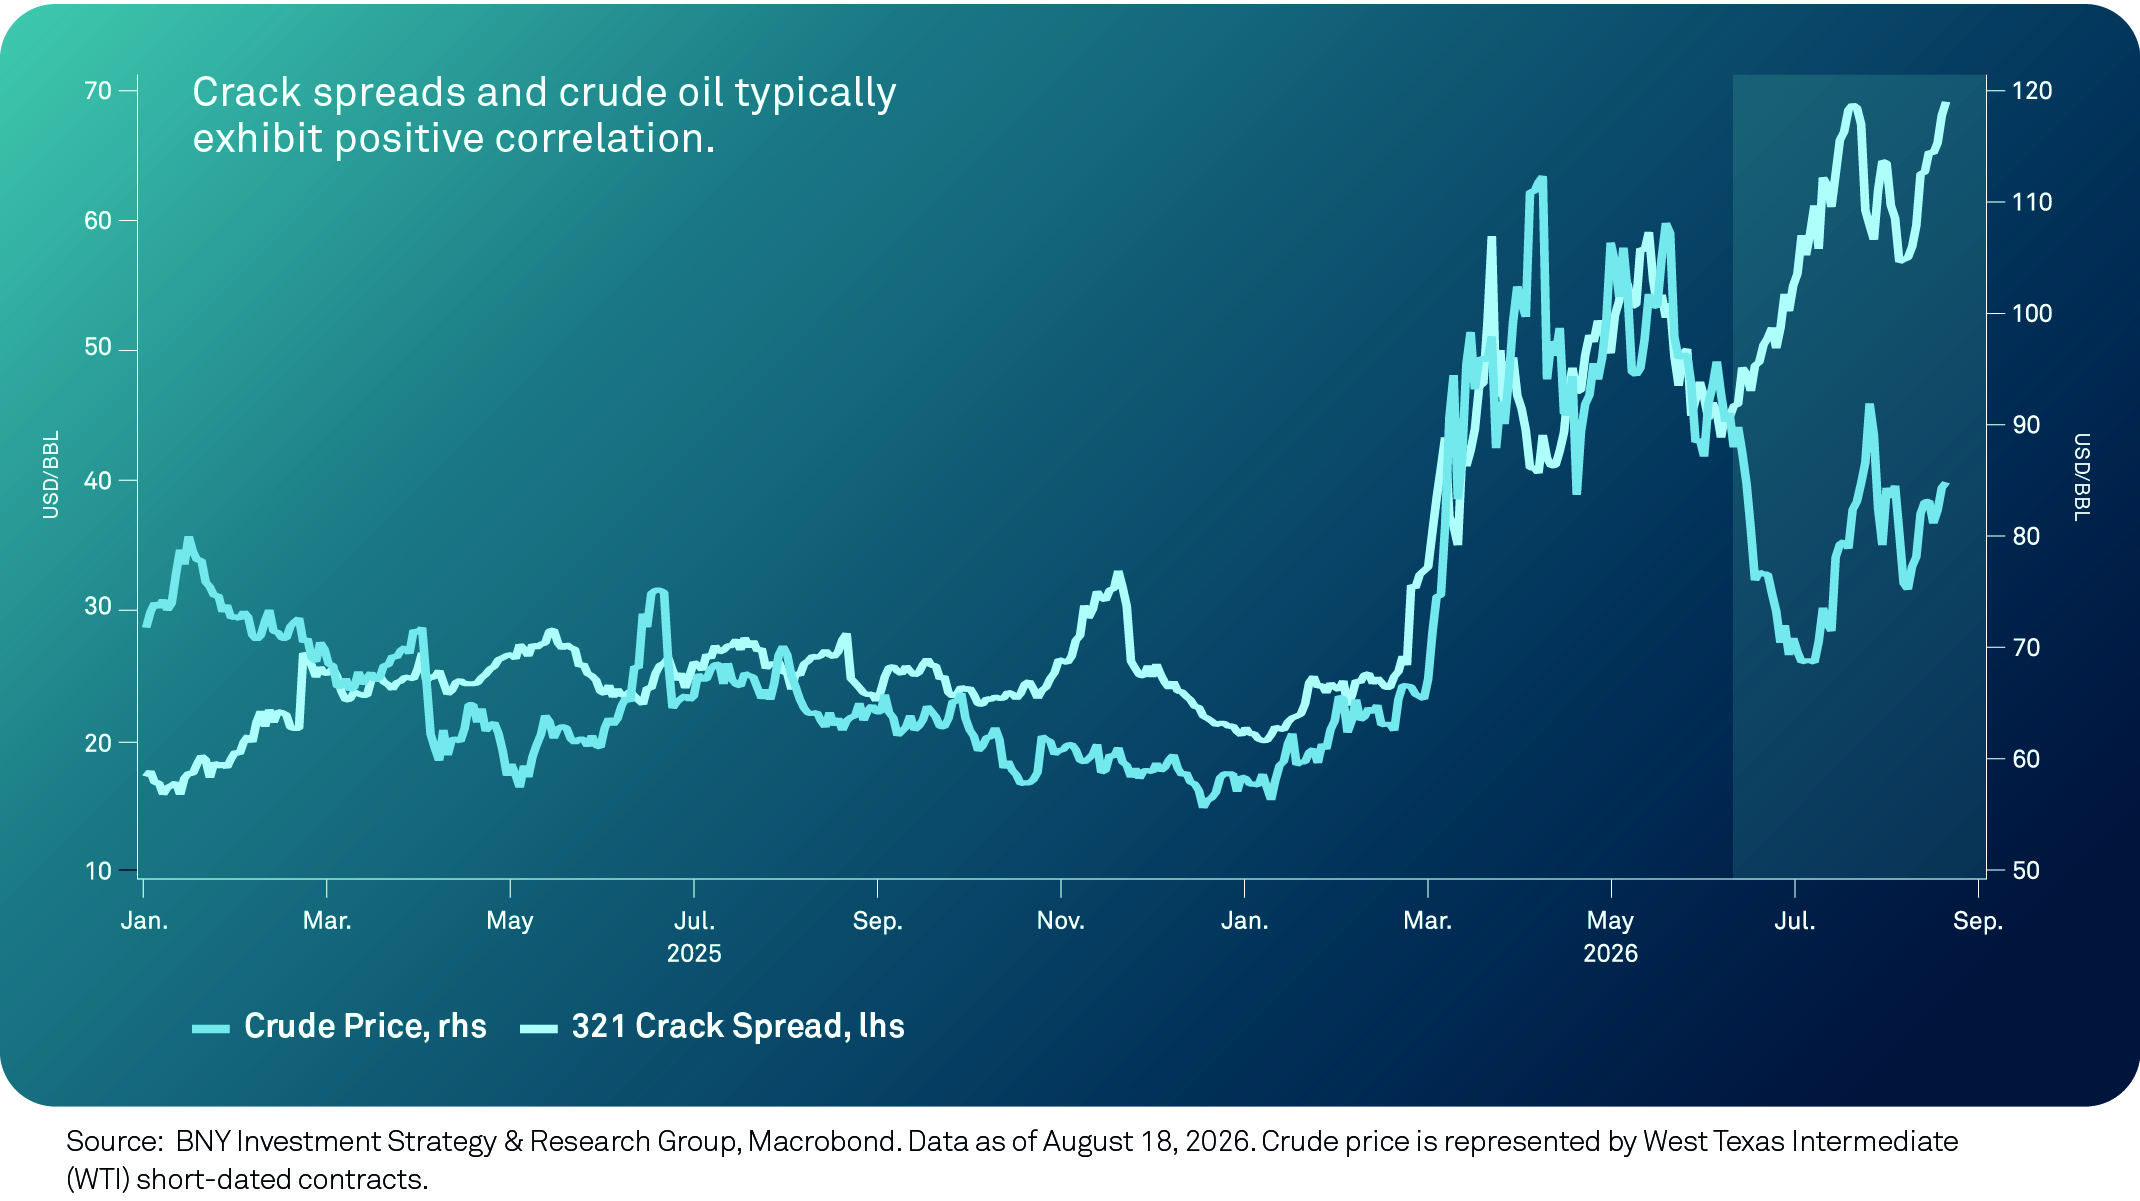
This divergence suggests that inflationary pressure stems more from tight supplies of refined products rather than crude oil alone. Refinery disruptions and low inventories are contributing to stockpiling of finished fuels by certain countries and adding to demand for gasoline, diesel, and other refined products at a time when supply is already constrained. As a result, energy costs could remain heightened even if crude oil prices ease.
Potential Spillover
Higher fuel prices can have a direct impact on inflation through gasoline and other household energy costs. If elevated energy prices persist, the effects could spread beyond the energy sector as increased fuel and transportation costs put upward strain on prices across other parts of the economy. With inflation expectations already showing signs of becoming less anchored, persistent energy pressures could increase the risk that inflation remains higher for longer.
Positioning for Sticky Inflation
If energy prices keep pressure on inflation, at a time when trend inflation is above target, monetary policy could remain more restrictive in response. However, central bank actions are unlikely to be uniform as a weaker growth outlook in certain regions may allow them to take a more accommodative stance. We believe that diverging inflation and growth dynamics could create opportunities for active positioning across global fixed income.
3-2-1 crack spread is a refining margin benchmark that assumes 3 barrels of crude oil yield 2 barrels of gasoline and 1 barrel of distillate, measuring the gross profit per barrel from converting crude into these products.
Important Information
BNY Investments is the brand name for the investment management business of BNY and its investment firm affiliates worldwide. BNY is the corporate brand of The Bank of New York Mellon Corporation and may be used to reference the corporation as a whole or its various subsidiaries generally.
The information contained herein reflects general views and is provided for informational purposes only. This material is not intended as investment advice nor is it a recommendation to adopt any investment strategy.
Opinions and views expressed are subject to change without notice.
Past performance is no guarantee of future results.
Issuing entities
This material is only for distribution in those countries and to those recipients listed, subject to the noted conditions and limitations: • United States: by BNY Mellon Securities Corporation (BNYSC), 240 Greenwich Street, New York, NY 10286. BNYSC, a registered broker-dealer and FINRA member, has entered into agreements to offer securities in the U.S. on behalf of certain BNY Investments firms. • Europe (excluding Switzerland): BNY Mellon Fund Management (Luxembourg) S.A., 2-4 Rue EugèneRuppertL-2453 Luxembourg. • UK, Africa and Latin America (ex-Brazil): BNY Mellon Investment Management EMEA Limited, BNY Mellon Centre, 160 Queen Victoria Street, London EC4V 4LA. Registered in England No. 1118580. Authorised and regulated by the Financial Conduct Authority. • South Africa: BNY Mellon Investment Management EMEA Limited is an authorised financial services provider. • Switzerland: BNY Mellon Investments Switzerland GmbH, Bärengasse 29, CH-8001 Zürich, Switzerland. • Middle East: DIFC branch of The Bank of New York Mellon. Regulated by the Dubai Financial Services Authority. • South East Asia and South Asia: BNY Mellon Investment Management Singapore Pte. Limited Co. Reg. 201230427E. Regulated by the Monetary Authority of Singapore. • Hong Kong: BNY Mellon Investment Management Hong Kong Limited. Regulated by the Hong Kong Securities and Futures Commission. • Japan: BNY Mellon Investment Management Japan Limited. BNY Mellon Investment Management Japan Limited is a Financial Instruments Business Operator with license no 406 (Kinsho) at the Commissioner of Kanto Local Finance Bureau and is a Member of the Investment Trusts Association, Japan and Japan Investment Advisers Association and Type II Financial Instruments Firms Association. • Brazil: ARX Investimentos Ltda., Av. Borges de Medeiros, 633, 4th floor, Rio de Janeiro, RJ, Brazil, CEP 22430-041. Authorized and regulated by the Brazilian Securities and Exchange Commission (CVM). • Canada: BNY Mellon Asset Management Canada Ltd. is registered in all provinces and territories of Canada as a Portfolio Manager and Exempt Market Dealer, and as a Commodity Trading Manager in Ontario. All issuing entities are subsidiaries of The Bank of New York Mellon Corporation.
No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission. All information contained herein is proprietary and is protected under copyright law.
NOT FDIC INSURED | NO BANK GUARANTEE | MAY LOSE VALUE
© 2026 THE BANK OF NEW YORK MELLON CORPORATION
MARK-988257-2026-08-18
GU-928-31 August 2027