Please ensure Javascript is enabled for purposes of website accessibility A Good Outlook for Global Earnings
ch
de
intermediary
intermediary
false
true
Gathering data
Disclaimer Not Available

A good outlook for global earnings

A good outlook for global earnings

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.
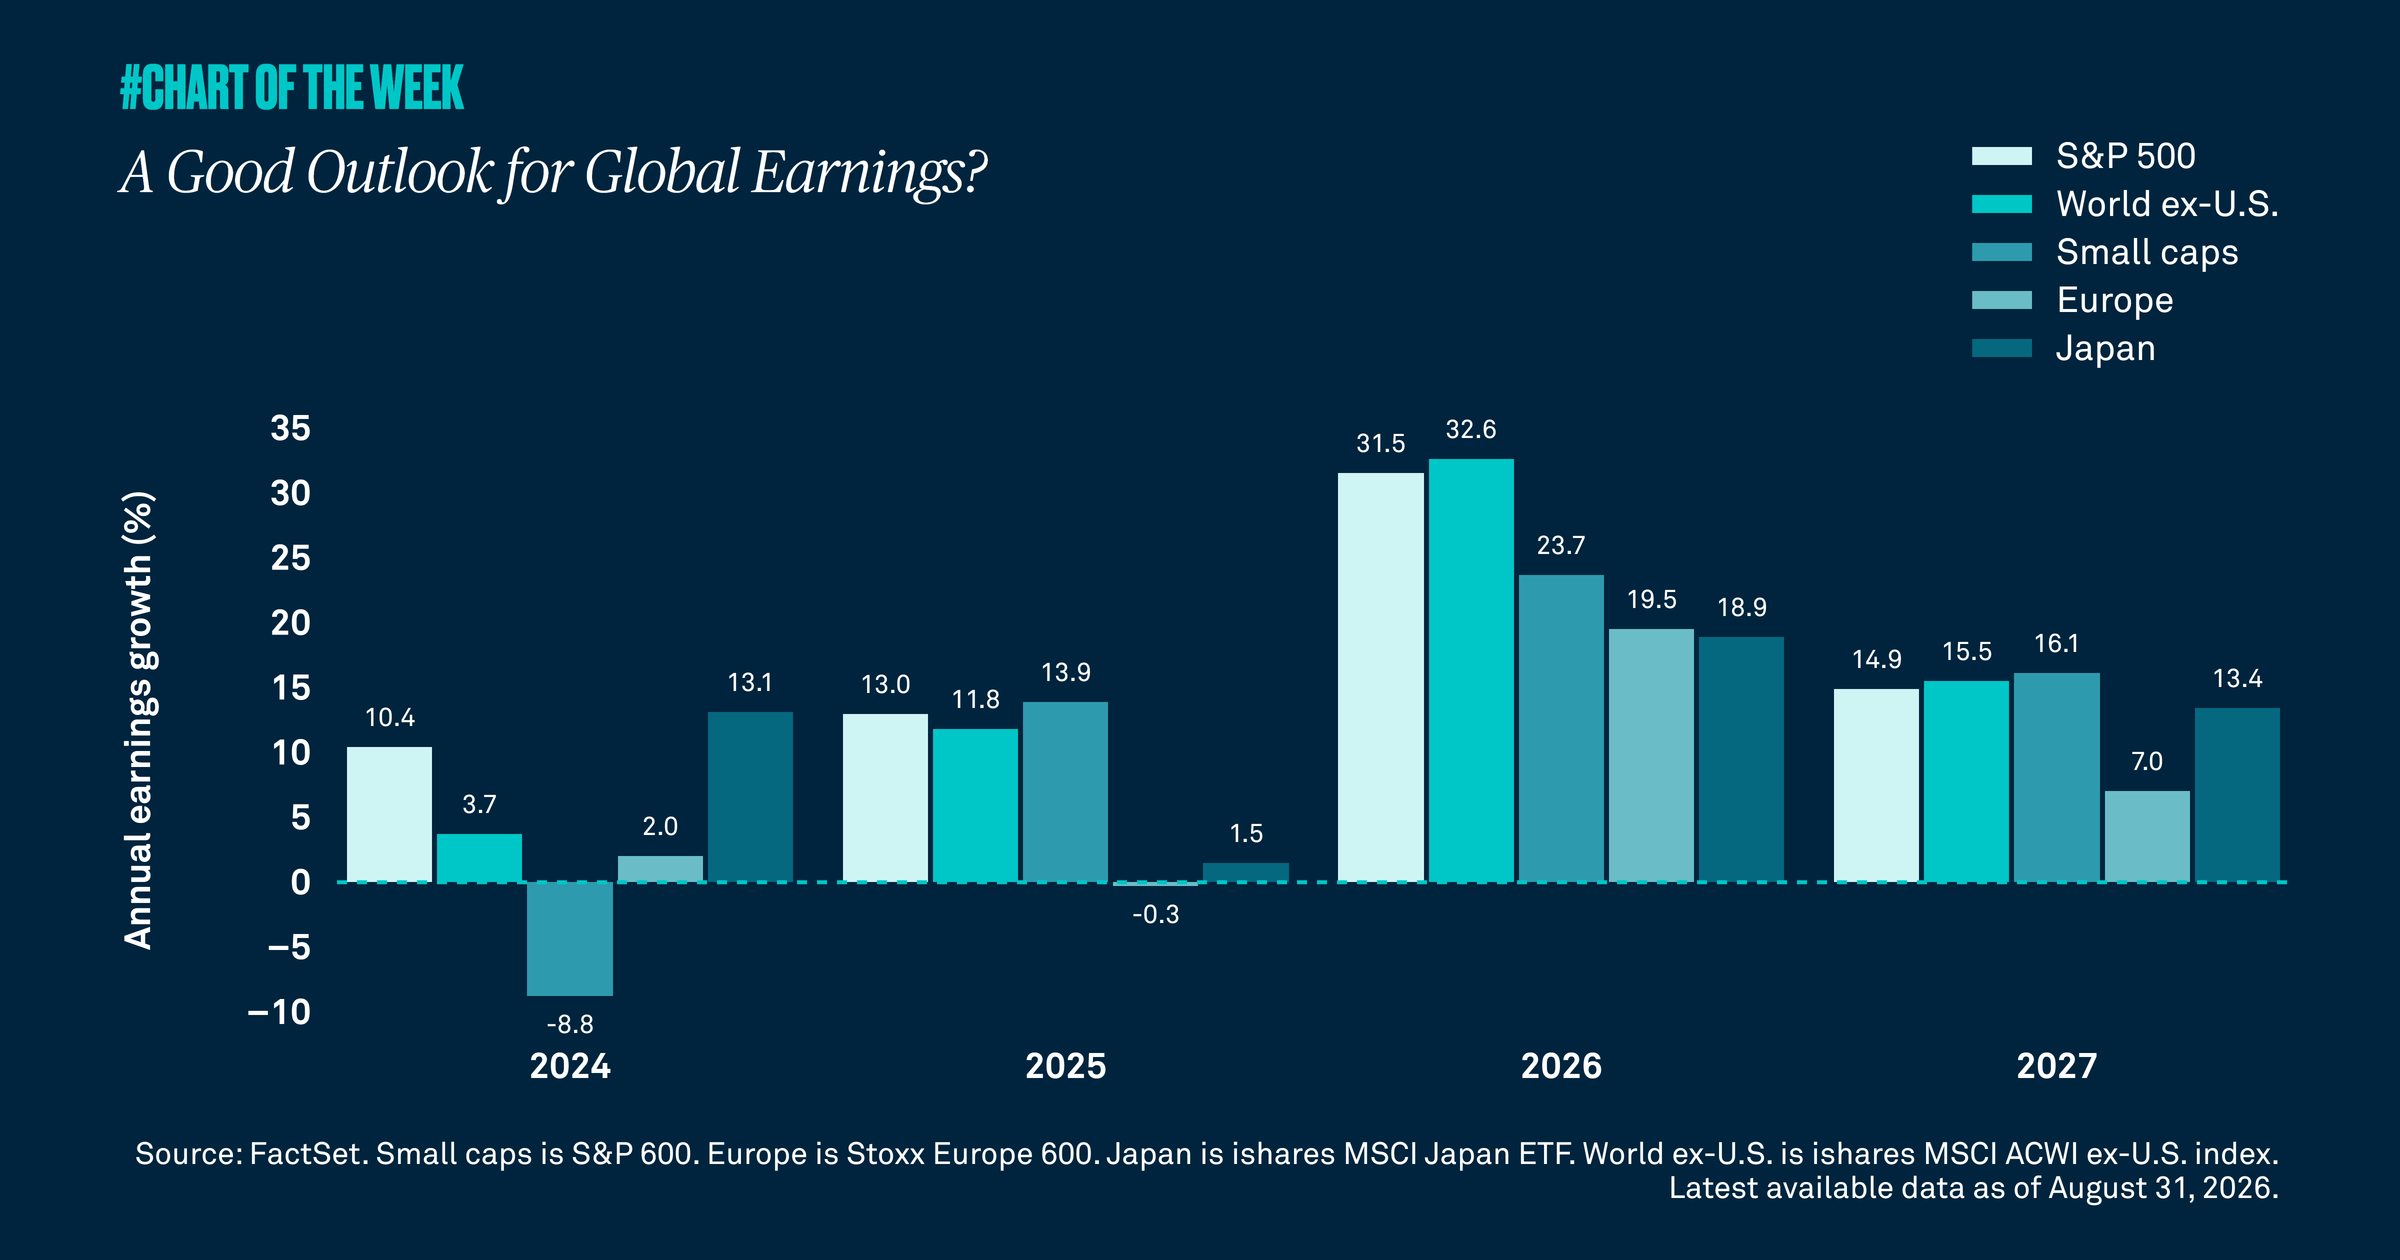

This year has been notable for the strength of global earnings growth. In the U.S., S&P 500 earnings are expected to rise 31.5% in 2026, up sharply from 13% in 2025. The story does not end there. Earnings growth has improved meaningfully across Europe, Japan and other major markets, with each region expected to deliver profit growth well above last year’s pace.

Though global earnings momentum is likely to slow in 2027 from this year’s unusually strong levels, growth may still remain above historical averages. That should matter for markets, especially as the earnings story has broadened beyond a narrow group of U.S. stocks. Corporate margins continue to rise, and while artificial intelligence-related capital spending has been a major driver of growth, the broader market remains fundamentally solid.

We do expect volatility to increase as markets contend with a range of uncertainties, including higher U.S. Treasury yields, the approaching midterm elections and ongoing geopolitical tensions. Still, we view the combination of above-average earnings growth and broad-based global participation as a clear positive for the forward outlook for global equities. After all, earnings growth remains the key driver of long-term market returns. We therefore remain constructive.
VERWANDTE THEMEN
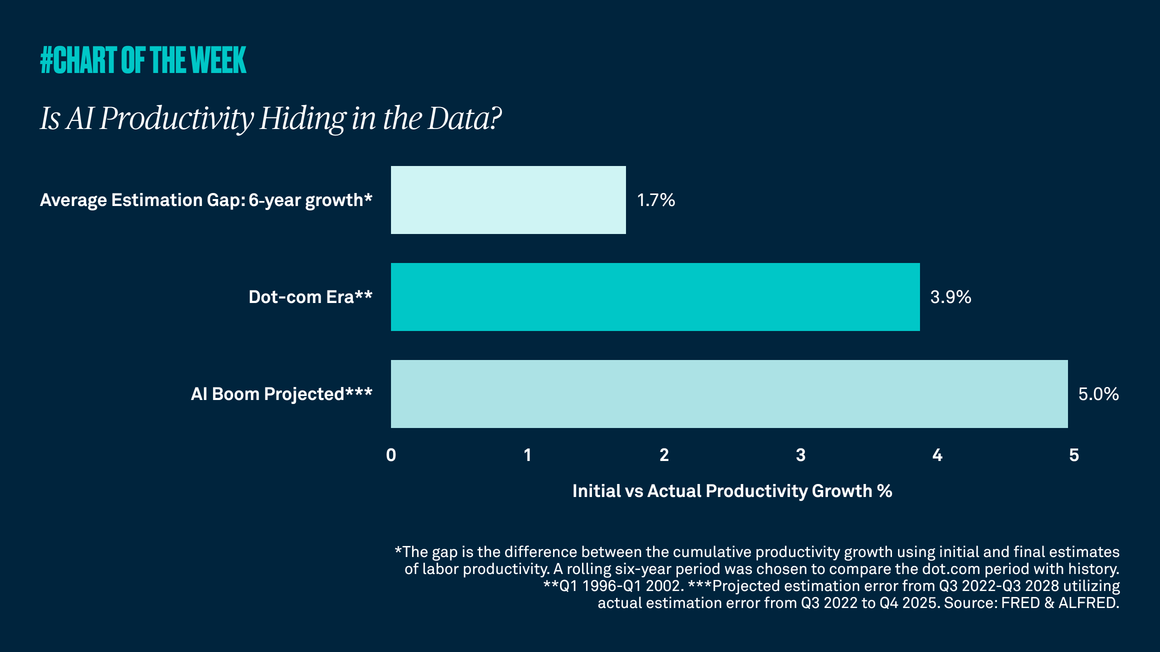
Is AI productivity hiding in the data?
Chart of the Week | Makroökonomisch

Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.

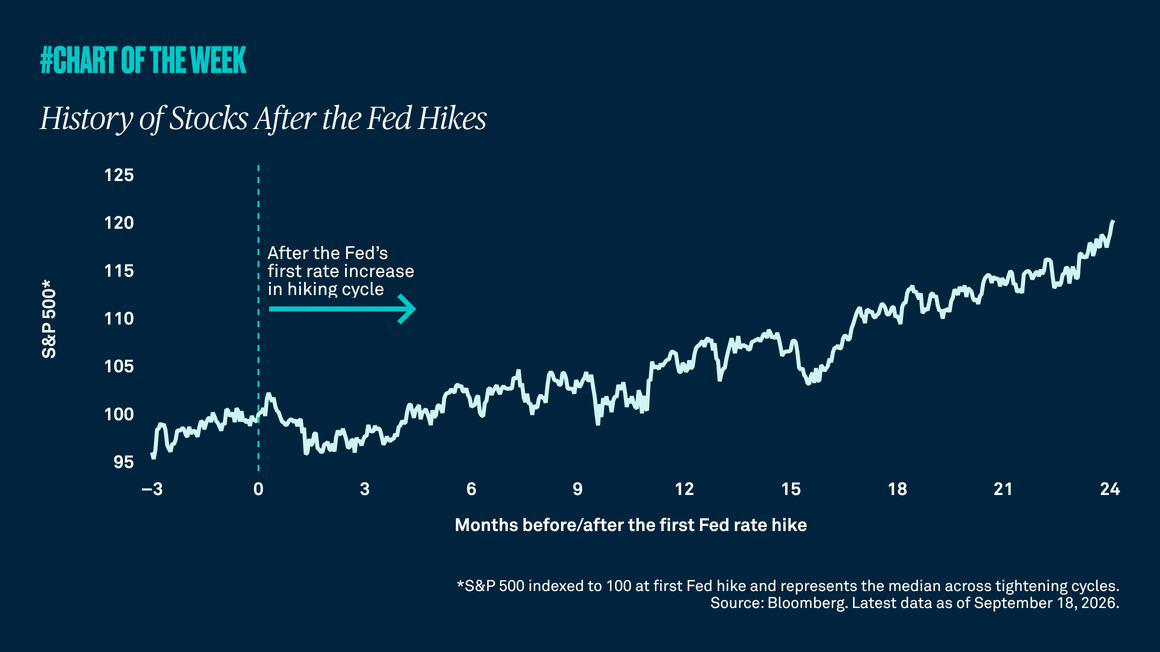
History of stocks after the fed hikes
Chart of the Week | Makroökonomisch

Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.

Inflation is a global problem
Chart of the Week | Makroökonomisch

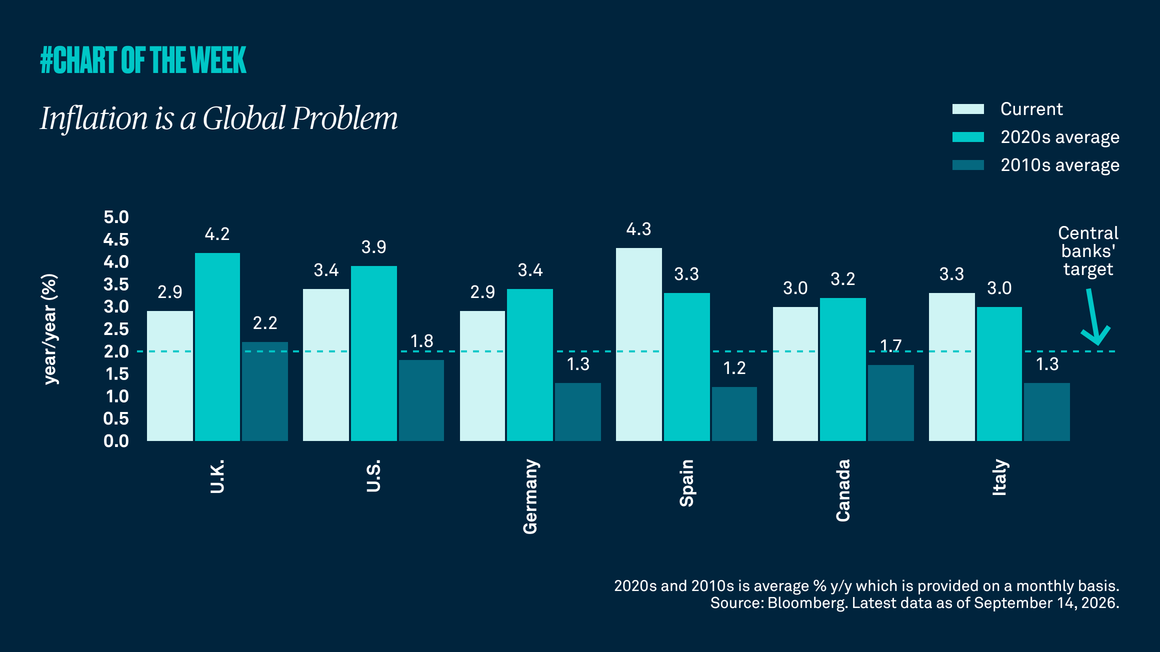
Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.

In a real regime shift?
Chart of the Week | Makroökonomisch

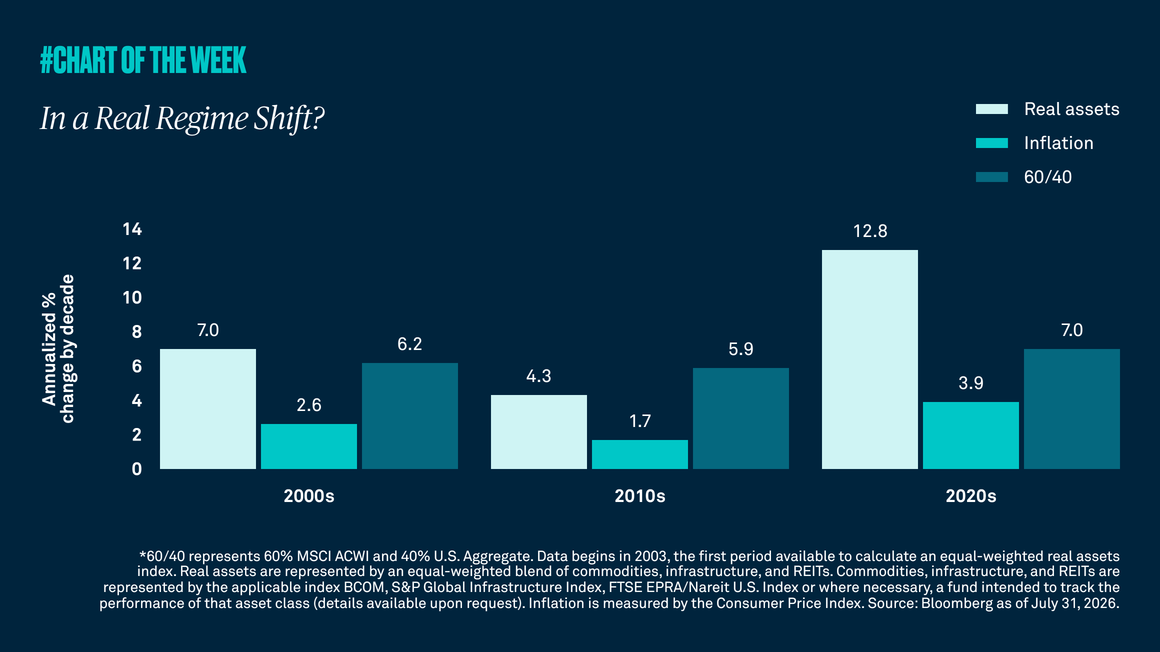
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Gathering data
Disclaimer Not Available

Dies ist eine Marketingkommunikation