Please ensure Javascript is enabled for purposes of website accessibility Impact of Geopolitics over Time?
at
de
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Impact of geopolitics over time?

Impact of geopolitics over time?

Tensions between the U.S./Israel and Iran have recently boiled over into a military conflict, which has given many investors the jitters. However, our research shows that equity market pullbacks resulting from geopolitical events are often short lived with the S&P 500 typically higher in the months following these events.  
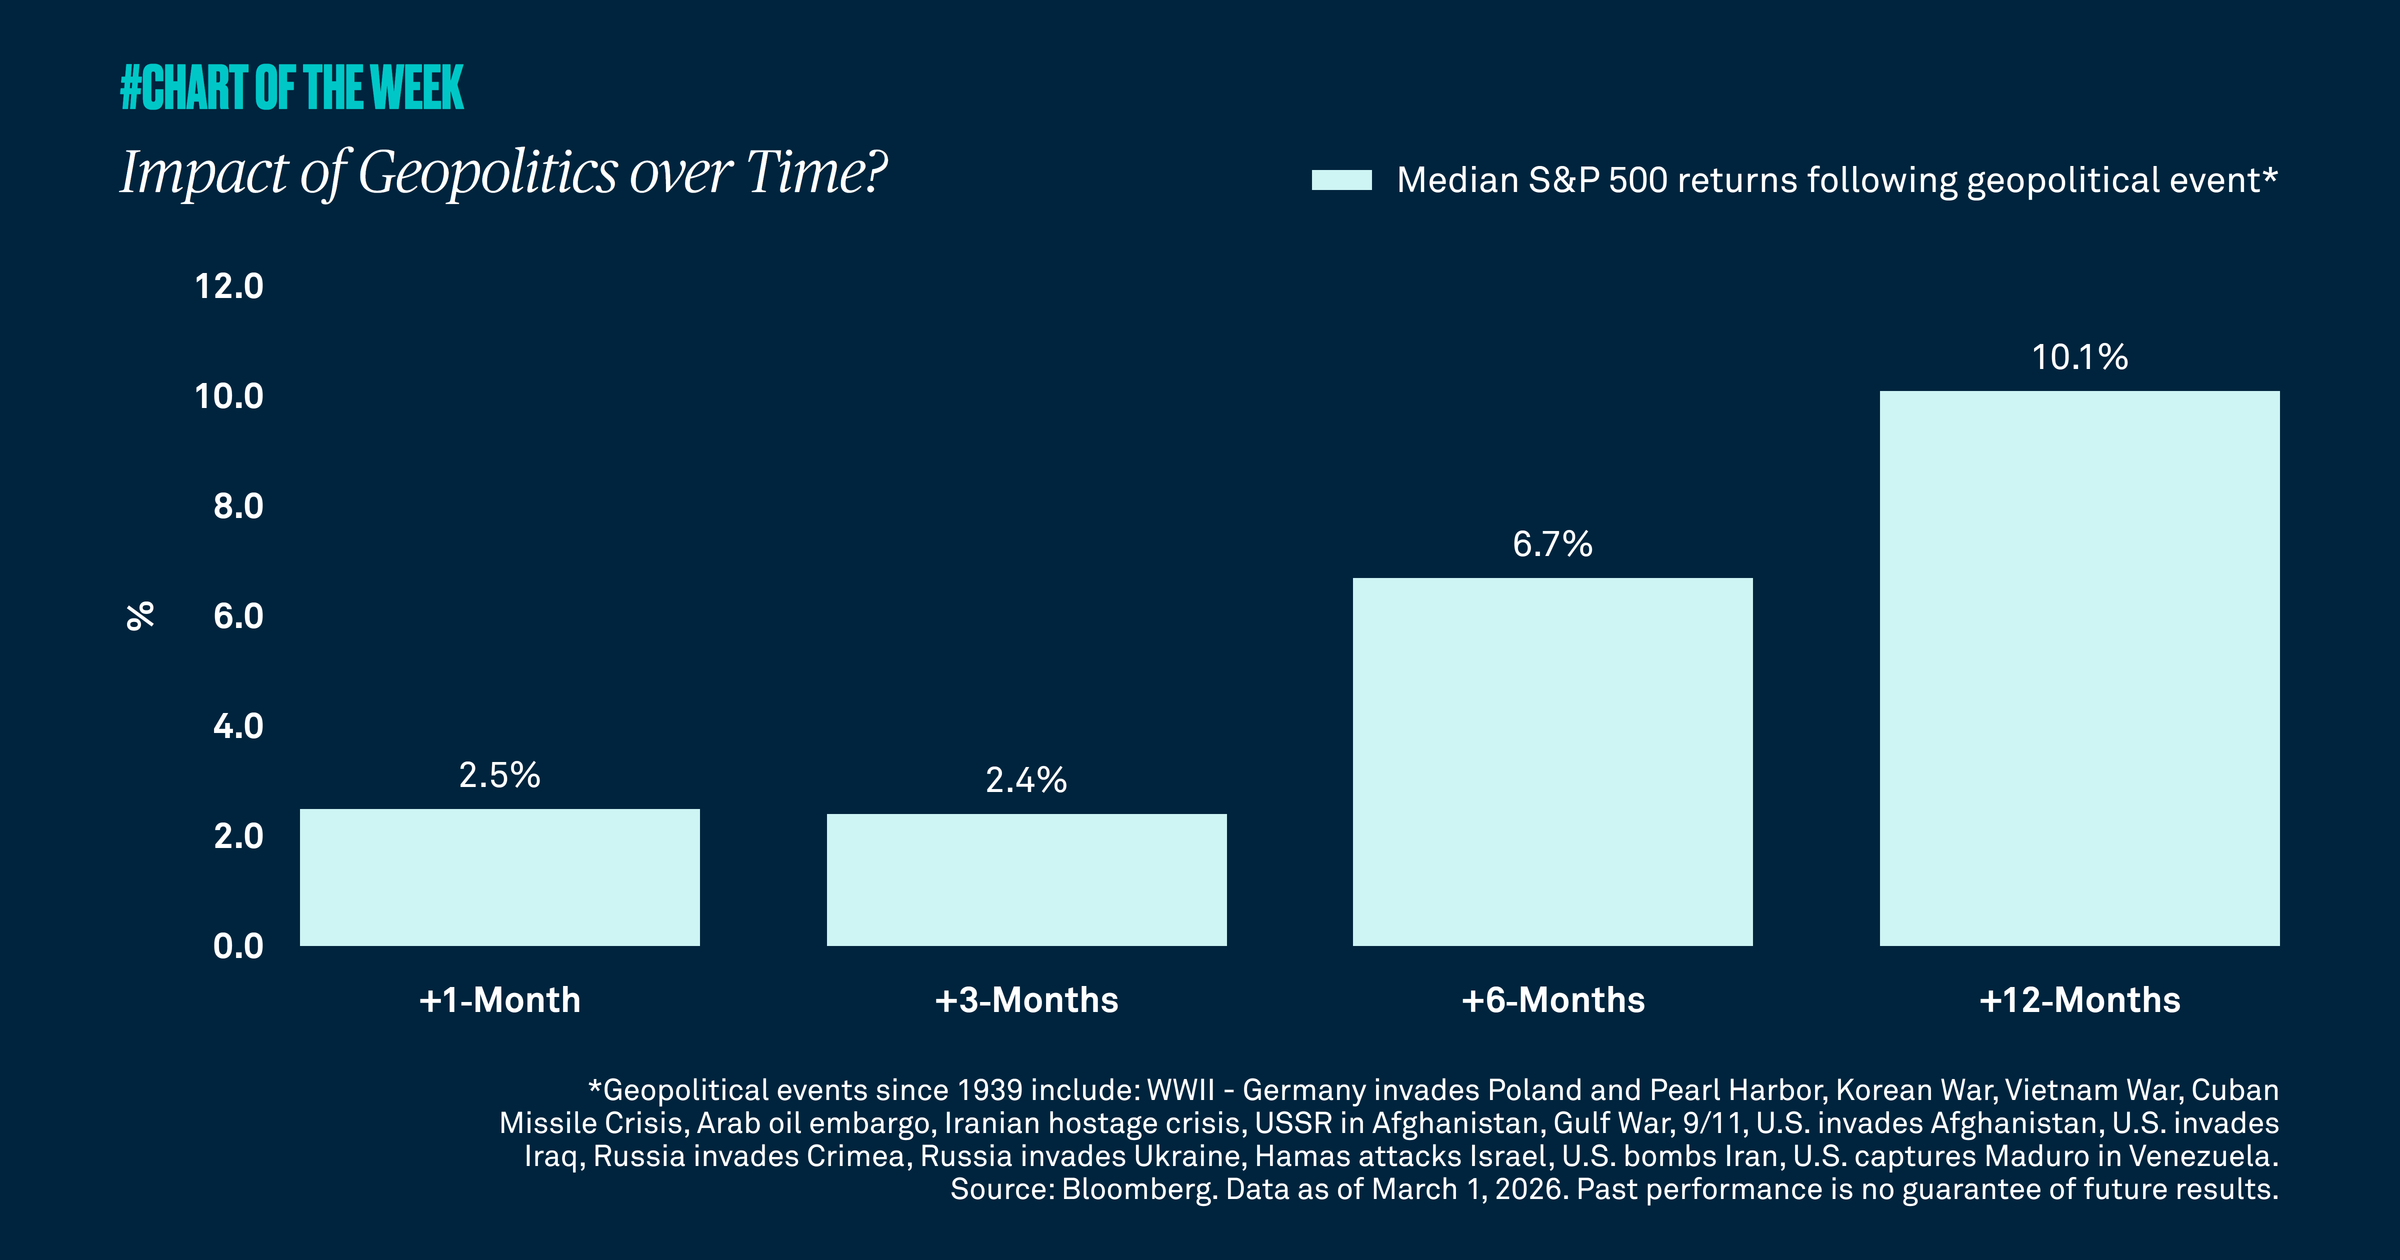

The events in the Middle East involving the U.S., Israel and Iran have led many investors to worry about the near-term implications for financial markets and oil in particular. As largely expected, the biggest impact has been on the price of oil. While it may be hard to know how long this conflict will last, history demonstrates that as long as there is no sustained energy supply shock, S&P 500 returns are higher one, three, six and 12 months after a geopolitical conflict according to data since 1939.

Over time, it’s equity market fundamentals — earnings and interest rates ― that drive markets. Given that the fundamentals remain supportive, we reiterate our constructive outlook on global growth and markets in 2026, reminding investors that a globally diversified portfolio will help navigate near-term uncertainty and preserve wealth. 
VERWANDTE THEMEN
Inflation is a global problem
Chart of the Week | Makroökonomisch

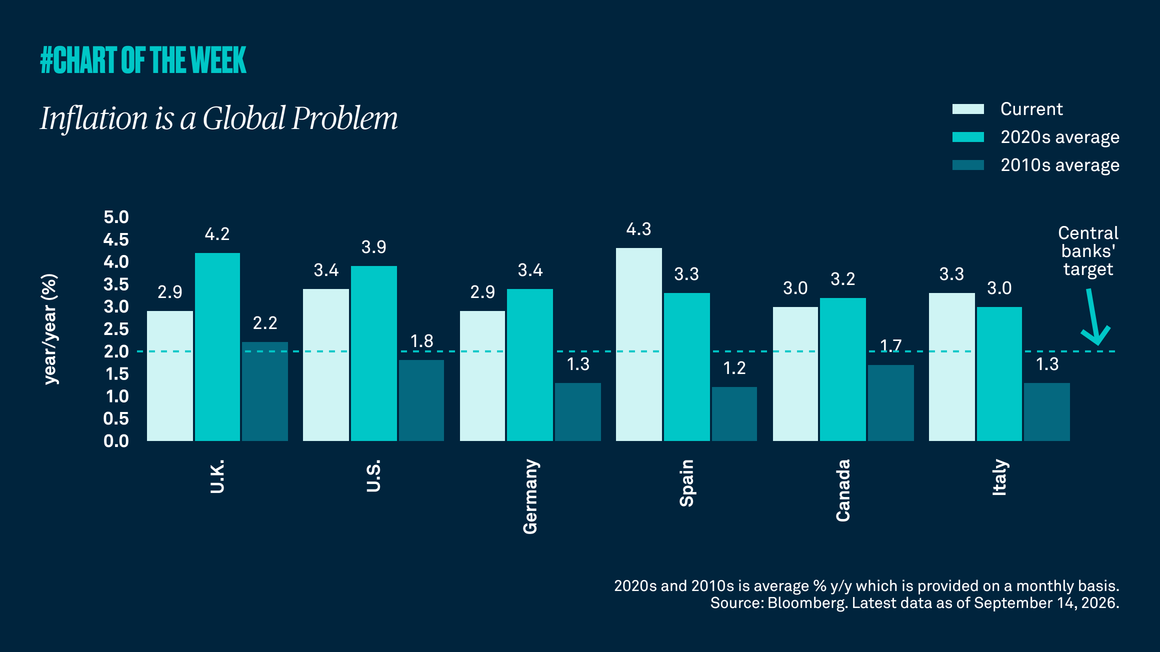
Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.

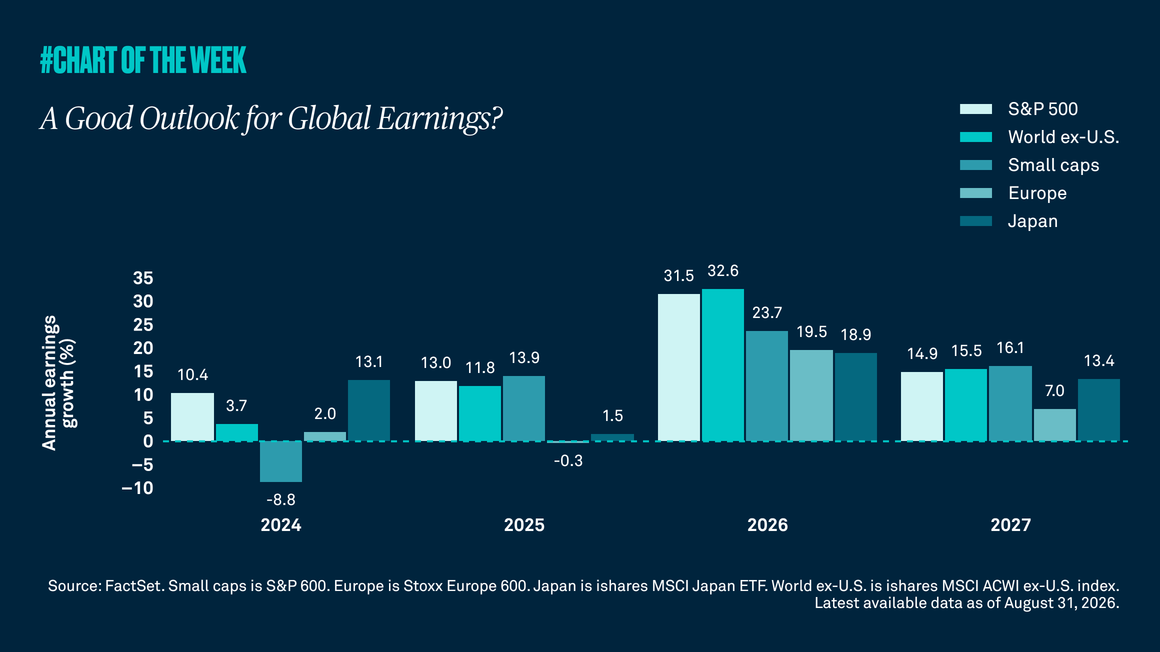
A good outlook for global earnings
Chart of the Week | Makroökonomisch

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

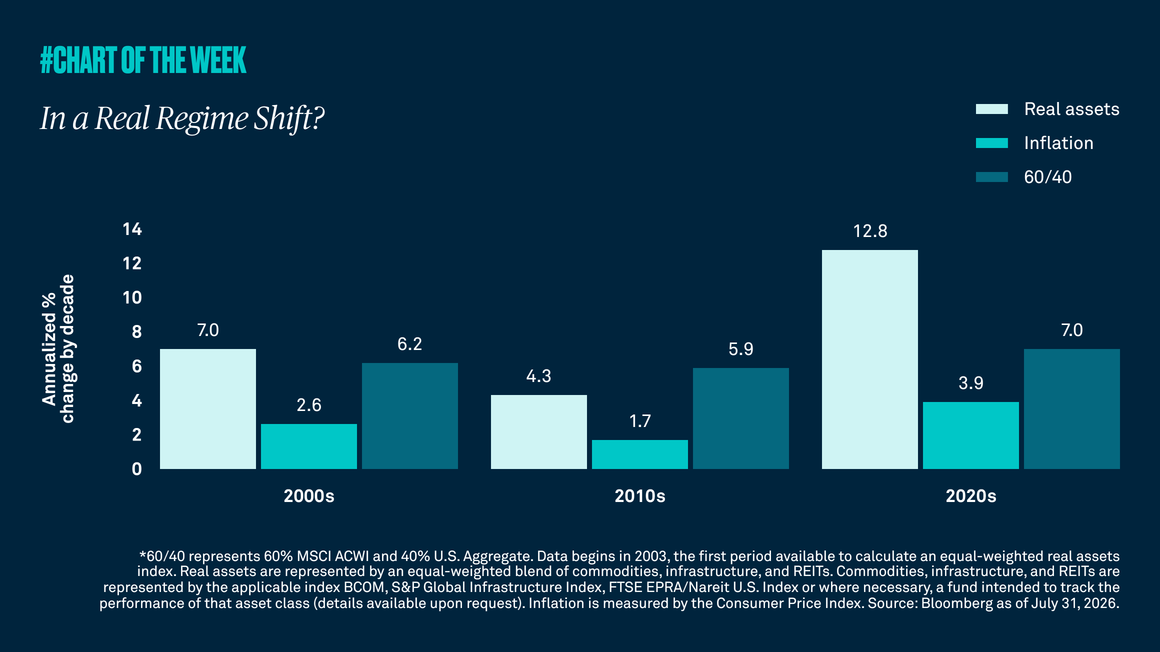
In a real regime shift?
Chart of the Week | Makroökonomisch

Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

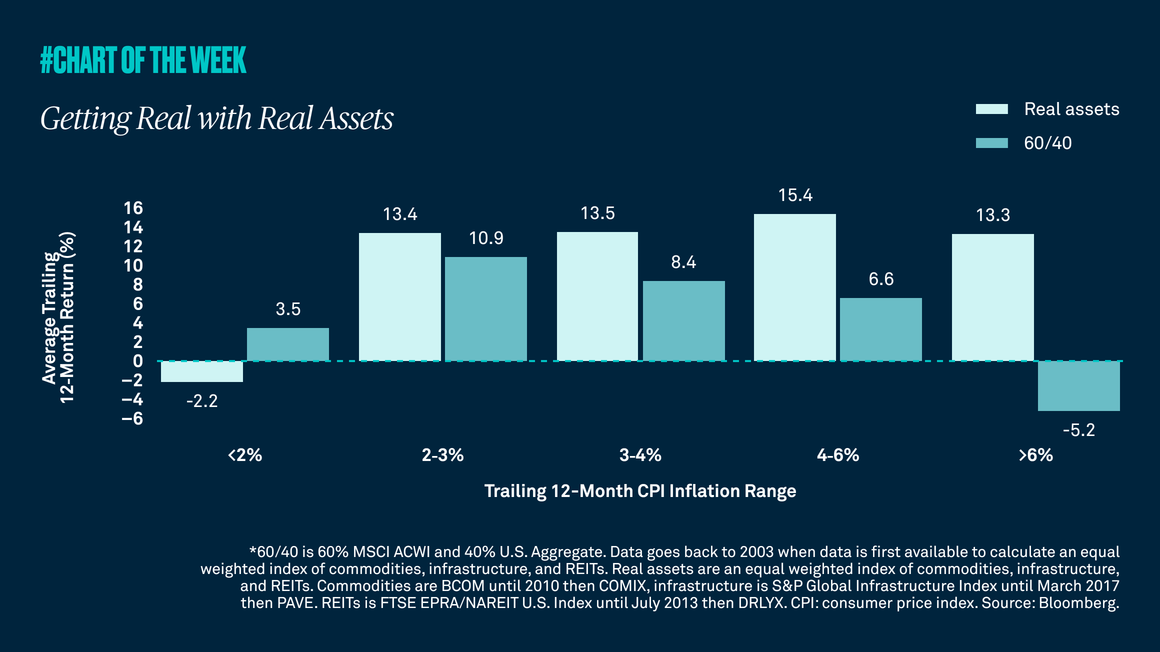
Getting real with real assets
Chart of the Week | Makroökonomisch

Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Gathering data
Disclaimer Not Available

Dies ist eine Marketingkommunikation