Please ensure Javascript is enabled for purposes of website accessibility Bubble or Is This Market Different?
uk
en
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Bubble or is this market different?

Bubble or is this market different?

The S&P 500 is up 14% year to date after gaining more than 20% annually over the past couple of years. Valuations are certainly elevated, but we believe the market is in a new world where higher multiples are normal rather than stretched.

The S&P 500 is up 14% year to date after gaining more than 20% annually over the past couple of years. Some investors are speculating that we are amidst another tech bubble because technology companies have been leading the market higher. However, we believe the market is in a new world where higher multiples are normal rather than a sign of stretched valuations.

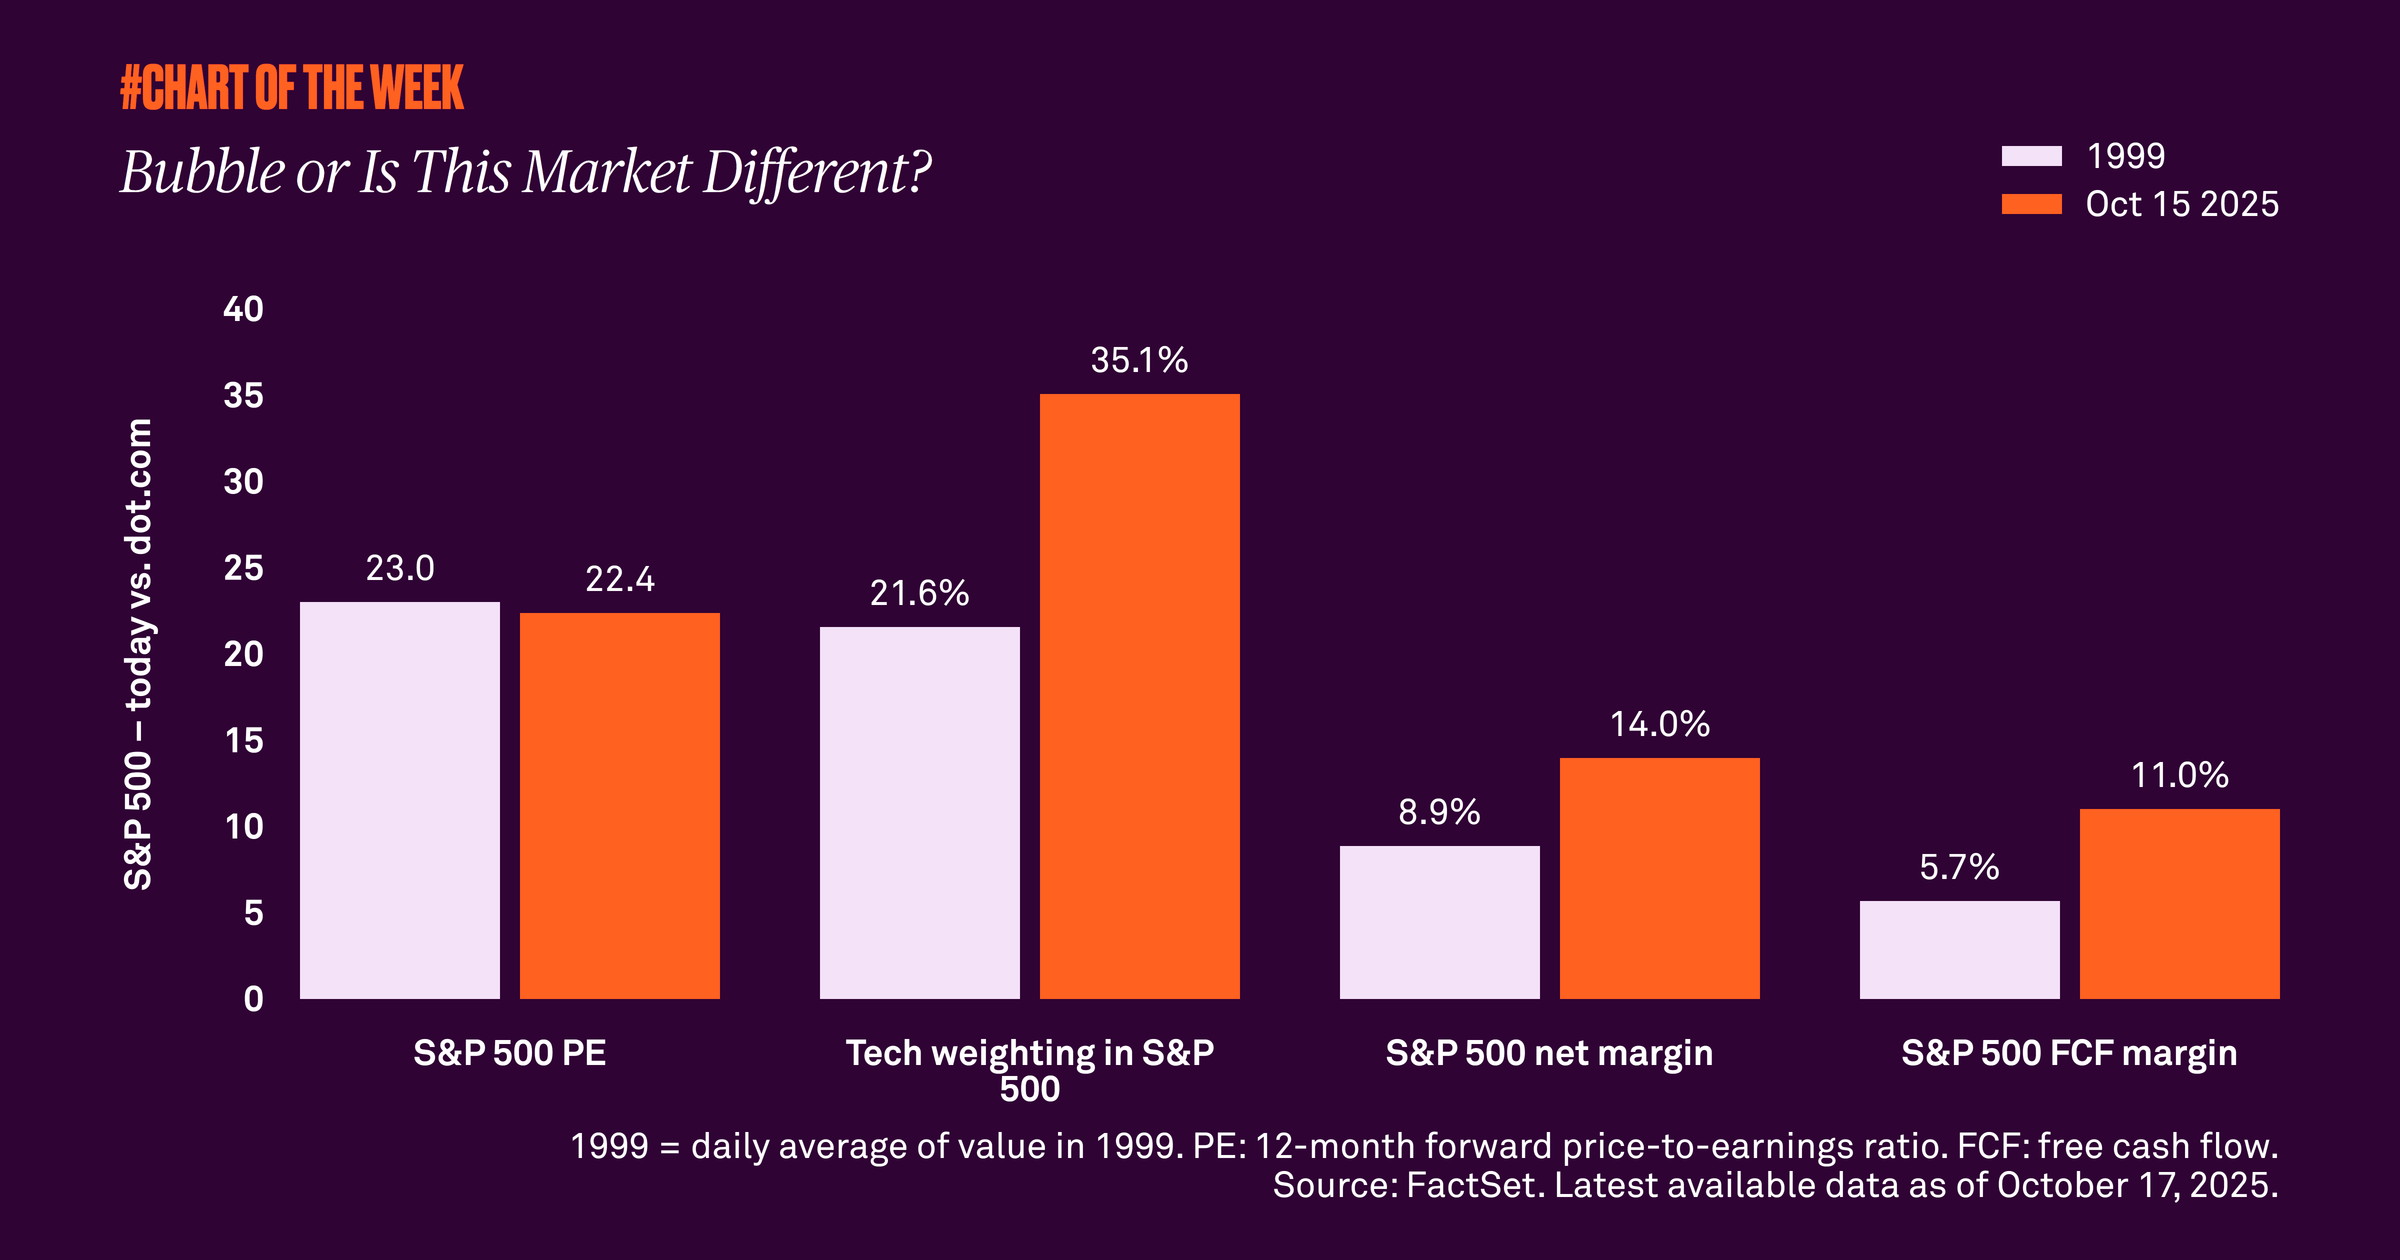
For some context, the S&P 500’s 12-month future price-to-earnings (PE) ratio is currently 22.4x, notably greater than the 16.8x average since 1996. While the index appears expensive relative to history, we believe this higher-multiple environment is justified. A key reason is the improved profitability of the market; net margins are 1.6x higher at 14% compared to the dot.com era. Similarly, free cash flow margins are 1.9x higher at 11%. In addition, the weight of the technology sector, which has the highest PE, has increased 1.6x since the dot.com era to 35% of the index. This naturally increases the PE of the index.

The changing market structure with the increased size of tech and the broader index’s higher profitability have led to higher PEs compared to long-term averages. In our view, the disconnect between current valuations and historical averages reflects a different type of market – not an overvalued one.

So, while we don’t believe the market is in a bubble, we believe that investors’ skepticism is healthy for keeping bull markets intact. Current valuations could consolidate from elevated levels, but we remain constructive on the forward outlook given improving earnings.
RELATED CONTENT
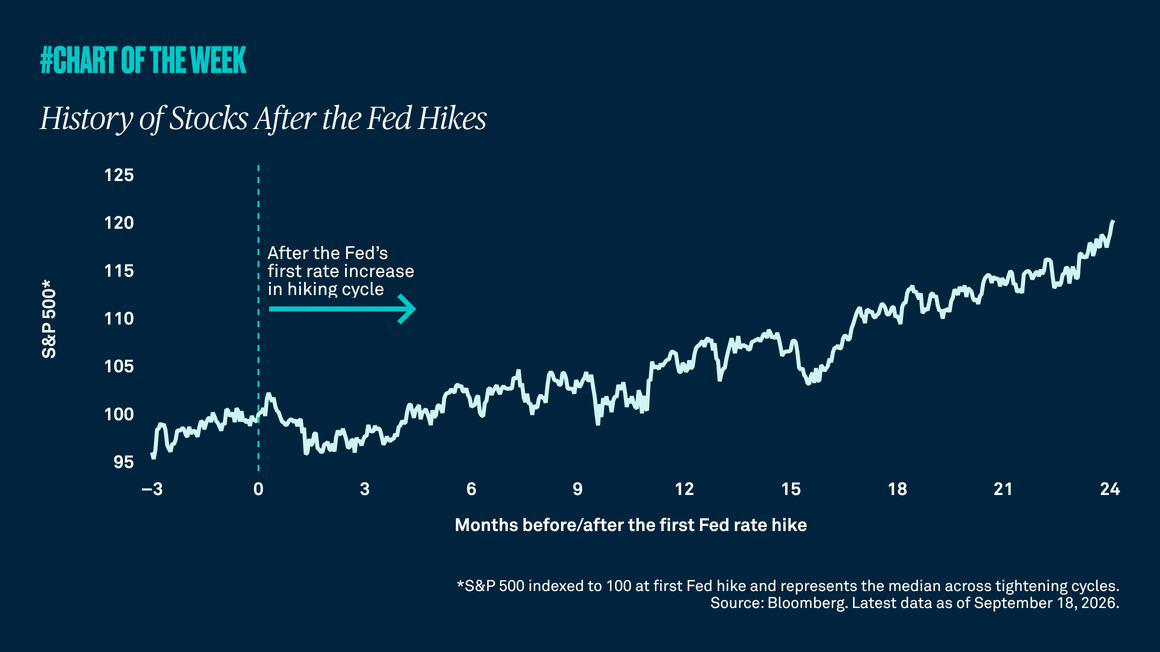
History of stocks after the fed hikes
Chart of the Week | Macroeconomic

Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.

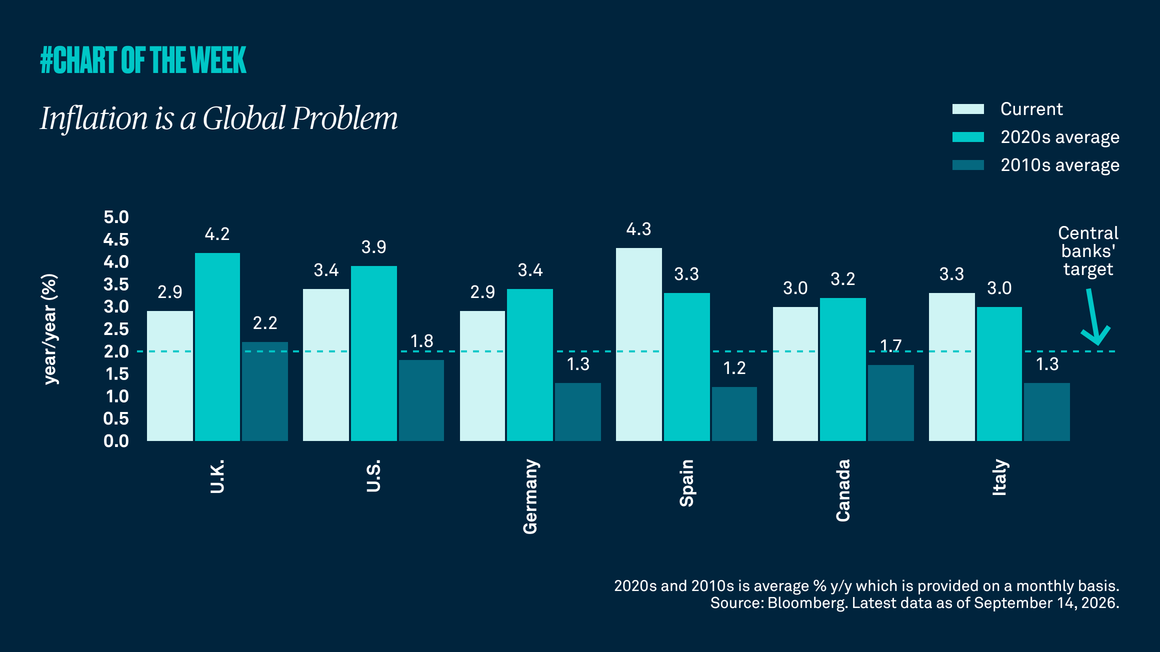
Inflation is a global problem
Chart of the Week | Macroeconomic

Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.

A good outlook for global earnings
Chart of the Week | Macroeconomic

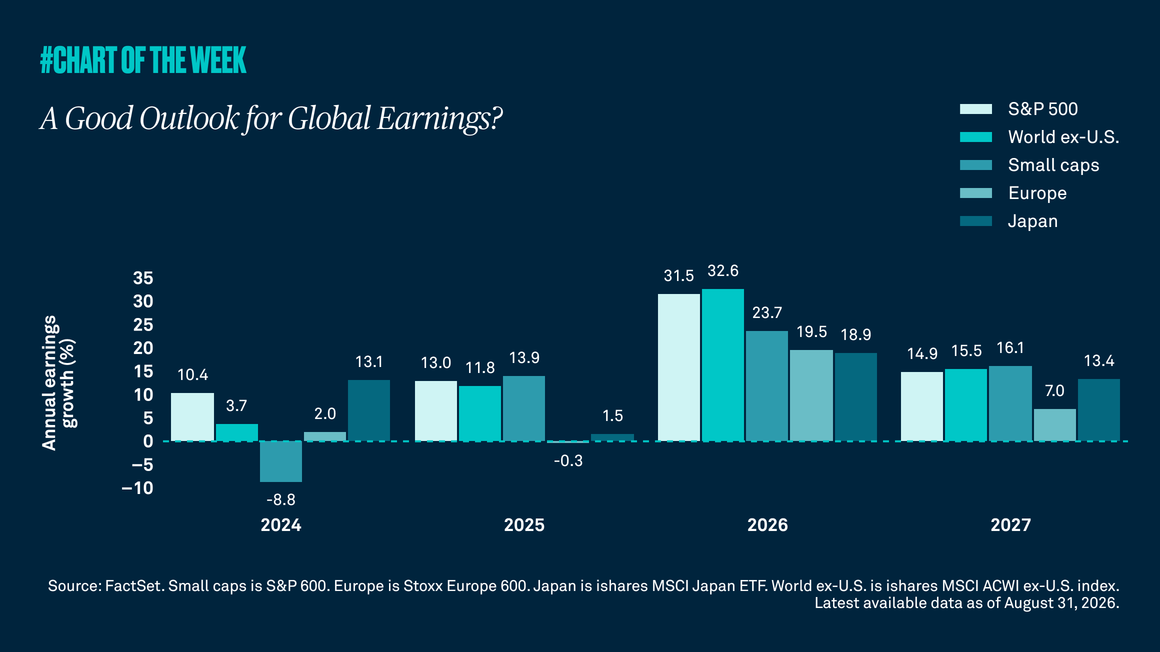
Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

In a real regime shift?
Chart of the Week | Macroeconomic

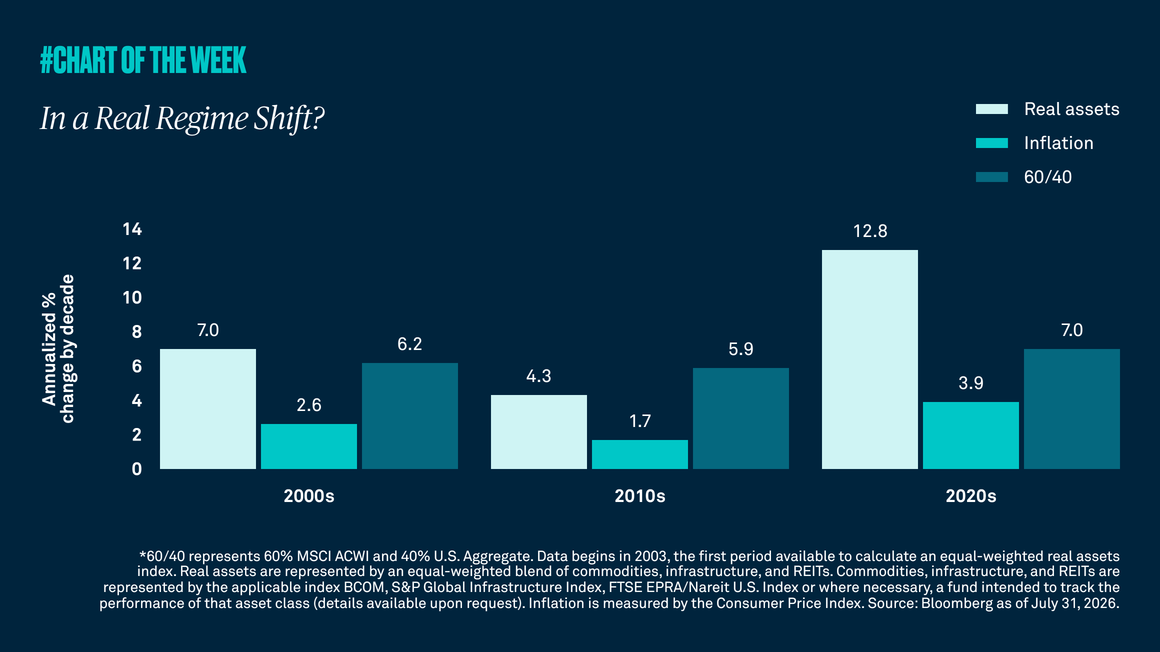
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Gathering data
Disclaimer Not Available

This is a marketing communication