Please ensure Javascript is enabled for purposes of website accessibility Earnings Breadth Still Improving
sg
en
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Earnings breadth still improving

Earnings breadth still improving

Rising earnings estimates continue to support equities despite geopolitical and macroeconomic uncertainty. With profit growth broadening across S&P 500 industries, resilient corporate earnings underpin our constructive outlook for the stock market.
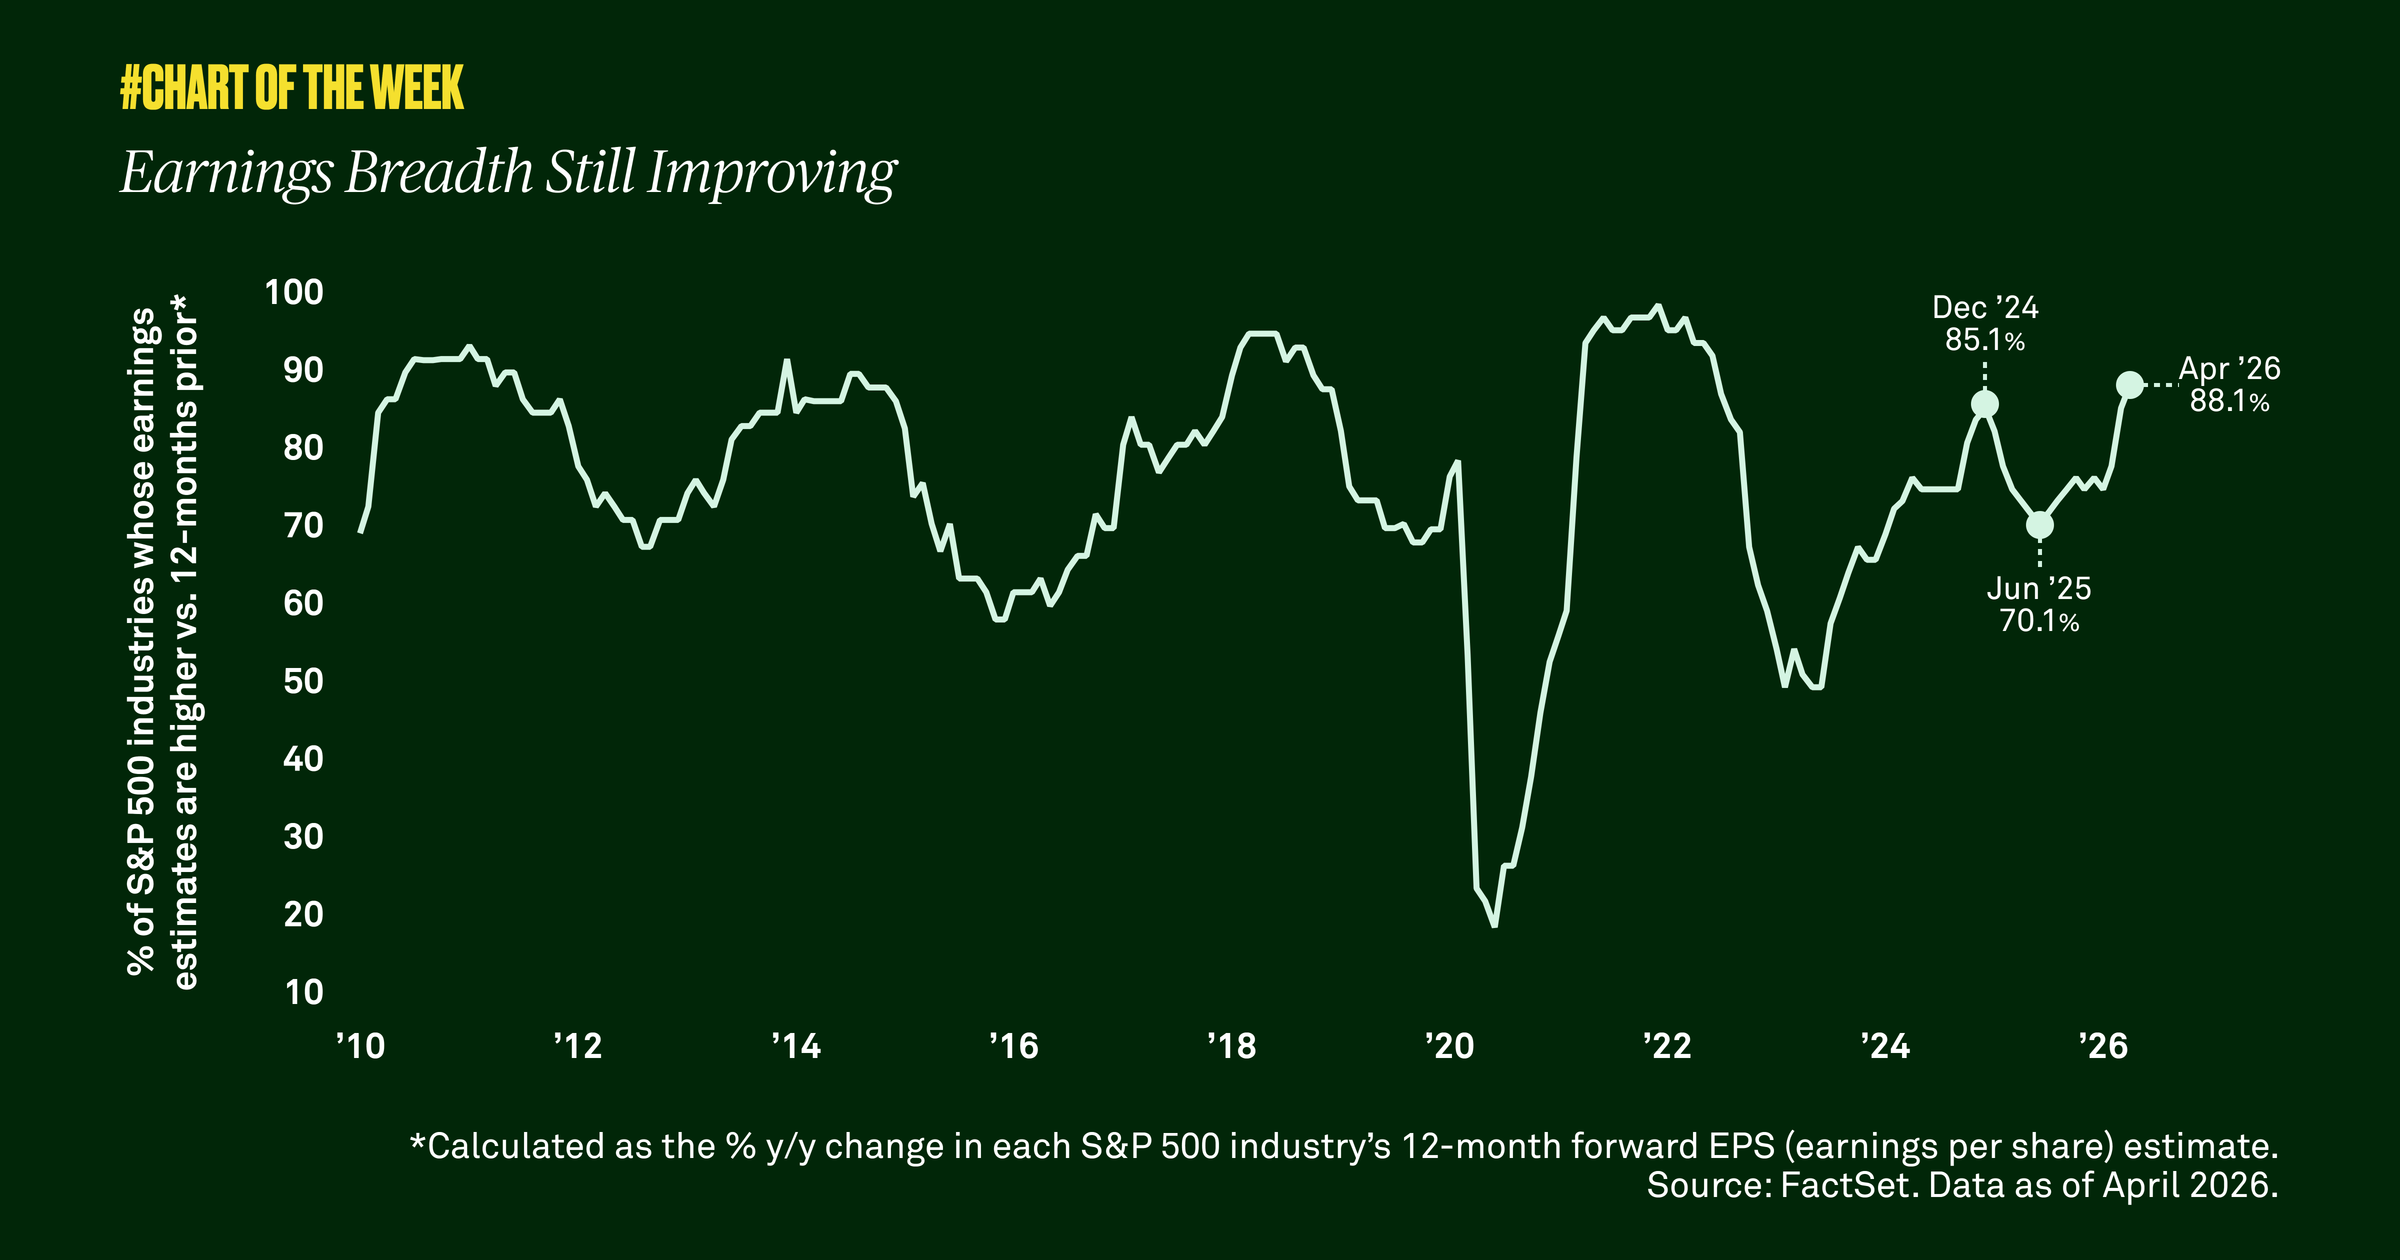

Expectations for future earnings growth remain a key driver of equity market performance. That dynamic is especially visible today: rising earnings estimates have supported equities despite persistent concerns over the war in the Middle East and its potential effects on energy prices, inflation and global growth. Consensus forecasts now call for S&P 500 earnings to grow 20.6% in 2026, up from 14.3% before the conflict began — a meaningful upward revision that highlights companies’ profit resilience.  

Earnings strength is becoming broader, with more industries expected to post stronger results. Notably, 88% of S&P 500 companies now have earnings estimates higher than their levels 12 months ago — the highest share in three years. That widening earnings breadth supports a more durable market backdrop.

In fact, earnings and interest rates are the main drivers of equity returns. With interest rates on hold, it’s corporate profitability across a wide range of industries that continues to support our constructive outlook for equities.
RELATED CONTENT
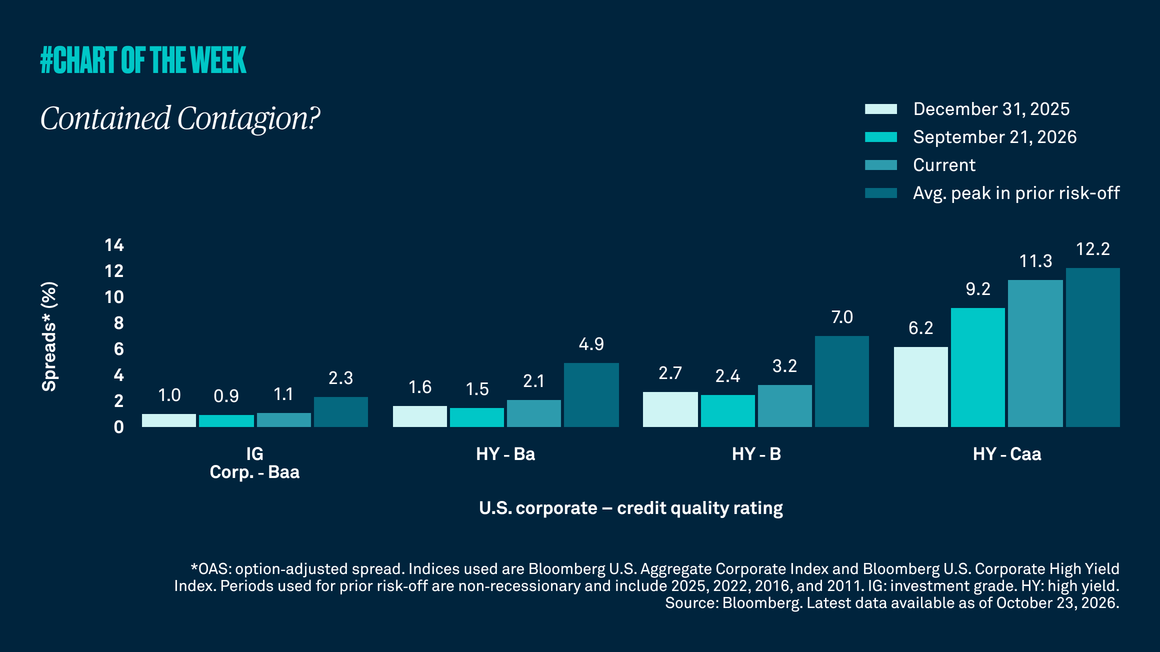
Contained contagion?
Chart of the Week | Macroeconomic

U.S. high yield credit spreads have widened year to date, reflecting greater investor caution about perceived default risk. The move also raises concerns about possible credit contagion. However, because spread widening has been concentrated in the lowest-quality issuers rather than higher-quality issuers, we don’t anticipate broader market stress.

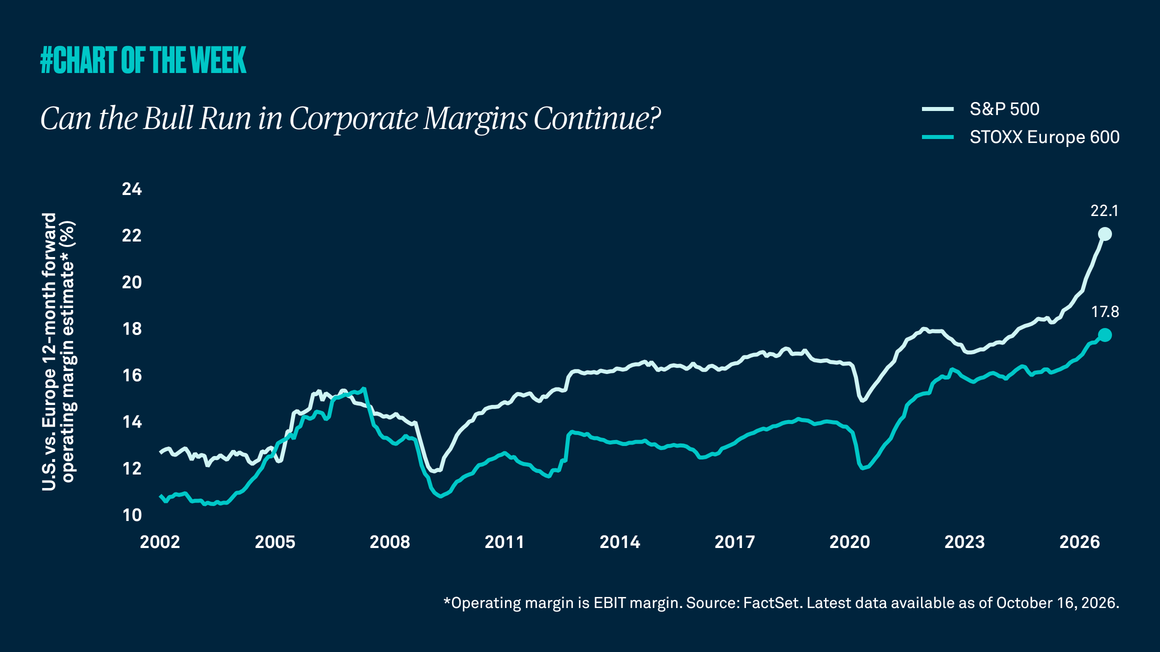
Can the bull run in corporate margins continue?
Chart of the Week | Macroeconomic

Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?

Higher yields, but lower sensitivity
Chart of the Week | Macroeconomic

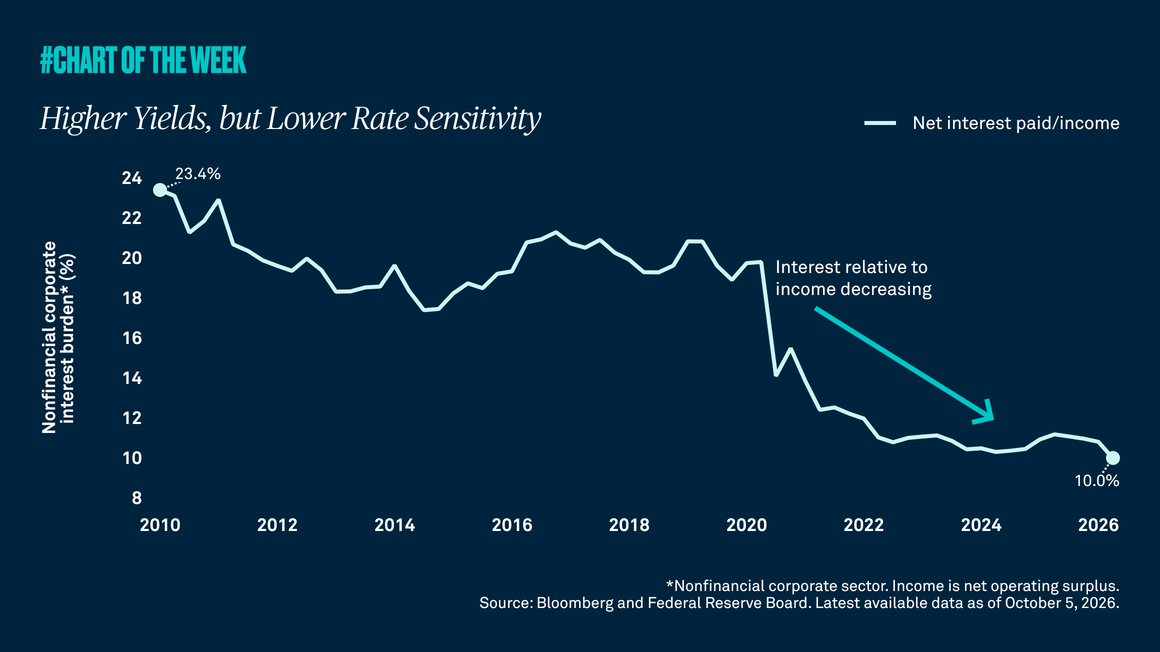
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.

Is AI productivity hiding in the data?
Chart of the Week | Macroeconomic

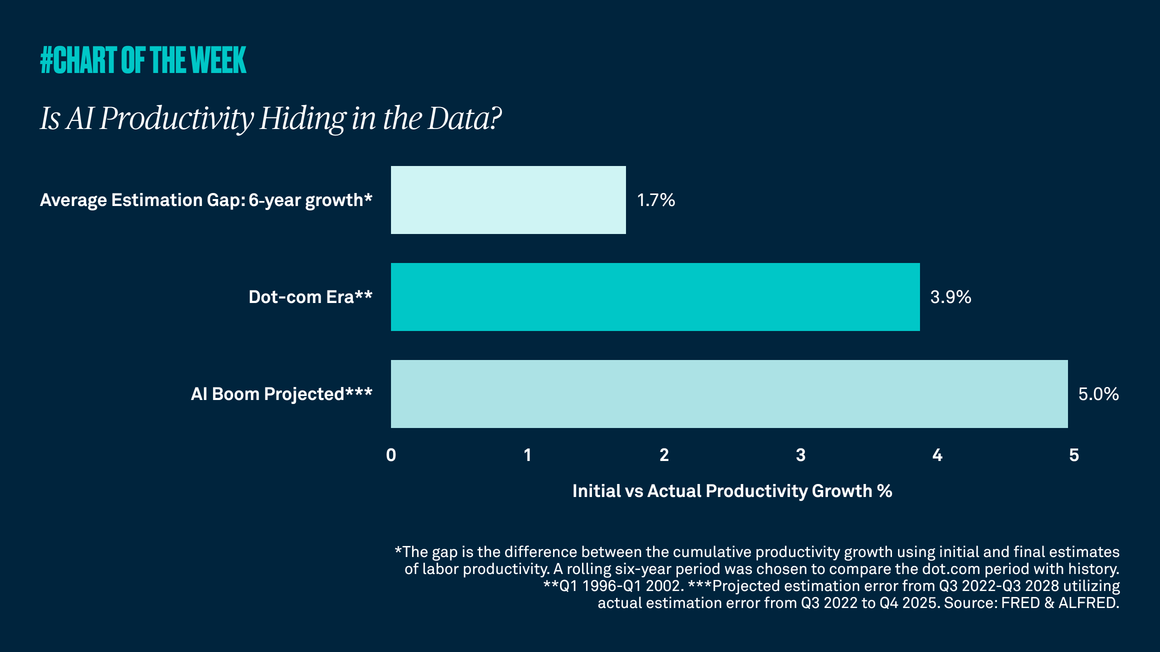
Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.

Gathering data
Disclaimer Not Available

CONTACT US  |  +65 6432 0222