Please ensure Javascript is enabled for purposes of website accessibility Fed Friction?
se
en
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Fed friction?

Fed friction?

Markets are navigating tensions between a Fed that offers less guidance and an inflation backdrop that remains sticky. Added uncertainty from Middle East tensions and energy-price swings is further shaping sentiment, with recent moves in Treasury yields suggesting the market wants the Fed to hike. However, with yield volatility expected to linger in the near term, we see today’s elevated Treasury yields as an especially compelling opportunity in fixed income.
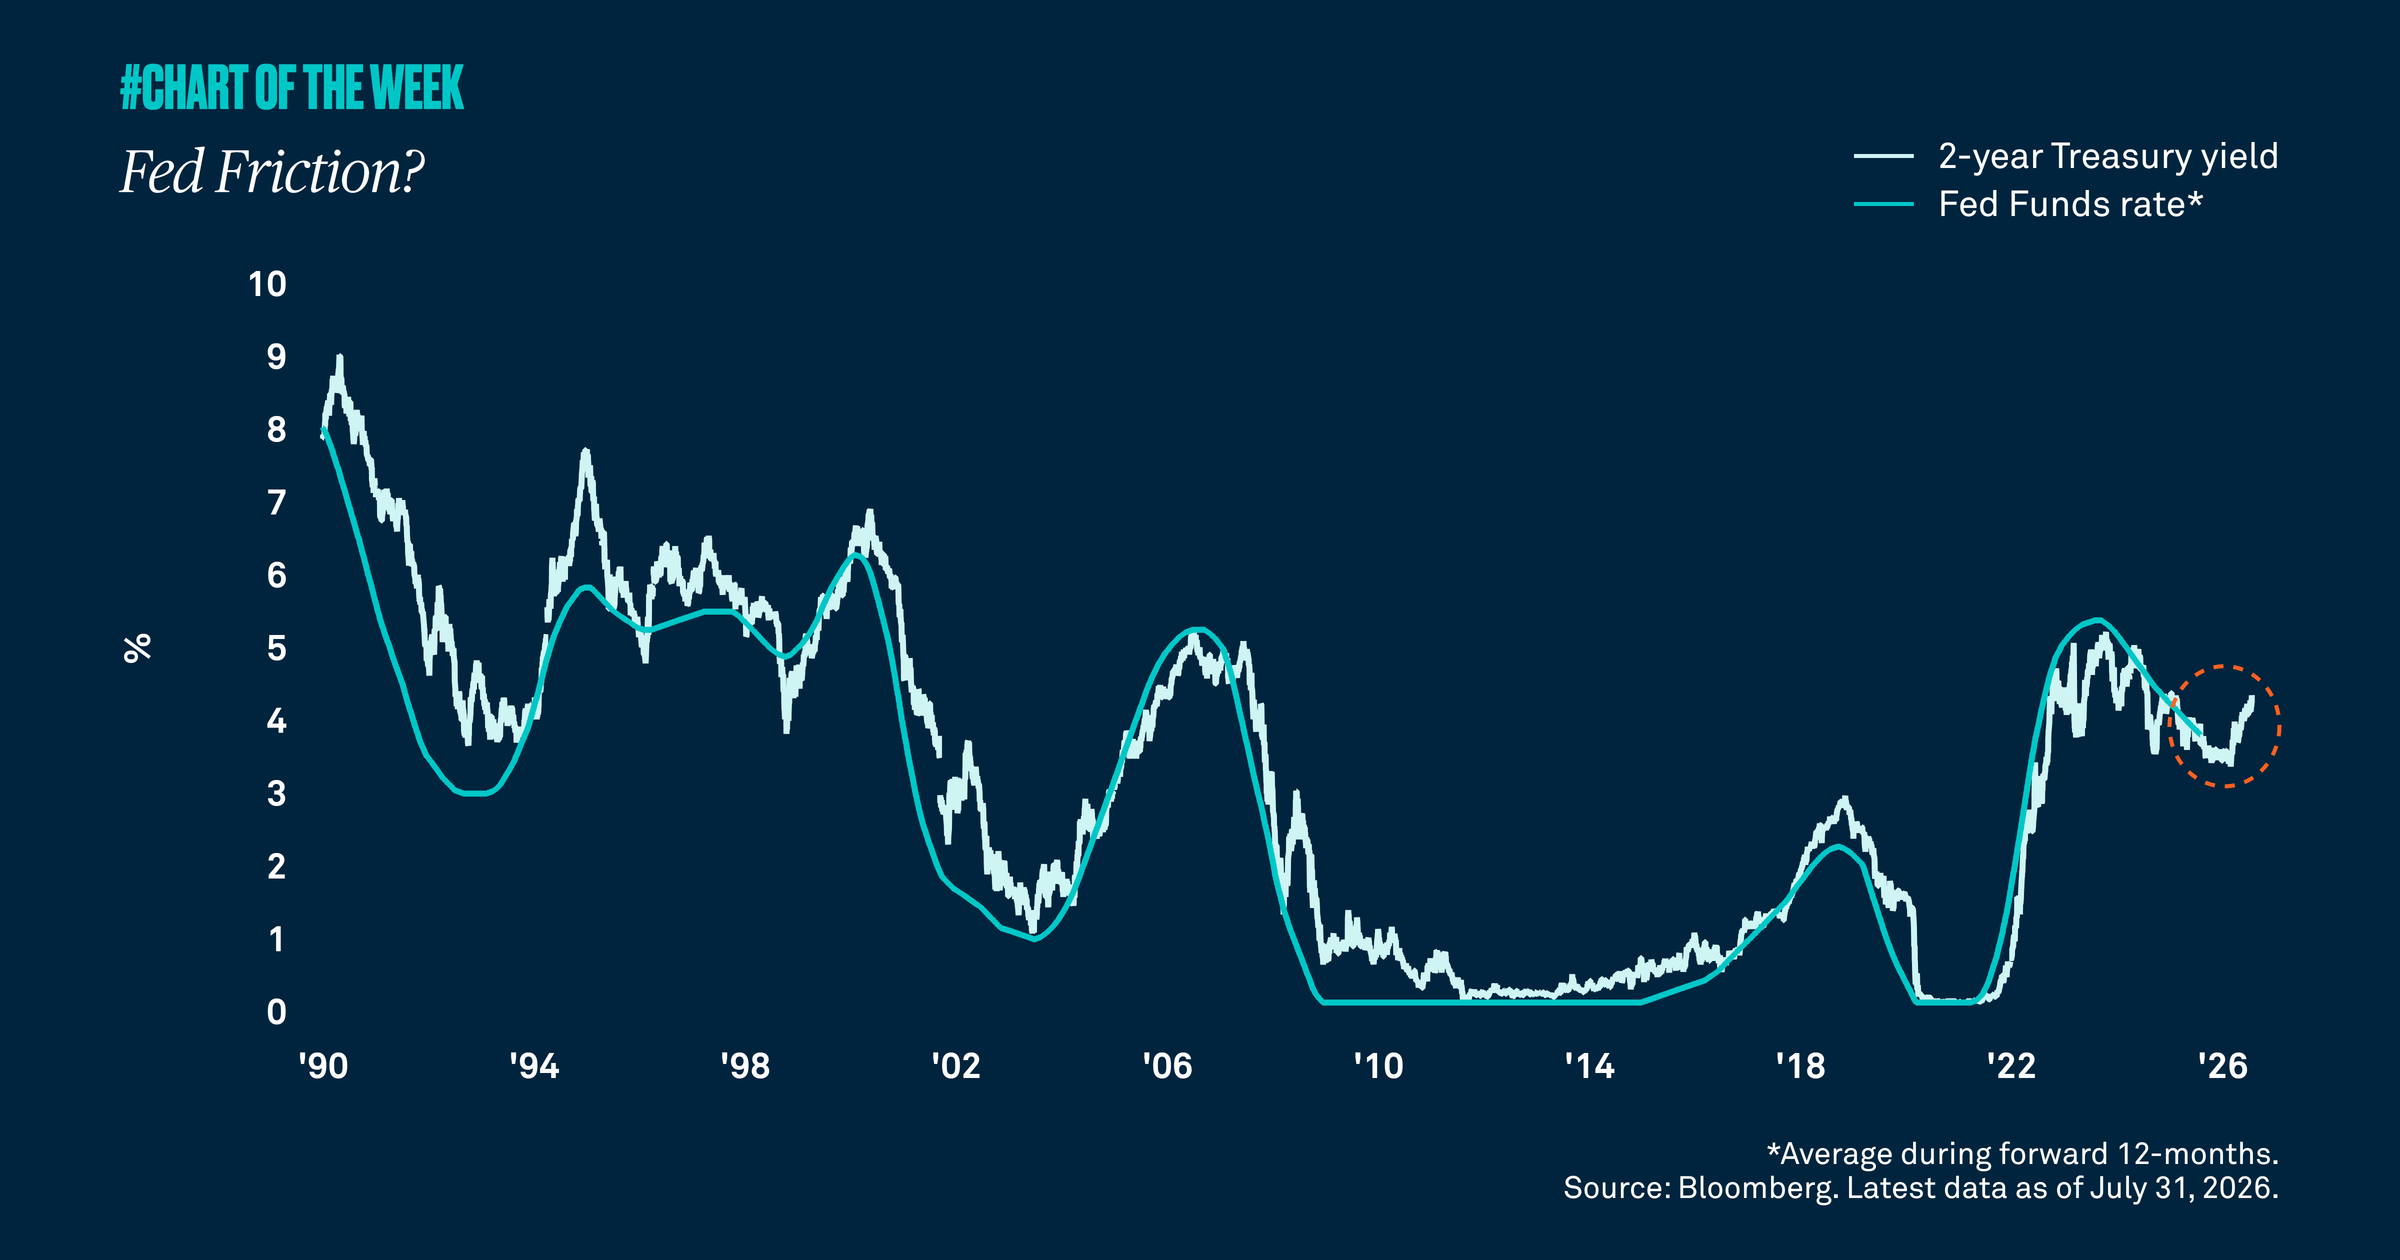

Renewed tensions in the Middle East, volatile energy prices, and still-resilient U.S. growth would be enough to unsettle fixed income markets. Last week only added to that unease: the Federal Open Market Committee left the fed funds rate unchanged, and Chair Kevin Warsh followed through on the less transparent approach to forward guidance he had signaled, deepening uncertainty around the path of policy ahead.

The market continues to expect the central bank to hike by year end, although near-term expectations came down slightly after the meeting. Futures still imply meaningful odds of additional tightening by year end, and based on history, recent moves in the two-year Treasury yield suggest that investors see Fed action as plausible.

Still, the Fed has made clear that its next move will hinge on inflation, and June core inflation data were somewhat softer, indicating some progress even if price levels remain above target.

This week began with renewed U.S.-Iran talks, which helped push yields lower as oil prices retreated and some energy-driven inflation fears eased. But with bond volatility still high and several Treasury yields recently touching year-to-date highs, we continue to view current yield levels as attractive entry points. We expect the Fed to stay patient and data-dependent for longer than investors seem to currently anticipate, which in our view, underscores the opportunity in today’s yields.
RELATED CONTENT
Play the long game
Chart of the Week | Macroeconomic

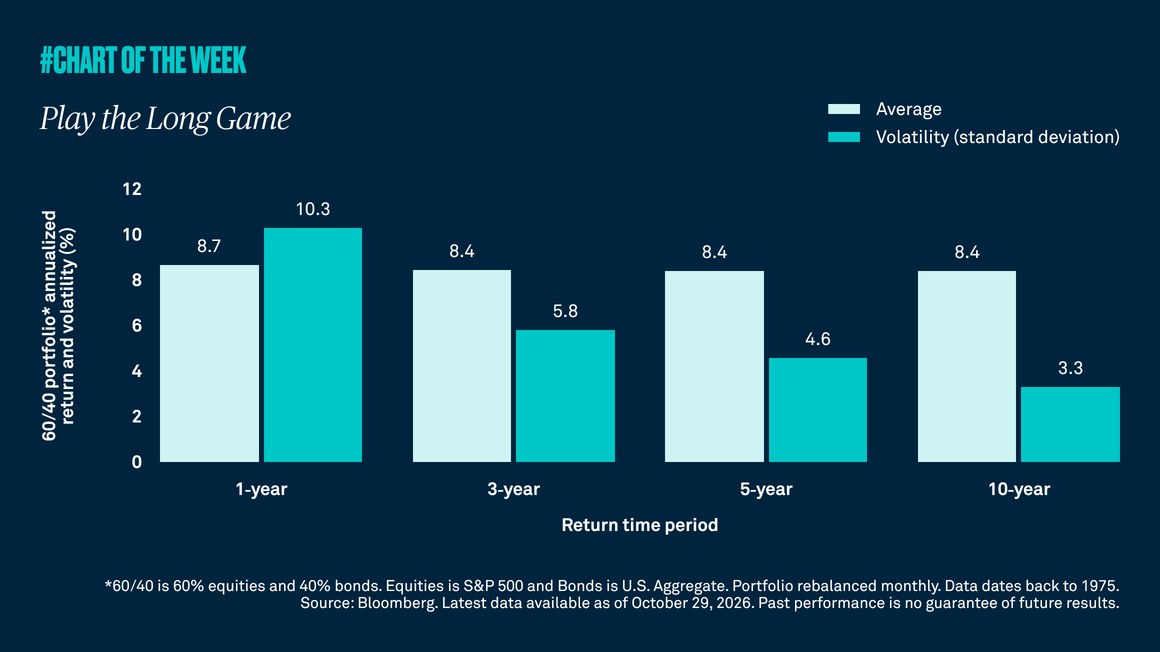
When it comes to investing, time matters. While headlines and short-term perspectives can lead investors to try and time the market, investors have historically been rewarded by playing the long game. Rather than overreacting to market noise, investing over longer time periods can help smooth the ride without sacrificing returns. The lesson: stay diversified and invested for the long term.

Contained contagion?
Chart of the Week | Macroeconomic

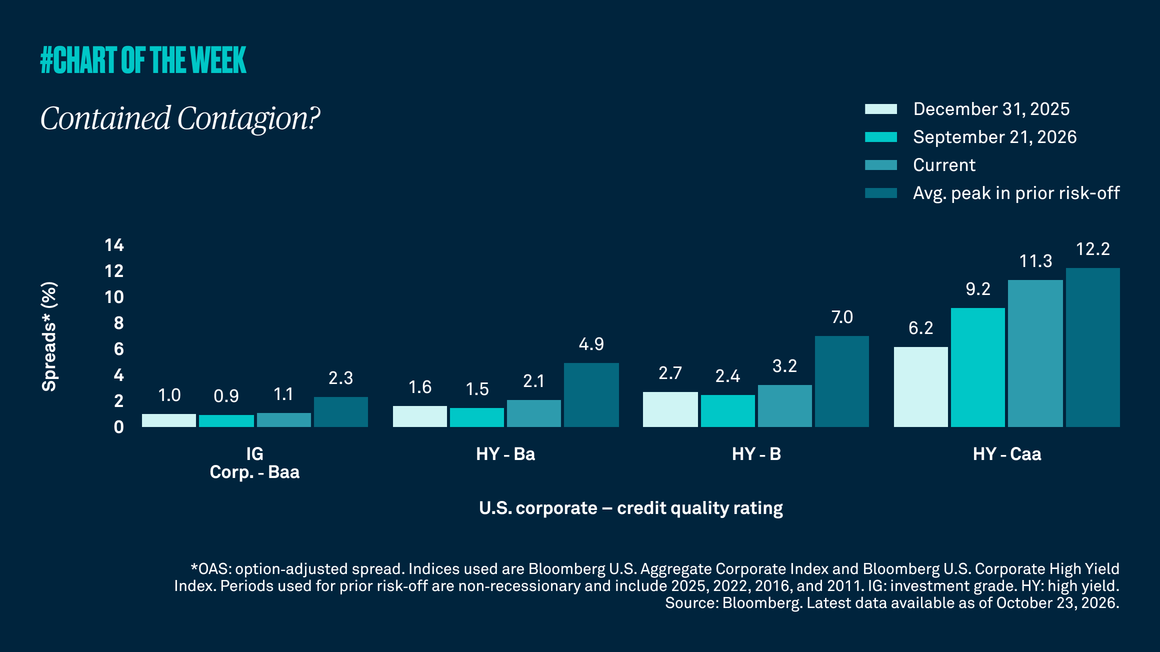
U.S. high yield credit spreads have widened year to date, reflecting greater investor caution about perceived default risk. The move also raises concerns about possible credit contagion. However, because spread widening has been concentrated in the lowest-quality issuers rather than higher-quality issuers, we don’t anticipate broader market stress.

Can the bull run in corporate margins continue?
Chart of the Week | Macroeconomic

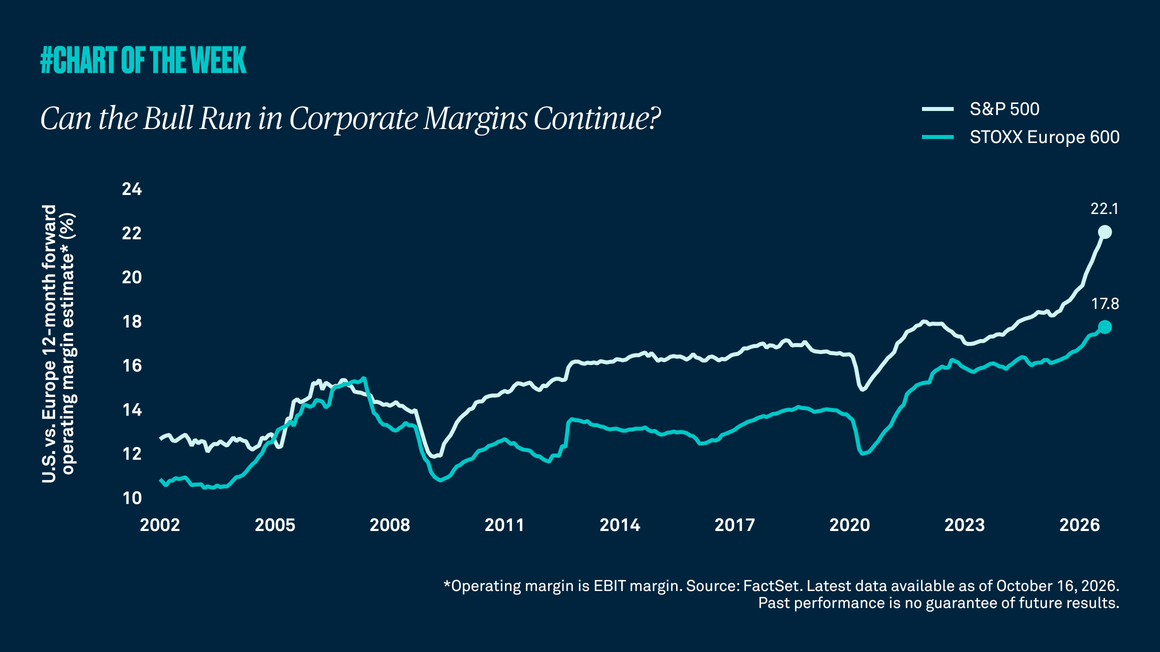
Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?

Higher yields, but lower sensitivity
Chart of the Week | Macroeconomic

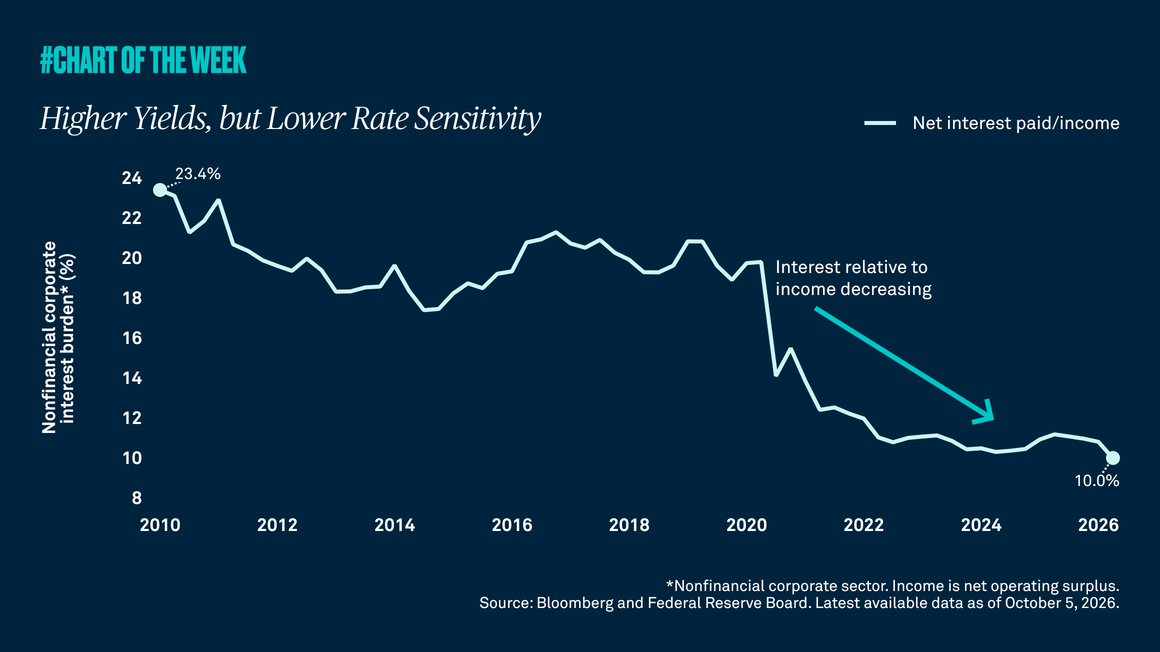
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.

Gathering data
Disclaimer Not Available

This is a marketing communication