Please ensure Javascript is enabled for purposes of website accessibility Capex as a Catalyst
se
en
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Capex as a catalyst

Capex as a catalyst

Improved business confidence and recent tax legislation are compelling corporations to reinvest their cash flows in their businesses. We believe this is a positive signal for economic growth. 
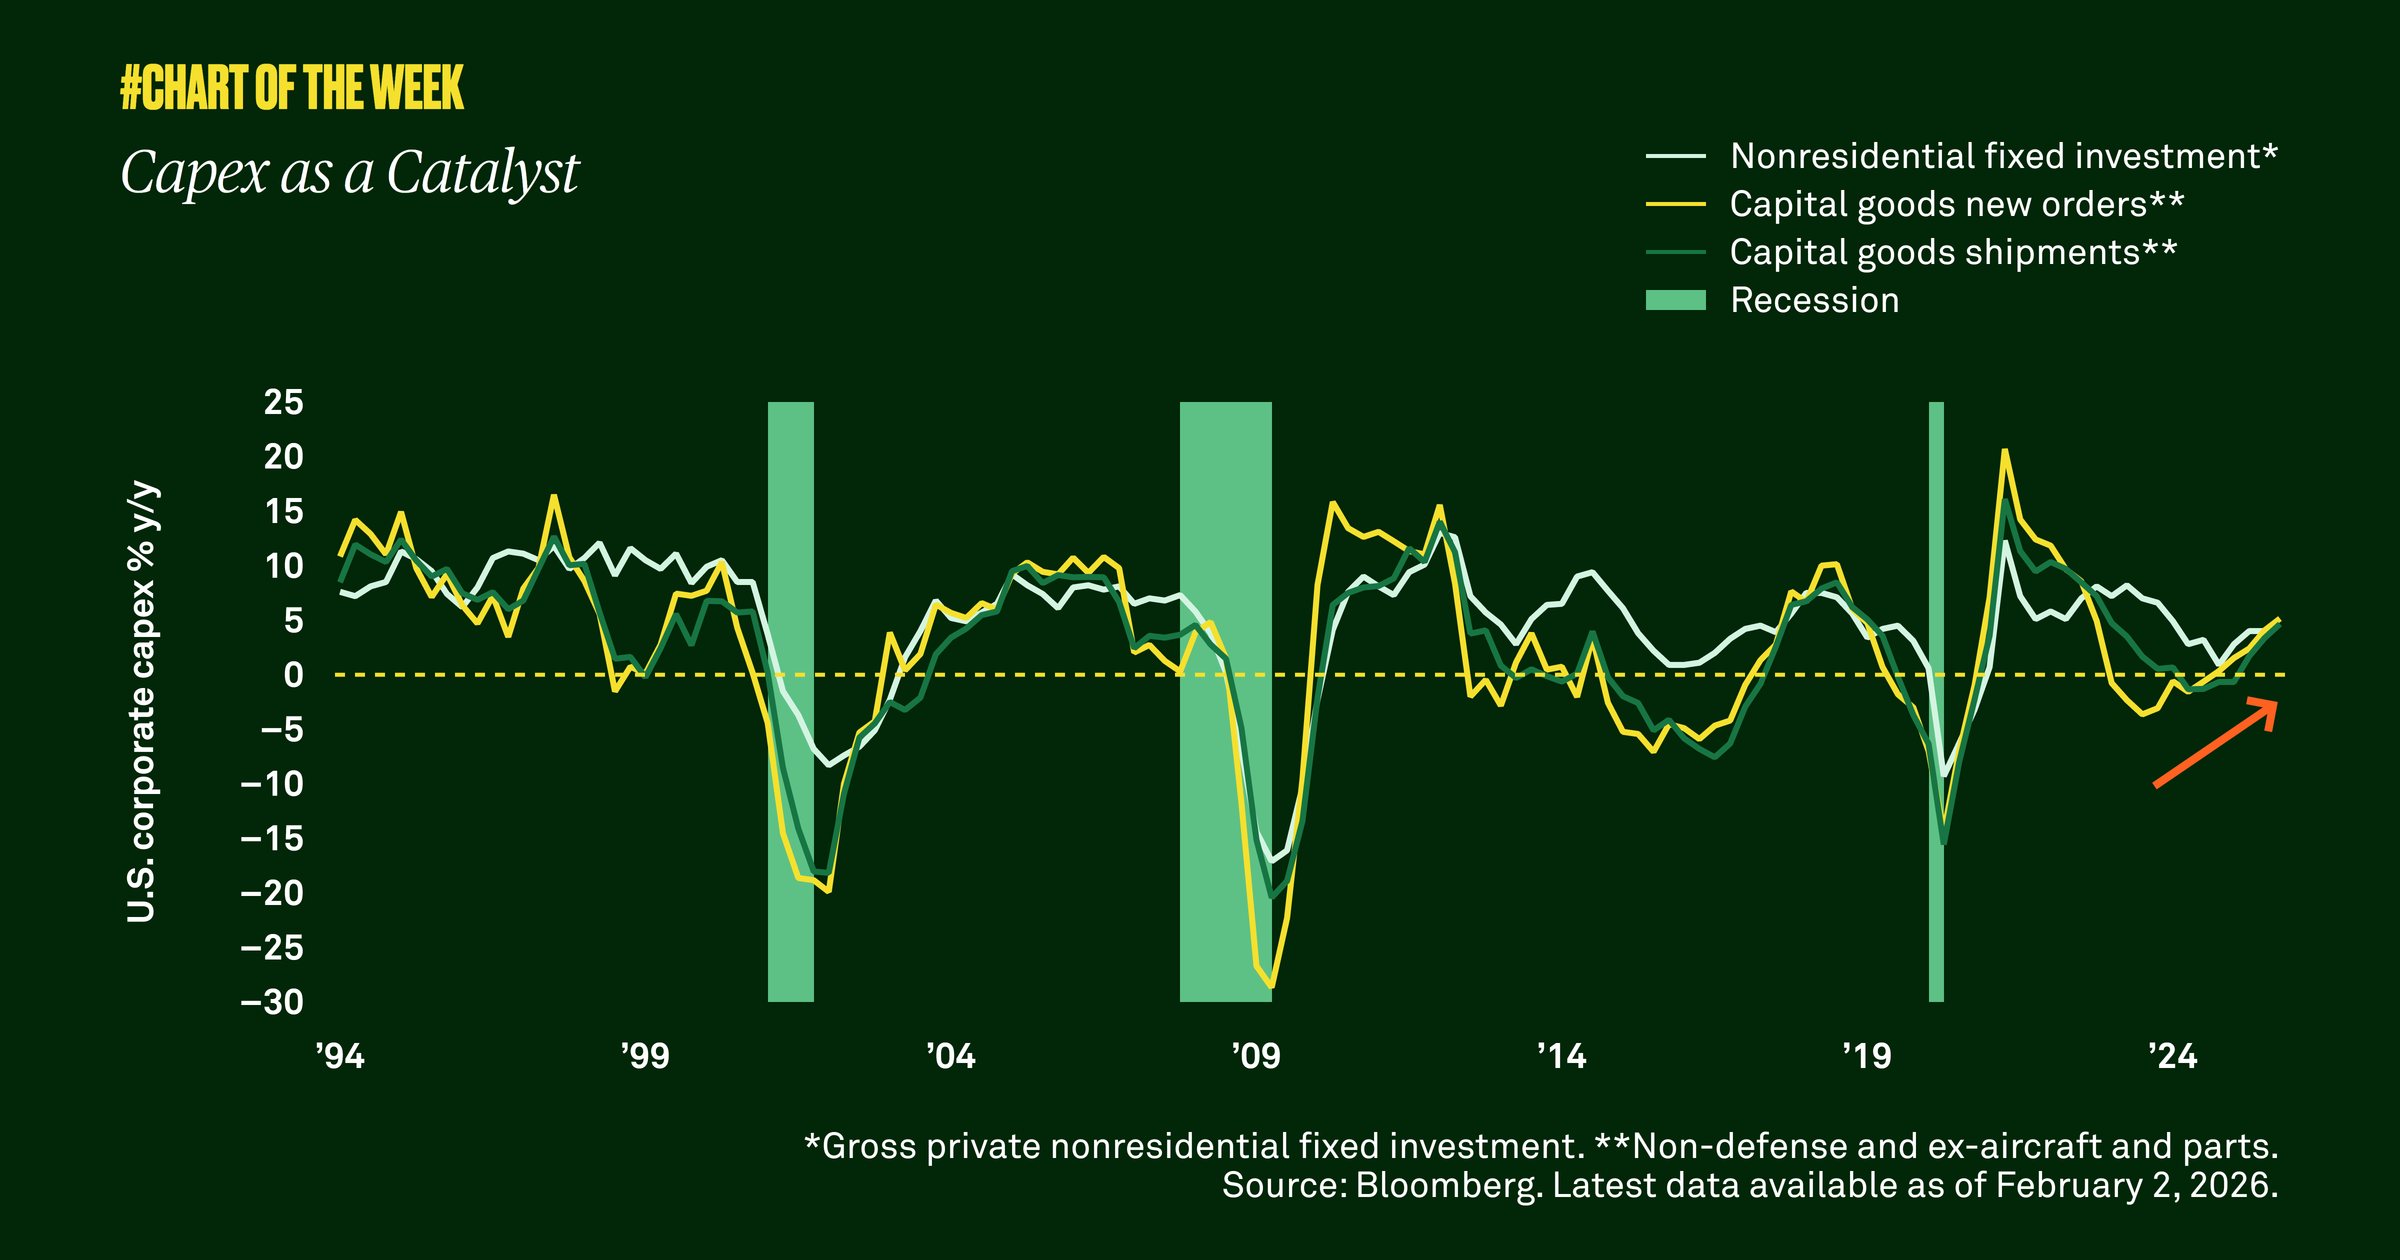

Reinvesting capital is key for U.S. corporations to remain competitive and grow their businesses. But timing these expenditures often depends on the economic cycle and expectations about future business conditions. In the early part of 2025, tariff uncertainty weighed negatively on these decisions. However, since the passage of last year’s pro-growth legislation, which includes the full expensing of capital expenditures (capex), we’ve seen a pickup in capex by U.S. corporations.

While there are many measures of capital investment, nonresidential fixed investment is an important indicator of economic health and business confidence. It represents spending on fixed assets, including structures, equipment and intellectual property products, such as research and development and software. For the first time in four years, we’ve seen this metric increase for three consecutive quarters. Another proxy for capex — capital goods new orders and shipments — is growing at its highest annual rate in three years.

We expect the improving economic outlook to support this strengthening capex trend. While corporate spend has focused on technology given the artificial intelligence race, we believe capex will broaden to include equipment manufacturing of aircraft, auto and power generation. Historically, rising capex has been a catalyst for stronger economic growth, and we expect that pattern to hold in 2026.
RELATED CONTENT
Play the long game
Chart of the Week | Macroeconomic

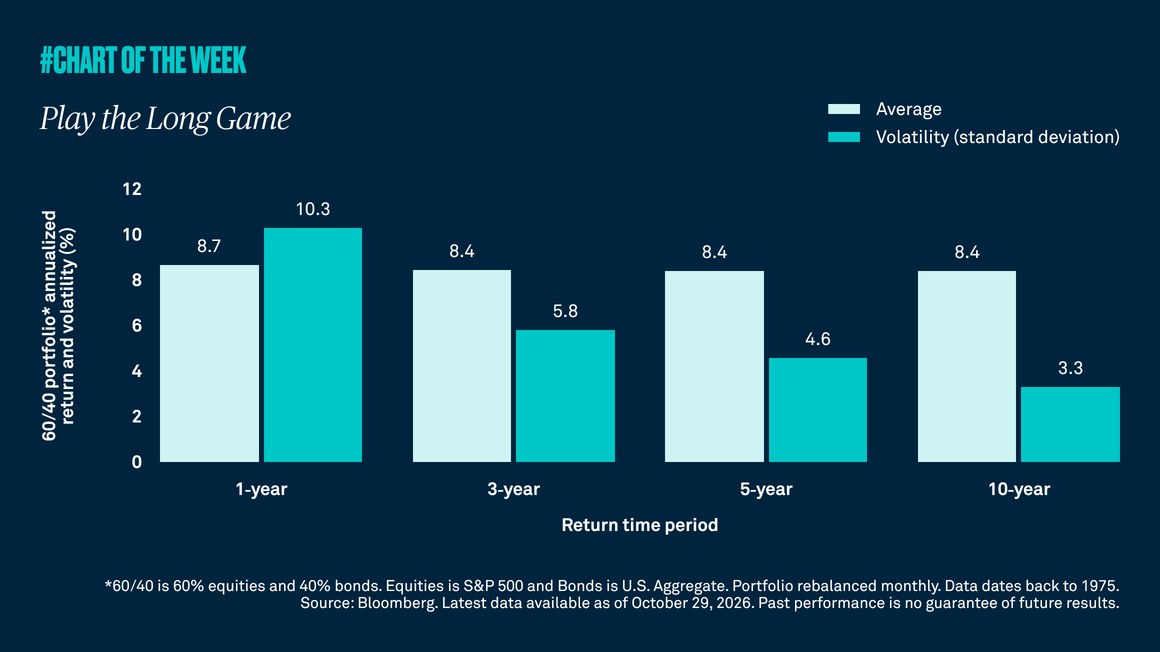
When it comes to investing, time matters. While headlines and short-term perspectives can lead investors to try and time the market, investors have historically been rewarded by playing the long game. Rather than overreacting to market noise, investing over longer time periods can help smooth the ride without sacrificing returns. The lesson: stay diversified and invested for the long term.

Contained contagion?
Chart of the Week | Macroeconomic

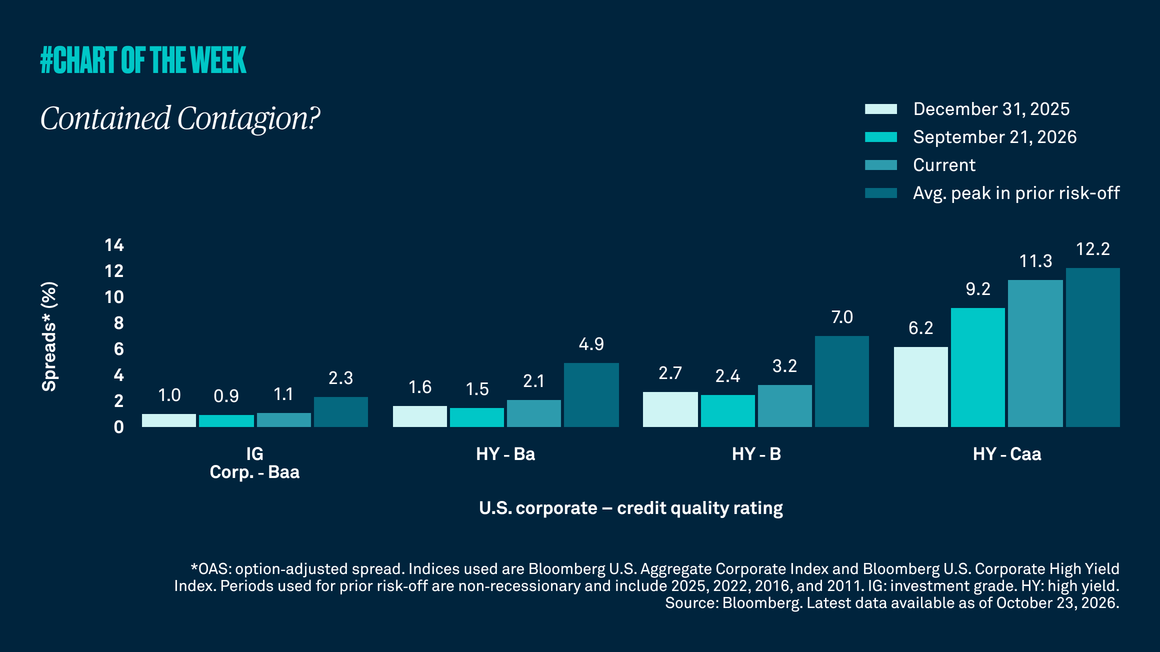
U.S. high yield credit spreads have widened year to date, reflecting greater investor caution about perceived default risk. The move also raises concerns about possible credit contagion. However, because spread widening has been concentrated in the lowest-quality issuers rather than higher-quality issuers, we don’t anticipate broader market stress.

Can the bull run in corporate margins continue?
Chart of the Week | Macroeconomic

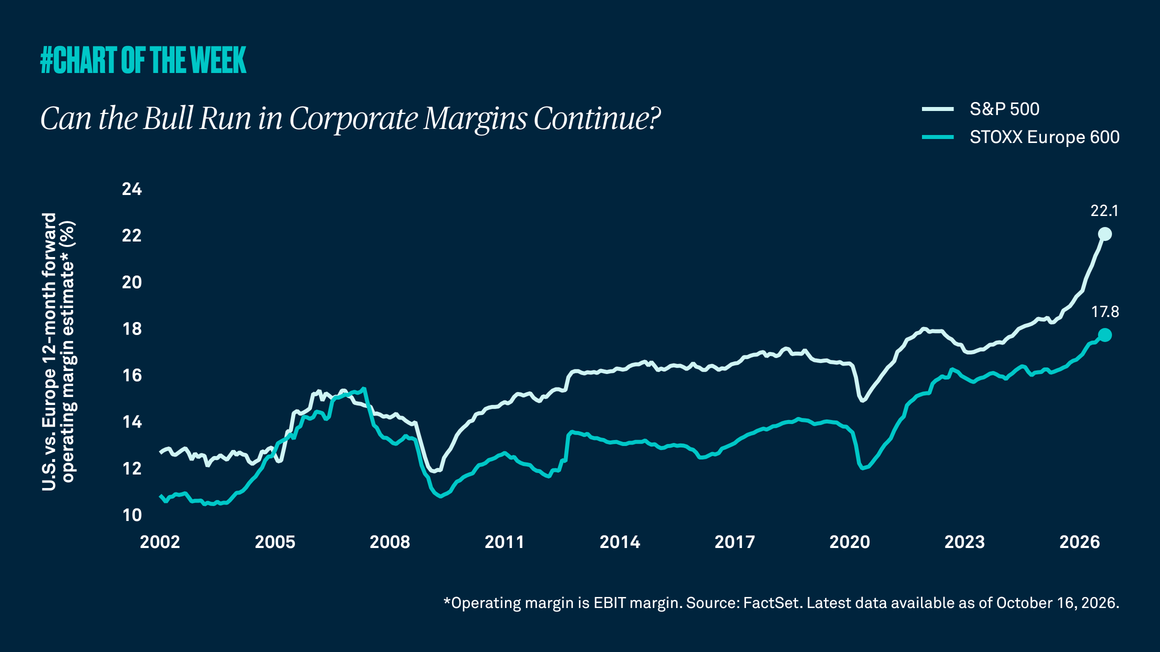
Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?

Higher yields, but lower sensitivity
Chart of the Week | Macroeconomic

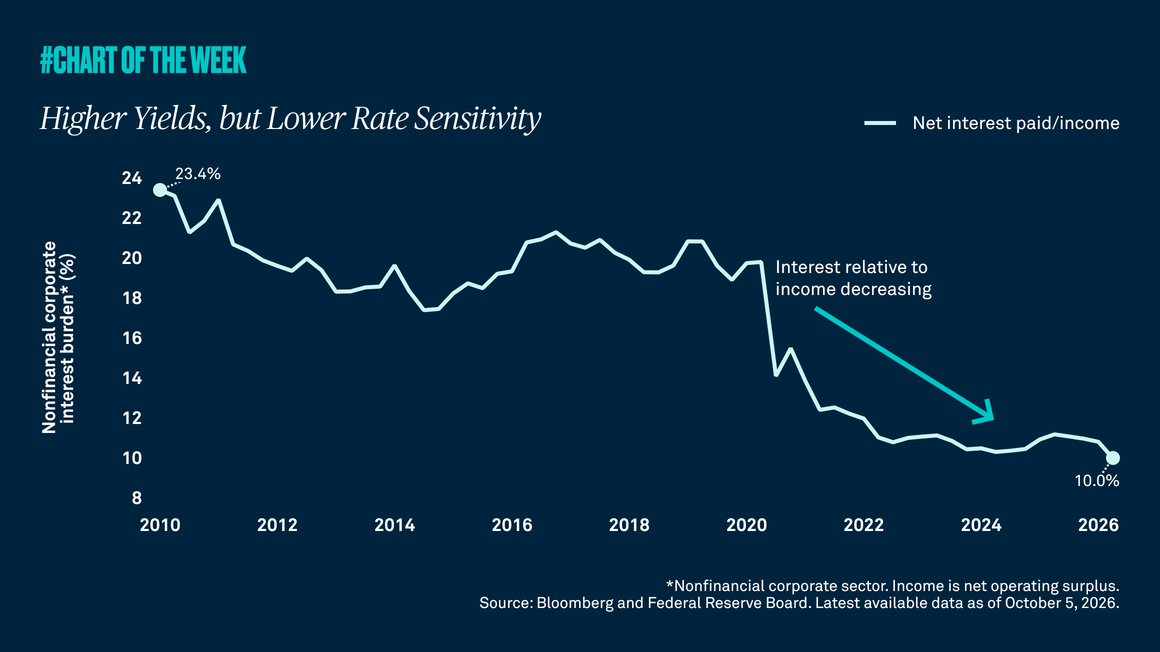
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.

Gathering data
Disclaimer Not Available

This is a marketing communication