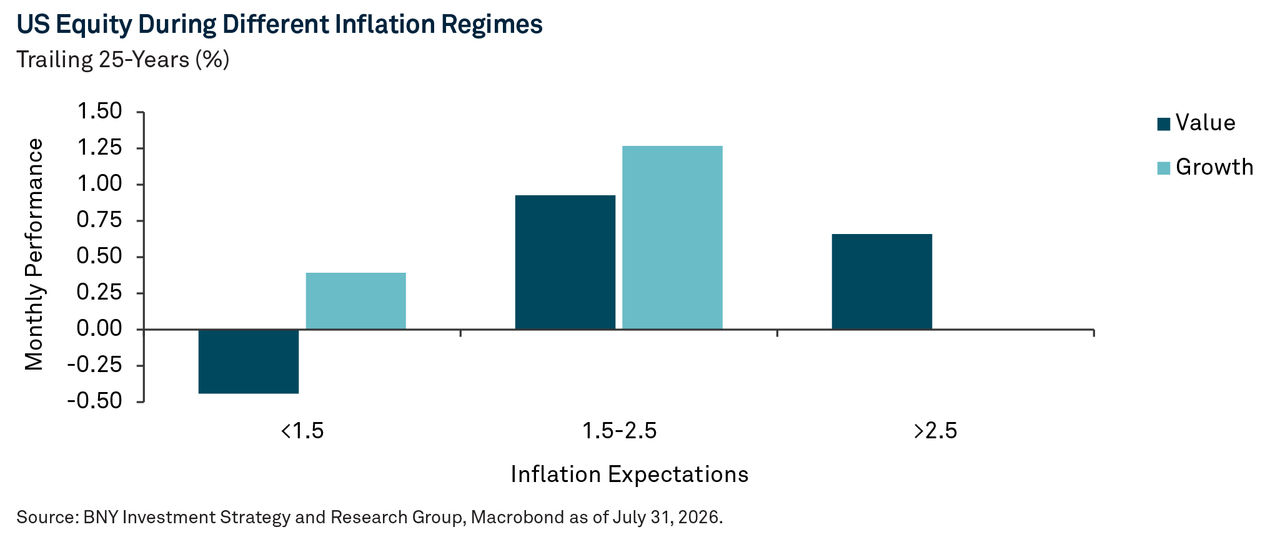
Value equities have historically shown resiliency during higher inflationary periods versus their growth counterparts. With inflation remaining elevated, we believe that value opportunities continue to be a compelling option for portfolio diversification and potential stability.
“Sticky” Core Services Persist
Although inflation has eased a bit this year, it is still lingering above the Federal Reserve’s (Fed’s) 2% target and remains sticky within certain core sectors. As indicated by the latest headline Consumer Price Index (CPI), which reached 3.4% in July, these sticky core services continue to drive price pressures and resist the broader cooling trend.
In our view, these price pressures could persist and keep the Fed from easing in the near term. Given this backdrop, we believe higher inflation and real yields should remain relatively supportive for value.
Value Beyond Tech
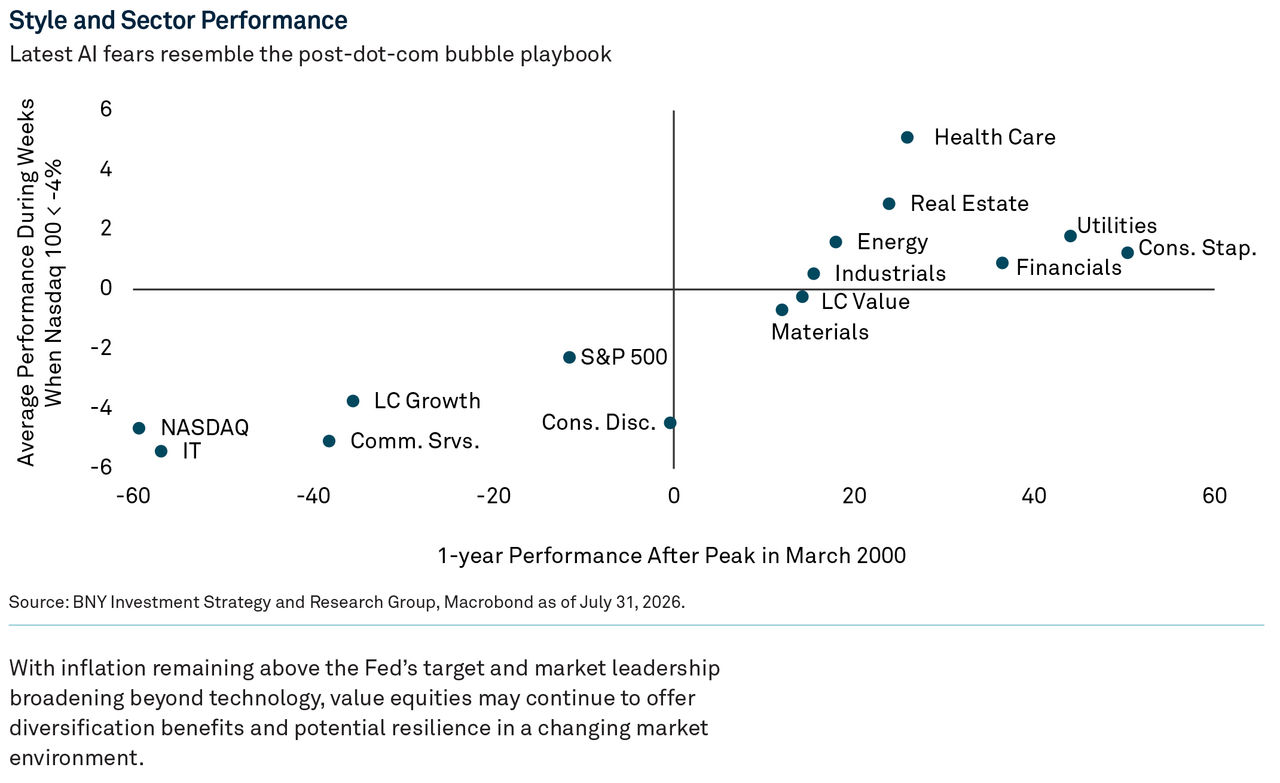
As equity markets remain highly concentrated in more technology-driven, growth-oriented companies, recent AI-related pullbacks, mostly driven by overinvestment concerns, have led to a rotation away from growth toward value, resembling the post-dot-com period of the early 2000s. These trends underscore the benefits of combining growth and value within a diversified portfolio.
In financials, we believe large banks can offer opportunities through diversified lines of business where deregulation and buybacks or dividends are tailwinds for the sector. In energy, we see attractive supply-demand dynamics in oil, gas and refineries, although ongoing geopolitical conflicts have had a major impact on oil price volatility.
Glossary
The Consumer Price Index (CPI) tracks inflation by measuring how much the cost of everyday goods and services changes over time.
Sticky Inflation is inflation that remains higher than desired and is slow to ease, particularly in areas such as services and housing where prices tend to change gradually.
Risks
All investments involve risk, including the possible loss of principal. Certain investments have specific or unique risks that should be considered along with the objectives, fees, and expenses before investing.
Equities are subject to market, market sector, market liquidity, issuer, and investment style risks to varying degrees.
Disclosures
Asset allocation and diversification cannot ensure a profit or protect against a loss.
BNY Investments is the brand name for the investment management business of BNY and its investment firm affiliates worldwide. BNY is the corporate brand of The Bank of New York Mellon Corporation and may be used to reference the corporation as a whole or its various subsidiaries generally.
The information contained herein reflects general views and is provided for informational purposes only. This material is not intended as investment advice nor is it a recommendation to adopt any investment strategy.
Opinions and views expressed are subject to change without notice.
Past performance is no guarantee of future results.
Issuing entities
This material is only for distribution in those countries and to those recipients listed, subject to the noted conditions and limitations: • United States: by BNY Mellon Securities Corporation (BNYSC), 240 Greenwich Street, New York, NY 10286. BNYSC, a registered broker-dealer and FINRA member, has entered into agreements to offer securities in the U.S. on behalf of certain BNY Investments firms. • Europe (excluding Switzerland): BNY Mellon Fund Management (Luxembourg) S.A., 2-4 Rue EugèneRuppertL-2453 Luxembourg. • UK, Africa and Latin America (ex-Brazil): BNY Mellon Investment Management EMEA Limited, BNY Mellon Centre, 160 Queen Victoria Street, London EC4V 4LA. Registered in England No. 1118580. Authorised and regulated by the Financial Conduct Authority. • South Africa: BNY Mellon Investment Management EMEA Limited is an authorised financial services provider. • Switzerland: BNY Mellon Investments Switzerland GmbH, Bärengasse 29, CH-8001 Zürich, Switzerland. • Middle East: DIFC branch of The Bank of New York Mellon. Regulated by the Dubai Financial Services Authority. • South East Asia and South Asia: BNY Mellon Investment Management Singapore Pte. Limited Co. Reg. 201230427E. Regulated by the Monetary Authority of Singapore. • Hong Kong: BNY Mellon Investment Management Hong Kong Limited. Regulated by the Hong Kong Securities and Futures Commission. • Japan: BNY Mellon Investment Management Japan Limited. BNY Mellon Investment Management Japan Limited is a Financial Instruments Business Operator with license no 406 (Kinsho) at the Commissioner of Kanto Local Finance Bureau and is a Member of the Investment Trusts Association, Japan and Japan Investment Advisers Association and Type II Financial Instruments Firms Association. • Brazil: ARX Investimentos Ltda., Av. Borges de Medeiros, 633, 4th floor, Rio de Janeiro, RJ, Brazil, CEP 22430-041. Authorized and regulated by the Brazilian Securities and Exchange Commission (CVM). • Canada: BNY Mellon Asset Management Canada Ltd. is registered in all provinces and territories of Canada as a Portfolio Manager and Exempt Market Dealer, and as a Commodity Trading Manager in Ontario. All issuing entities are subsidiaries of The Bank of New York Mellon Corporation.
No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission. All information contained herein is proprietary and is protected under copyright law.
NOT FDIC INSURED | NO BANK GUARANTEE | MAY LOSE VALUE
©2026 THE BANK OF NEW YORK MELLON CORPORATION
MARK-995403-2026-09-02
GU-933 2 September 2027