Please ensure Javascript is enabled for purposes of website accessibility Inflation is a global problem
master-copy
fr
actualites-et-analyses
false
true

Inflation is a global problem

Inflation is a global problem

Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.
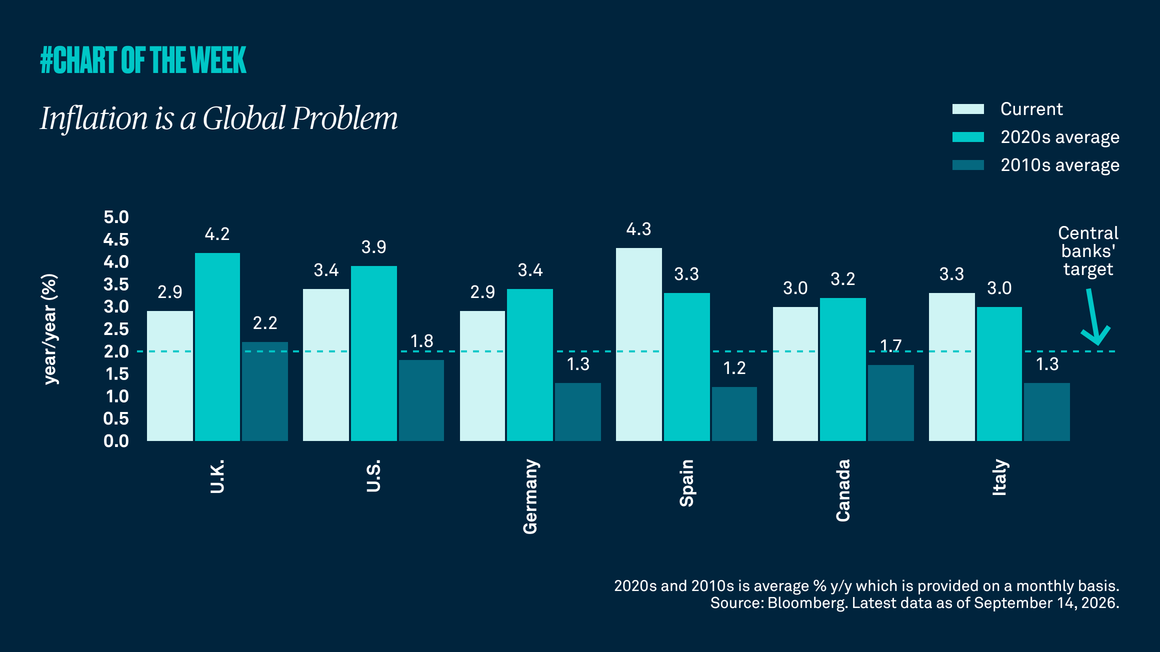

Inflation has dominated headlines since Covid, amplified more recently by higher oil prices and uncertainty surrounding the conflict with Iran. And it’s not a problem unique to the U.S. Since the pandemic, inflation across many global economies has remained persistently above historical norms — highlighting the resilience of underlying cost dynamics.

This stickiness makes it more difficult for central banks to bring inflation back toward the widely targeted 2% level in the near term. As a result, policymakers are likely to remain highly data dependent, particularly as geopolitical uncertainty continues. We would not be surprised if the outlook for central bank policy around the world shifts toward a more restrictive stance, with the possibility of further tightening if inflation proves more persistent.
AUTRES ARTICLES ASSOCIÉS
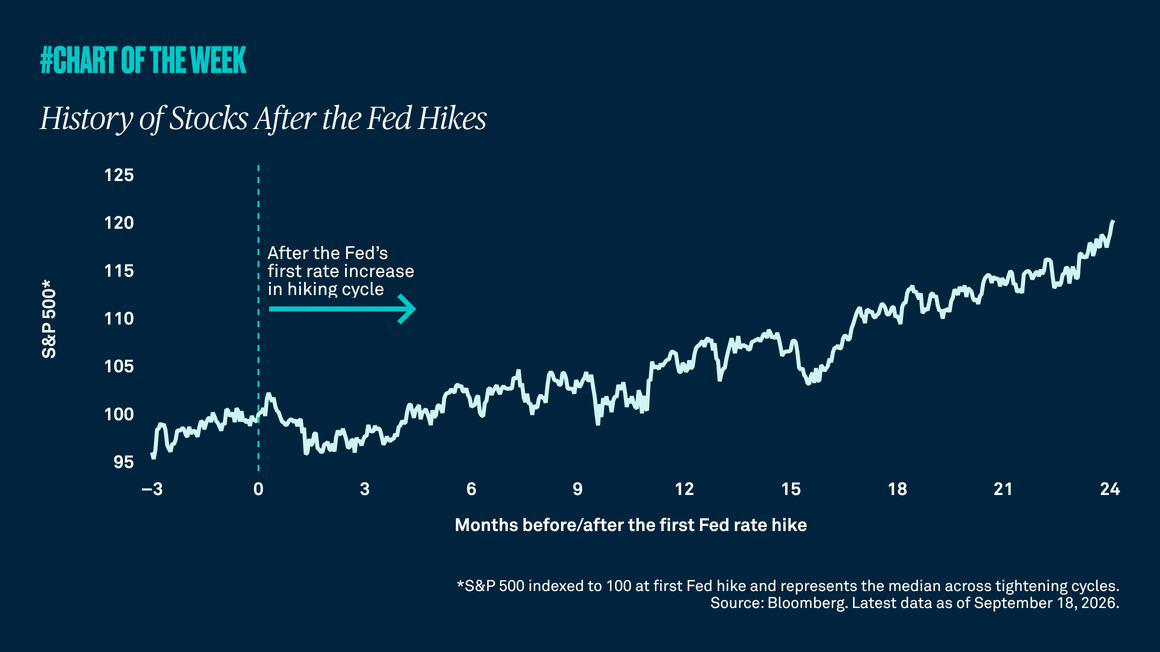
History of stocks after the fed hikes
Chart of the Week | Macroéconomique

Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.

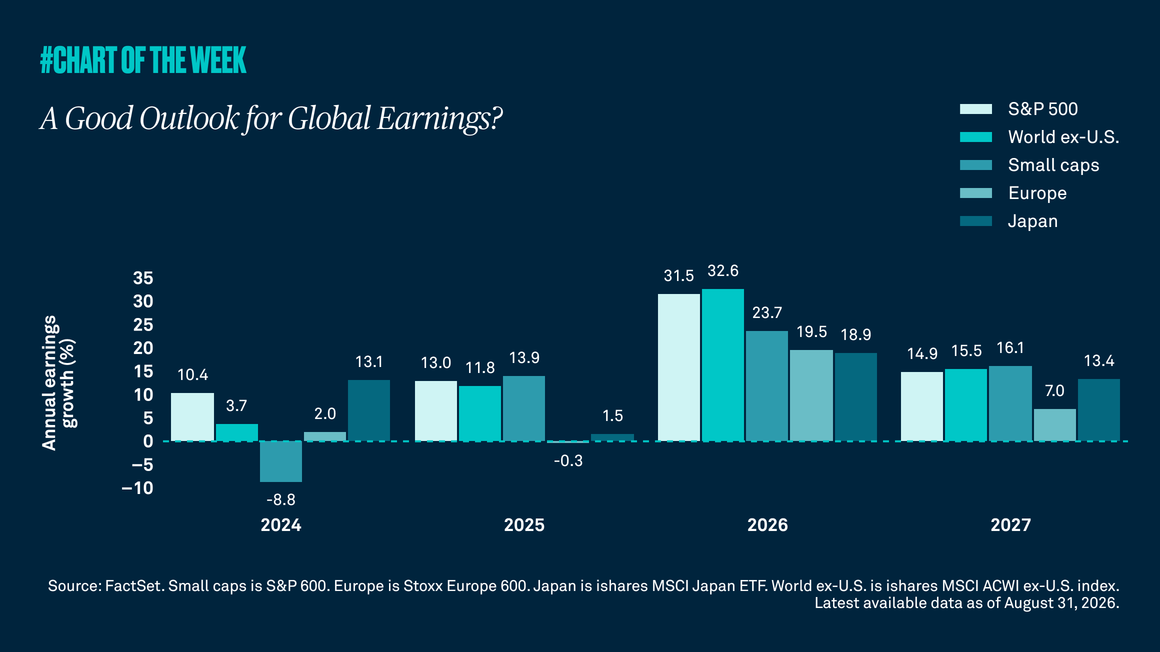
A good outlook for global earnings
Chart of the Week | Macroéconomique

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

In a real regime shift?
Chart of the Week | Macroéconomique

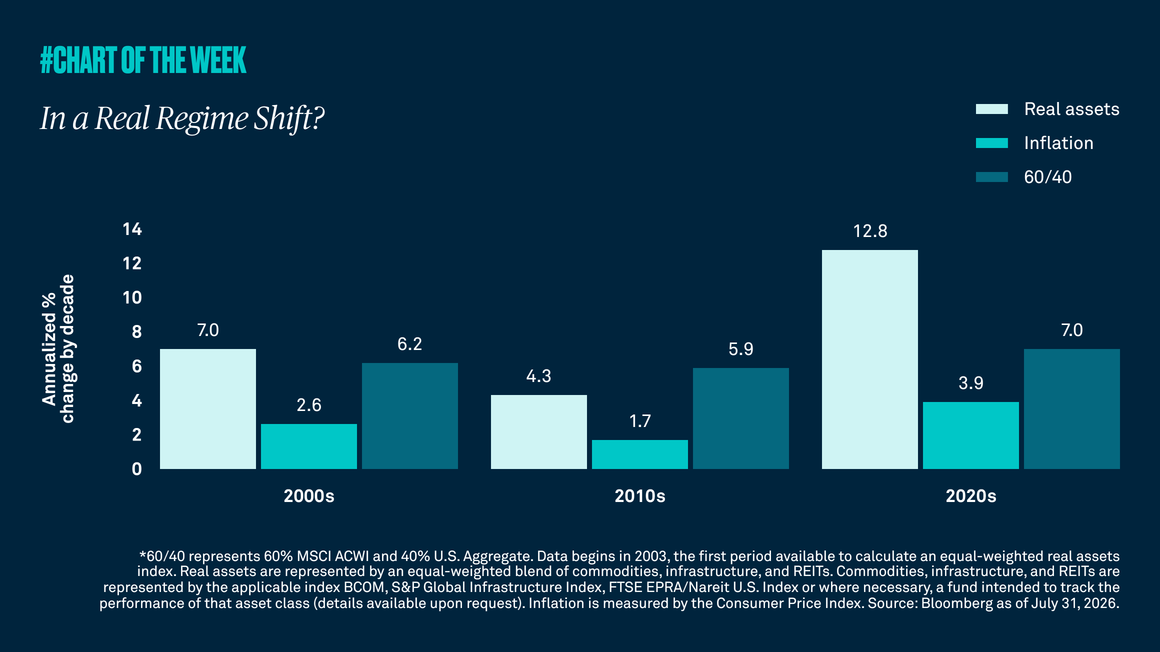
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Getting real with real assets
Chart of the Week | Macroéconomique

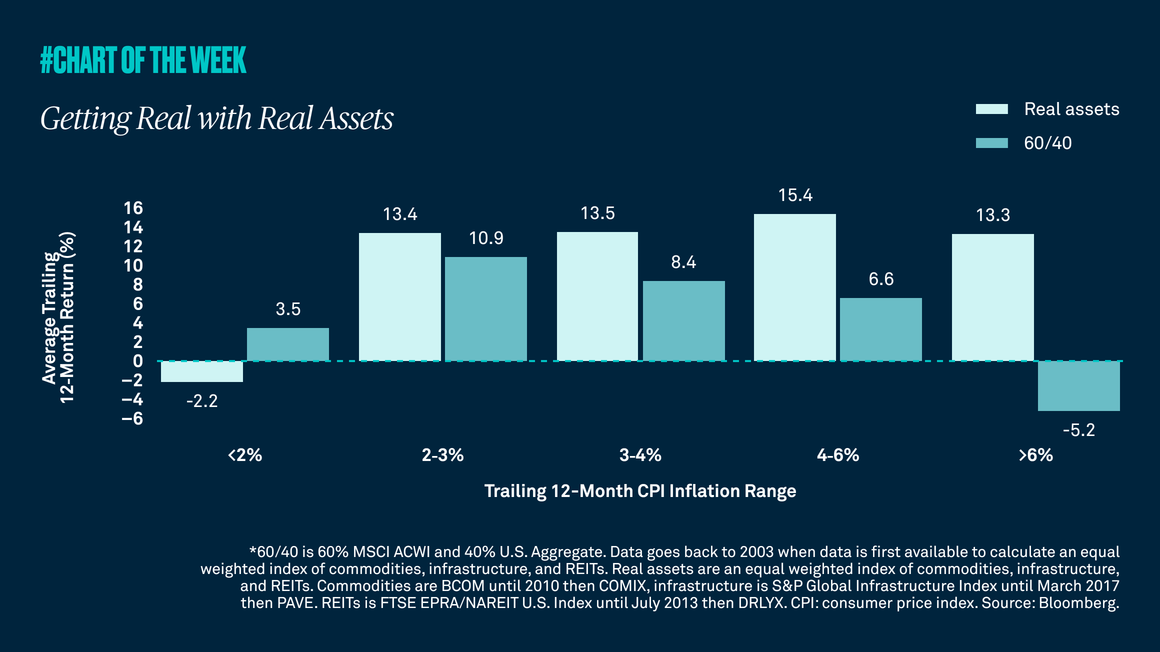
Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Gathering data
Disclaimer Not Available