Please ensure Javascript is enabled for purposes of website accessibility Monthly Checkpoints
fr
fr
intermediary
intermediary
false
true
Gathering data
Disclaimer Not Available

Monthly Checkpoints

Monthly Checkpoints

Checkpoints is a comprehensive monthly chartbook highlighting major top-of-mind themes that could shape financial markets in the near term. In addition to the broader macroeconomic discussion, Checkpoints delivers detailed views on major asset classes, including global equities, fixed income and real assets.

BABR-994077-2026-08-31 | GU-933 -28 February 2027
AUTRES ARTICLES ASSOCIÉS
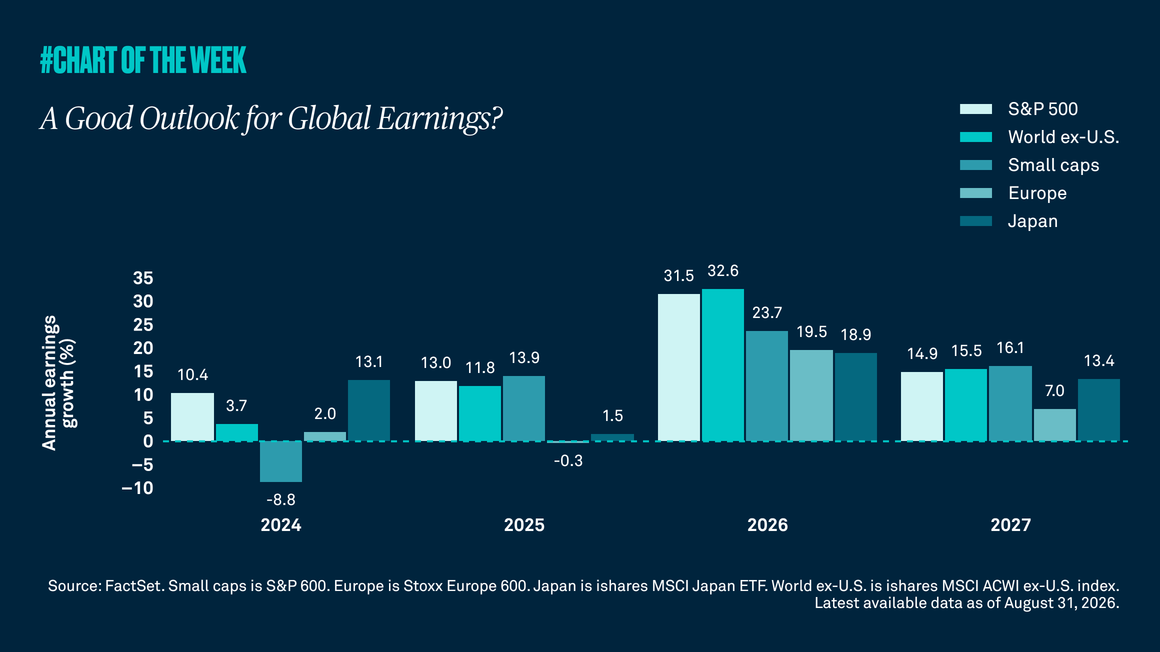
A good outlook for global earnings
Chart of the Week | Macroéconomique

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

In a real regime shift?
Chart of the Week | Macroéconomique

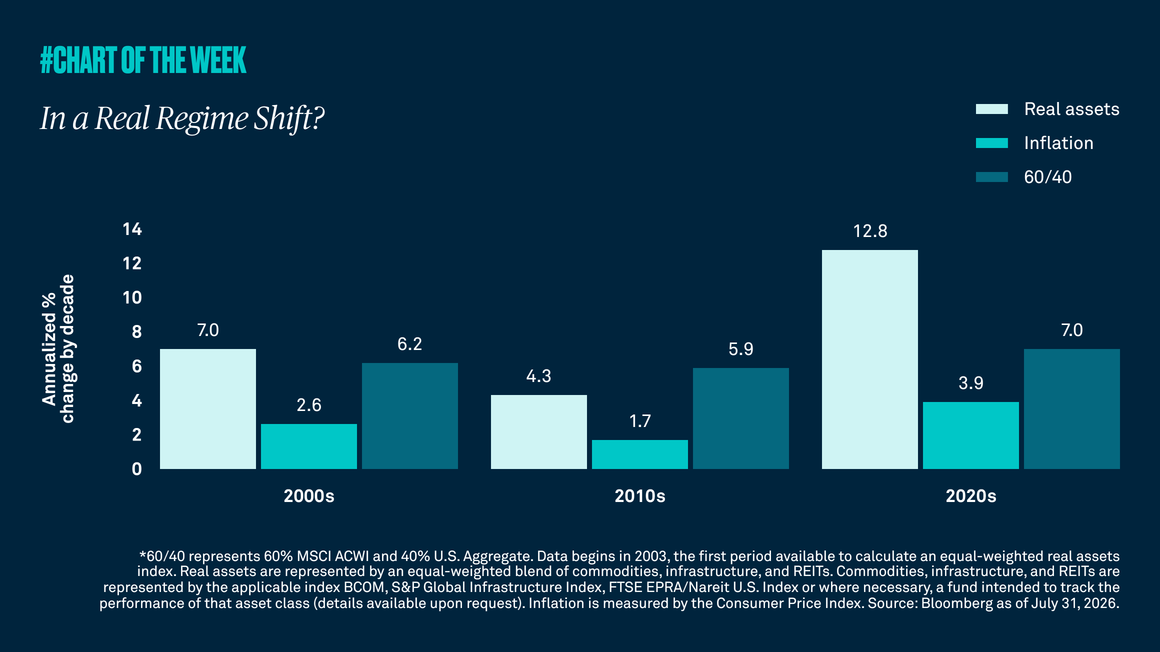
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Vue d’ensemble : leaders, retardataires et rotations de marché
Articles | Macroéconomique

Le leadership n’est jamais figé. Les gagnants d’hier peuvent sembler être les leaders de demain, mais cette mosaïque montre à quelle vitesse les actifs les plus performants peuvent perdre la faveur des investisseurs. Comme on le voit ici, les matières premières sont passées de l’une des classes d’actifs les plus performantes en 2022 à l’une des moins performantes en 2023. Ces rotations sont difficiles à prévoir, et l’incertitude est inhérente à l’investissement.

Getting real with real assets
Chart of the Week | Macroéconomique

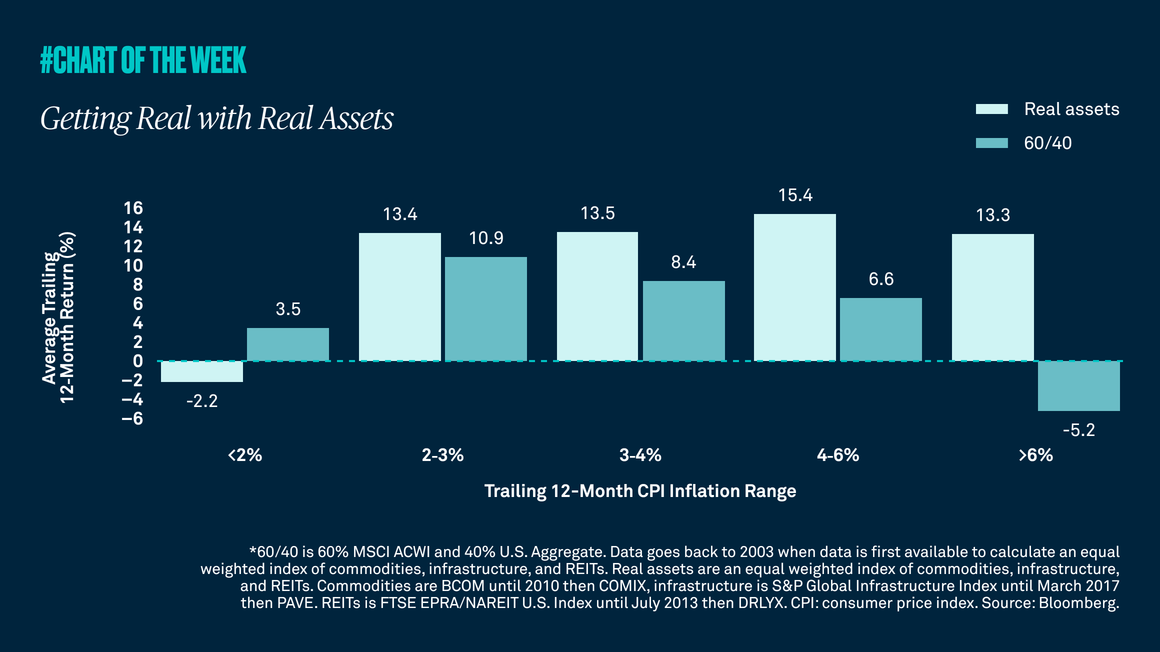
Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Gathering data
Disclaimer Not Available

Ce document constitue une communication marketing