Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?
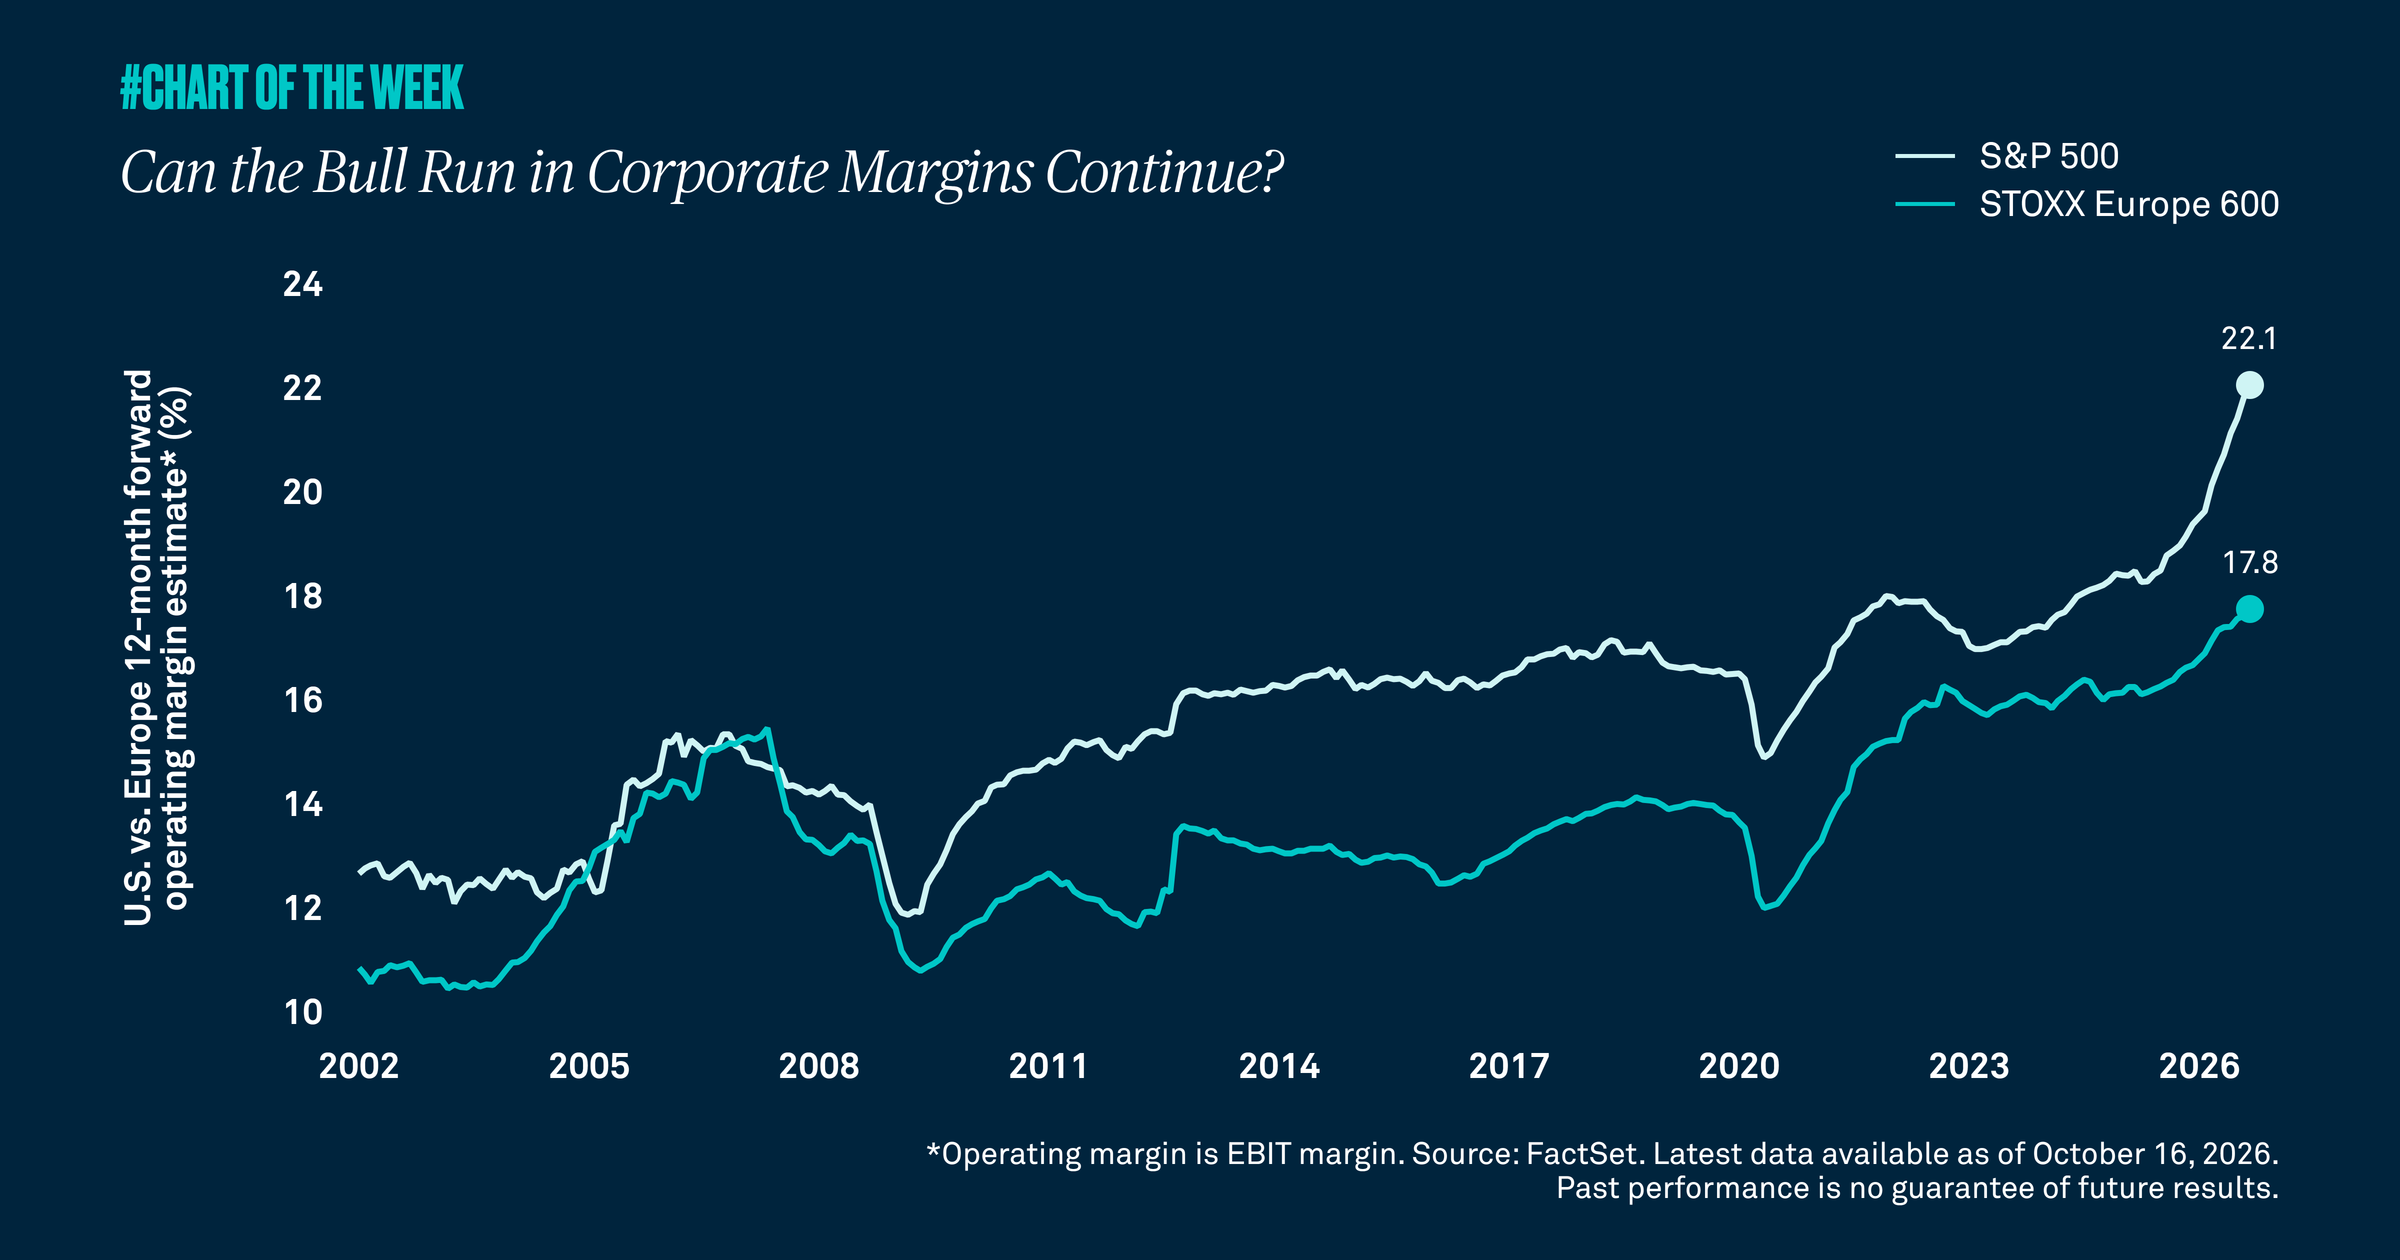
For investors, corporate margins allow companies to retain more profit from each dollar of revenue and are an important part of the earnings equation. The current bull run in corporate profit margins began during Covid and has been driven in part by advances in technology and artificial intelligence. Despite this year’s higher inflation and interest rates, there have been further gains.
While margins have been rising in both the U.S. and Europe, the U.S. retains a clear advantage. Consensus 12-month forward operating margin estimates for the S&P 500 now exceed those for the STOXX Europe 600 by 4.3 percentage points – the widest gap on record. Stronger margins have supported resilient earnings and helped underpin U.S. equity leadership.
Can the momentum continue? We expect margins to remain strong, although the pace of improvement could moderate over the next six to 12 months. Even so, that backdrop should continue to support earnings growth and reinforce our continued preference for U.S. large cap equities within a diversified portfolio.