Please ensure Javascript is enabled for purposes of website accessibility History of stocks after the Fed hikes
master-copy
en
news-and-insights
news-and-insights
false
true

History of stocks after the Fed hikes

History of stocks after the Fed hikes

As the BNY Strategic Bond Fund marks its fifth anniversary, we reflect on a period of significant change across global fixed income markets.
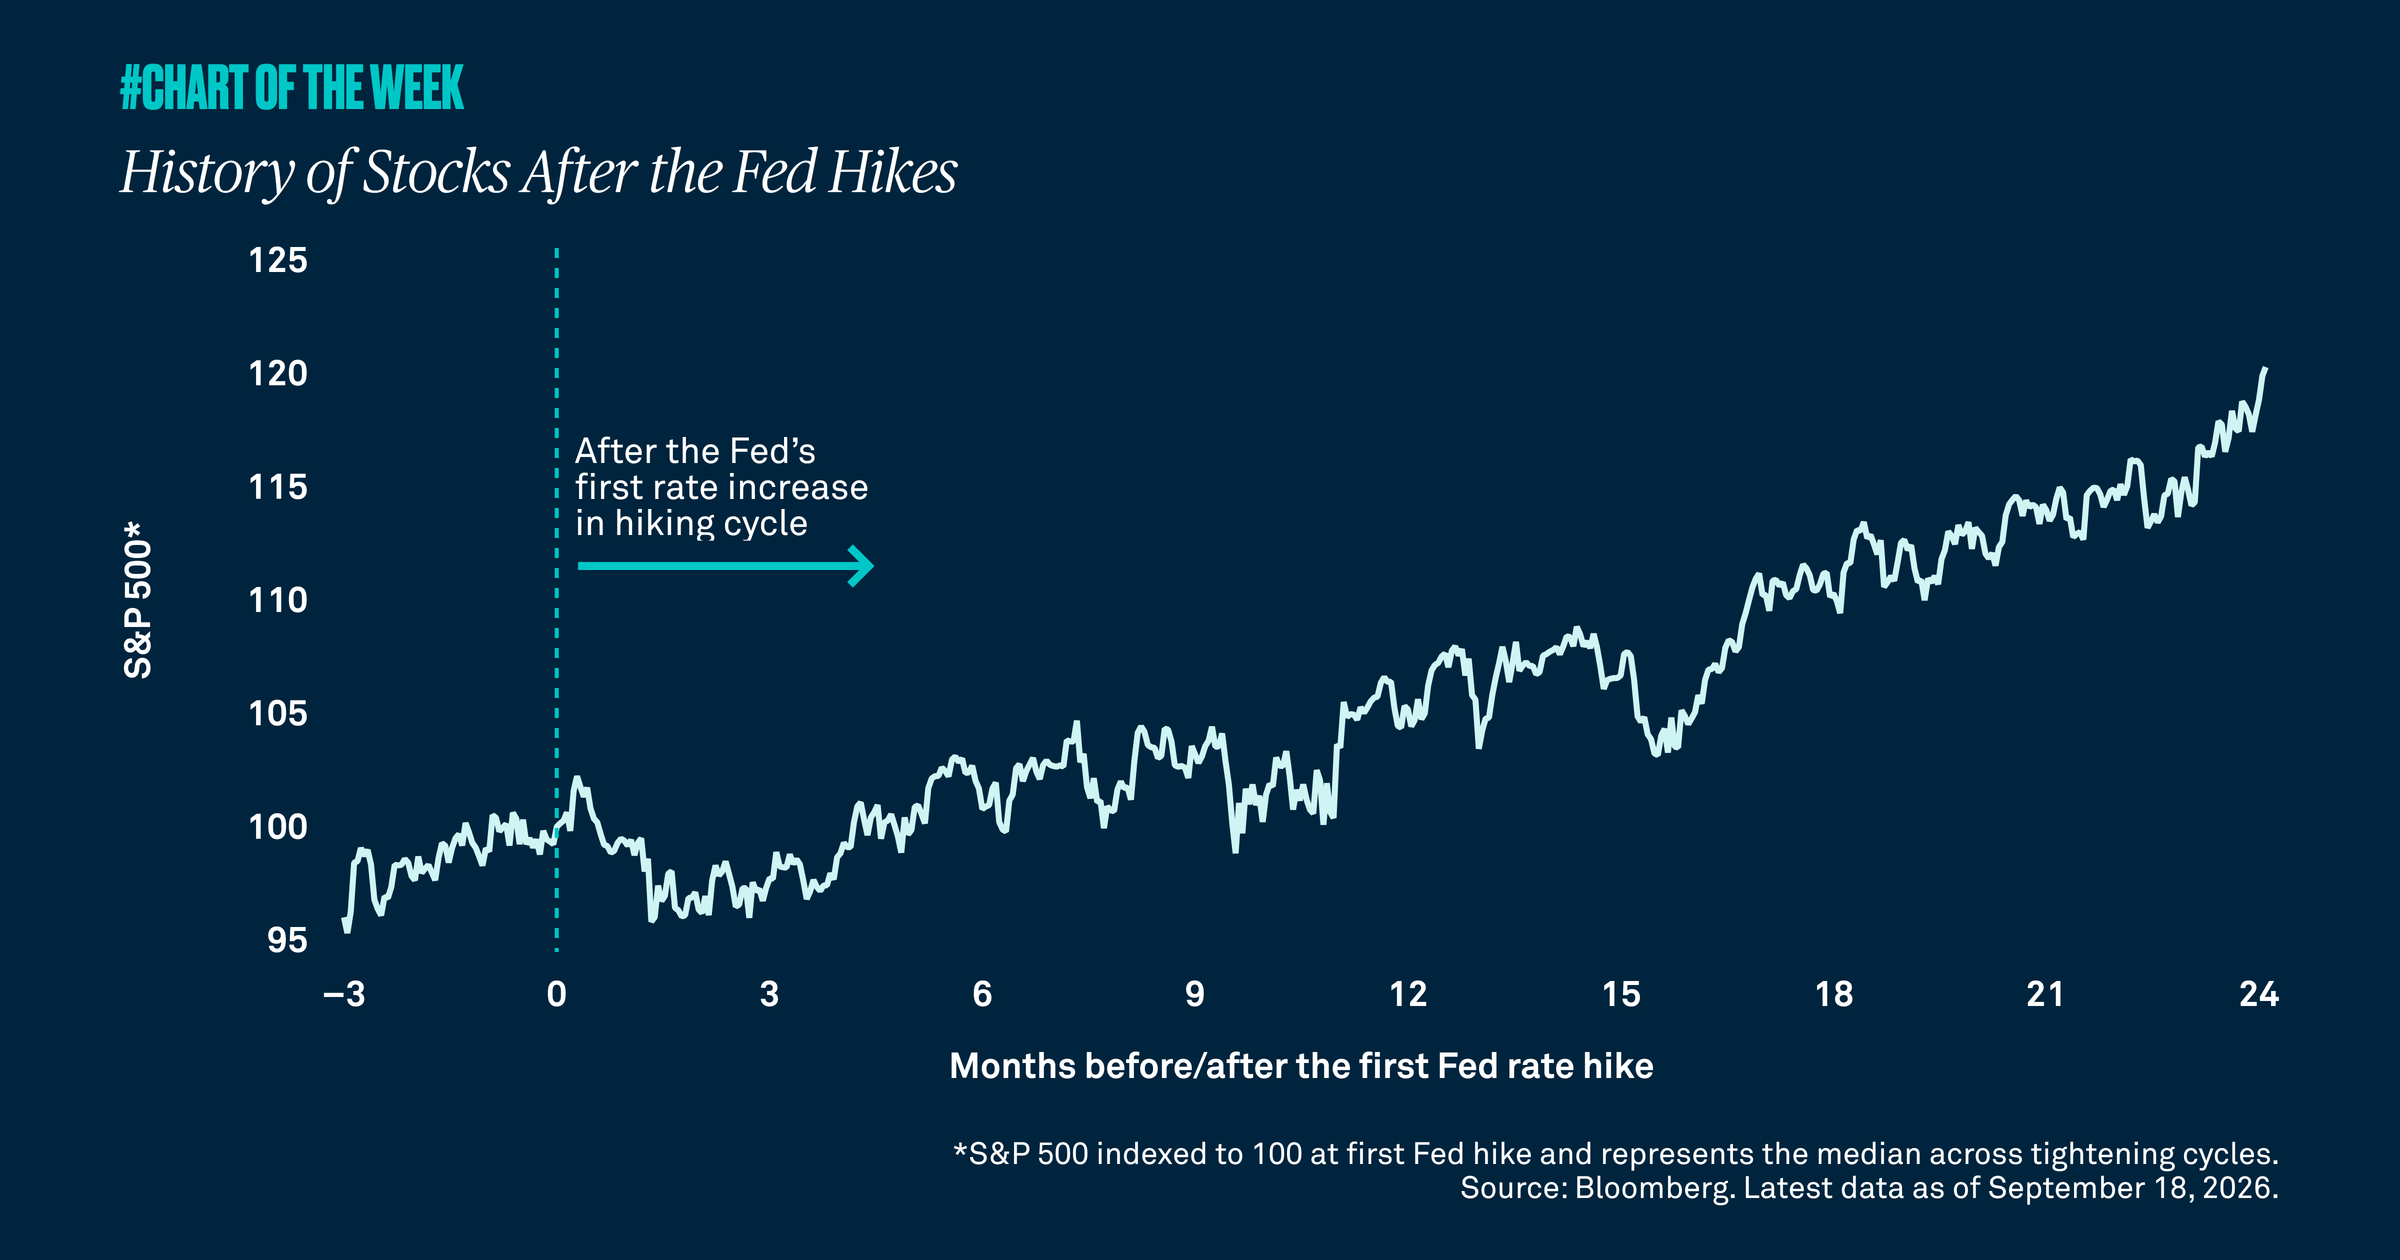
 

Sticky inflation and resilient growth have pushed the Federal Reserve back into a tightening mode for the first time in three years. Last week’s policy announcement suggested that more hikes may lie ahead, raising the risk of higher-for-longer rates. Historically, equities often struggle in the first few months of a hiking cycle as markets adjust to tighter financial conditions, then begin to recover as earnings and growth expectations remain intact.

With yields elevated, policy uncertainty still a factor and midterm election season approaching, near-term volatility could persist, even if the broader economic backdrop remains constructive.

Because we do not expect a recession and continue to foresee resilient earnings growth, we believe periods of market weakness should be viewed as buying opportunities. In addition, we recommend allocating to real assets to hedge against structurally higher inflation and to benefit from the ongoing capital expenditure cycle, which is helping support resilient growth and, in our view, still offers further upside.
RELATED CONTENT
Higher yields, but lower sensitivity
Chart of the Week | Macroeconomic

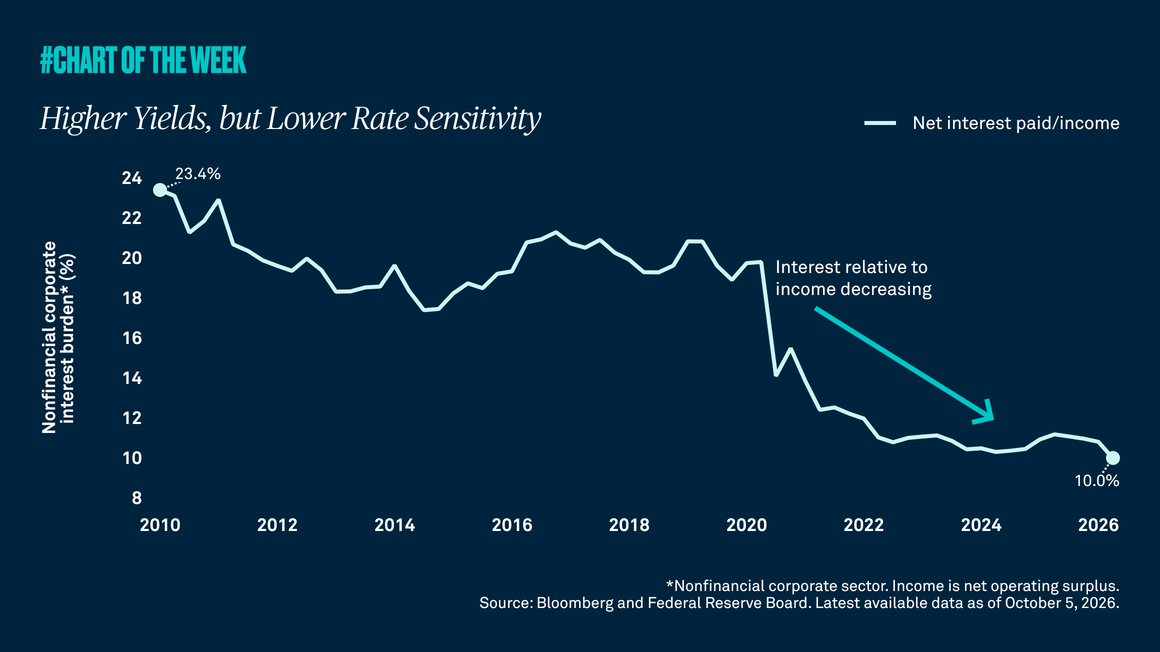
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.

Is AI productivity hiding in the data?
Chart of the Week | Macroeconomic

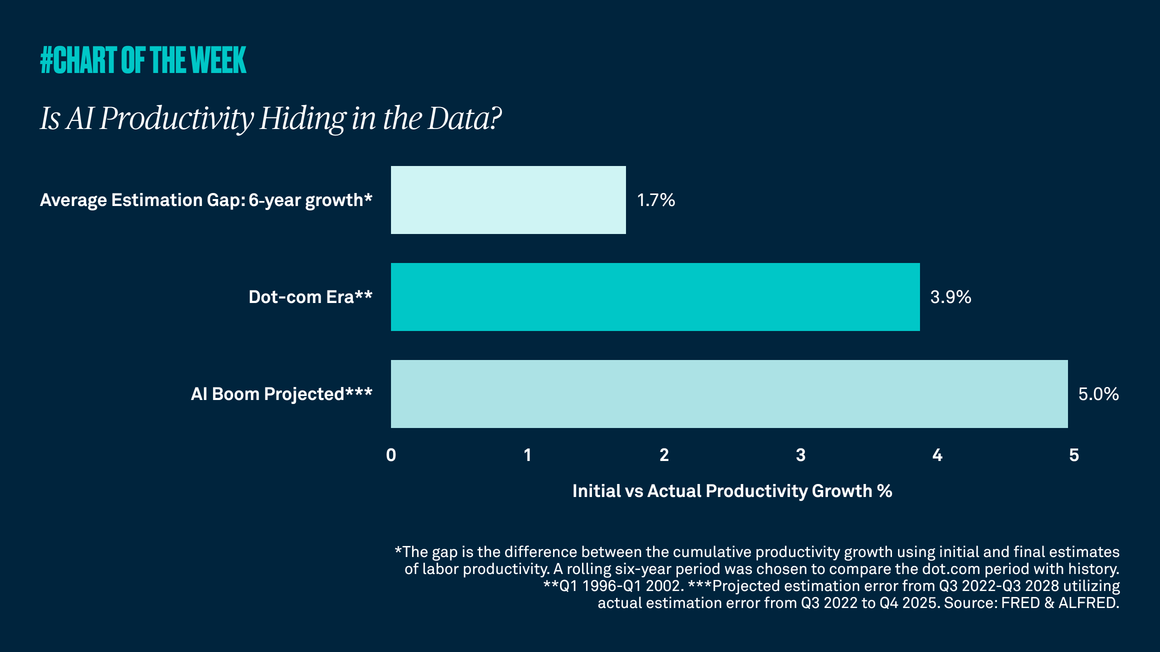
Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.

Inflation is a global problem
Chart of the Week | Macroeconomic

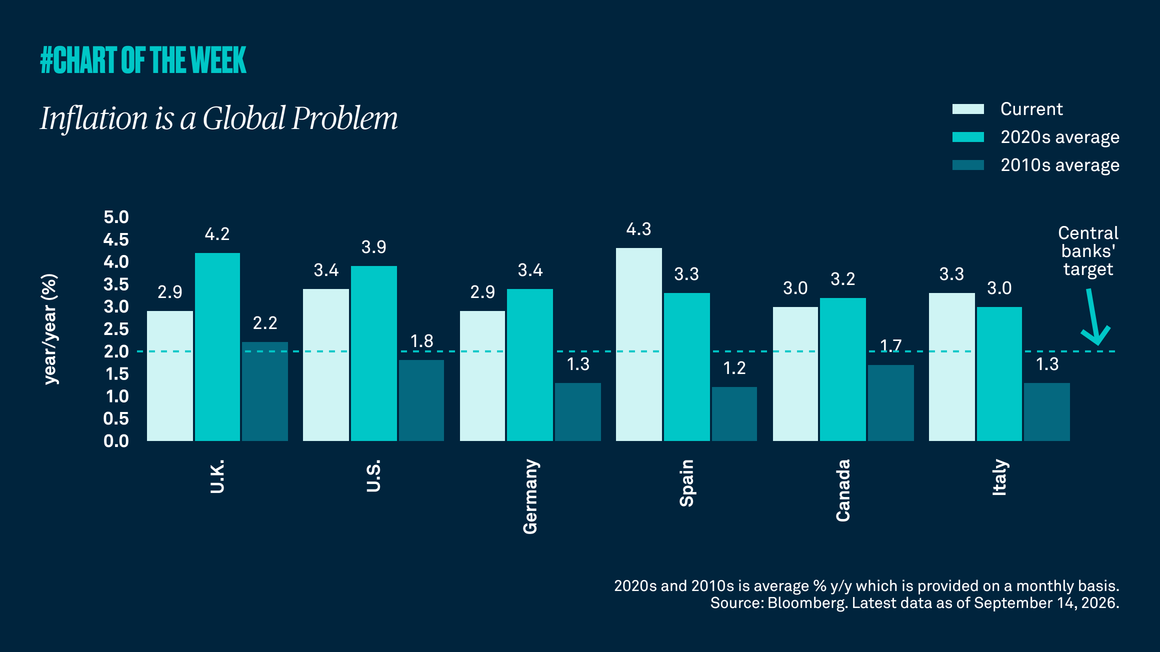
Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.

A good outlook for global earnings
Chart of the Week | Macroeconomic

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

Gathering data
Disclaimer Not Available