Please ensure Javascript is enabled for purposes of website accessibility Inflation is a global problem
master-copy
de
markte-und-analysen
markte-und-analysen
false
true

Inflation is a global problem

Inflation is a global problem

Resilient economic growth, sticky inflation driven by higher energy prices and continued geopolitical uncertainty are complicating the path back to central-bank price targets. We believe policymakers are likely to adopt a tightening bias but remain data dependent.
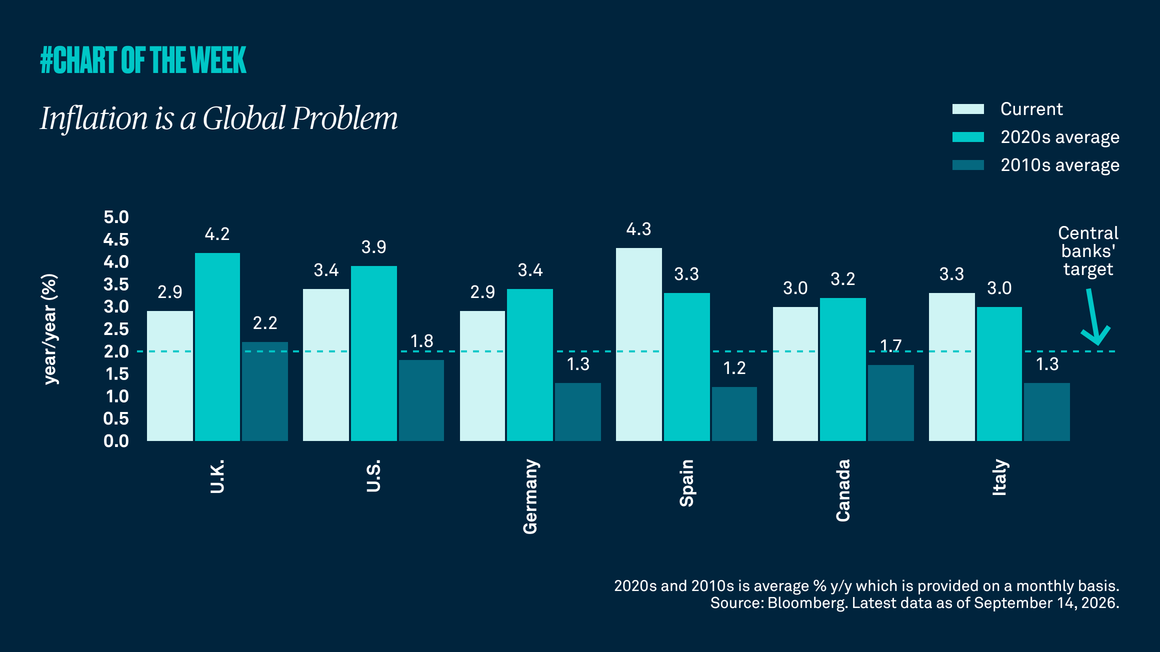

Inflation has dominated headlines since Covid, amplified more recently by higher oil prices and uncertainty surrounding the conflict with Iran. And it’s not a problem unique to the U.S. Since the pandemic, inflation across many global economies has remained persistently above historical norms — highlighting the resilience of underlying cost dynamics.

This stickiness makes it more difficult for central banks to bring inflation back toward the widely targeted 2% level in the near term. As a result, policymakers are likely to remain highly data dependent, particularly as geopolitical uncertainty continues. We would not be surprised if the outlook for central bank policy around the world shifts toward a more restrictive stance, with the possibility of further tightening if inflation proves more persistent.
VERWANDTE THEMEN
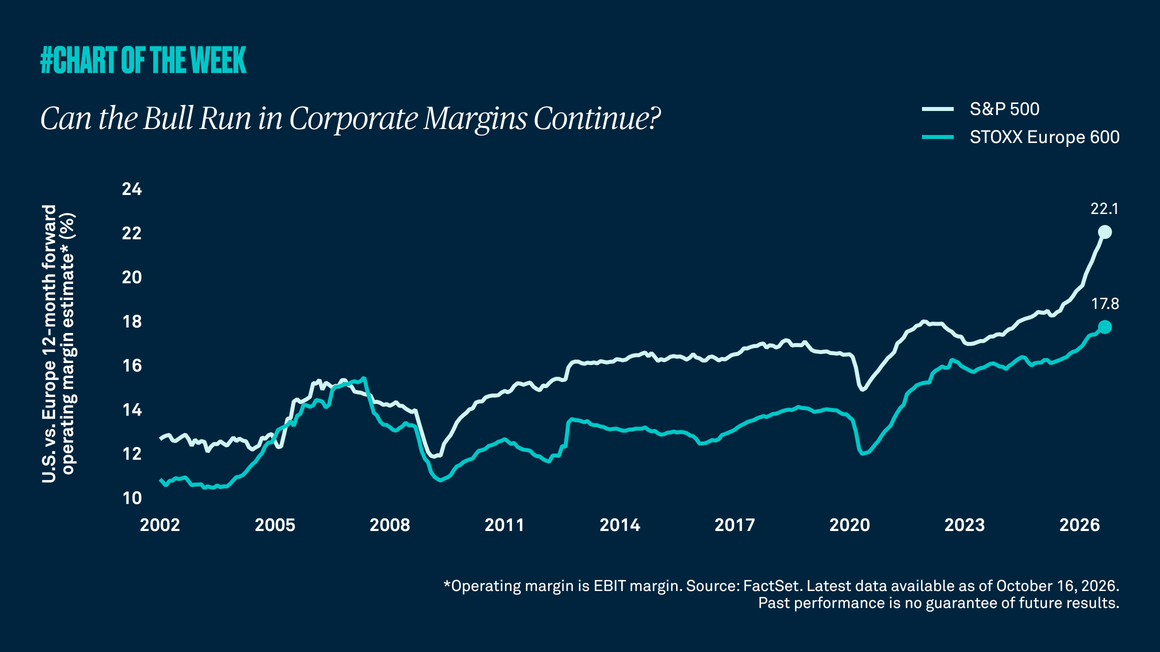
Can the bull run in corporate margins continue?
Chart of the Week | Makroökonomisch

Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?

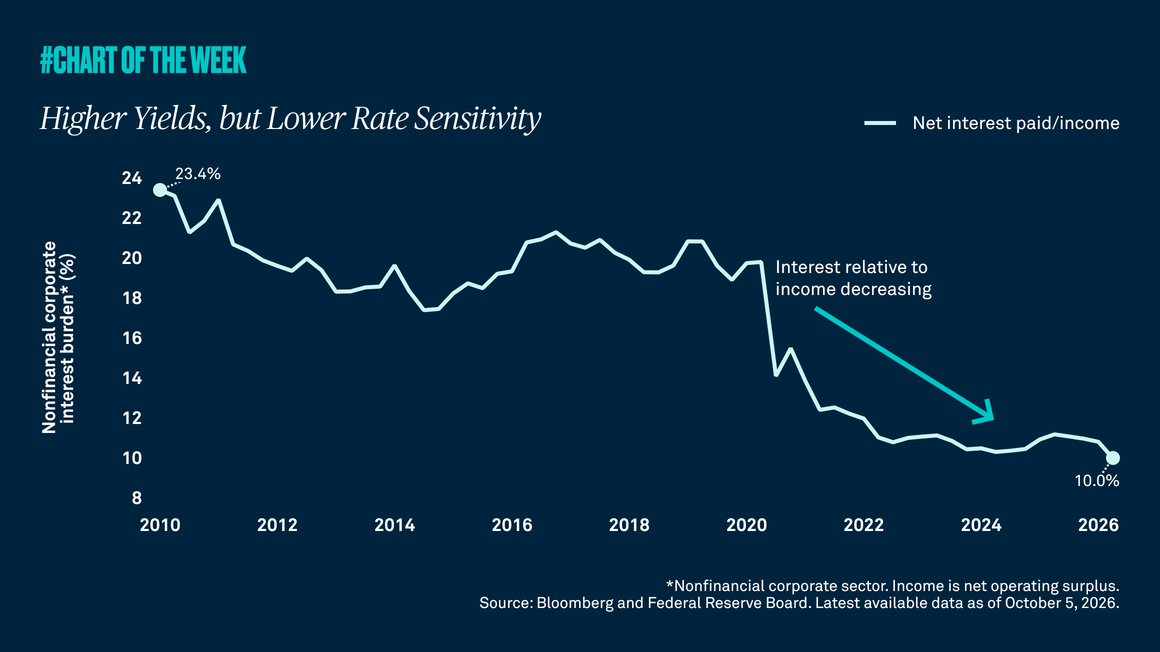
Higher yields, but lower sensitivity
Chart of the Week | Makroökonomisch

Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.

Is AI productivity hiding in the data?
Chart of the Week | Makroökonomisch

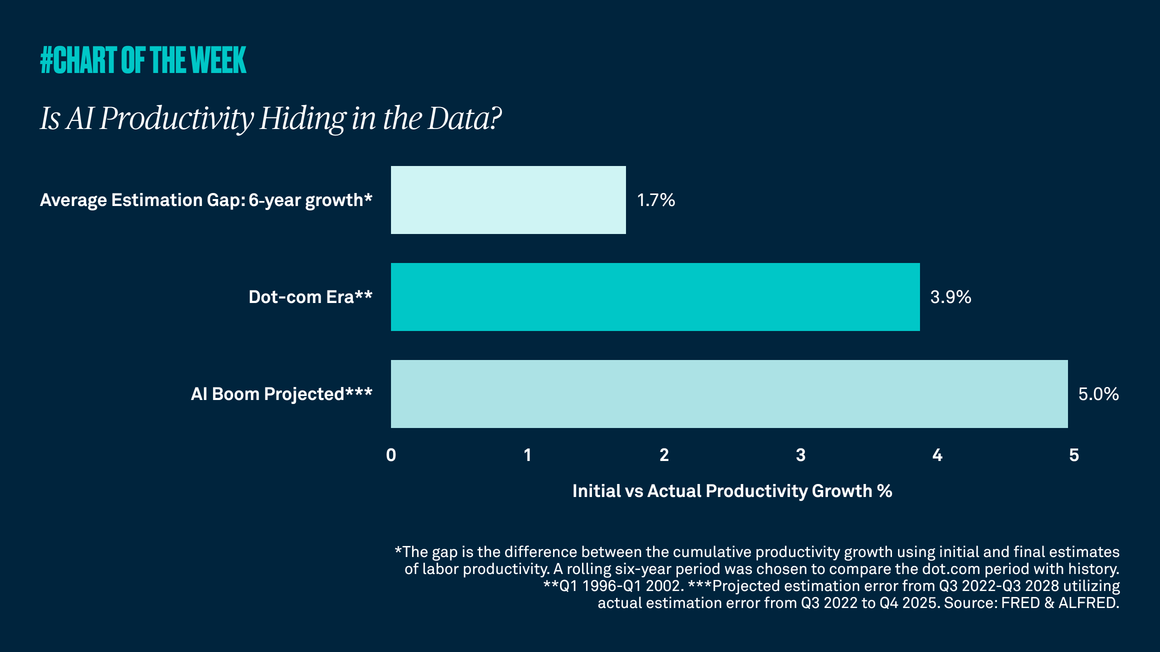
Both the dot-com era and the rise of artificial intelligence suggest that early productivity data can understate the actual economic impact of transformative technologies. In the case of the internet, later revisions to productivity gains surpassed early estimates. The same may prove true for AI, implying stronger support for growth.

History of stocks after the fed hikes
Chart of the Week | Makroökonomisch

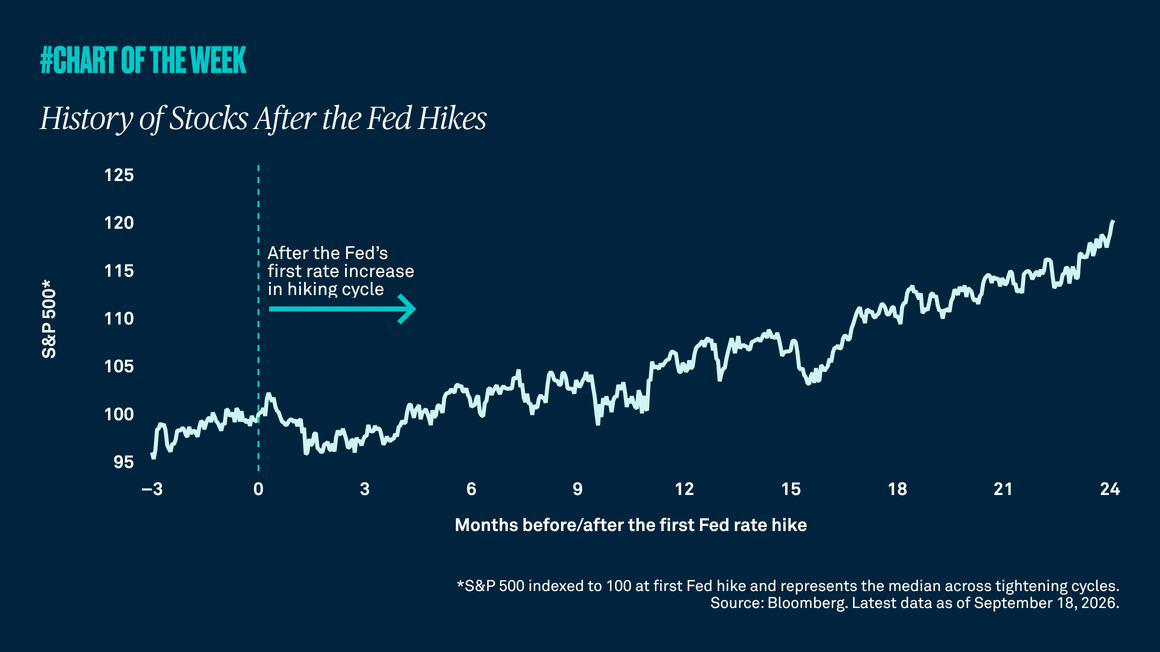
Sticky inflation and resilient growth have revived monetary tightening, increasing the risk of higher-for-longer rates and near-term volatility. We continue to believe economic resilience and strong corporate profits should continue to provide a favorable backdrop for stocks, and would use periods of market weakness to add selectively to equities. Additionally, owning real assets can help hedge against inflation.

Gathering data
Disclaimer Not Available