Please ensure Javascript is enabled for purposes of website accessibility Good News on Inflation?
ie
en
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Good news on inflation?

Good news on inflation?

Last week’s Consumer Price Index report, a widely used indicator of inflation in the U.S. economy, showed growth of 3% in September, which was above 2.9% in August but less than expected. Despite the modest increase, various categories have shown signs of stabilization. What does this mean for inflation going forward?
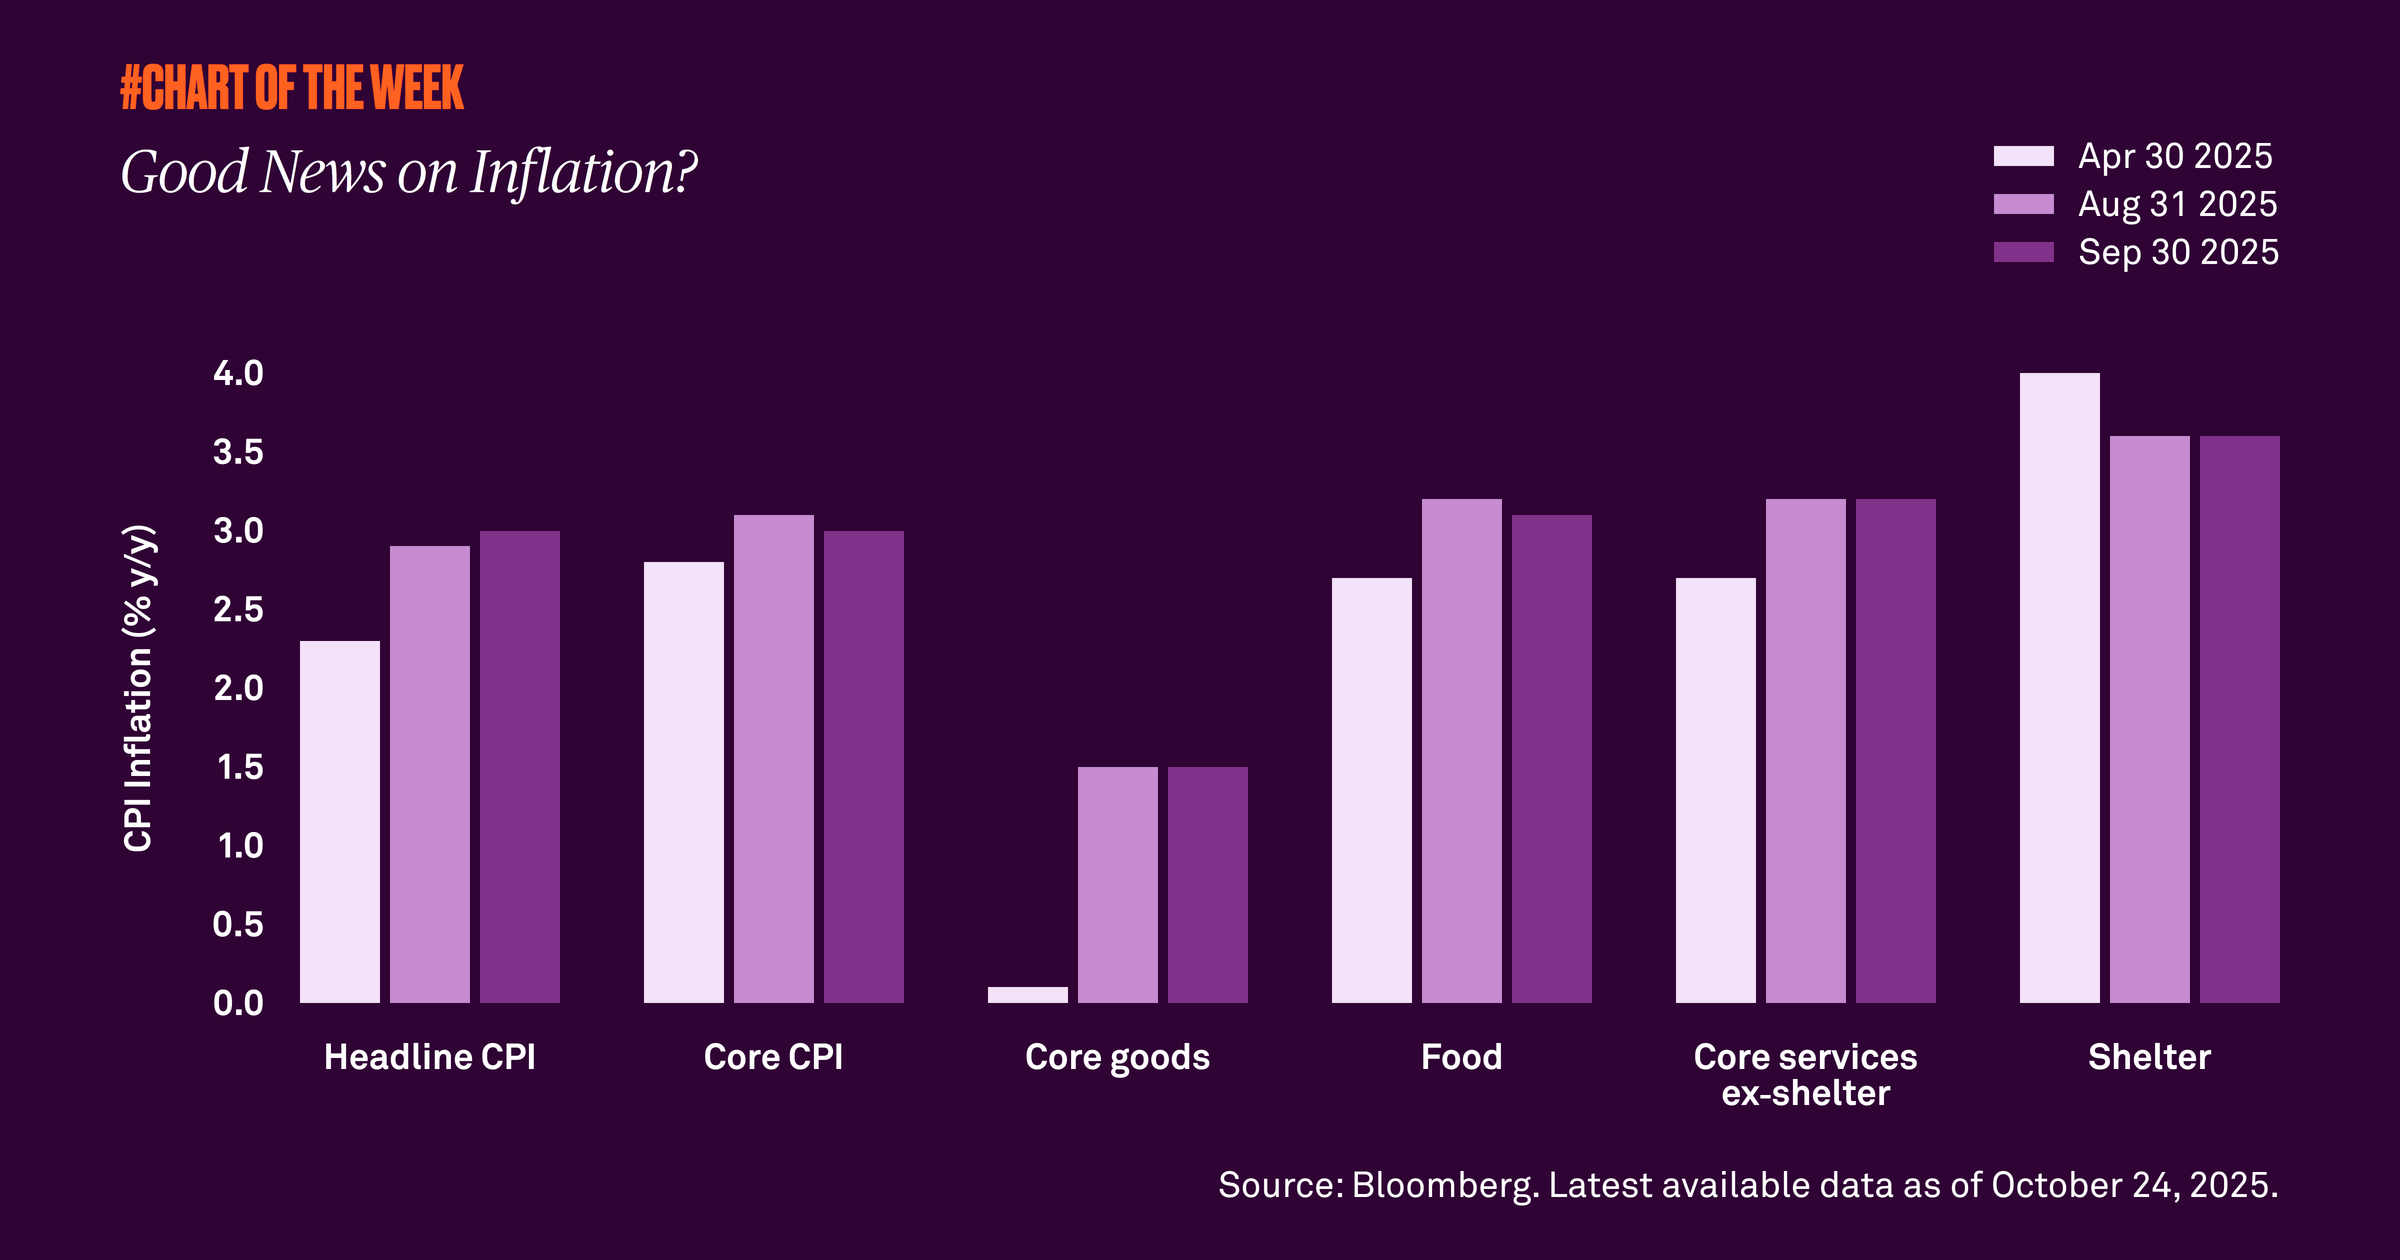

Last week’s Consumer Price Index (CPI) report, a widely used indicator of inflation in the U.S. economy, showed modest growth from 2.9% on an annual basis in August to 3% in September. Yet, the number came in below analysts’ expectations, helping to allay fears of rising inflation. Consequently, the market ended the week higher.

Though the inflation reading was slightly higher than in August, a look at underlying components is encouraging. Core goods, food and core services ex-shelter have risen since April, but appear to have peaked with readings either unchanged or lower in September. Importantly, shelter, which accounts for 35% of CPI, continues to slow, helping to stabilize inflation.

There is the question of what the impact of tariffs will be on inflation once all potential deals are in effect, but we maintain that the result will be a one-time rise in prices rather than a sustained increase. Our view is that inflation will remain within a range of 2.6% to 3.3% through year end. 
RELATED CONTENT
A good outlook for global earnings
Chart of the Week | Macroeconomic

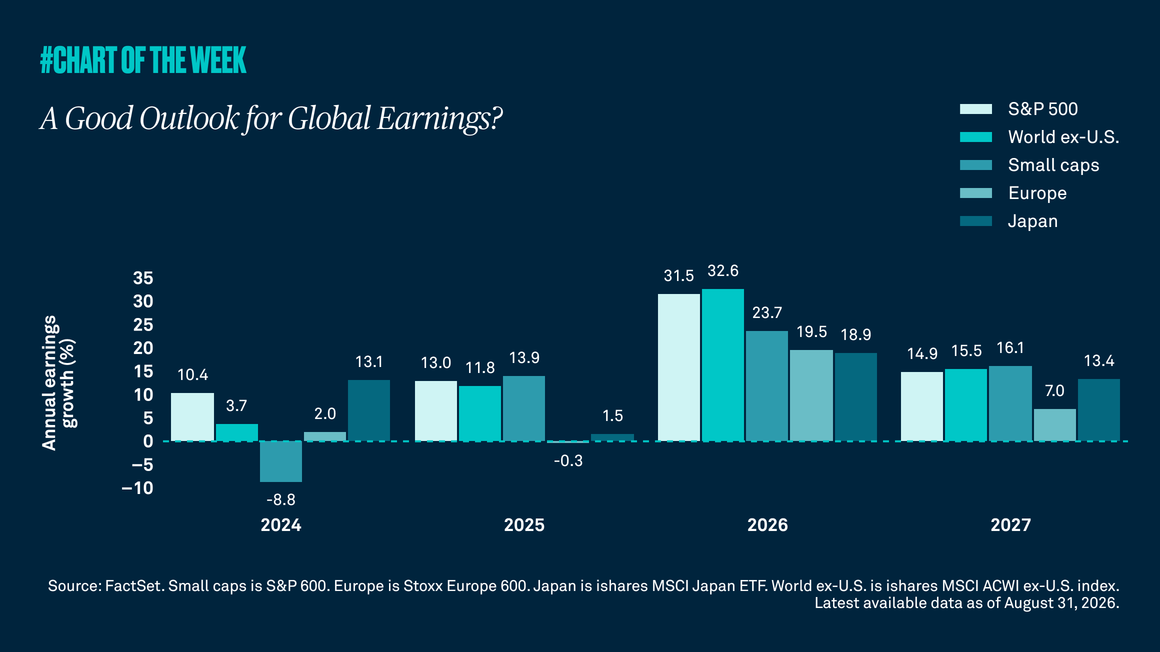
Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

In a real regime shift?
Chart of the Week | Macroeconomic

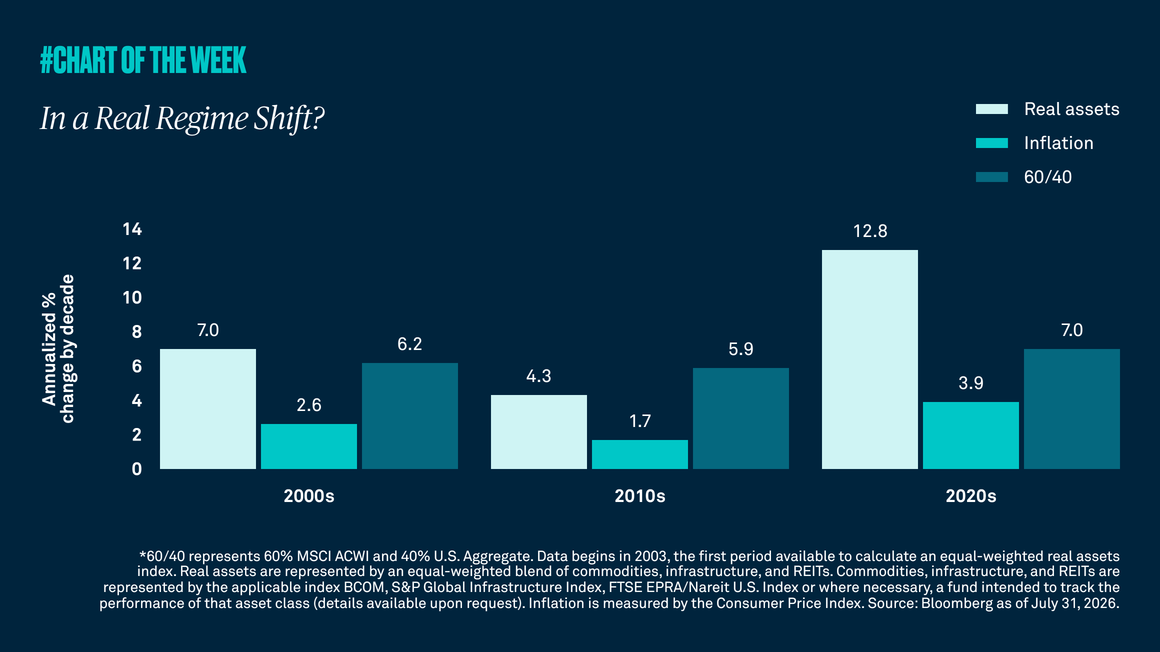
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Getting real with real assets
Chart of the Week | Macroeconomic

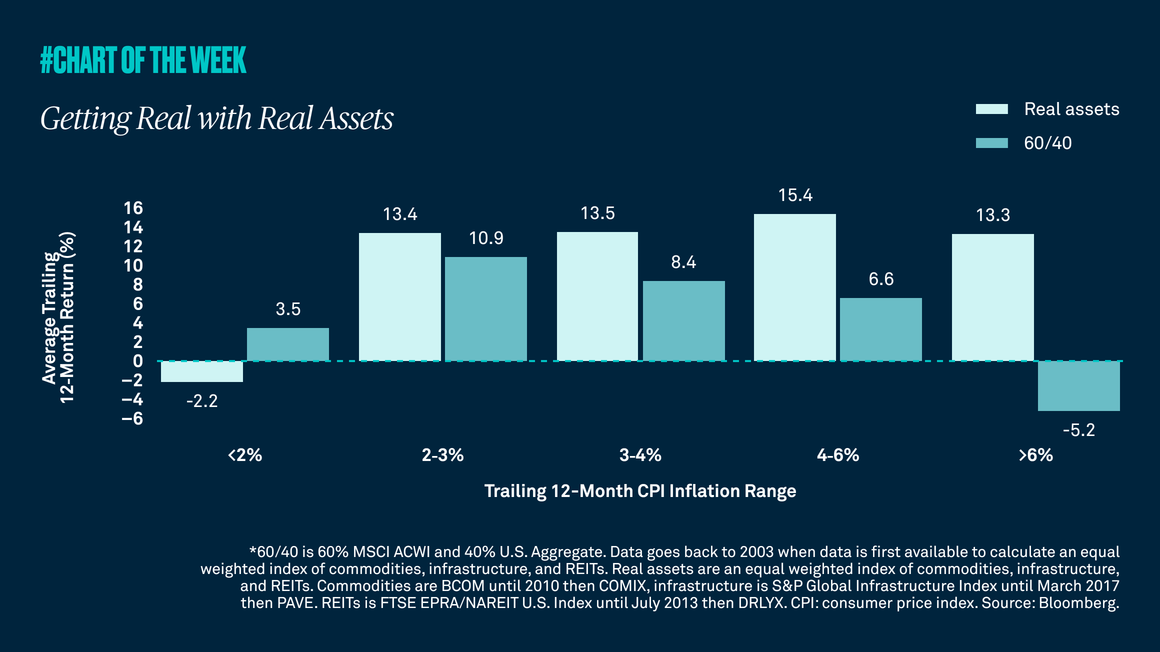
Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Not in a bubble
Chart of the Week | Macroeconomic

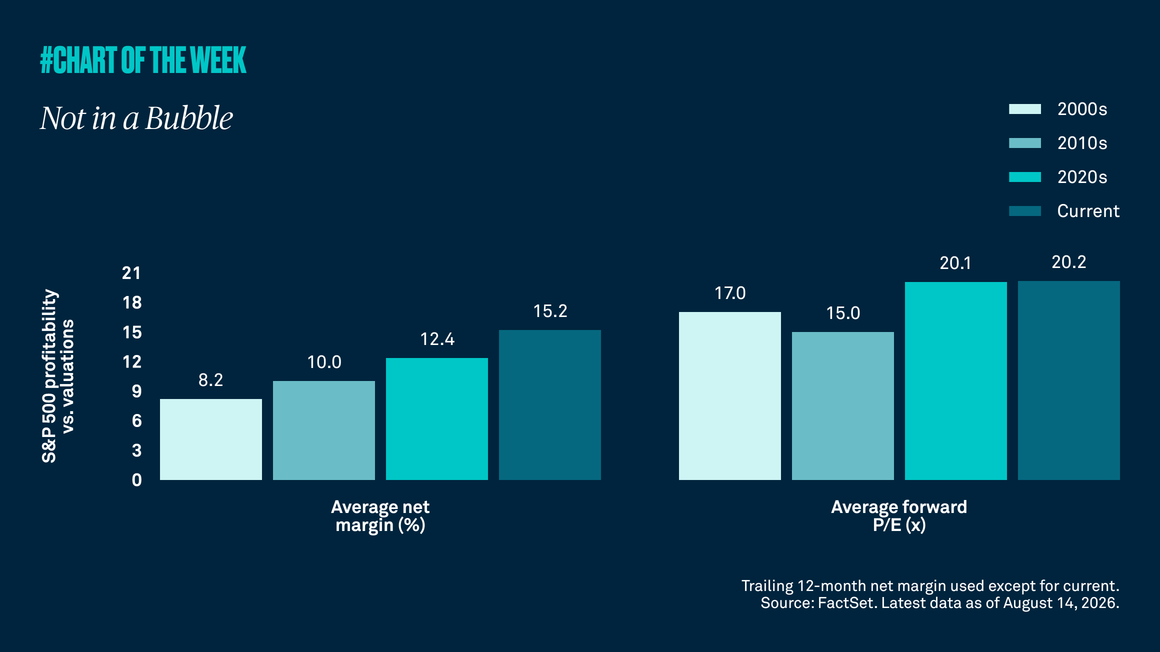
As the S&P 500 approaches all-time highs, there are renewed concerns among investors about elevated valuations. However, historically strong profitability and expected earnings growth appear to support current pricing. In addition, the current S&P 500 price-to-earnings (P/E) ratio is roughly equal to the average since Covid. As a result, we do not view U.S. equities as being in bubble territory and we remain constructive on the asset class.

Gathering data
Disclaimer Not Available

This is a marketing communication