Please ensure Javascript is enabled for purposes of website accessibility Resilient Through Uncertainty
fr
fr
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Resilient through uncertainty

Resilient through uncertainty

U.S. policy uncertainty has remained elevated and consumer sentiment has weakened. Even so, the economy has stayed resilient, and because growth has held up better than sentiment and headlines suggest, we continue to forecast 2% U.S. growth in 2026, in line with trend.
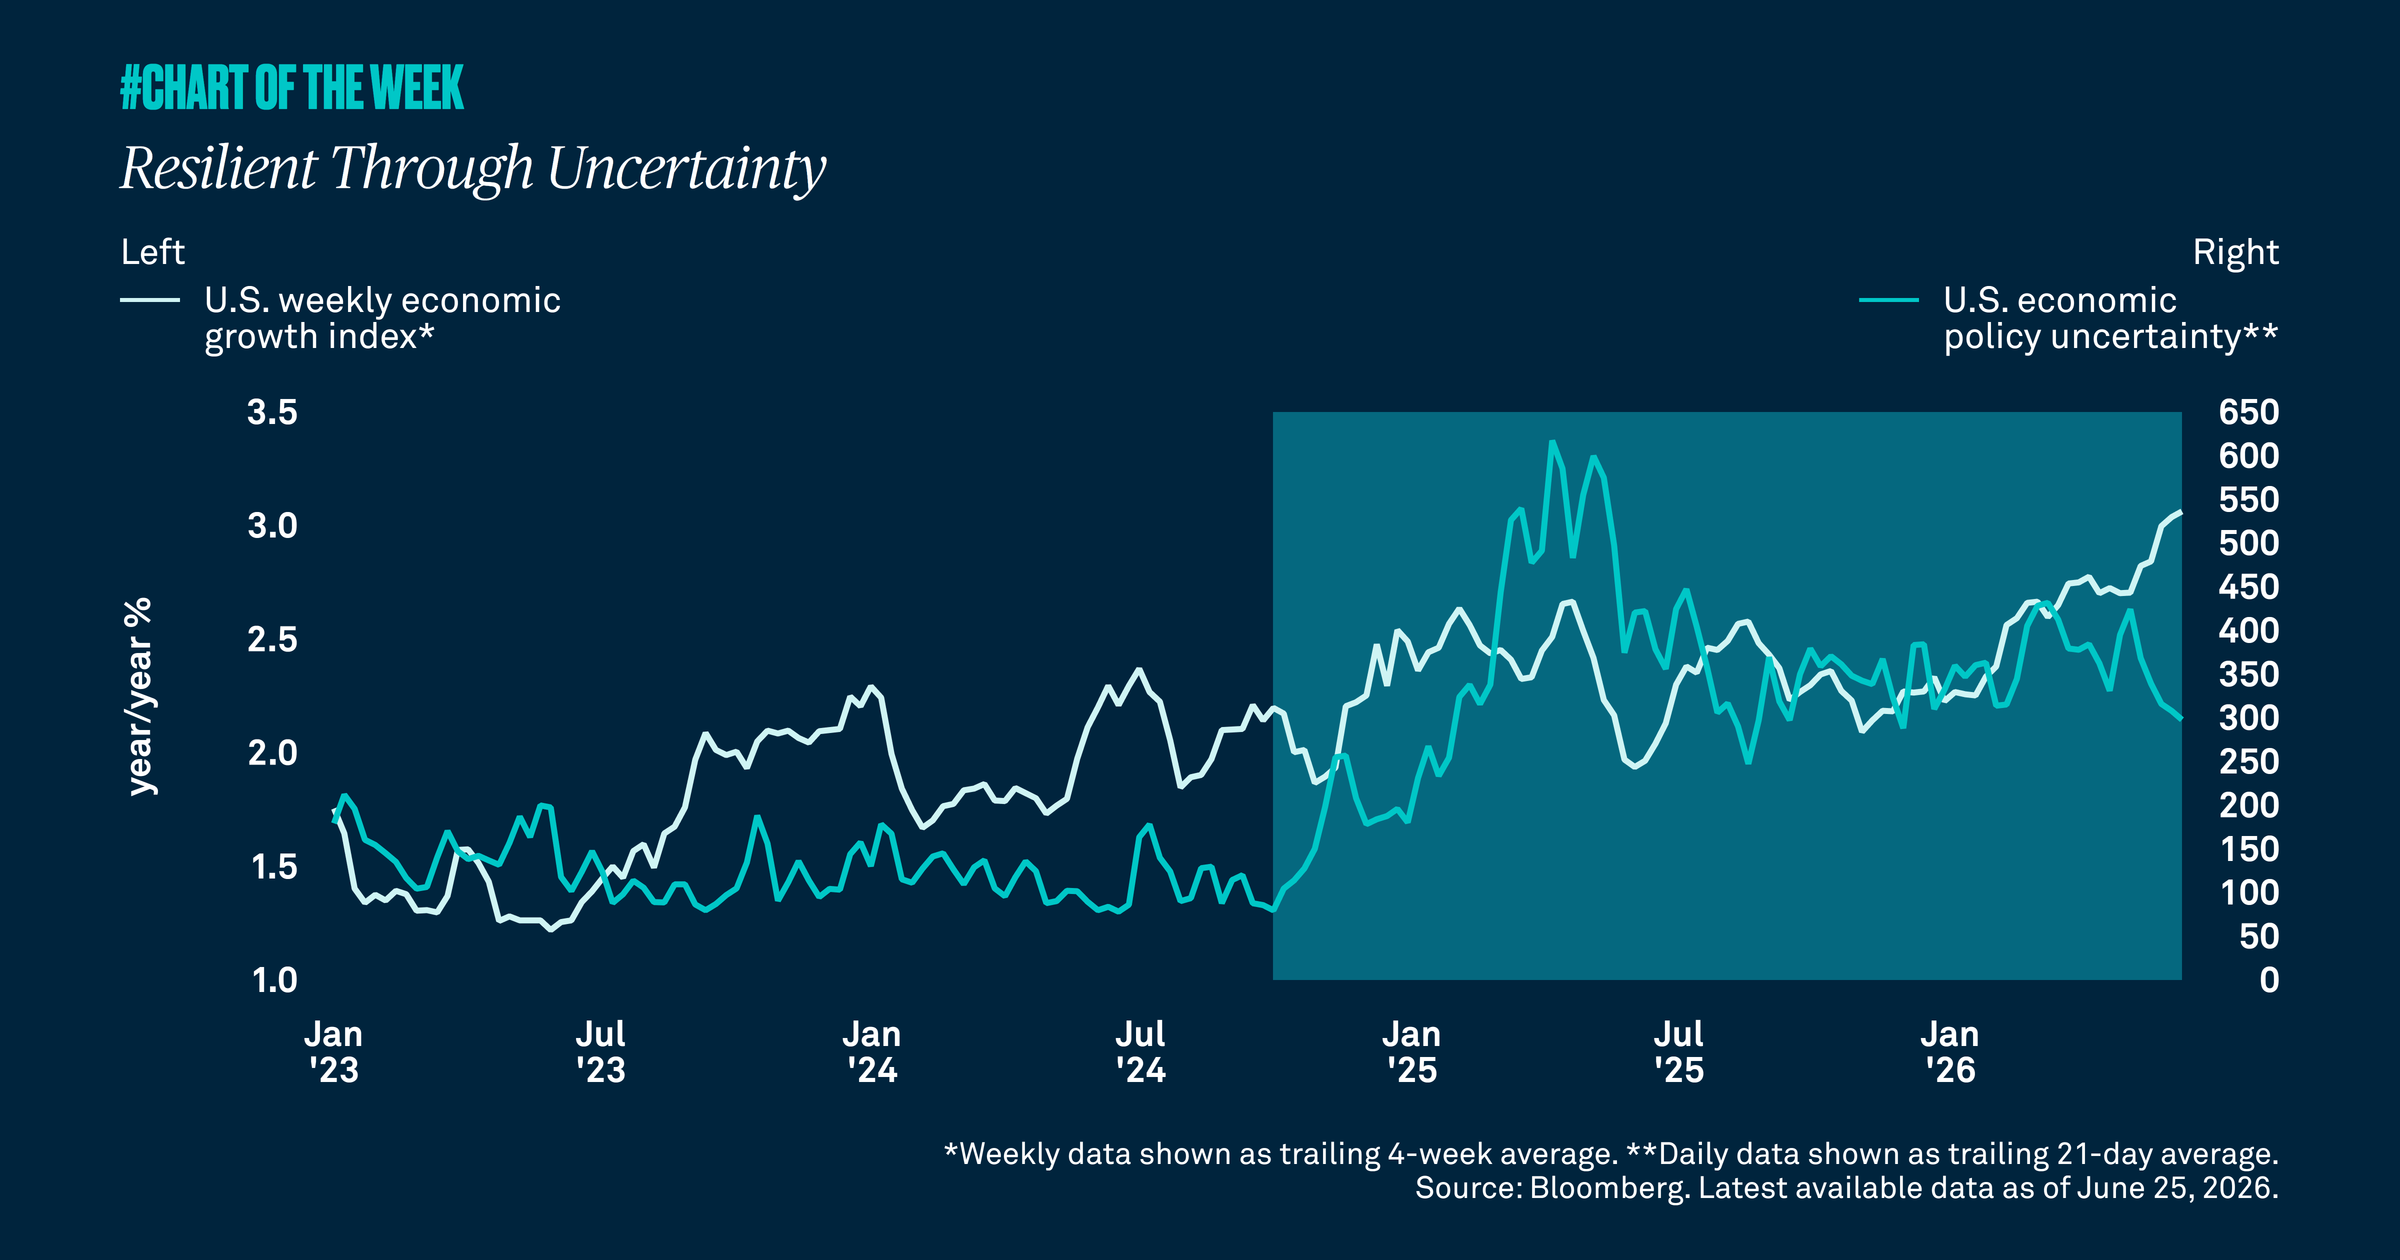

U.S. policy uncertainty — a dependable catalyst for investor anxiety — has remained elevated in recent years, with the Economic Policy Uncertainty Index running well above its long-run average. At the same time, consumer sentiment has deteriorated amid fears of a growth slowdown, which have prompted a reassessment of the outlook for risk assets.

Still, the economic backdrop has remained notably resilient — stronger than many investors and analysts expected — despite policy shocks like tariff changes and government shutdowns.

While the noise around the growth narrative has been loud, it has still been mostly noise. Policy uncertainty and investor unease have been real, but the economy has continued to absorb both. As a result, we reiterate our growth forecast for 2026 of 2%, in-line with trend.
AUTRES ARTICLES ASSOCIÉS
What happens on bad days?
Chart of the Week | Macroéconomique

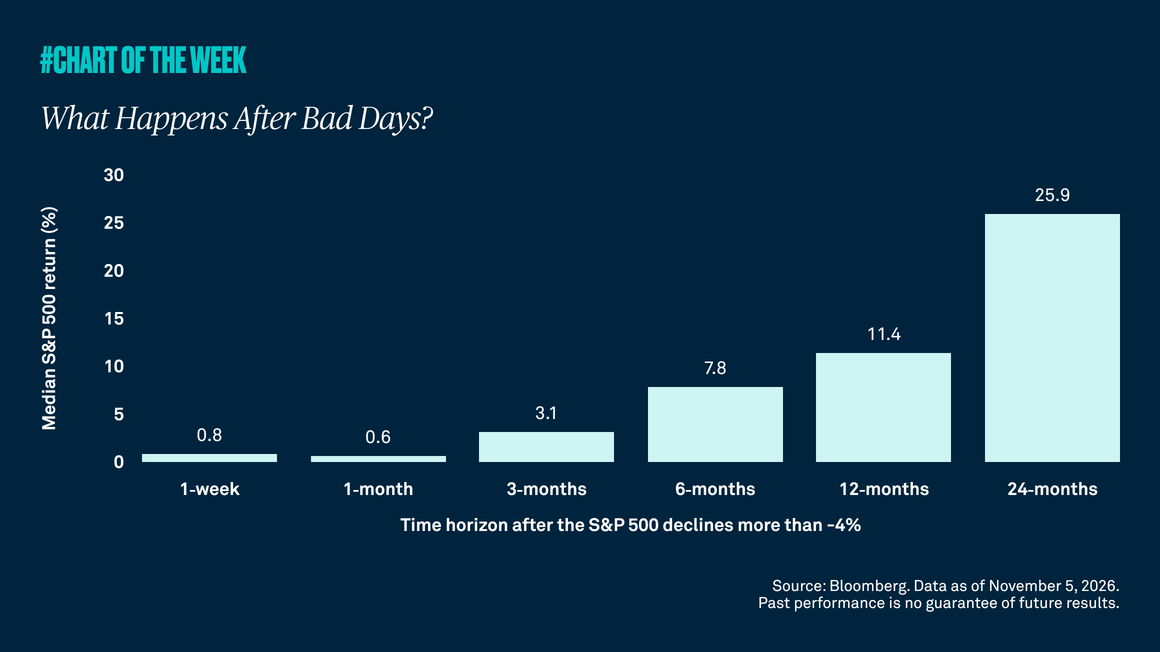
The recent one-day equity selloff reflected weaker sentiment amid election uncertainty and concerns that slower artificial intelligence spending could weigh on growth and earnings. Still, pullbacks of this magnitude have often been followed by solid returns, and we remain constructive given the economy’s resilience and AI’s long-term potential.

Play the long game
Chart of the Week | Macroéconomique

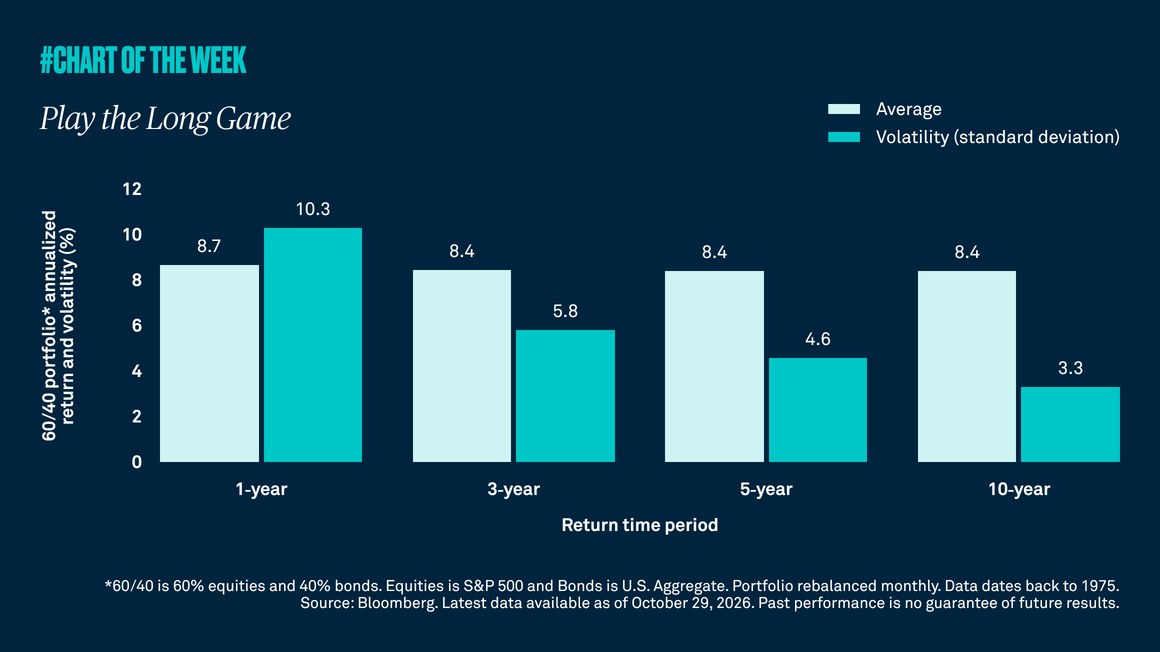
When it comes to investing, time matters. While headlines and short-term perspectives can lead investors to try and time the market, investors have historically been rewarded by playing the long game. Rather than overreacting to market noise, investing over longer time periods can help smooth the ride without sacrificing returns. The lesson: stay diversified and invested for the long term.

Contained contagion?
Chart of the Week | Macroéconomique

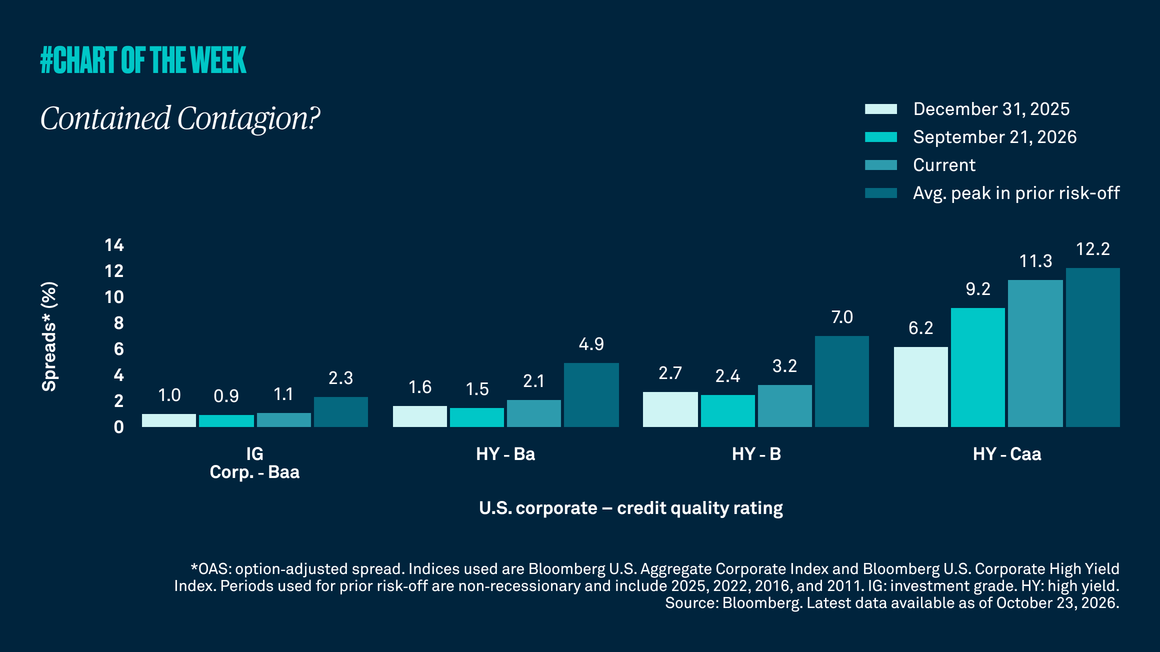
U.S. high yield credit spreads have widened year to date, reflecting greater investor caution about perceived default risk. The move also raises concerns about possible credit contagion. However, because spread widening has been concentrated in the lowest-quality issuers rather than higher-quality issuers, we don’t anticipate broader market stress.

Can the bull run in corporate margins continue?
Chart of the Week | Macroéconomique

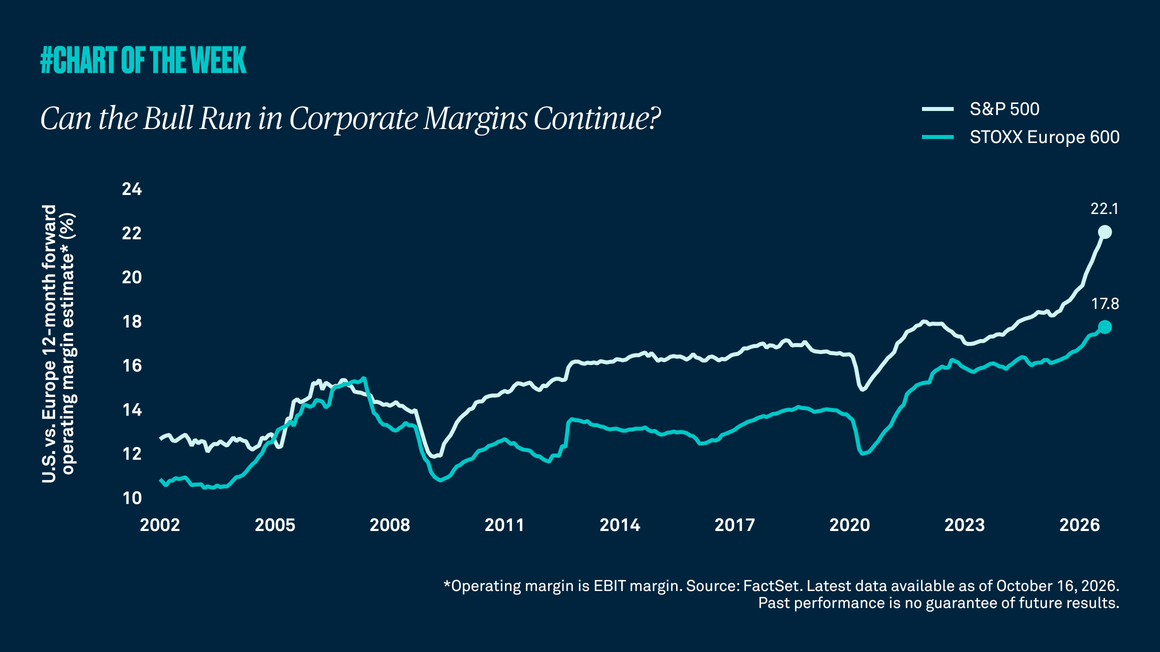
Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?

Gathering data
Disclaimer Not Available

Ce document constitue une communication marketing