Please ensure Javascript is enabled for purposes of website accessibility A Good Outlook for Global Earnings
fi
en
intermediary
intermediary
false
true
Gathering data
Disclaimer Not Available

A good outlook for global earnings

A good outlook for global earnings

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.


This year has been notable for the strength of global earnings growth. In the U.S., S&P 500 earnings are expected to rise 31.5% in 2026, up sharply from 13% in 2025. The story does not end there. Earnings growth has improved meaningfully across Europe, Japan and other major markets, with each region expected to deliver profit growth well above last year’s pace.

Though global earnings momentum is likely to slow in 2027 from this year’s unusually strong levels, growth may still remain above historical averages. That should matter for markets, especially as the earnings story has broadened beyond a narrow group of U.S. stocks. Corporate margins continue to rise, and while artificial intelligence-related capital spending has been a major driver of growth, the broader market remains fundamentally solid.

We do expect volatility to increase as markets contend with a range of uncertainties, including higher U.S. Treasury yields, the approaching midterm elections and ongoing geopolitical tensions. Still, we view the combination of above-average earnings growth and broad-based global participation as a clear positive for the forward outlook for global equities. After all, earnings growth remains the key driver of long-term market returns. We therefore remain constructive.
RELATED CONTENT
Play the long game
Chart of the Week | Macroeconomic

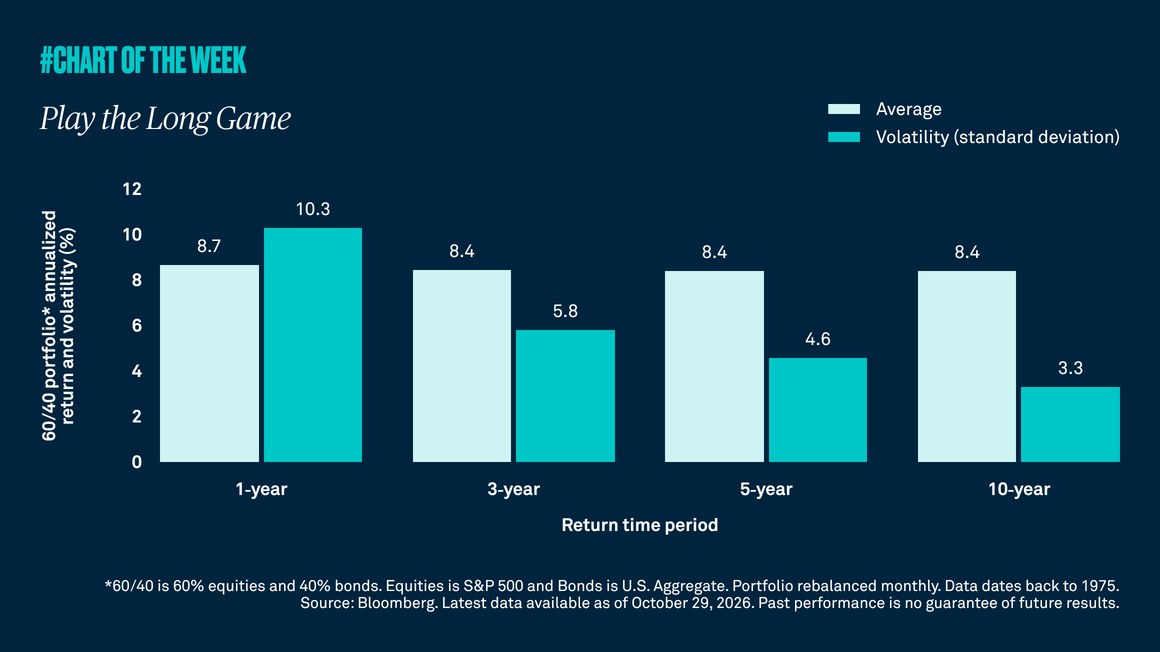
When it comes to investing, time matters. While headlines and short-term perspectives can lead investors to try and time the market, investors have historically been rewarded by playing the long game. Rather than overreacting to market noise, investing over longer time periods can help smooth the ride without sacrificing returns. The lesson: stay diversified and invested for the long term.

Contained contagion?
Chart of the Week | Macroeconomic

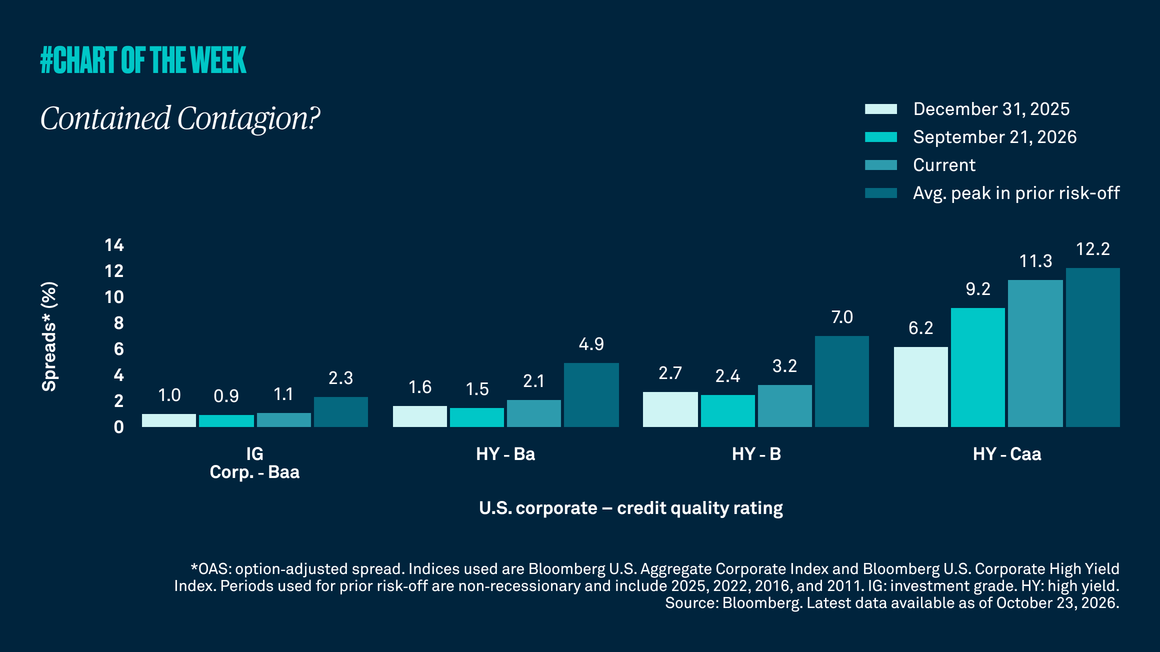
U.S. high yield credit spreads have widened year to date, reflecting greater investor caution about perceived default risk. The move also raises concerns about possible credit contagion. However, because spread widening has been concentrated in the lowest-quality issuers rather than higher-quality issuers, we don’t anticipate broader market stress.

Can the bull run in corporate margins continue?
Chart of the Week | Macroeconomic

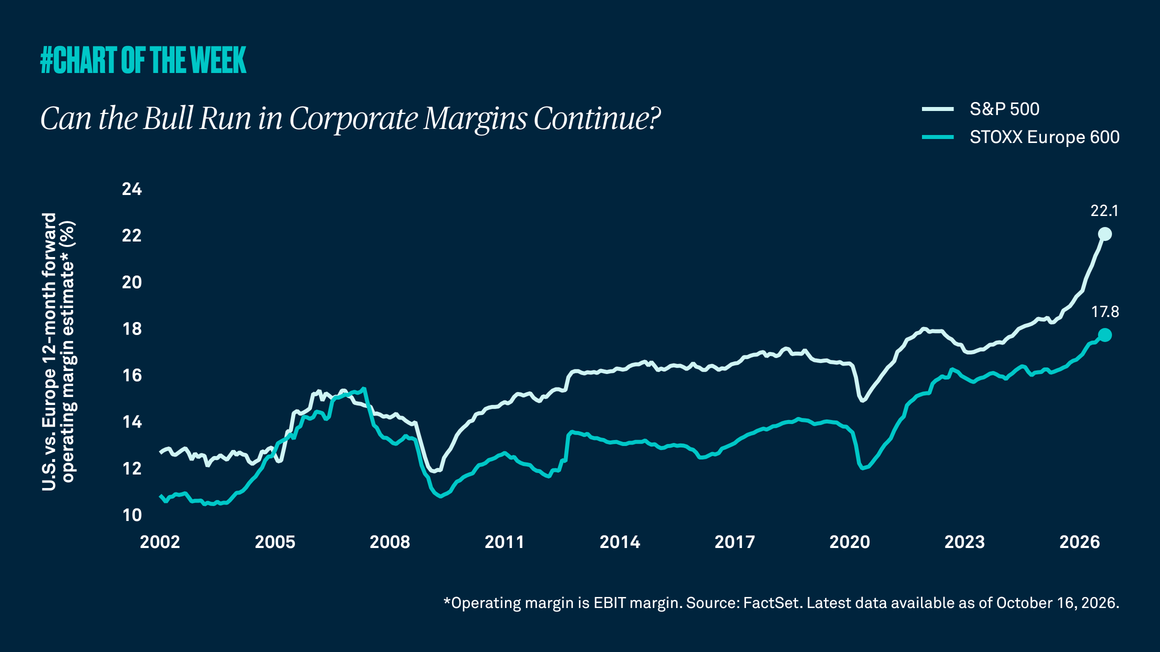
Higher inflation and elevated interest rates typically weigh on corporate profitability, yet corporate margins continue to climb to record highs. While that strength is evident both in the U.S. and abroad, U.S. outperformance versus Europe is now the widest on record. Stronger margins have helped contribute to better-than-expected earnings and reinforce U.S. equity leadership. The question now is whether that strength can persist?

Higher yields, but lower sensitivity
Chart of the Week | Macroeconomic

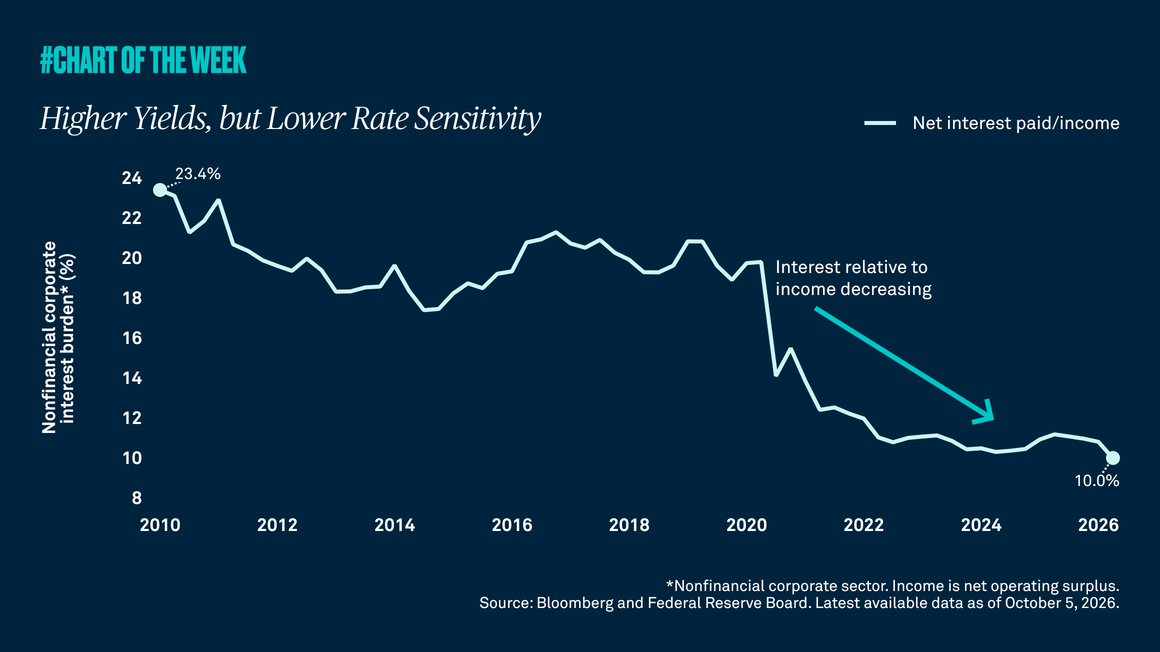
Higher interest rates have become a frequently cited risk to corporate earnings and the economy. The conventional thinking is straightforward: when borrowing costs rise, companies face higher interest expenses, profits come under pressure, and economic growth slows. While there is truth to that relationship, the current cycle may differ from investors’ expectations.

Gathering data
Disclaimer Not Available

This is a marketing communication