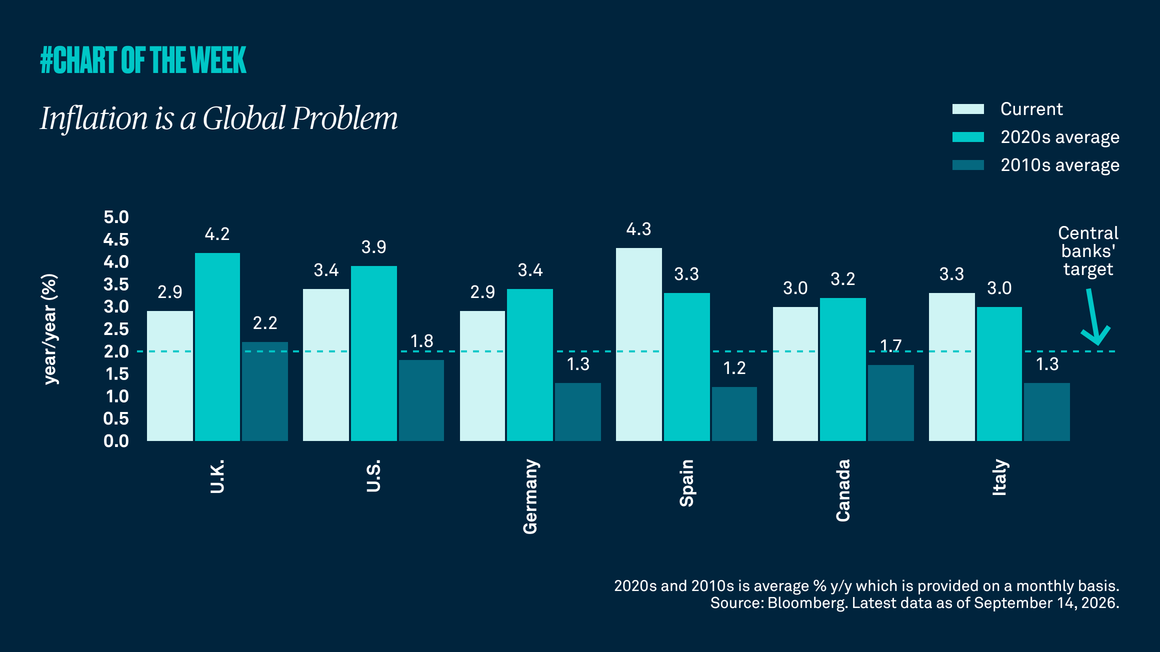
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.
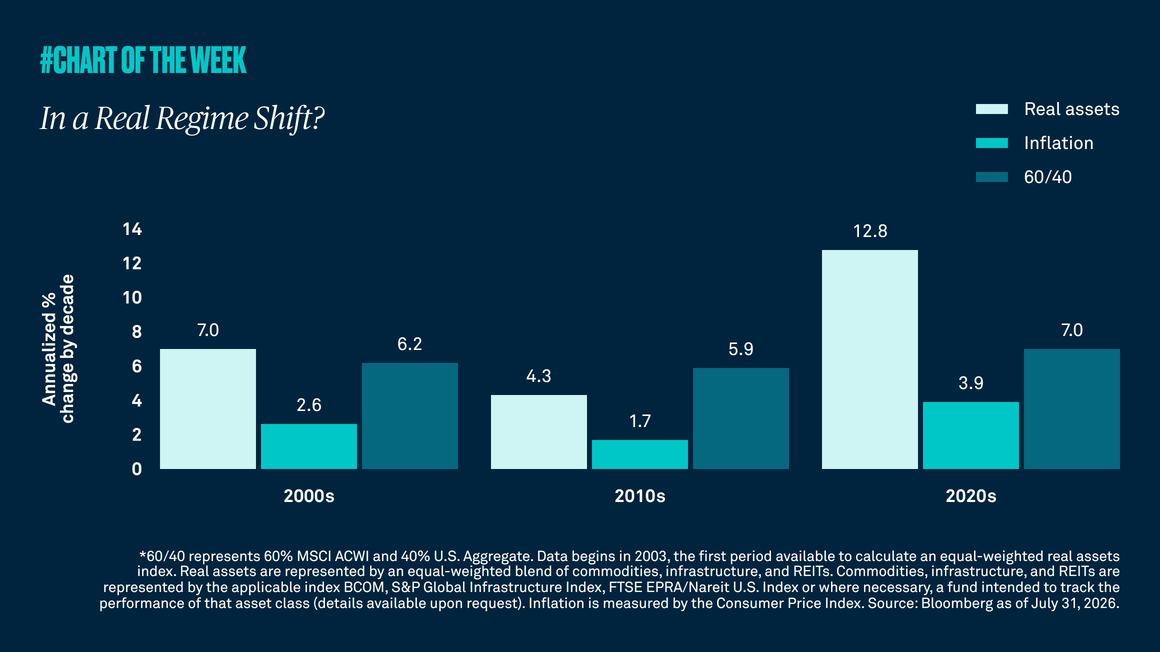
For much of the 2000s, inflation was broadly contained, averaging around 2.6% in the first decade and falling below 2.0% during the 2010s following the global financial crisis. Since the pandemic, however, inflation has shifted into a meaningfully higher range, with annualized inflation running at roughly 4% this decade — more than double the pace of the prior decade. In our view, various factors including event-driven spikes, such as COVID and energy-driven supply shocks, as well as deglobalization, suggest that inflation is likely to remain structurally higher than it was in the years preceding COVID.
As inflation has moved higher, real assets have meaningfully outperformed. Real assets have generated annualized returns of 12.8% this decade, compared with approximately 7% for a traditional 60/40 portfolio, while returns for real assets are roughly three times the level achieved in the 2010s. We believe this relative outperformance reflects more than a short-term cyclical adjustment and instead points to a long-term trend.
Importantly, the case for real assets is not driven by inflation alone. We also see support from a durable capital expenditure cycle reinforced by several powerful secular trends, including infrastructure investment, increased defense spending, onshoring across industries and the continued buildout of artificial intelligence-related capacity.
Given these factors, it’s important for investors to review their portfolio mix and consider including real assets as a way to enhance diversification, improve return potential and position for a structurally higher inflation environment.