Please ensure Javascript is enabled for purposes of website accessibility Bubble or Is This Market Different?
dk
en
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Bubble or is this market different?

Bubble or is this market different?

The S&P 500 is up 14% year to date after gaining more than 20% annually over the past couple of years. Valuations are certainly elevated, but we believe the market is in a new world where higher multiples are normal rather than stretched.
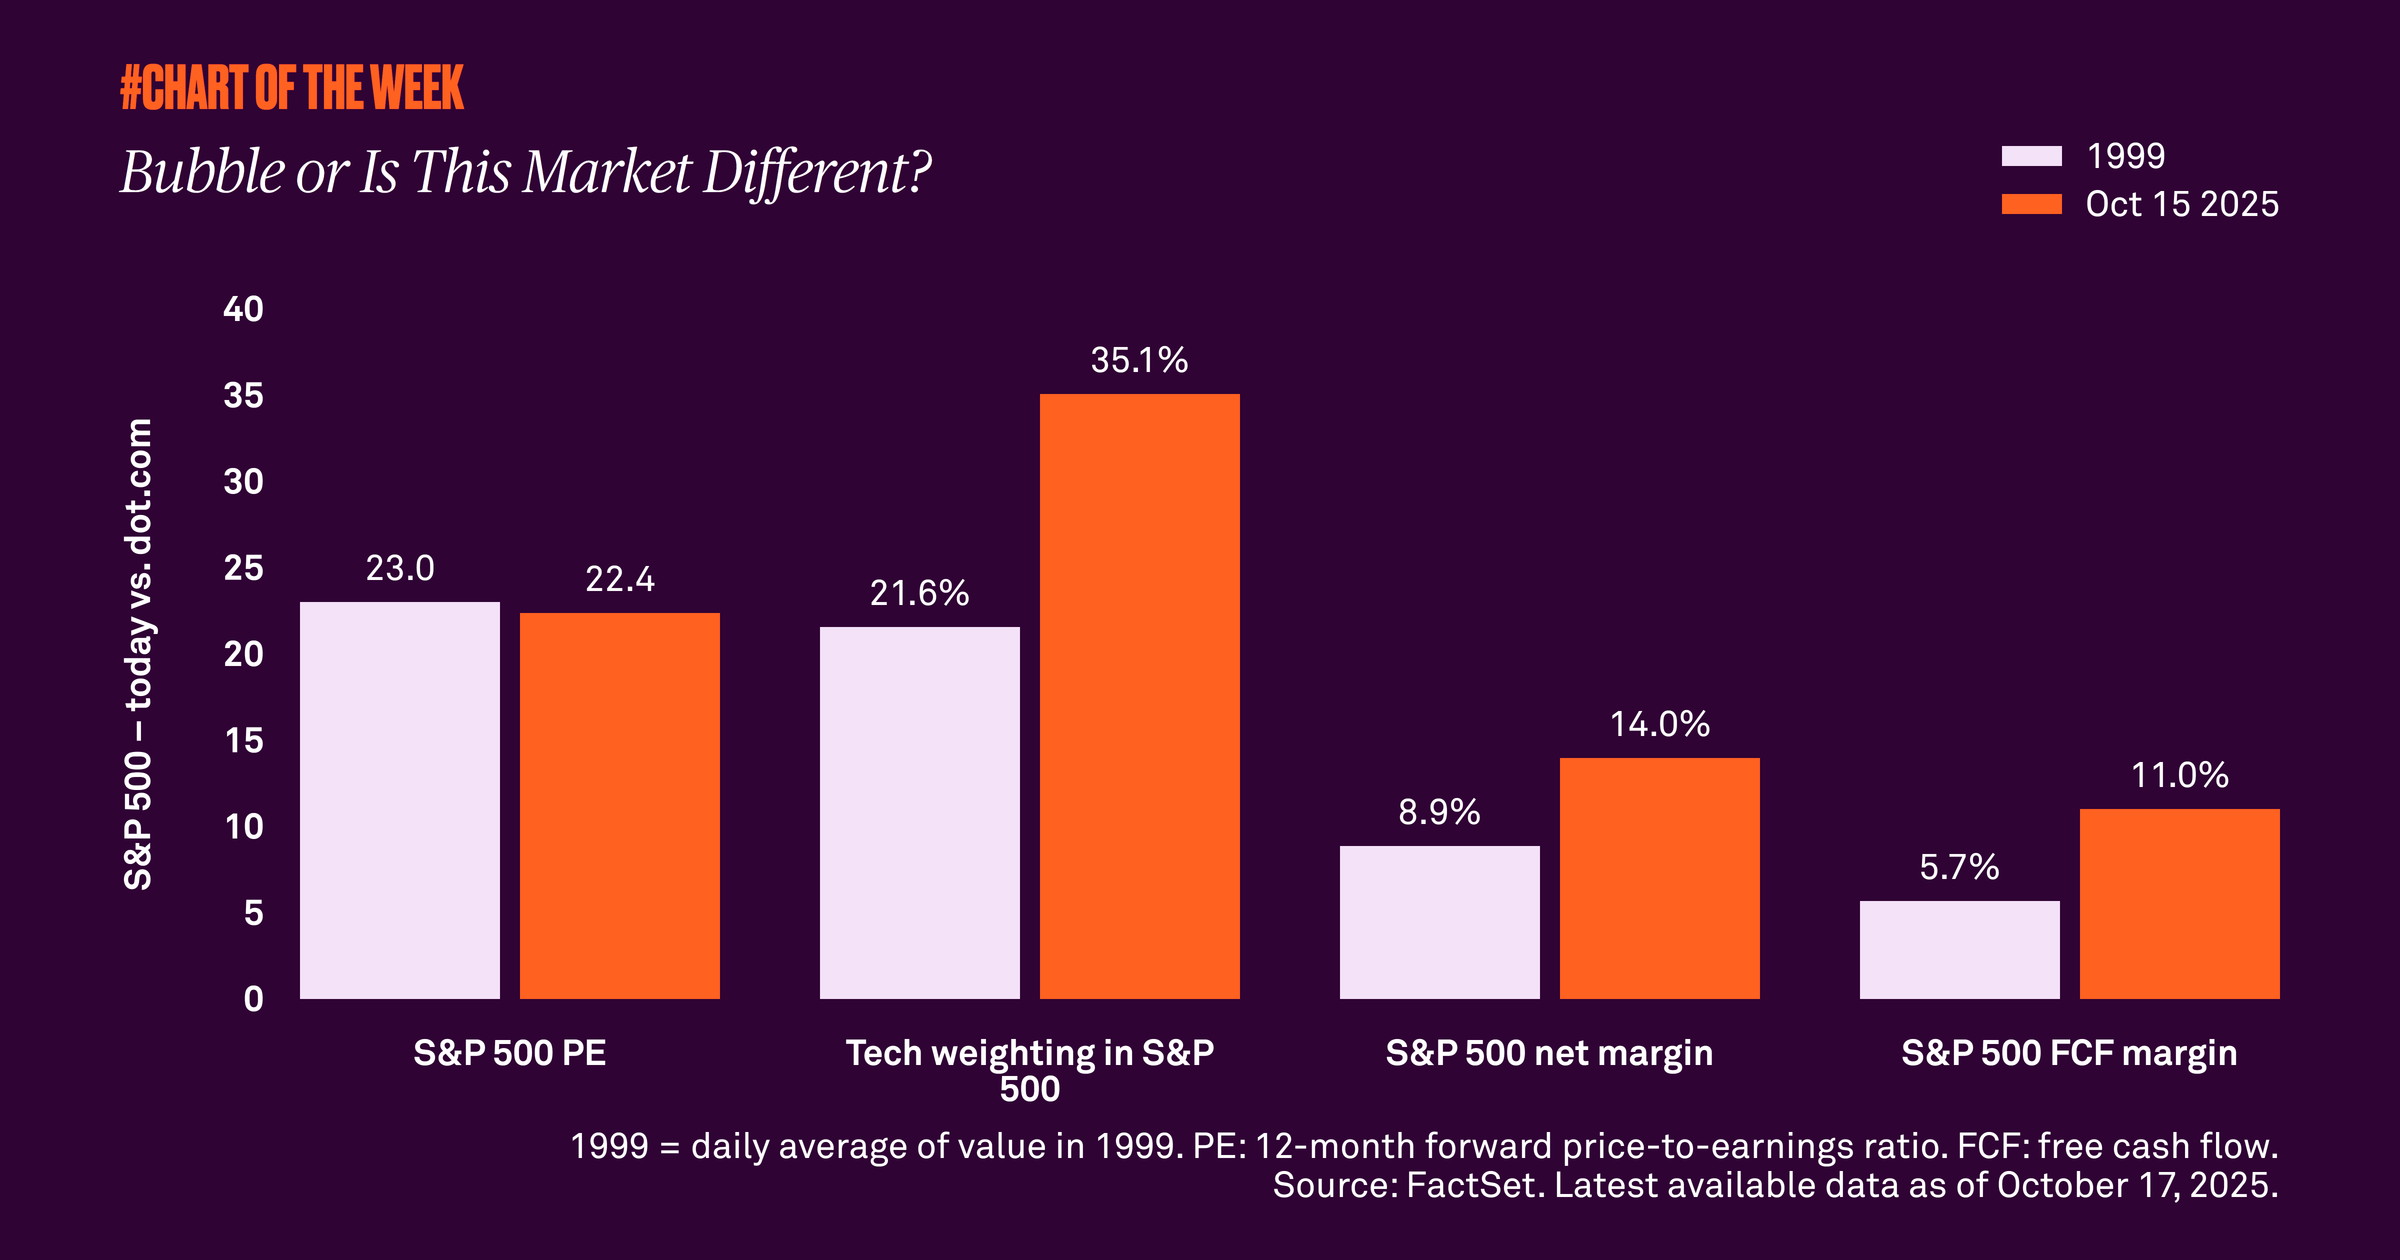

The S&P 500 is up 14% year to date after gaining more than 20% annually over the past couple of years. Some investors are speculating that we are amidst another tech bubble because technology companies have been leading the market higher. However, we believe the market is in a new world where higher multiples are normal rather than a sign of stretched valuations.

For some context, the S&P 500’s 12-month future price-to-earnings (PE) ratio is currently 22.4x, notably greater than the 16.8x average since 1996. While the index appears expensive relative to history, we believe this higher-multiple environment is justified. A key reason is the improved profitability of the market; net margins are 1.6x higher at 14% compared to the dot.com era. Similarly, free cash flow margins are 1.9x higher at 11%. In addition, the weight of the technology sector, which has the highest PE, has increased 1.6x since the dot.com era to 35% of the index. This naturally increases the PE of the index.

The changing market structure with the increased size of tech and the broader index’s higher profitability have led to higher PEs compared to long-term averages. In our view, the disconnect between current valuations and historical averages reflects a different type of market – not an overvalued one.

So, while we don’t believe the market is in a bubble, we believe that investors’ skepticism is healthy for keeping bull markets intact. Current valuations could consolidate from elevated levels, but we remain constructive on the forward outlook given improving earnings.
RELATED CONTENT
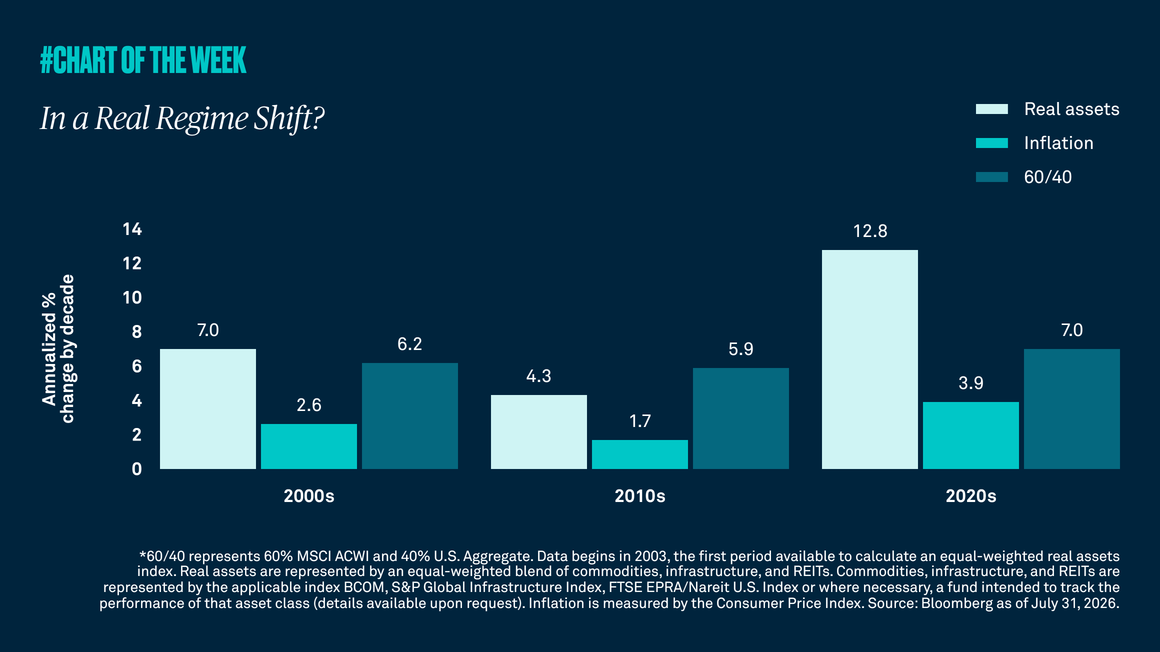
In a real regime shift?
Chart of the Week | Macroeconomic

Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

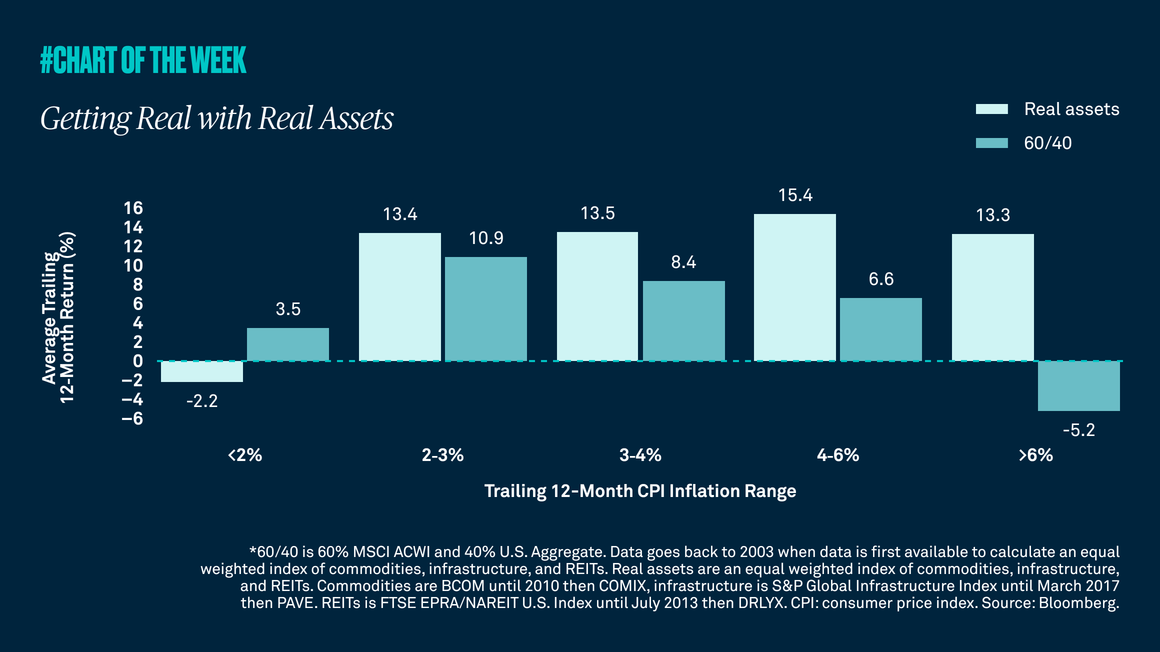
Getting real with real assets
Chart of the Week | Macroeconomic

Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Not in a bubble
Chart of the Week | Macroeconomic

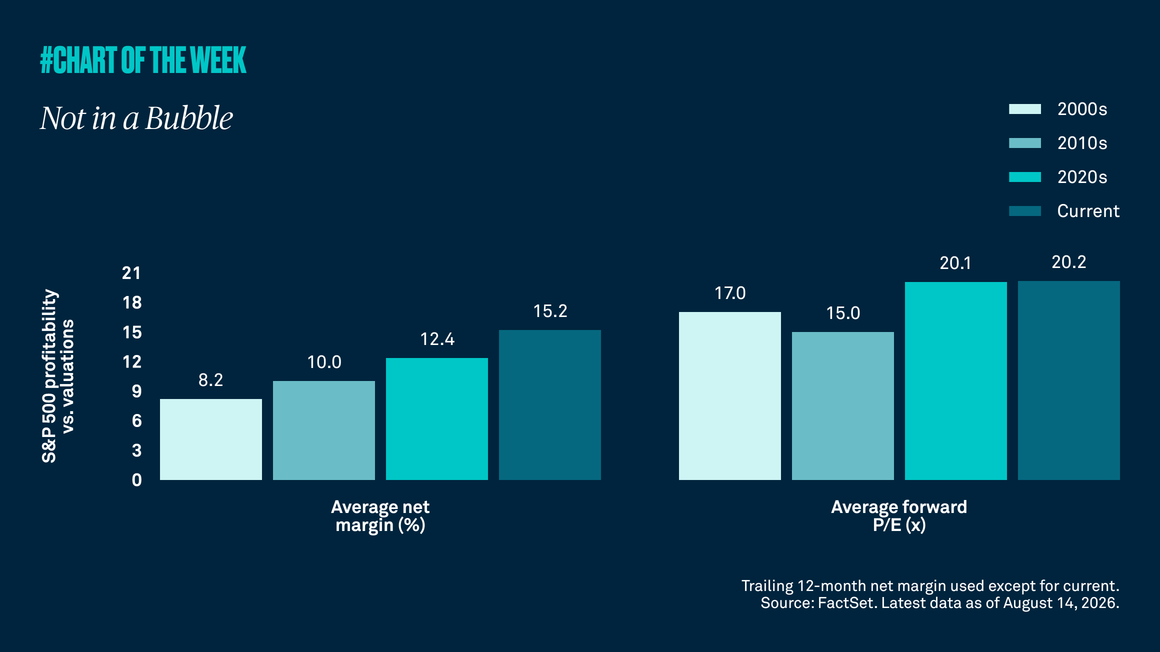
As the S&P 500 approaches all-time highs, there are renewed concerns among investors about elevated valuations. However, historically strong profitability and expected earnings growth appear to support current pricing. In addition, the current S&P 500 price-to-earnings (P/E) ratio is roughly equal to the average since Covid. As a result, we do not view U.S. equities as being in bubble territory and we remain constructive on the asset class.

Is the market rally broadening?
Chart of the Week | Macroeconomic

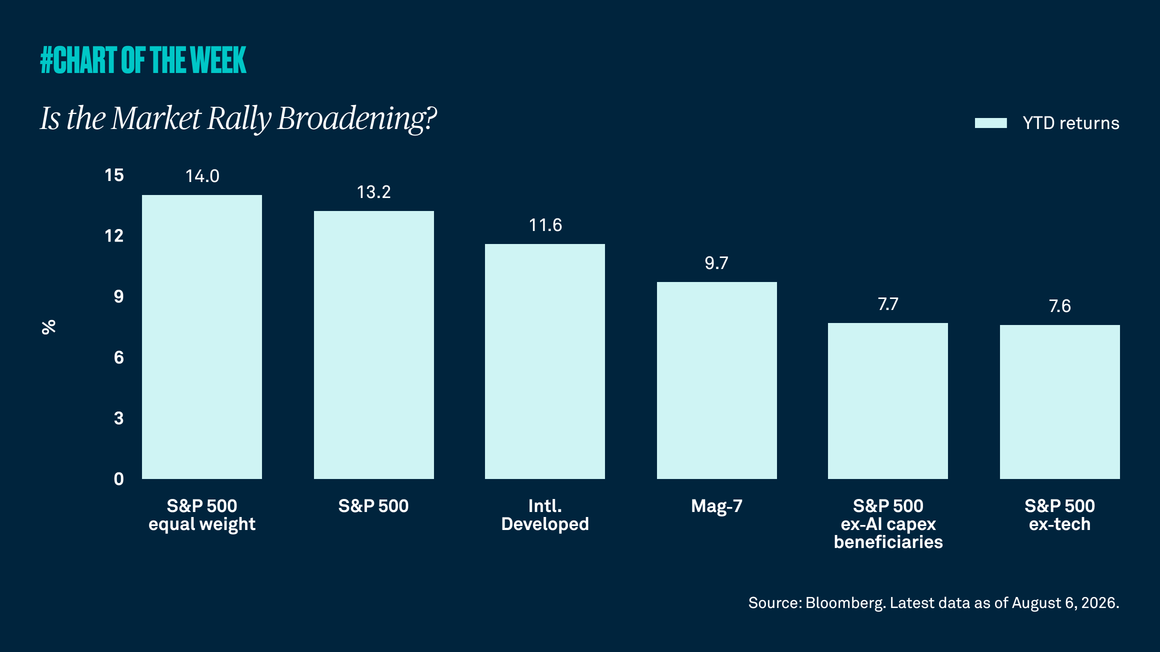
Stocks, as measured by the S&P 500, are up over 13% through early August. The solid gains have been fueled by a resilient economy, steady consumer spending, optimism around artificial intelligence and better-than-expected earnings growth. Still, some investors worry the advance may be too concentrated in technology and that AI-capex monetization may fall short of expectations. A closer look suggests that it is not just tech moving the market higher.

Gathering data
Disclaimer Not Available

This is a marketing communication