Please ensure Javascript is enabled for purposes of website accessibility Signals from spreads
it
it
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Signals from spreads

Signals from spreads

Credit spreads have risen yet remain historically low, reinforcing our view that the oil shock is likely temporary — not a driver of long-term growth concerns.
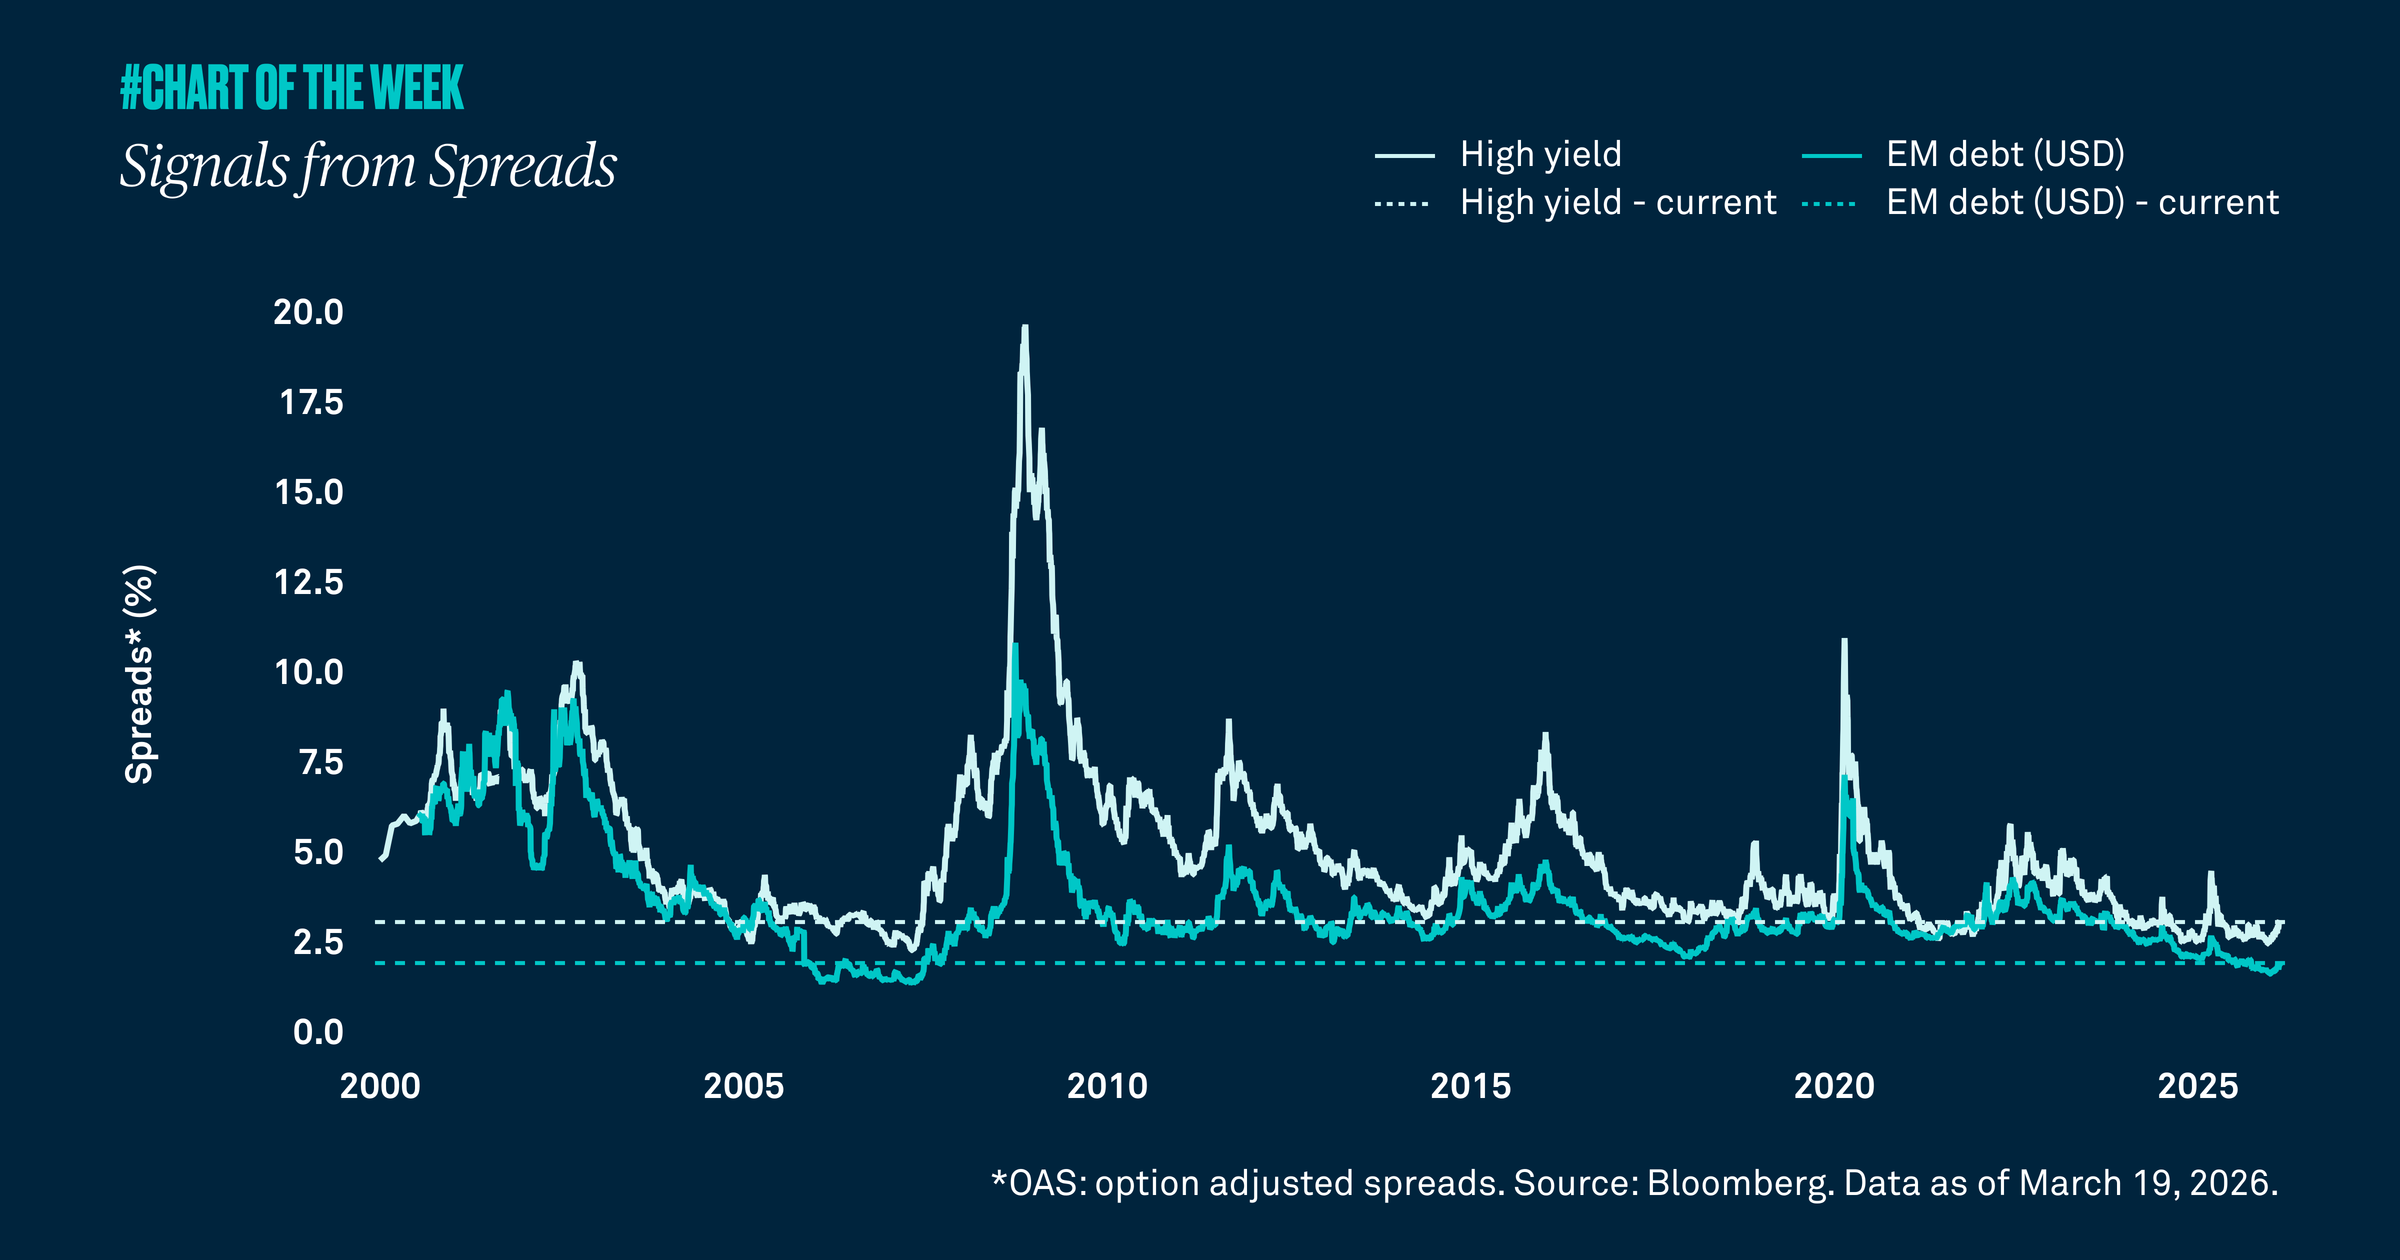

The Middle East conflict continues but key credit spreads remain relatively subdued. Historically, rising credit spreads signal greater risk aversion and concerns about slowing growth. A sustained widening would indicate more persistent growth concerns.

Similar to the equity market, credit spreads suggest the conflict will likely be short-lived. Though U.S. high yield spreads rose 55 basis points (bps) and emerging market debt spreads increased 30 bps in the last two months, these levels are historically low. We agree with the market and believe the oil shock will be temporary. While recent developments from President Trump on potential negotiations could be positive, the situation remains dynamic, and we’ll continue to watch whether credit spreads widen further.
Articoli correlati
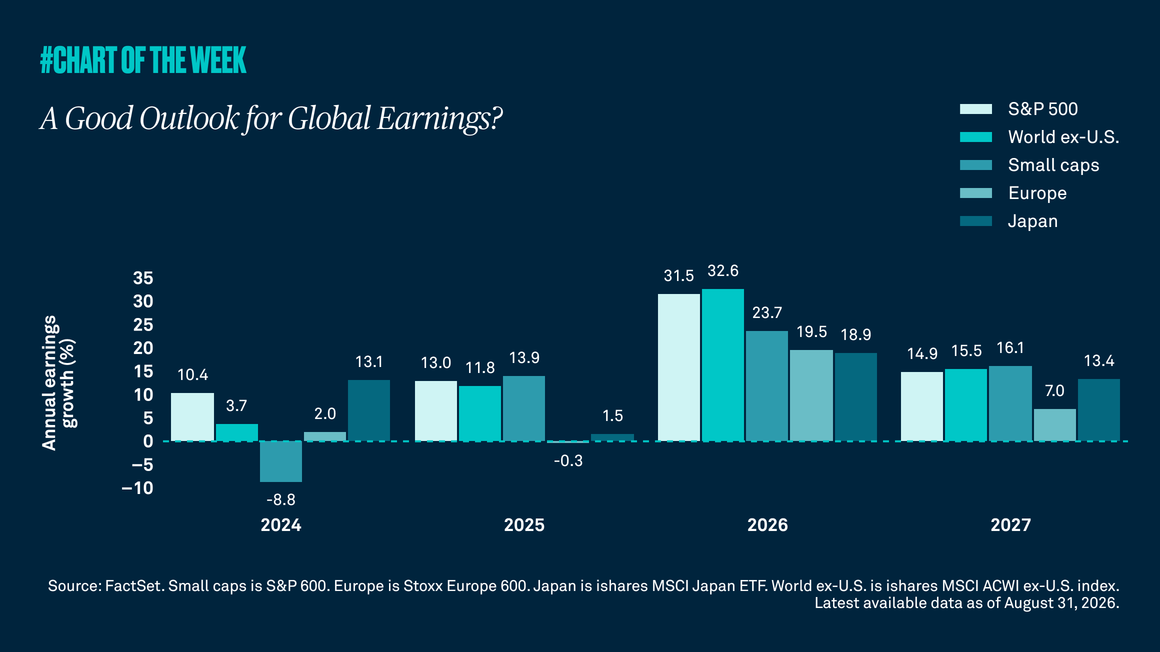
A good outlook for global earnings
Chart of the Week | Macroeconomico

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

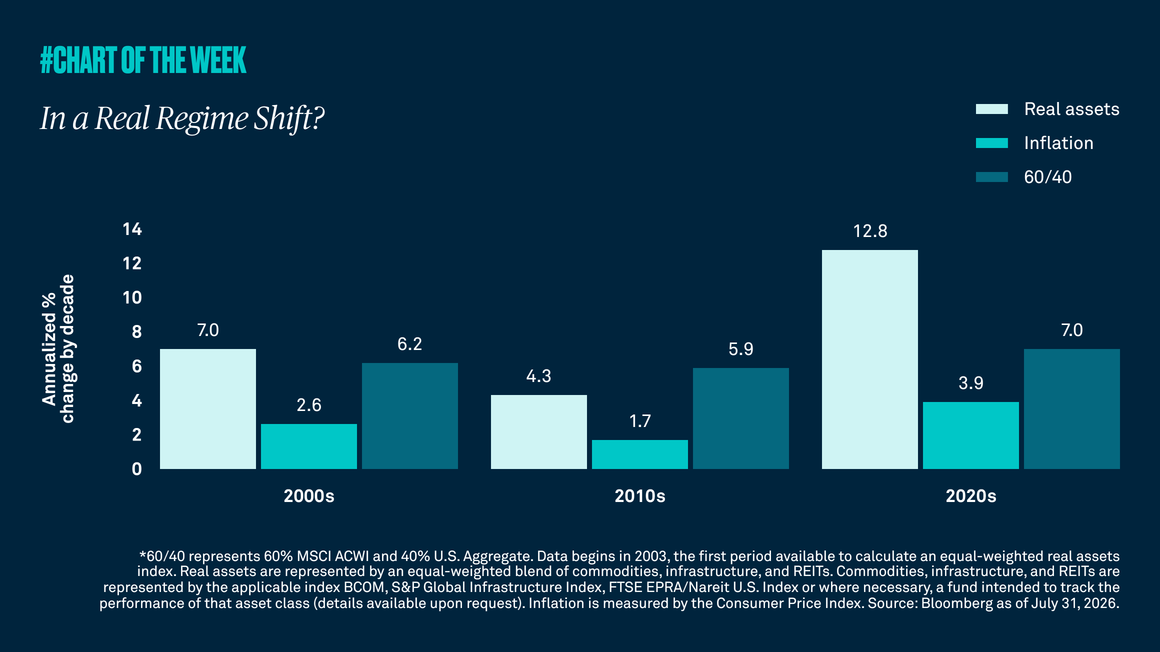
In a real regime shift?
Chart of the Week | Macroeconomico

Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Getting real with real assets
Chart of the Week | Macroeconomico

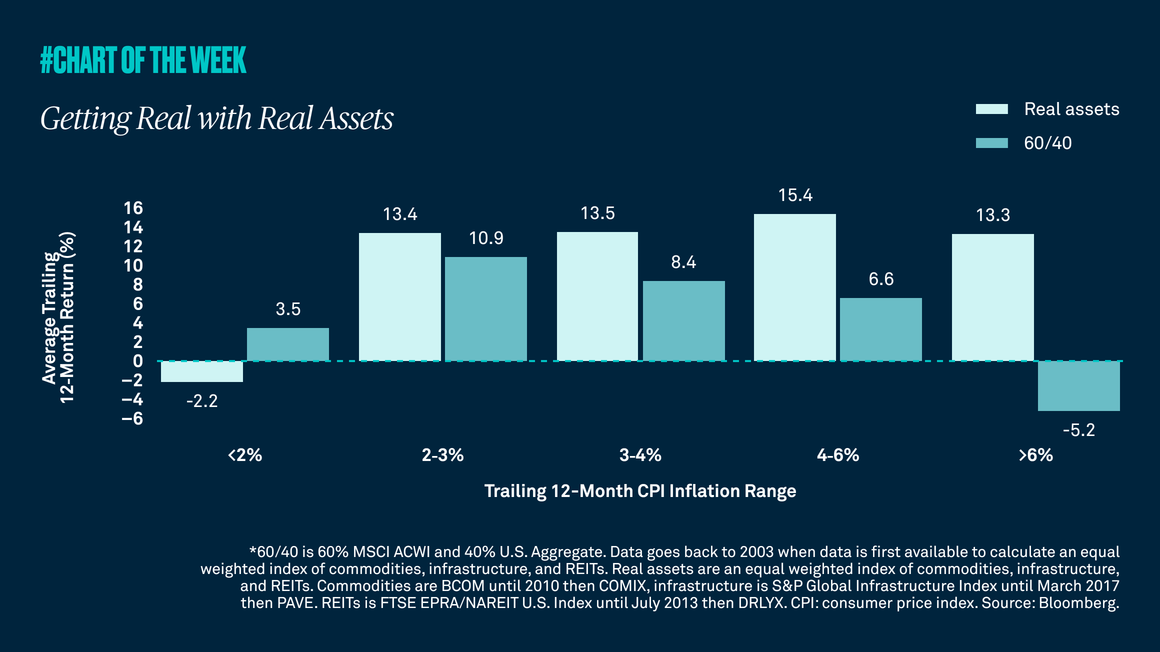
Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Is the market rally broadening?
Chart of the Week | Macroeconomico

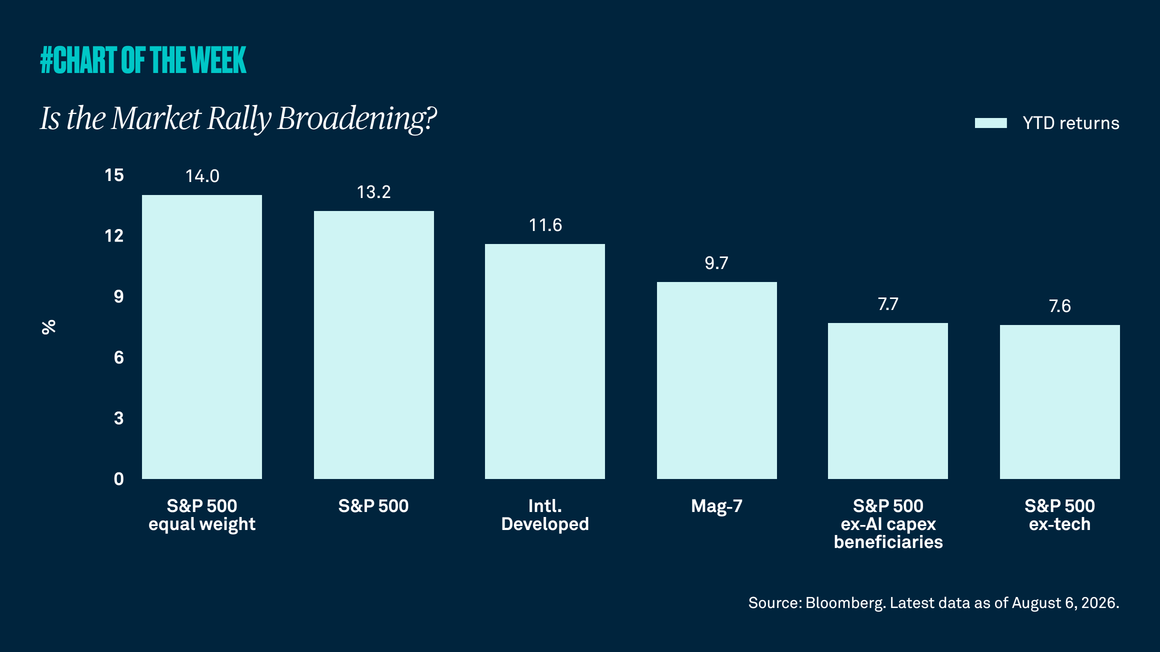
Stocks, as measured by the S&P 500, are up over 13% through early August. The solid gains have been fueled by a resilient economy, steady consumer spending, optimism around artificial intelligence and better-than-expected earnings growth. Still, some investors worry the advance may be too concentrated in technology and that AI-capex monetization may fall short of expectations. A closer look suggests that it is not just tech moving the market higher.

Gathering data
Disclaimer Not Available

Questa è una comunicazione di marketing