Please ensure Javascript is enabled for purposes of website accessibility Retail Sales Remain Resilient
it
it
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Retail sales remain resilient

Retail sales remain resilient

Considering the slowing job market, we dove into retail sales data to search for signs of the direction of household spending. We analyzed existing-store sales and found that, despite the softening labor market and concerns about growth, aggregate consumer spending remains resilient.
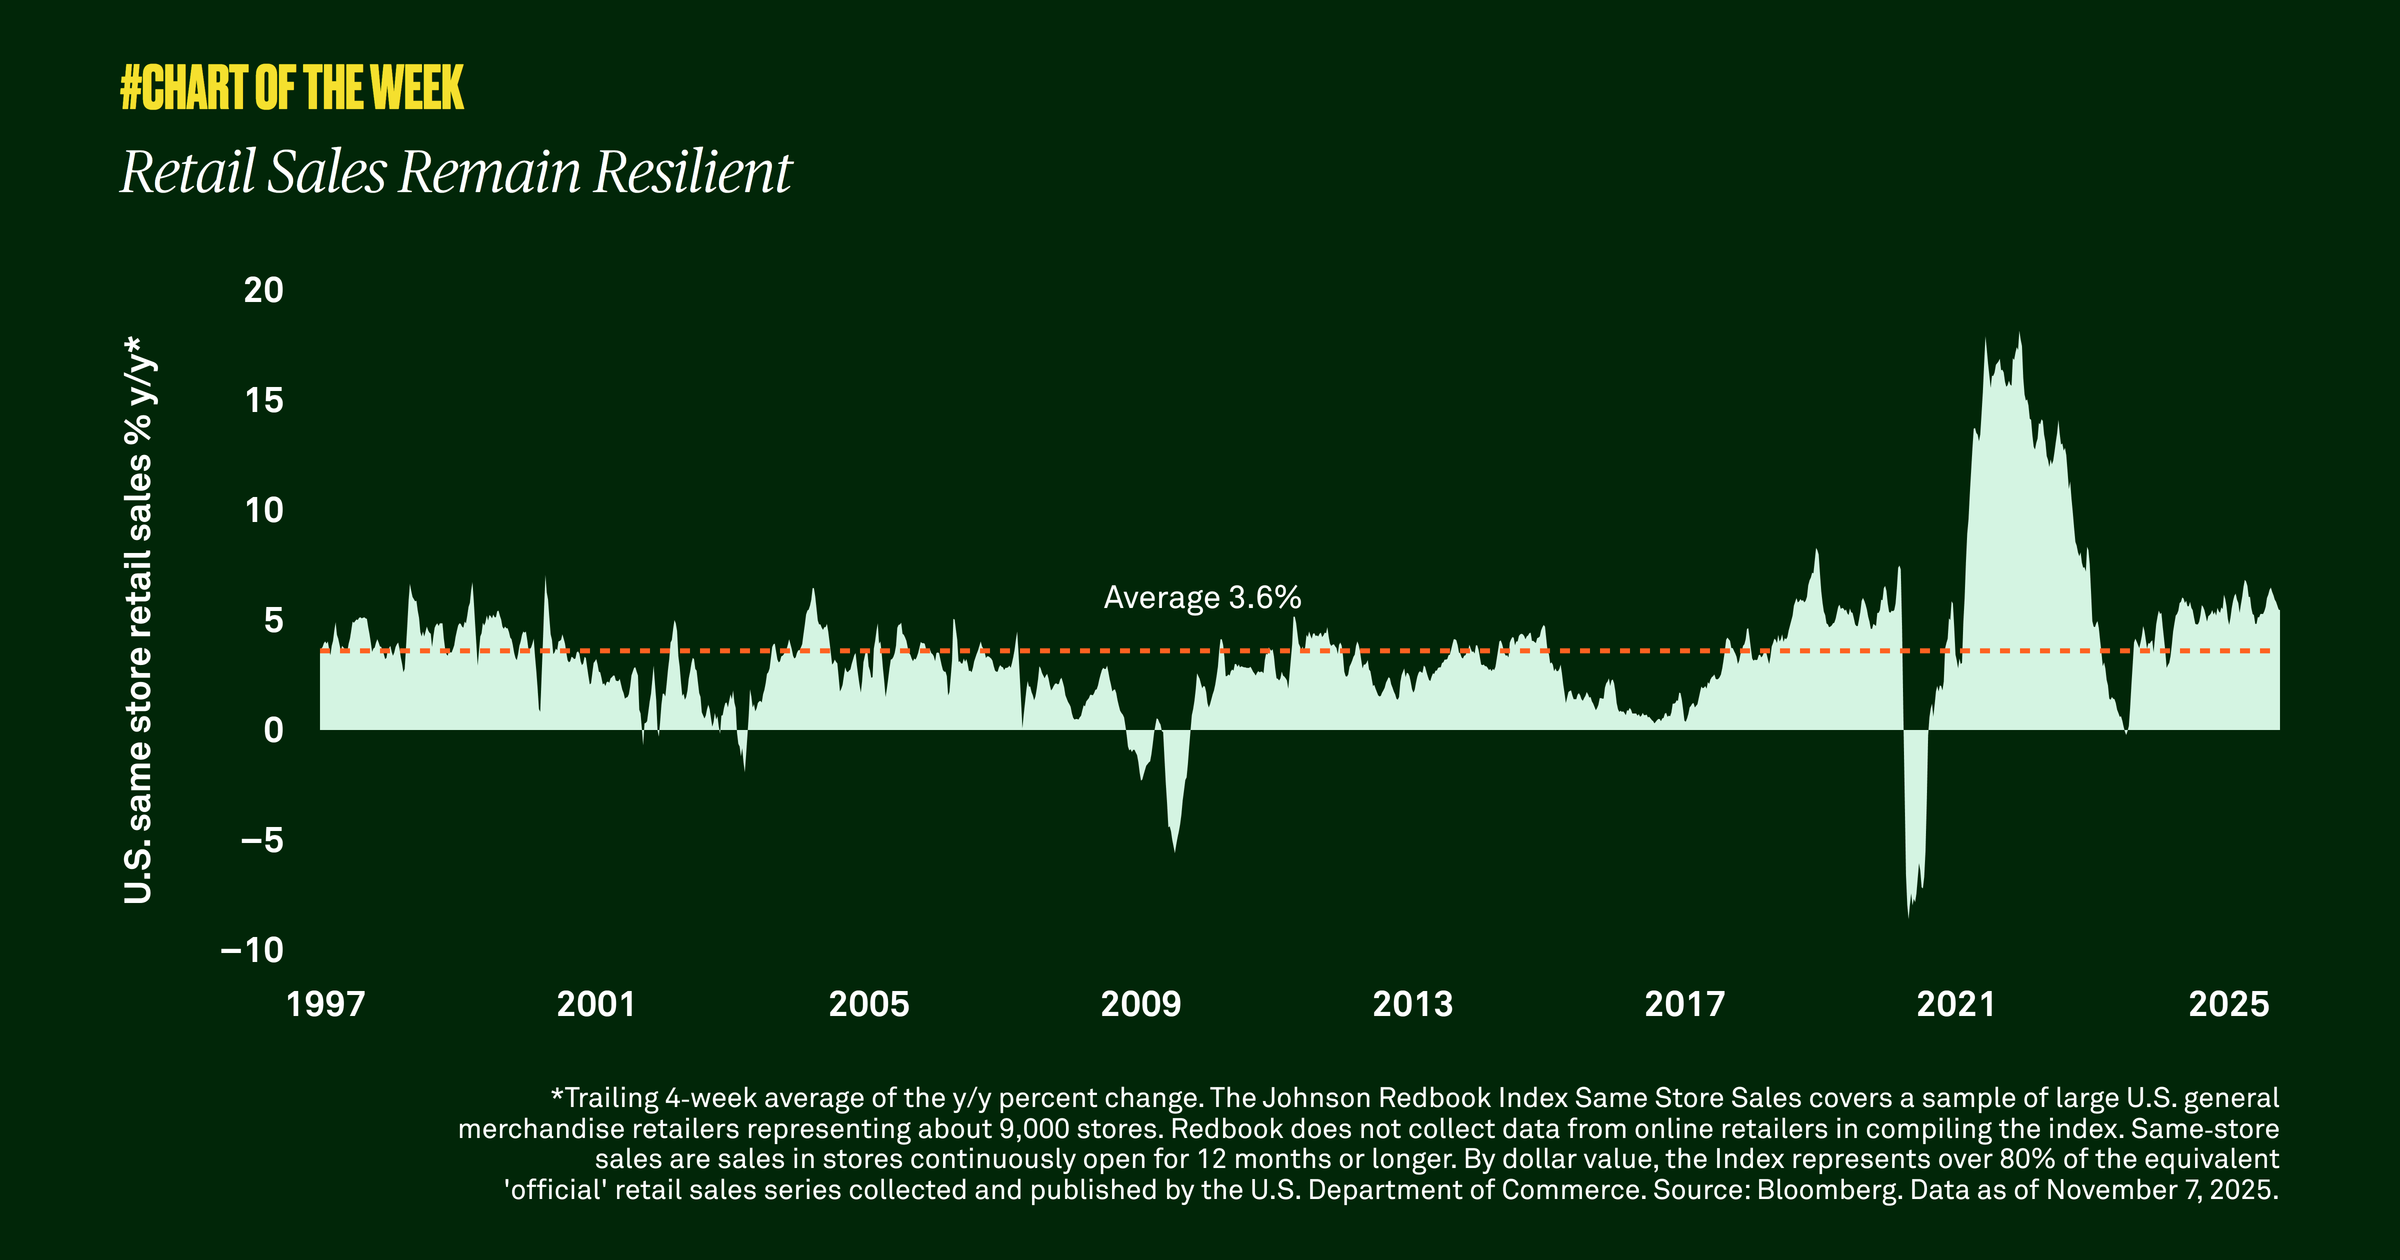
Chart-of-the-week-twentysix


In the wake of the government shutdown, investors have been turning to alternate sources of data in the private domain. Last week, a private outplacement firm announced that October layoffs were higher than many anticipated, raising concerns that growth could slow. With that in mind, we dove into retail sales data to search for signs of a consumer slowdown; after all, consumption comprises 70% of gross domestic product (GDP), and a softening labor market could potentially subdue spending.  

We found that the consumer’s shopping habits remain resilient. Same store retail sales, which measure in-store sales for existing stores, grew 5.7% year over year in October — 2% above the historical average going back to 1997.

In our view, retail sales will continue to be an important barometer of consumer health. While there have been differences in spending by income cohort, thus far total spending has remained resilient, In addition, next year households will enjoy some relief when the Federal Reserve’s easing results in lower borrowing costs. They can also expect stimulus of an estimated $160 billion in additional tax refunds compared to 2025. We believe consumption should continue to support positive economic growth this year and next.
Articoli correlati
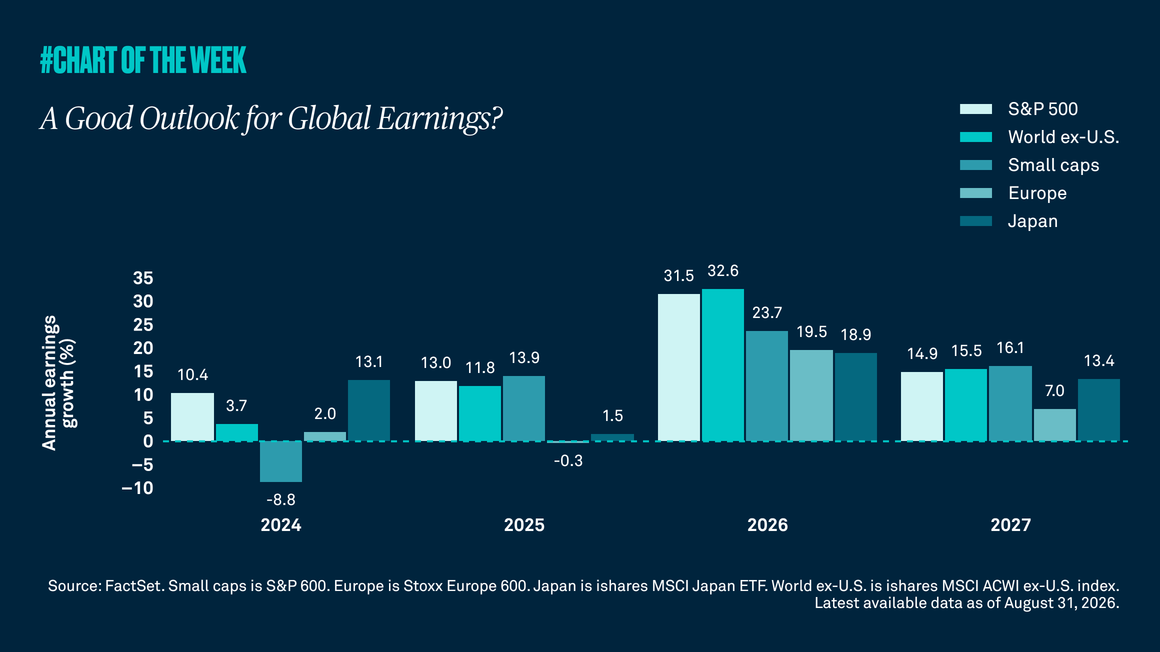
A good outlook for global earnings
Chart of the Week | Macroeconomico

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

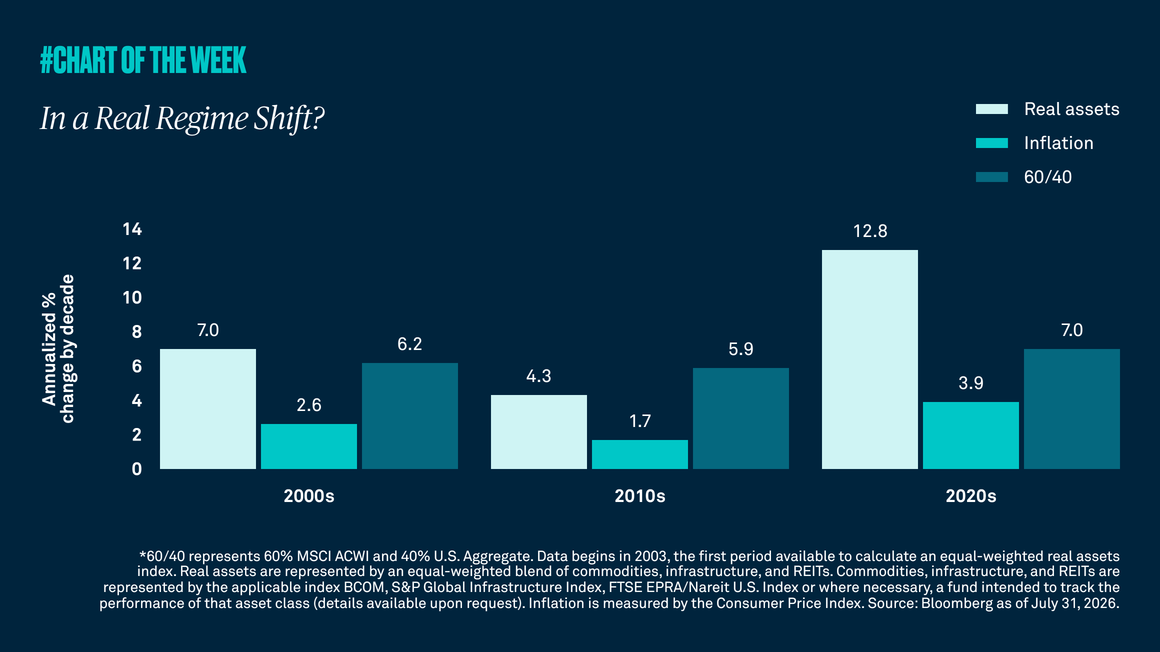
In a real regime shift?
Chart of the Week | Macroeconomico

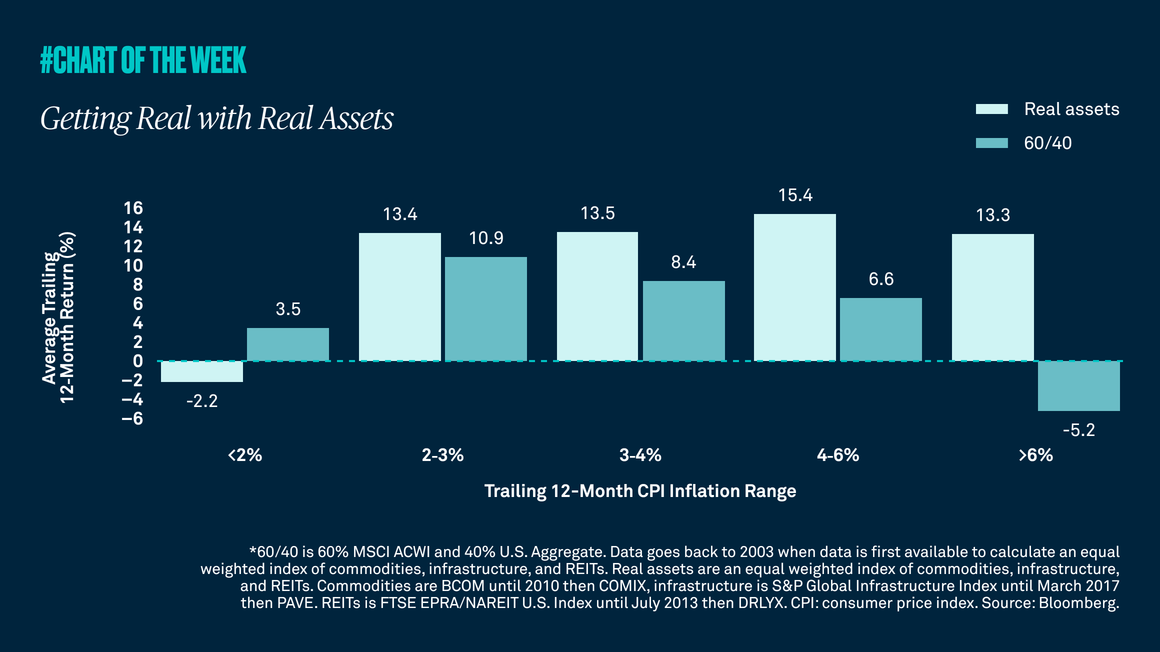
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Getting real with real assets
Chart of the Week | Macroeconomico

Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Is the market rally broadening?
Chart of the Week | Macroeconomico

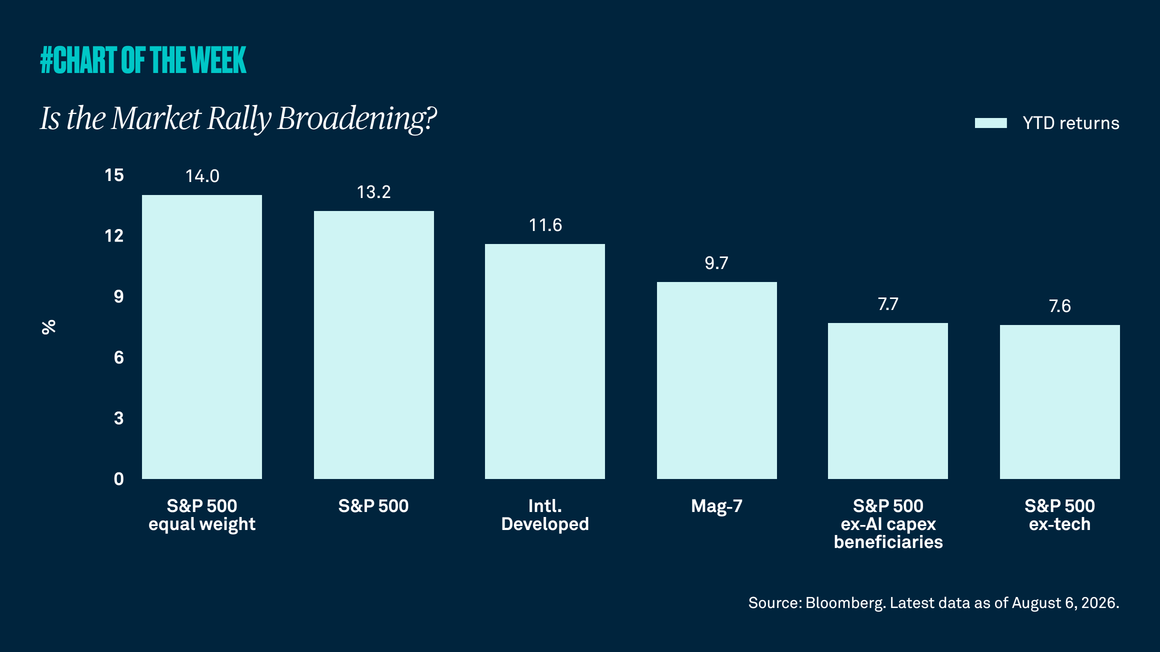
Stocks, as measured by the S&P 500, are up over 13% through early August. The solid gains have been fueled by a resilient economy, steady consumer spending, optimism around artificial intelligence and better-than-expected earnings growth. Still, some investors worry the advance may be too concentrated in technology and that AI-capex monetization may fall short of expectations. A closer look suggests that it is not just tech moving the market higher.

Gathering data
Disclaimer Not Available

Questa è una comunicazione di marketing