Please ensure Javascript is enabled for purposes of website accessibility Are Earnings Broadening Beyond the Magnificent 7?
fr
fr
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Are earnings broadening beyond the magnificent 7?

Are earnings broadening beyond the magnificent 7?

Tech stocks have outperformed the rest of the S&P 500 for several years, and while we expect earnings growth among these companies to continue in 2026, we see another encouraging trend emerging. Earnings across the rest of the market are on an upward path too — and are set to contribute more to earnings growth for the S&P 500 Index in 2026 than the Magnificent 7.
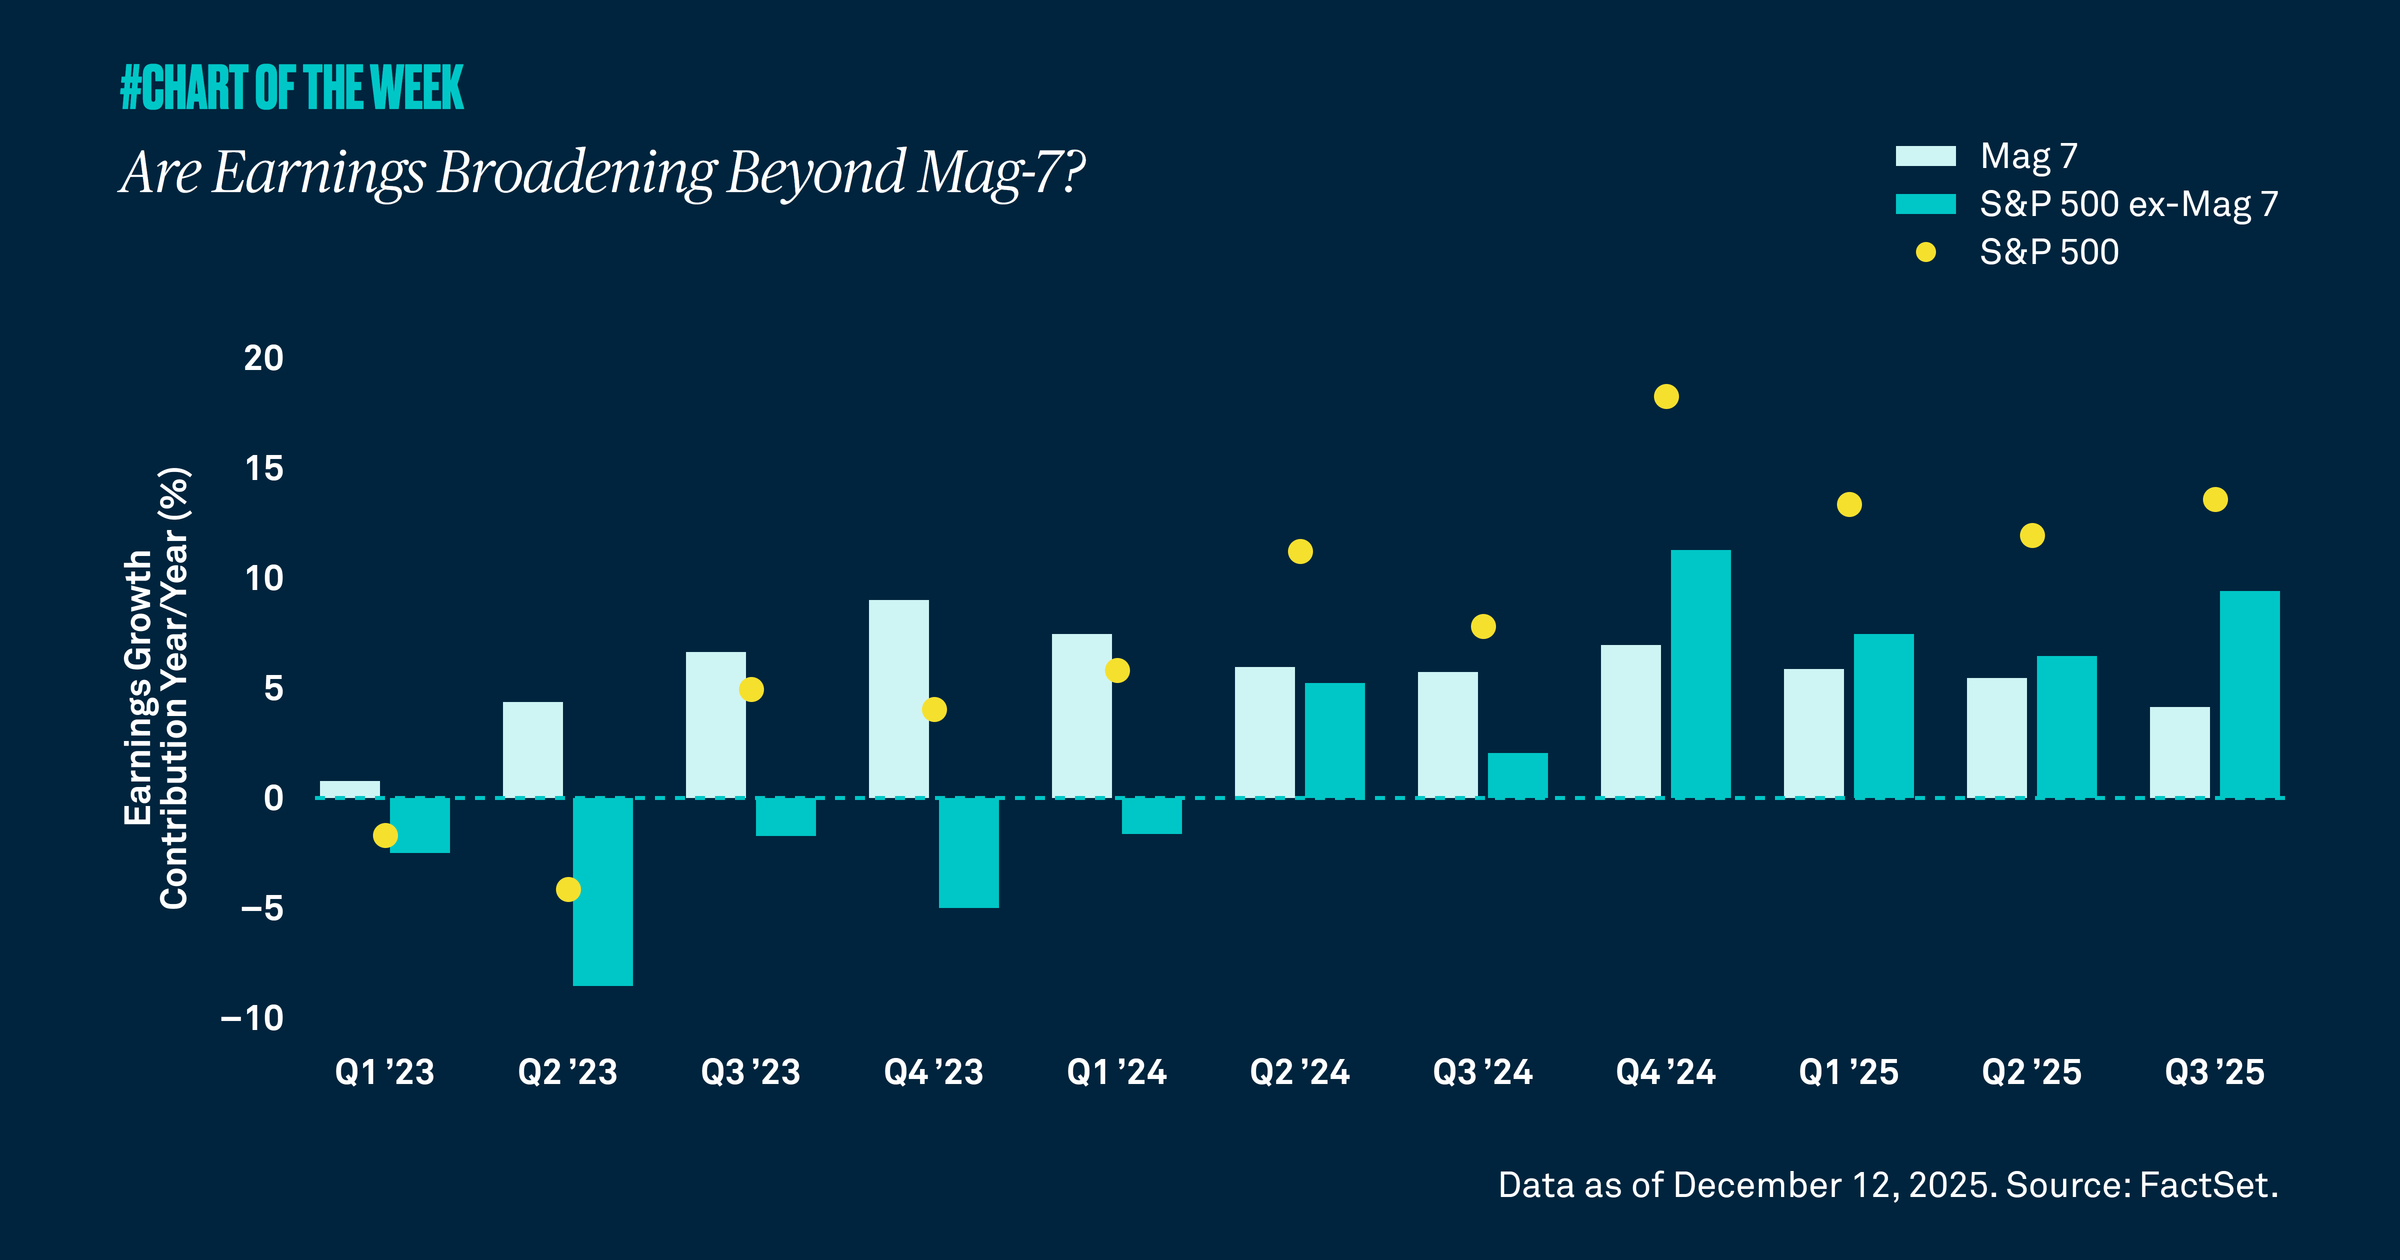

In the third quarter, the Magnificent 7 stocks contributed 4.1% to the S&P 500’s year-over-year earnings growth compared to more than double that, or 9.4%, from the rest of the index. Beyond the third quarter, the Magnificent 7 stocks are expected to trail the earnings growth contribution from the rest of the market for all of 2025. Earnings are broadening beyond tech, and they are on track to continue this path in 2026 — a positive sign in our view.

What’s behind this shift? Productivity and profitability among all sectors have been improving on the heels of AI technology advancements, lower borrowing costs and business-friendly regulatory and policy provisions set by this year’s tax and spending bill. These factors should support upward earnings momentum in 2026 across the S&P 500.

In fact, consensus expectations are for the index’s earnings to grow 14% next year with 5.4% of that growth coming from the Magnificent 7 and 8.9% from the rest of the market. This is in line with our 10-15% earnings target for 2026 as well as our view that the broadening trend will strengthen further in the upcoming months.  
AUTRES ARTICLES ASSOCIÉS
A good outlook for global earnings
Chart of the Week | Macroéconomique

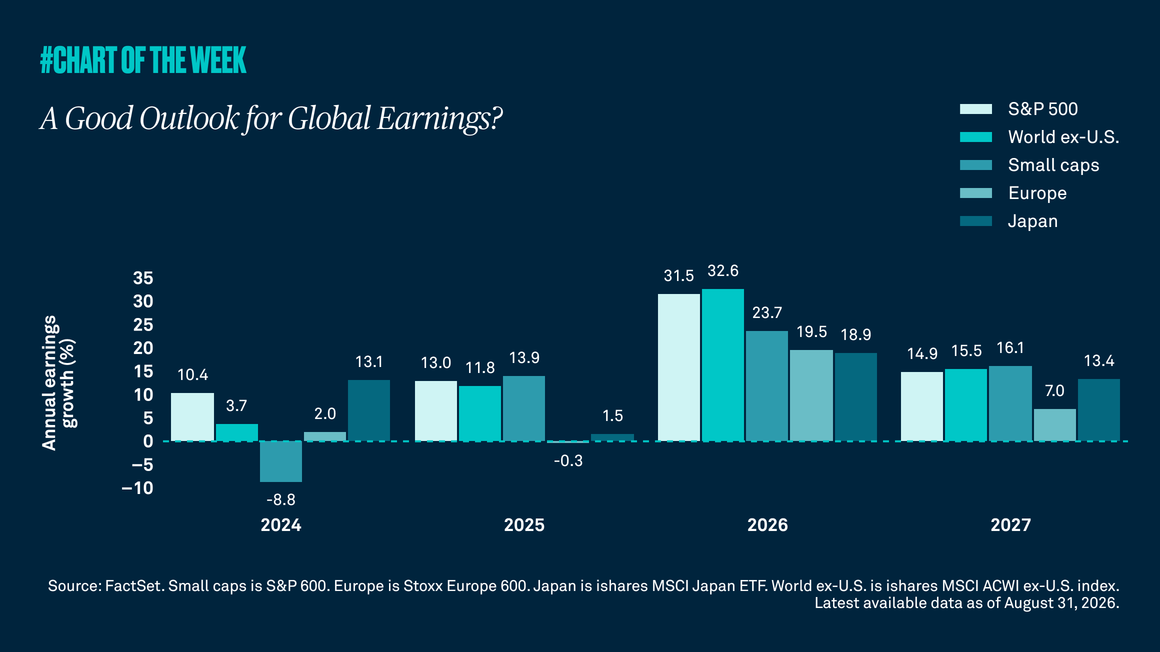
Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

In a real regime shift?
Chart of the Week | Macroéconomique

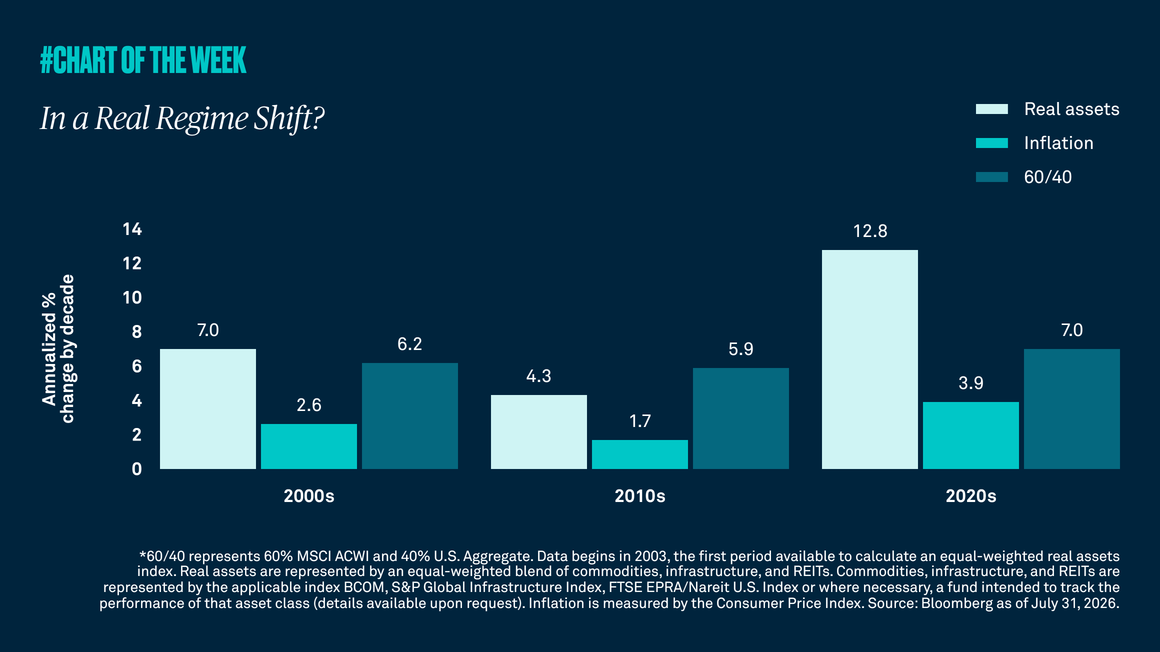
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Getting real with real assets
Chart of the Week | Macroéconomique

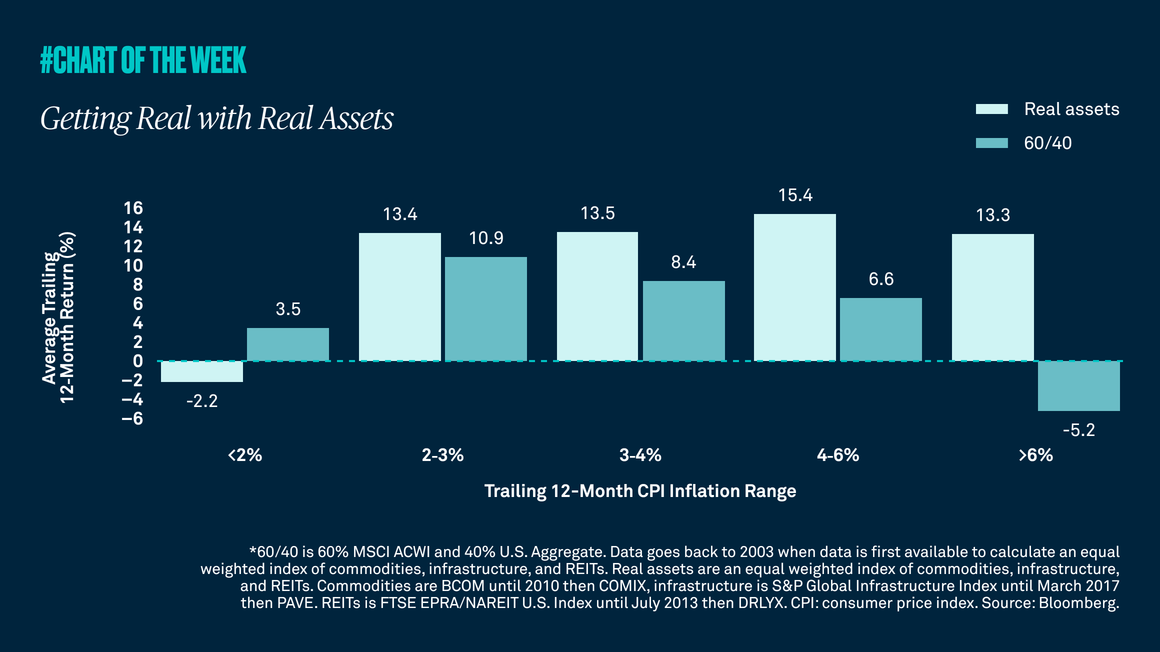
Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Not in a bubble
Chart of the Week | Macroéconomique

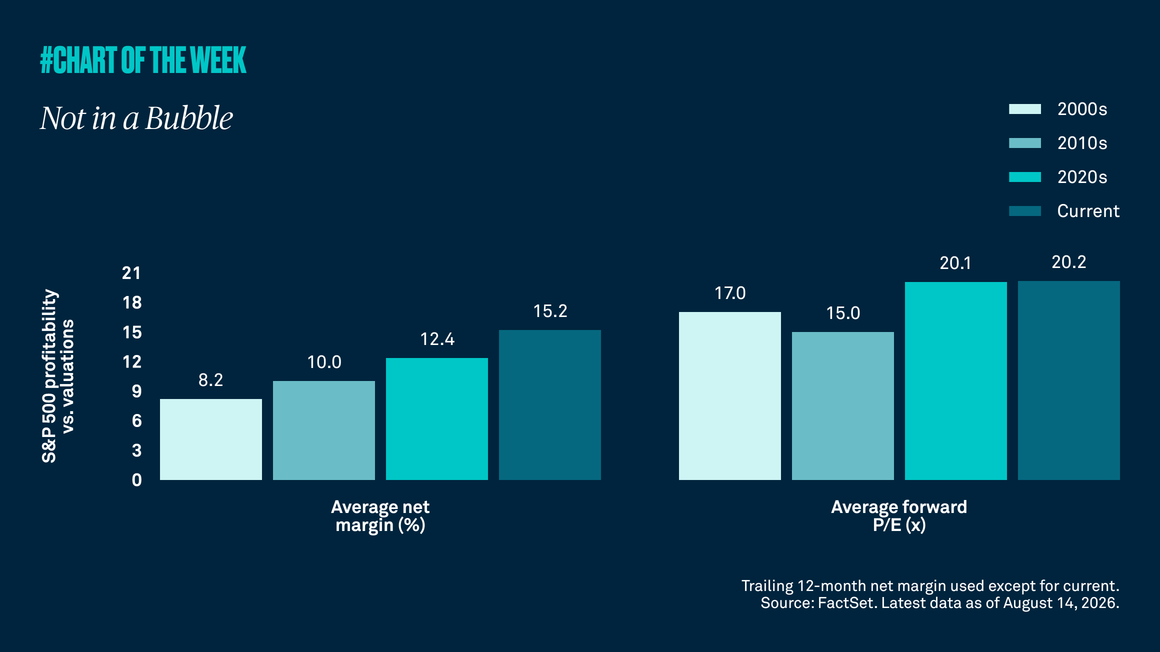
As the S&P 500 approaches all-time highs, there are renewed concerns among investors about elevated valuations. However, historically strong profitability and expected earnings growth appear to support current pricing. In addition, the current S&P 500 price-to-earnings (P/E) ratio is roughly equal to the average since Covid. As a result, we do not view U.S. equities as being in bubble territory and we remain constructive on the asset class.

Gathering data
Disclaimer Not Available

Ce document constitue une communication marketing