Please ensure Javascript is enabled for purposes of website accessibility The Global Economy Is Holding Up
de
de
intermediary
intermediary
false
true
Gathering data
Disclaimer Not Available

The global economy is holding up

The global economy is holding up

This past year was rife with risks to the global economy: policy changes, tariff uncertainty and more. Yet, the global economy held up as manufacturing and services activity strengthened across the world. We see an opportunity for U.S. investors to diversify geographically.
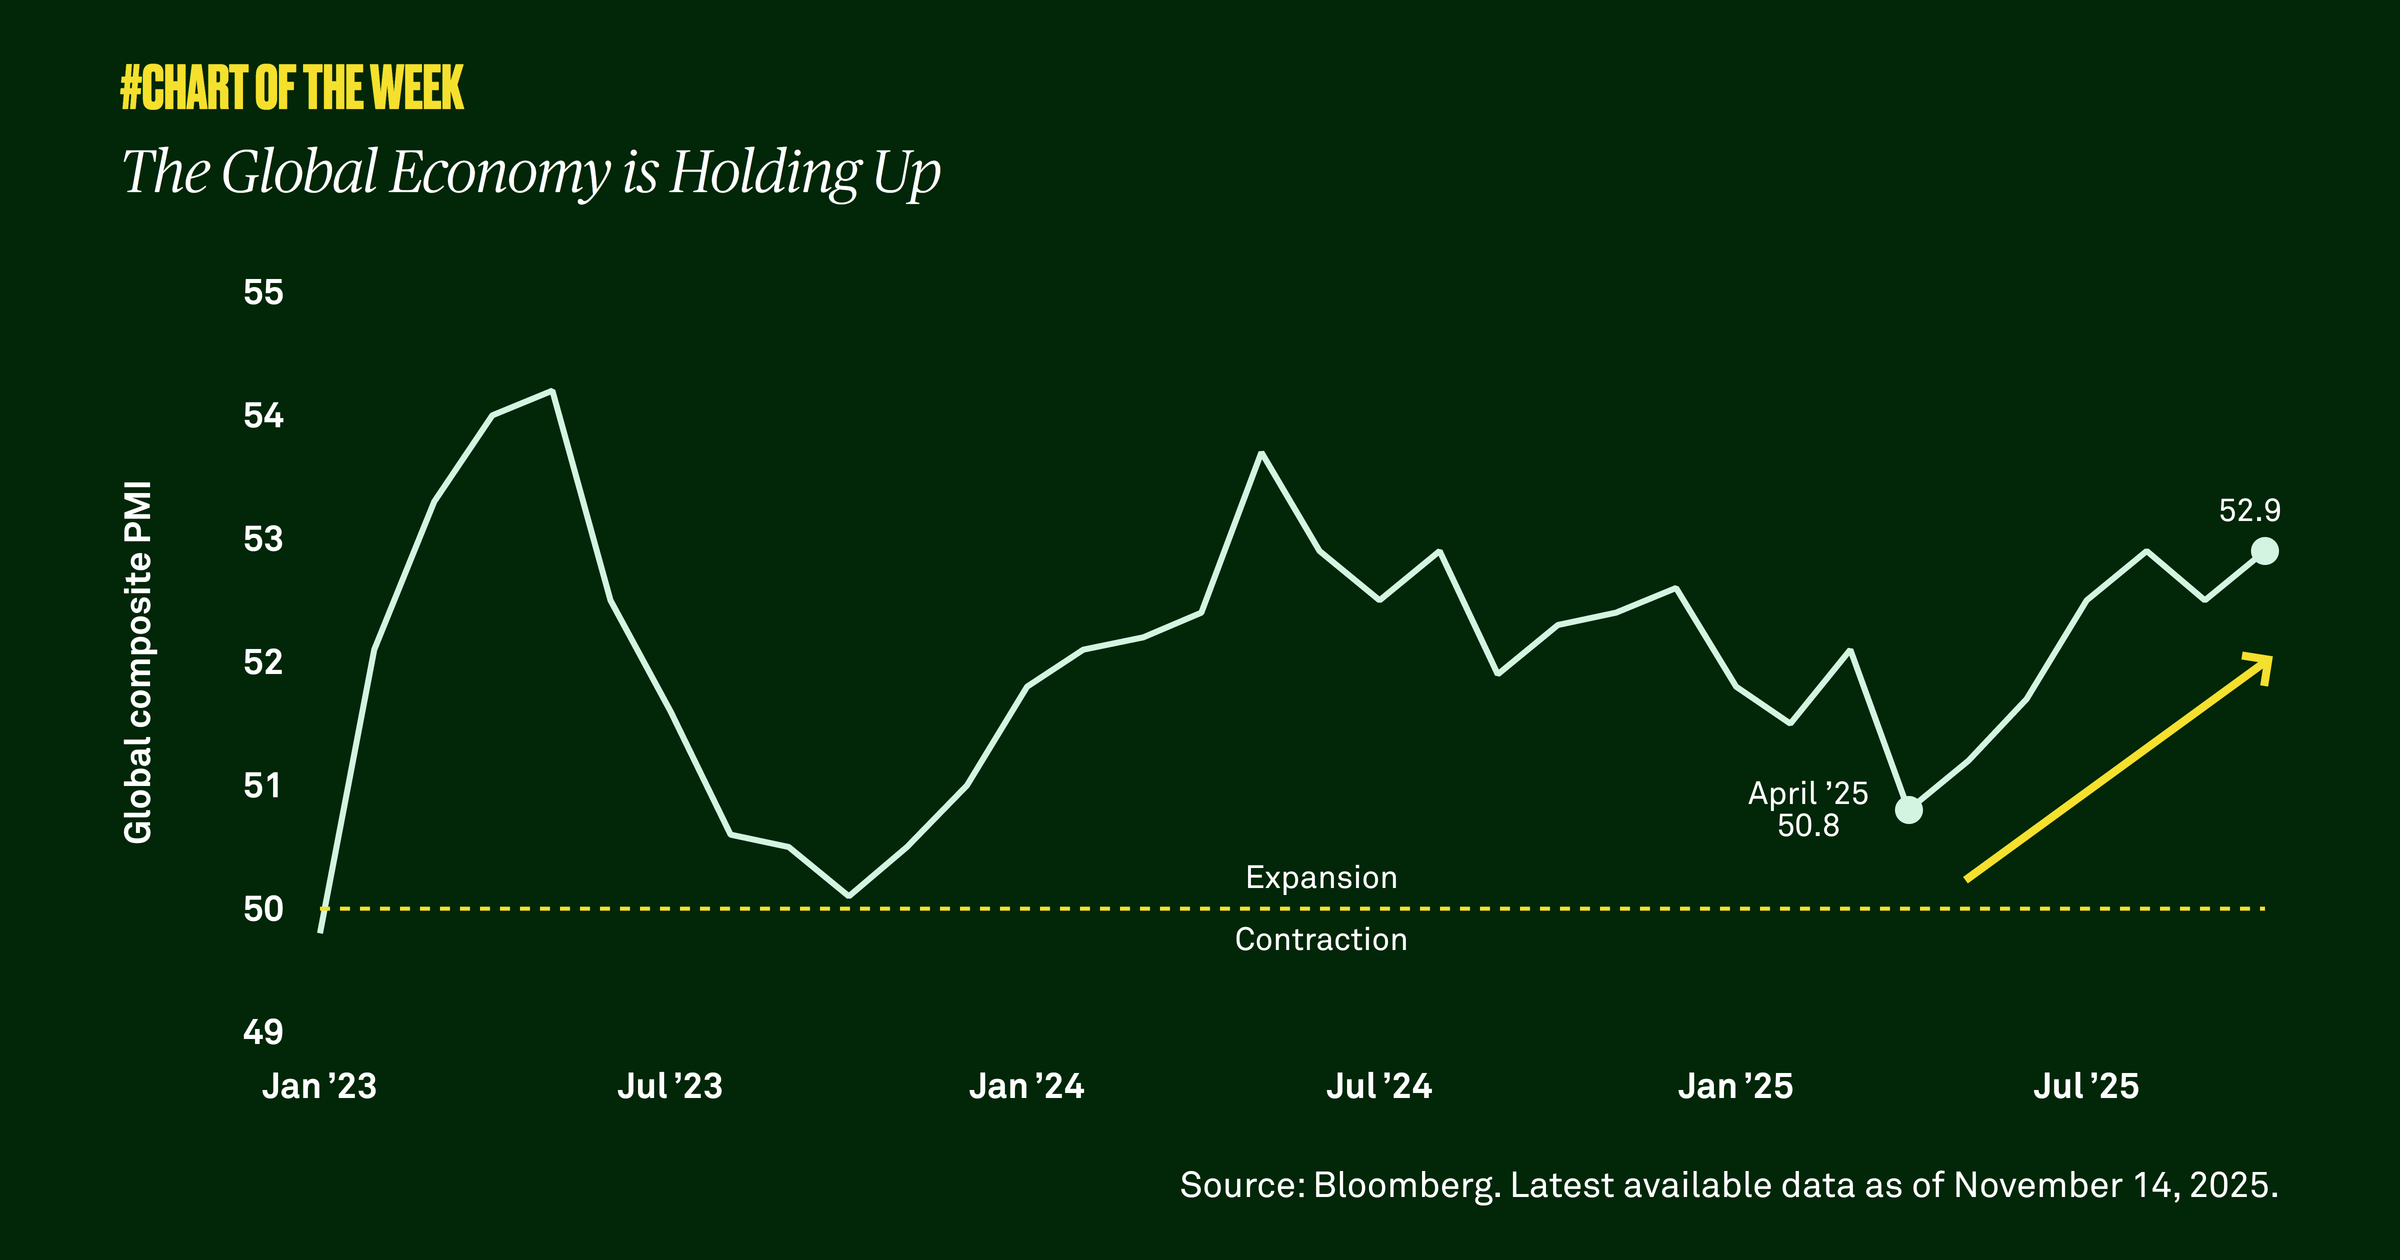
Chart-of-the-week-twentyseven


The global economy remained resilient this past year during a time of pronounced policy and tariff uncertainty, as well as geopolitical tensions. Yet, fiscal support, monetary easing and strong capital expenditures helped economies deliver positive growth.

A key measure of economic conditions, the Global Composite Purchasing Managers’ Index (PMI), a weighted average of the global manufacturing and services PMIs, provides a snapshot of overall worldwide economic health. A reading above 50 indicates economic expansion, while a reading below 50 suggests a contraction. This metric is at its highest since August 2024 and underpins our positive outlook for global growth as we head into 2026.

A strong global economy is important to investors because increased economic activity leads to higher corporate profits, boosting stock prices.  It is one of the reasons we maintain a constructive view on equities and why diversification across regions remains important.
VERWANDTE THEMEN
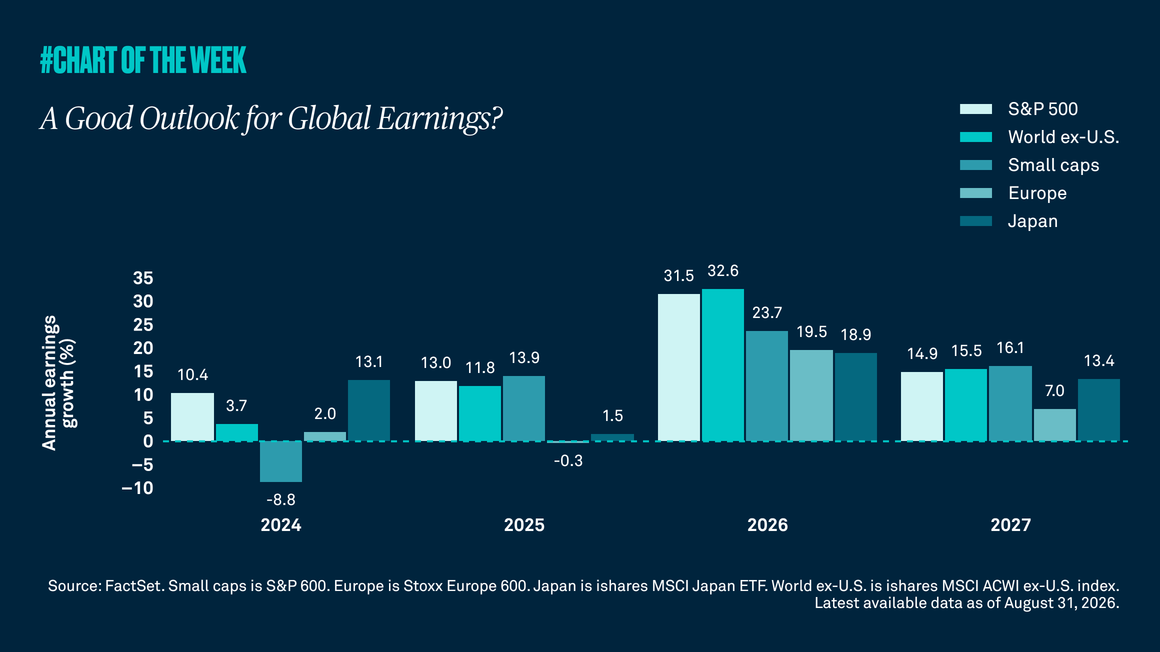
A good outlook for global earnings
Chart of the Week | Makroökonomisch

Global earnings growth has been strong this year, led by the U.S. and reinforced by improving profit growth across Europe, Japan and other major markets. While volatility may rise in the near term, above-average earnings and broader global participation remain supportive of global equities.

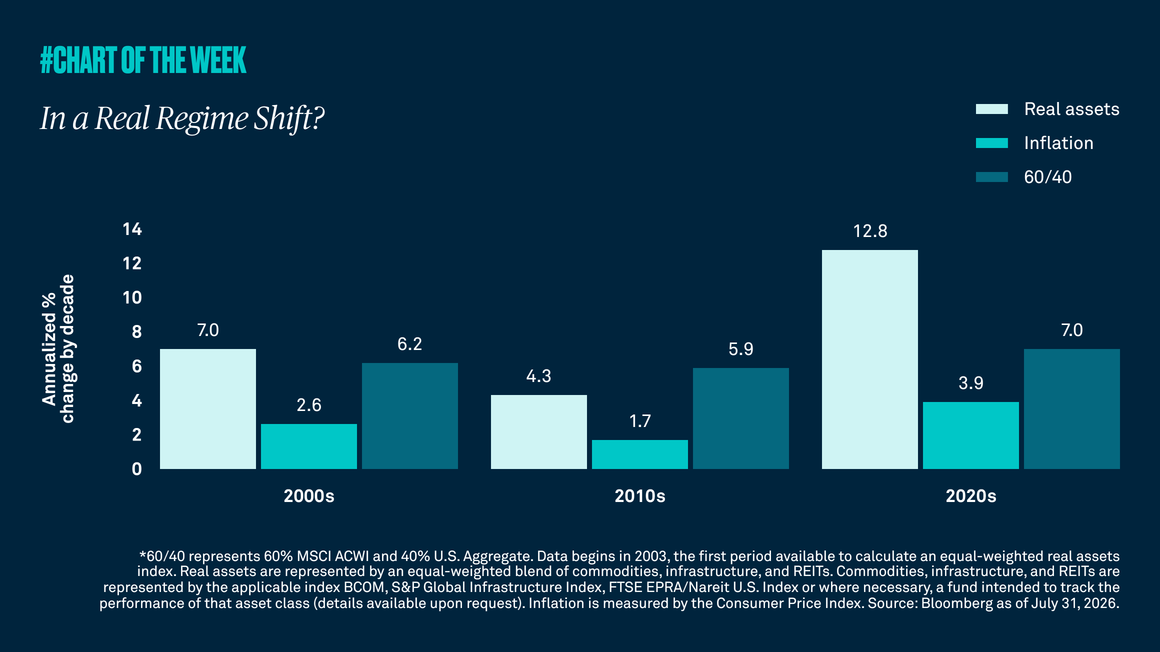
In a real regime shift?
Chart of the Week | Makroökonomisch

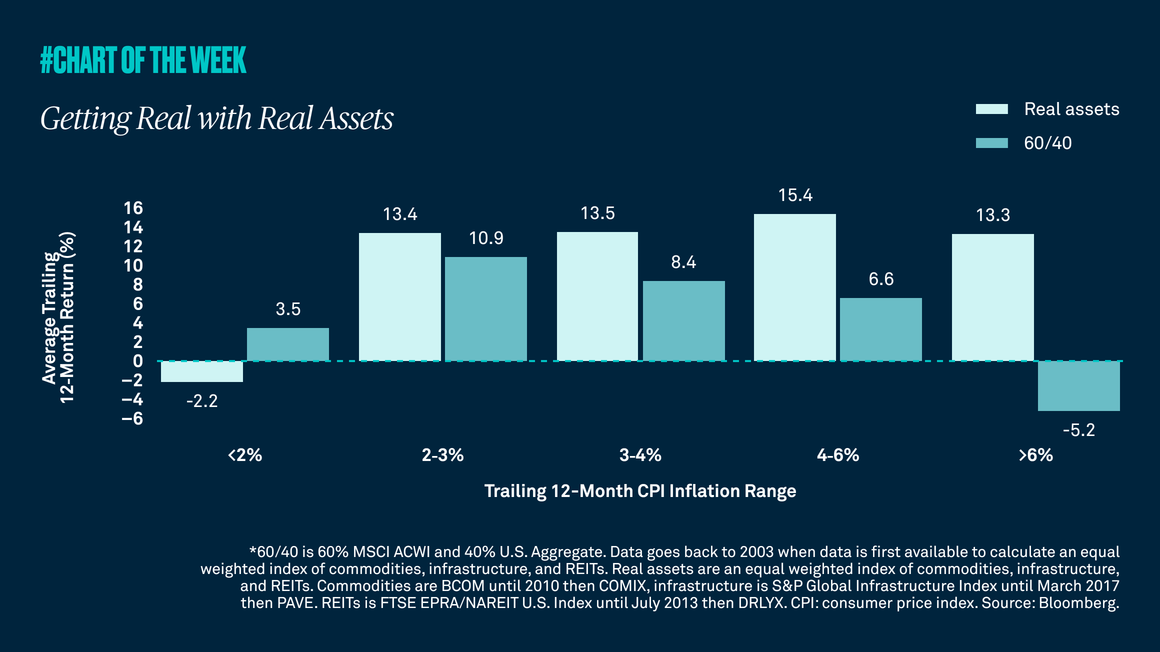
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Getting real with real assets
Chart of the Week | Makroökonomisch

Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Not in a bubble
Chart of the Week | Makroökonomisch

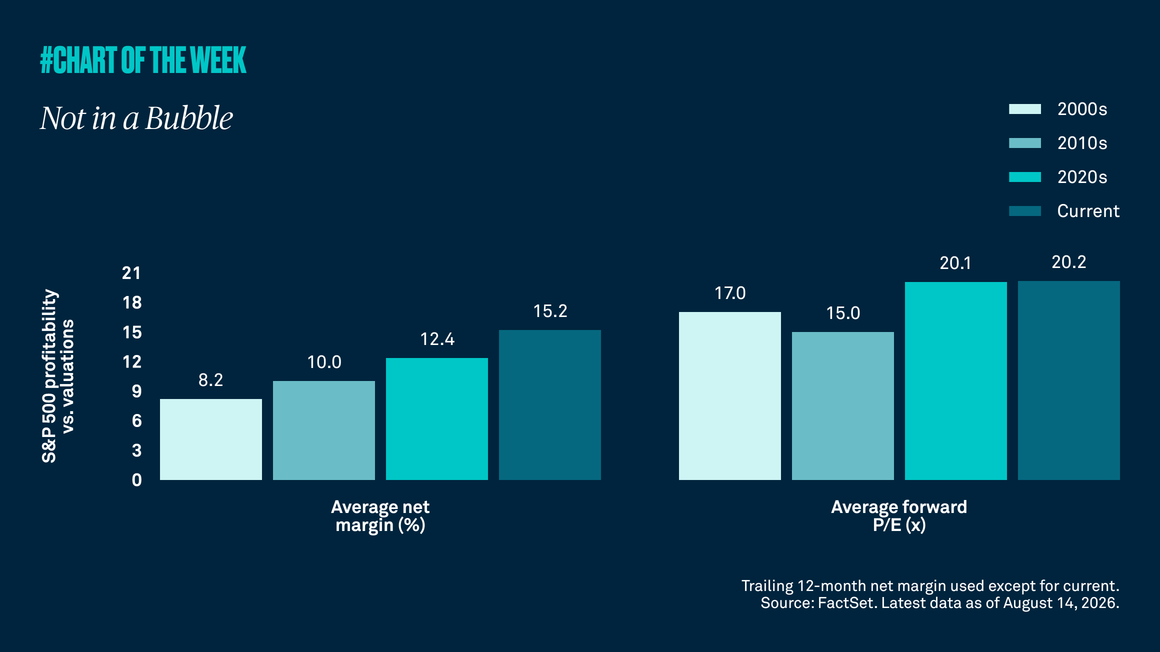
As the S&P 500 approaches all-time highs, there are renewed concerns among investors about elevated valuations. However, historically strong profitability and expected earnings growth appear to support current pricing. In addition, the current S&P 500 price-to-earnings (P/E) ratio is roughly equal to the average since Covid. As a result, we do not view U.S. equities as being in bubble territory and we remain constructive on the asset class.

Gathering data
Disclaimer Not Available

Dies ist eine Marketingkommunikation