Please ensure Javascript is enabled for purposes of website accessibility Muni yields are attractive
de
de
institutional
institutional
false
true
Gathering data
Disclaimer Not Available

Muni yields are attractive

cotw_27_07_2026_580x326

The war in Iran has increased volatility across fixed income markets, pushing municipal bond yields higher as investors reassess inflation risk, energy costs and the path of Federal Reserve policy. Even so, historically elevated municipal bond yields present a compelling opportunity for tax-sensitive investors.


The war in Iran has added pressure to fixed income markets, particularly in U.S. Treasuries. The 10-year Treasury yield recently traded near 4.7% as investors repriced inflation risk and the economic effects of higher energy costs and what that may mean for monetary policy. At the same time, municipal bond yields have risen as well, with 10-year tax-free bond yields reaching roughly 3.8% or 6.3% on a tax-equivalent basis. This is key because entry-point yield is often a strong indicator of long-term return potential.

While yield volatility is likely to persist, our Tax-Managed Fixed Income solution seeks to uncover value in the municipal bond market through disciplined security selection, active risk management and tax-aware portfolio management.
 

VERWANDTE THEMEN
In a real regime shift?
Chart of the Week | Makroökonomisch

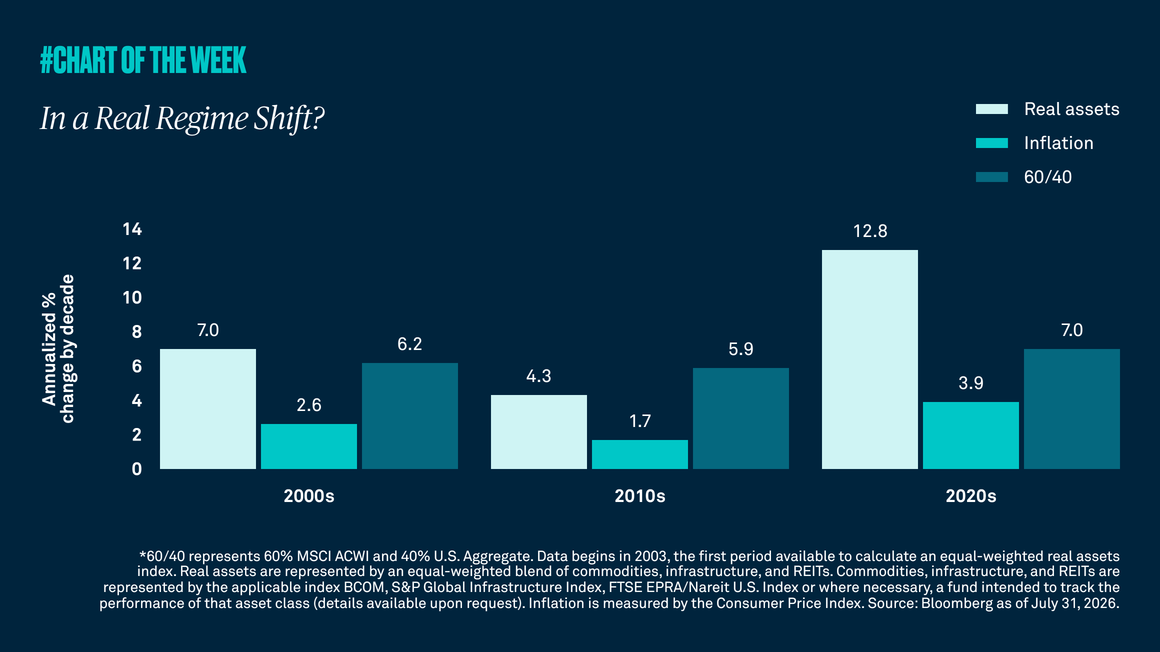
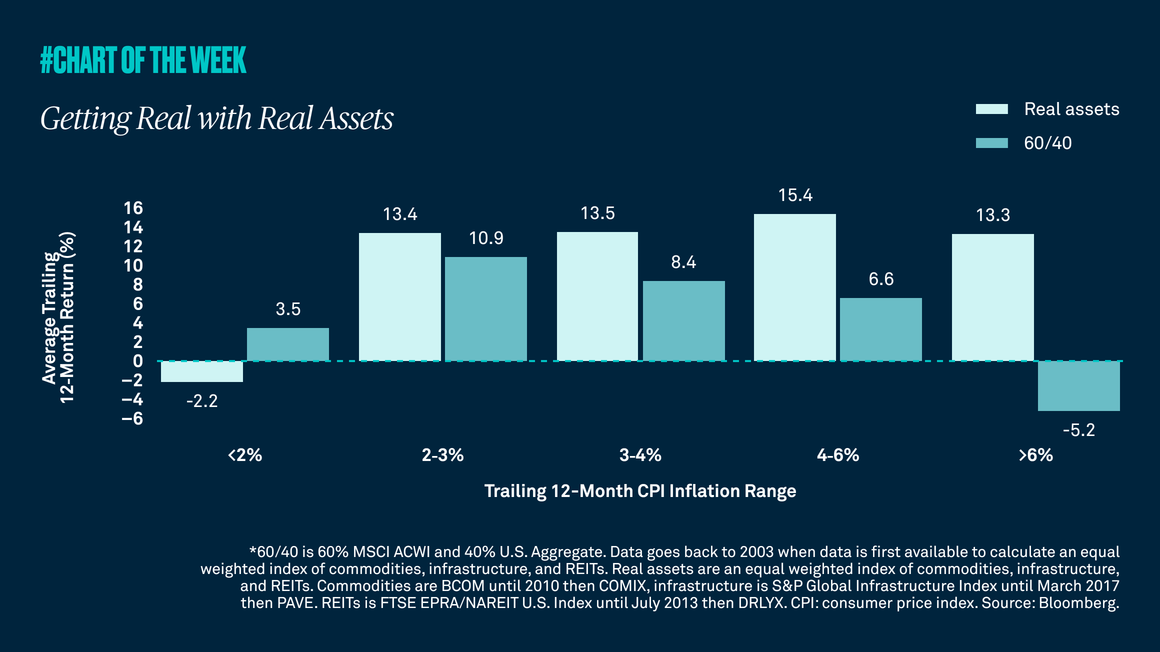
Higher inflation has been a dominant theme of the current decade. In addition to price shocks, it is being shaped by secular investment trends in infrastructure, defense spending, onshoring and the ongoing AI buildout. These structural changes reinforce the case for looking beyond traditional 60/40 portfolios to include real assets as a source of diversification and return potential in portfolios.

Getting real with real assets
Chart of the Week | Makroökonomisch

Inflation appears to have transitioned from its pre-Covid average of 2% to a stickier point closer to 3%, and we do not expect a near-term return to prior levels. In this environment, we believe real assets, such as commodities, infrastructure and REITs, can provide inflation protection, diversification and return potential.

Not in a bubble
Chart of the Week | Makroökonomisch

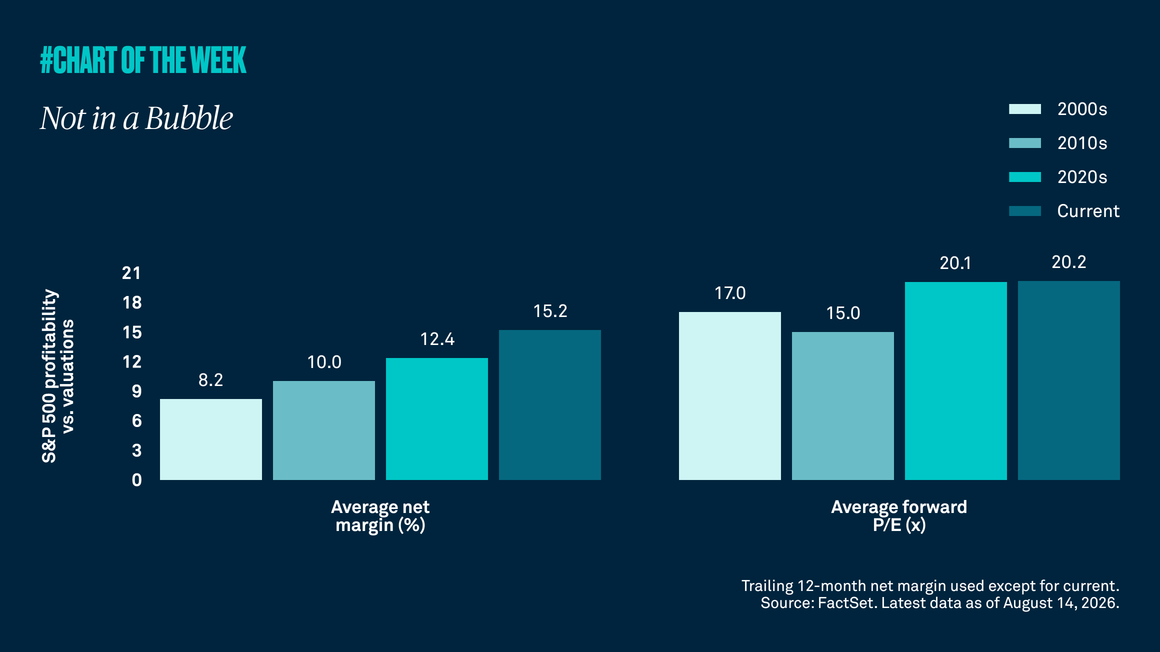
As the S&P 500 approaches all-time highs, there are renewed concerns among investors about elevated valuations. However, historically strong profitability and expected earnings growth appear to support current pricing. In addition, the current S&P 500 price-to-earnings (P/E) ratio is roughly equal to the average since Covid. As a result, we do not view U.S. equities as being in bubble territory and we remain constructive on the asset class.

Is the market rally broadening?
Chart of the Week | Makroökonomisch

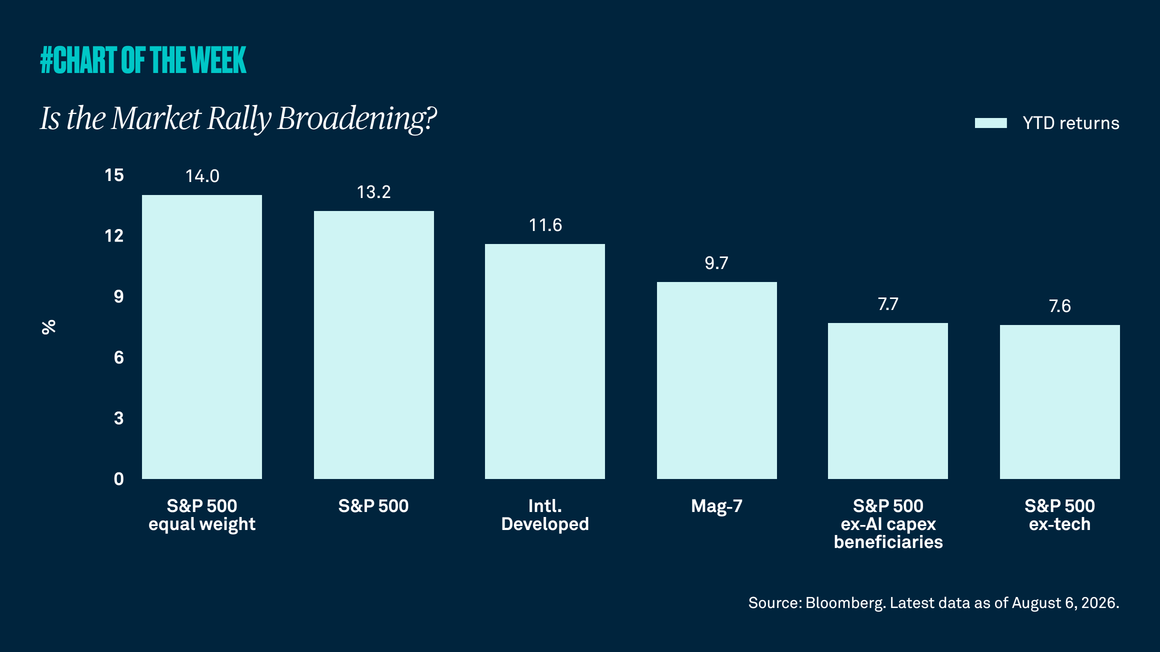
Stocks, as measured by the S&P 500, are up over 13% through early August. The solid gains have been fueled by a resilient economy, steady consumer spending, optimism around artificial intelligence and better-than-expected earnings growth. Still, some investors worry the advance may be too concentrated in technology and that AI-capex monetization may fall short of expectations. A closer look suggests that it is not just tech moving the market higher.

Gathering data
Disclaimer Not Available

Dies ist eine Marketingkommunikation