U.S. Treasury Buybacks: Signal Matters More than Size
Special Report

Geoff Yu, David Tam
Time to Read: 7 minutes
Treasury’s move matters more as a policy signal than a source of demand. It supports a tactical long-end rally and curve flattening, but sustained gains require stronger underlying demand. Rising inflation expectations could instead weaken real yields and the dollar.
Announcement: The U.S. Treasury announced that it will at least double its liquidity-support buybacks in longer-dated nominal securities. Starting on September 9, the maximum size of operations in both the 10–20-year and 20–30-year sectors will rise “to at least $4bn” from $2bn. The increase will remain in place through the end of the current refunding quarter on November 4, when Treasury will provide further guidance.
Treasury’s Conviction: The unscheduled announcement, only two weeks after the quarterly refunding update, shows Treasury is increasingly attentive to long-end liquidity as yields approach multi-decade highs.
Market Reaction: Long-end Treasury yields fell around 9bp and the 5s30s curve flattened by approximately 5bp. Foreign sovereign curves moved in sympathy, with JGBs and Gilts down 5bp. The Bloomberg Dollar Spot Index fell as much as 0.5%, emerging-market currencies rallied and lower yields supported U.S. equities. The breadth of the move suggests investors placed greater weight on the policy signal than on the direct demand from the additional buybacks.
Move can go further: Our traders believe the initial move has scope to extend, making a near-term fade unattractive. Long-end valuations had become stretched, leaving roughly 10bp of readily reversible weakness. Widely-held steepener positions create scope for further unwinding, although many are not yet under significant pressure.
Flow signals: Initial flows showed some interest in fading the outright bond rally, but little appetite to fade the curve flattening. At present, at least, the buybacks are small and infrequent; their immediate importance lies in demonstrating that Treasury is prepared to act rather than rely solely on verbal guidance.
Treasury’s reaction function: If the initial increase fails to improve long-end conditions sustainably, operations could be scaled up further, although conviction is limited by the lack of guidance on how far Treasury is willing to intervene.
Activism rising: The growing use of official measures across currency and interest-rate markets raises questions about Treasury’s broader willingness to intervene. Larger or more persistent buybacks may support the long end tactically, but would not remove the underlying financing requirement. Over time, the net effect will likely be greater reliance on shorter-dated issuance.
Overweight the front end: Ahead of the announcement, iFlow showed considerably stronger demand for liquidity and short-dated instruments than for government duration. U.S. T-bills recorded eight consecutive days of purchases from the beginning of August, while their rolling six-week flow remained firmly positive. Cash-equivalent demand also recovered, pointing to a preference for front-end carry and liquidity amid uncertainty over inflation and policy.
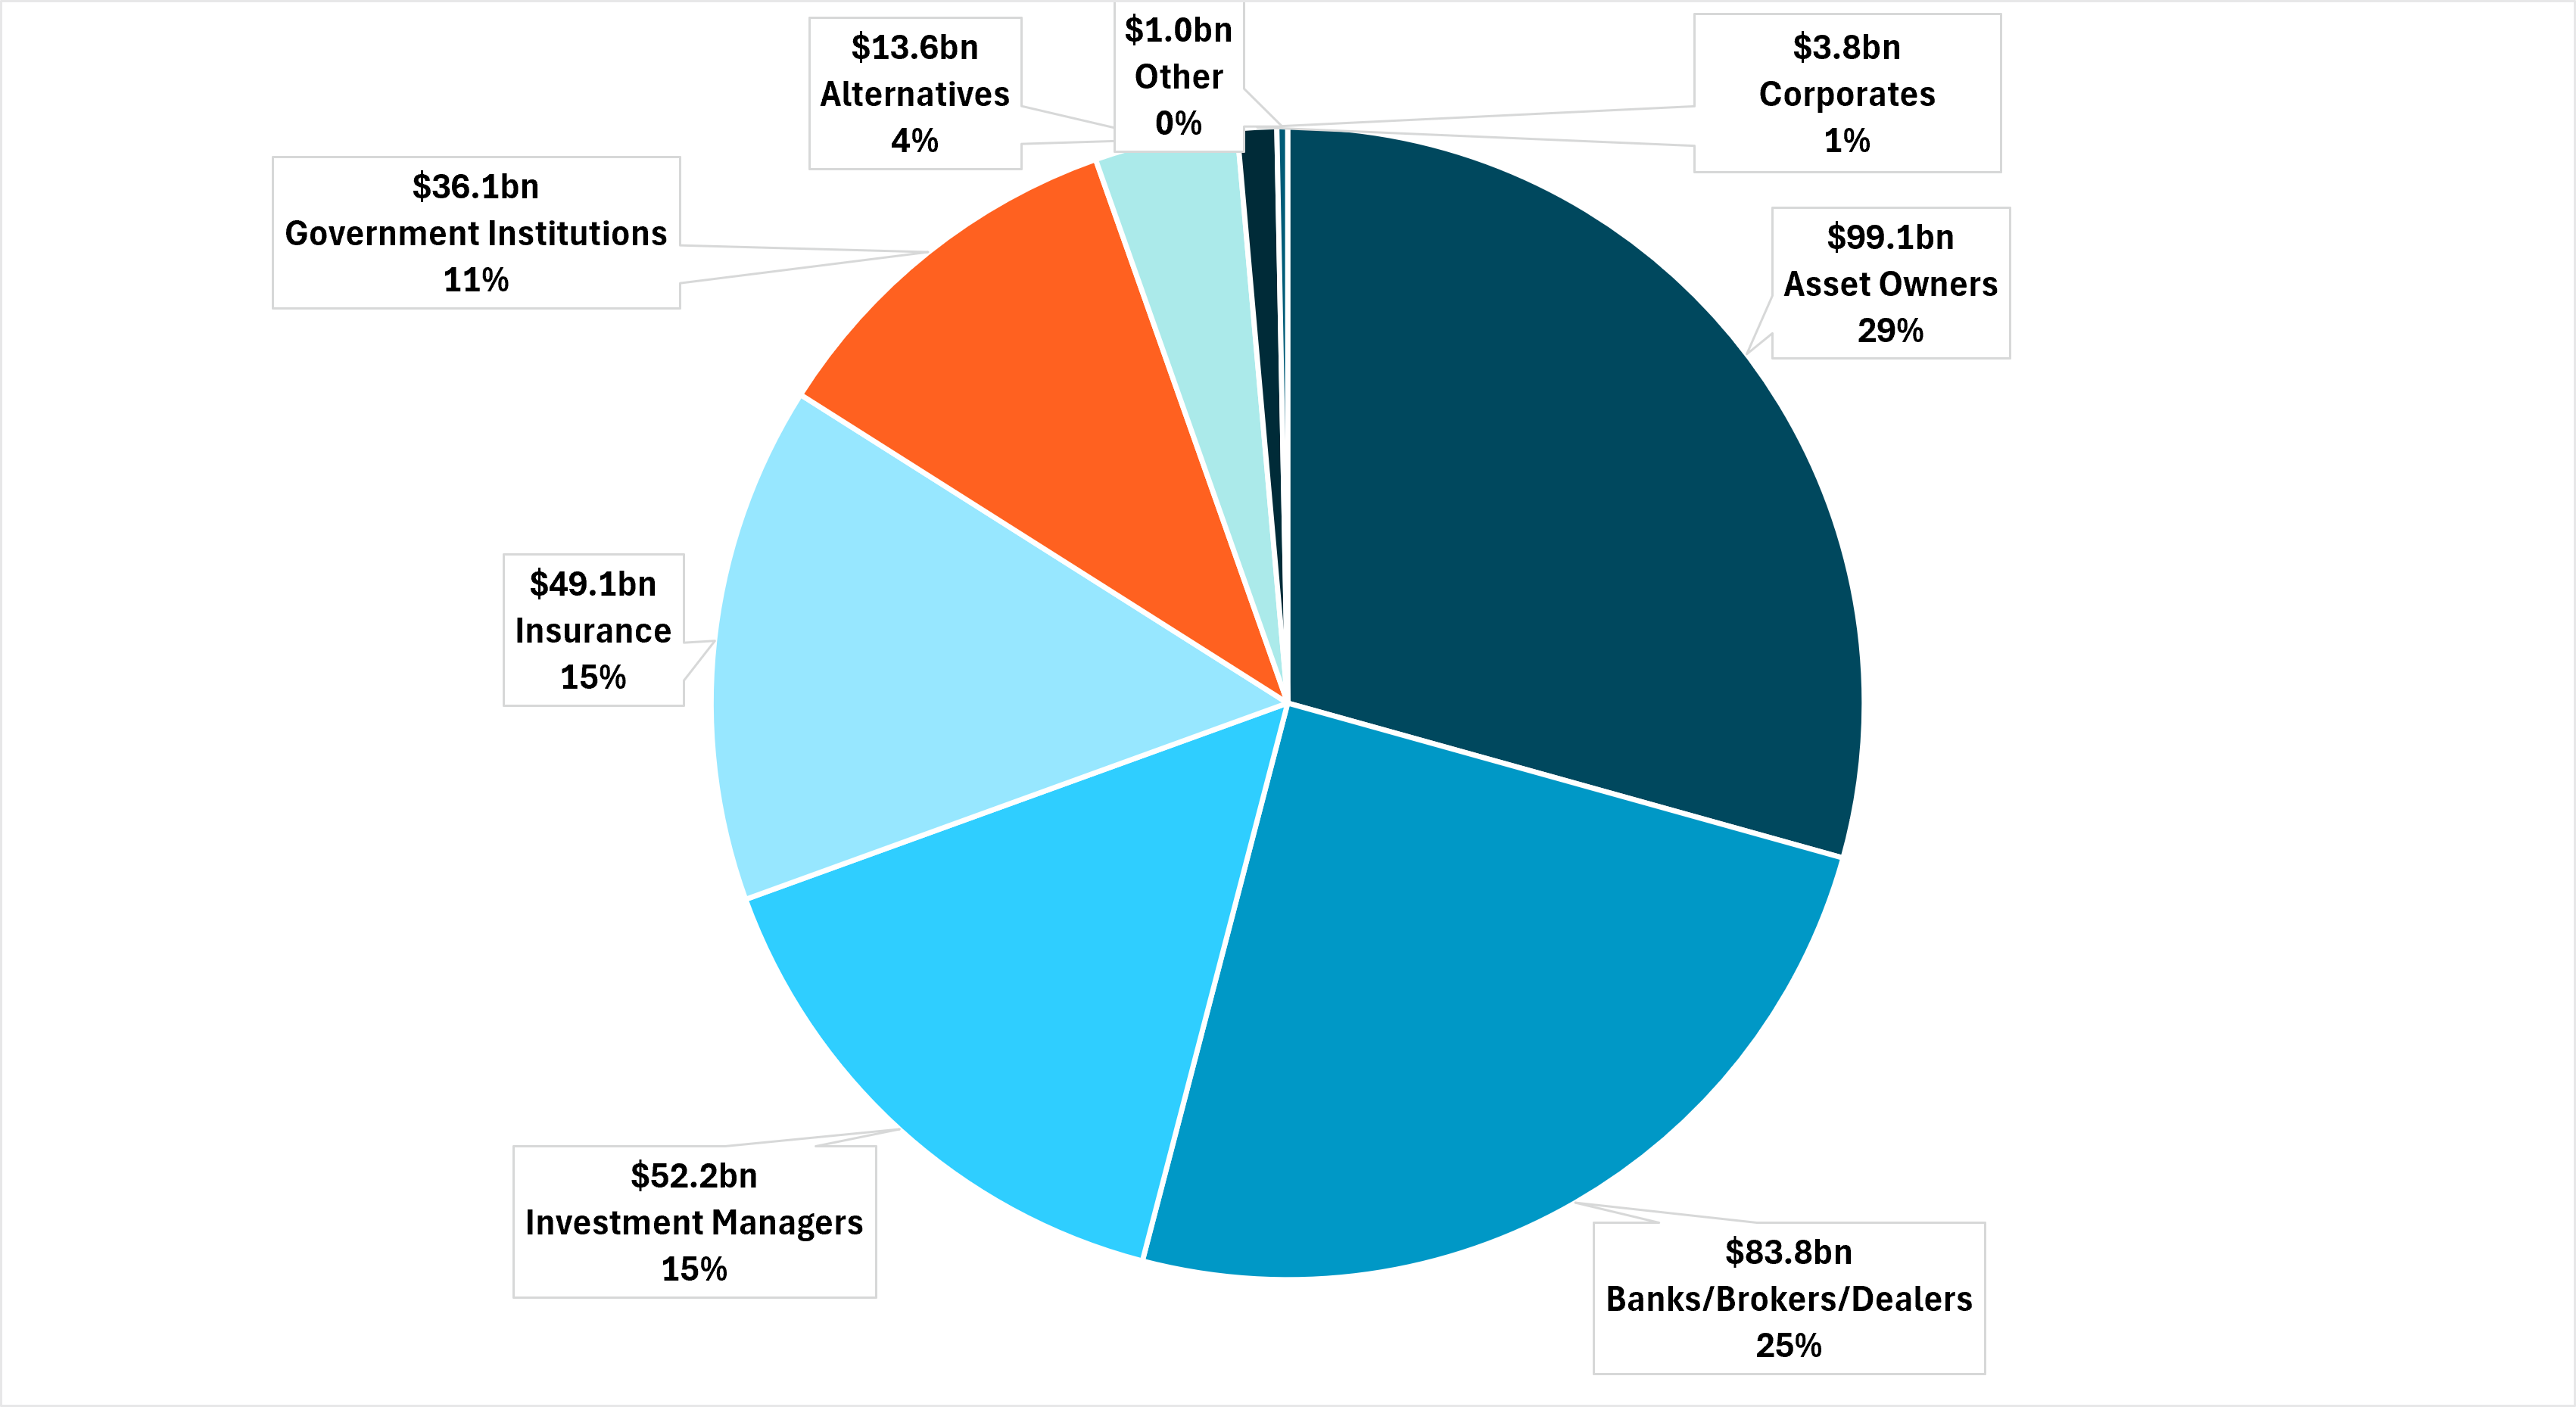
Who owns the long end?: Within iFlow holdings, pension and benefit funds are the largest cohort, accounting for $92.5bn, or 27.6%, while insurers hold a further $49.1bn, or 14.7%. Both represent structurally sticky demand tied to liability matching. Banks, brokers and dealers are the second-largest group at $83.8bn, or 25.0%, but their positions are more likely to reflect inventory, collateral and balance-sheet management than duration conviction, leaving them sensitive to funding costs and regulation.
EXHIBIT #1: BREAKDOWN OF CURRENT U.S. TREASURY OWNERSHIP
Source: BNY
Mutual funds and ETFs hold $46.5bn, or 13.9%, and are likely to be important marginal price-setters during stress. Official-sector holdings total $36.1bn, including $17.9bn held by central banks and sovereign wealth funds.
Foreigners have significant exposure: U.S.-domiciled investors hold $215.9bn, or 58.1%, of the long-dated Treasurys captured by iFlow. Foreign-domiciled clients account for $155.9bn, or 41.9%; EMEA represents $61.4bn, or 18.1%, and APAC a further $43.2bn, or 12.8%. Together, the two regions comprise almost one-third of reported long-end holdings.
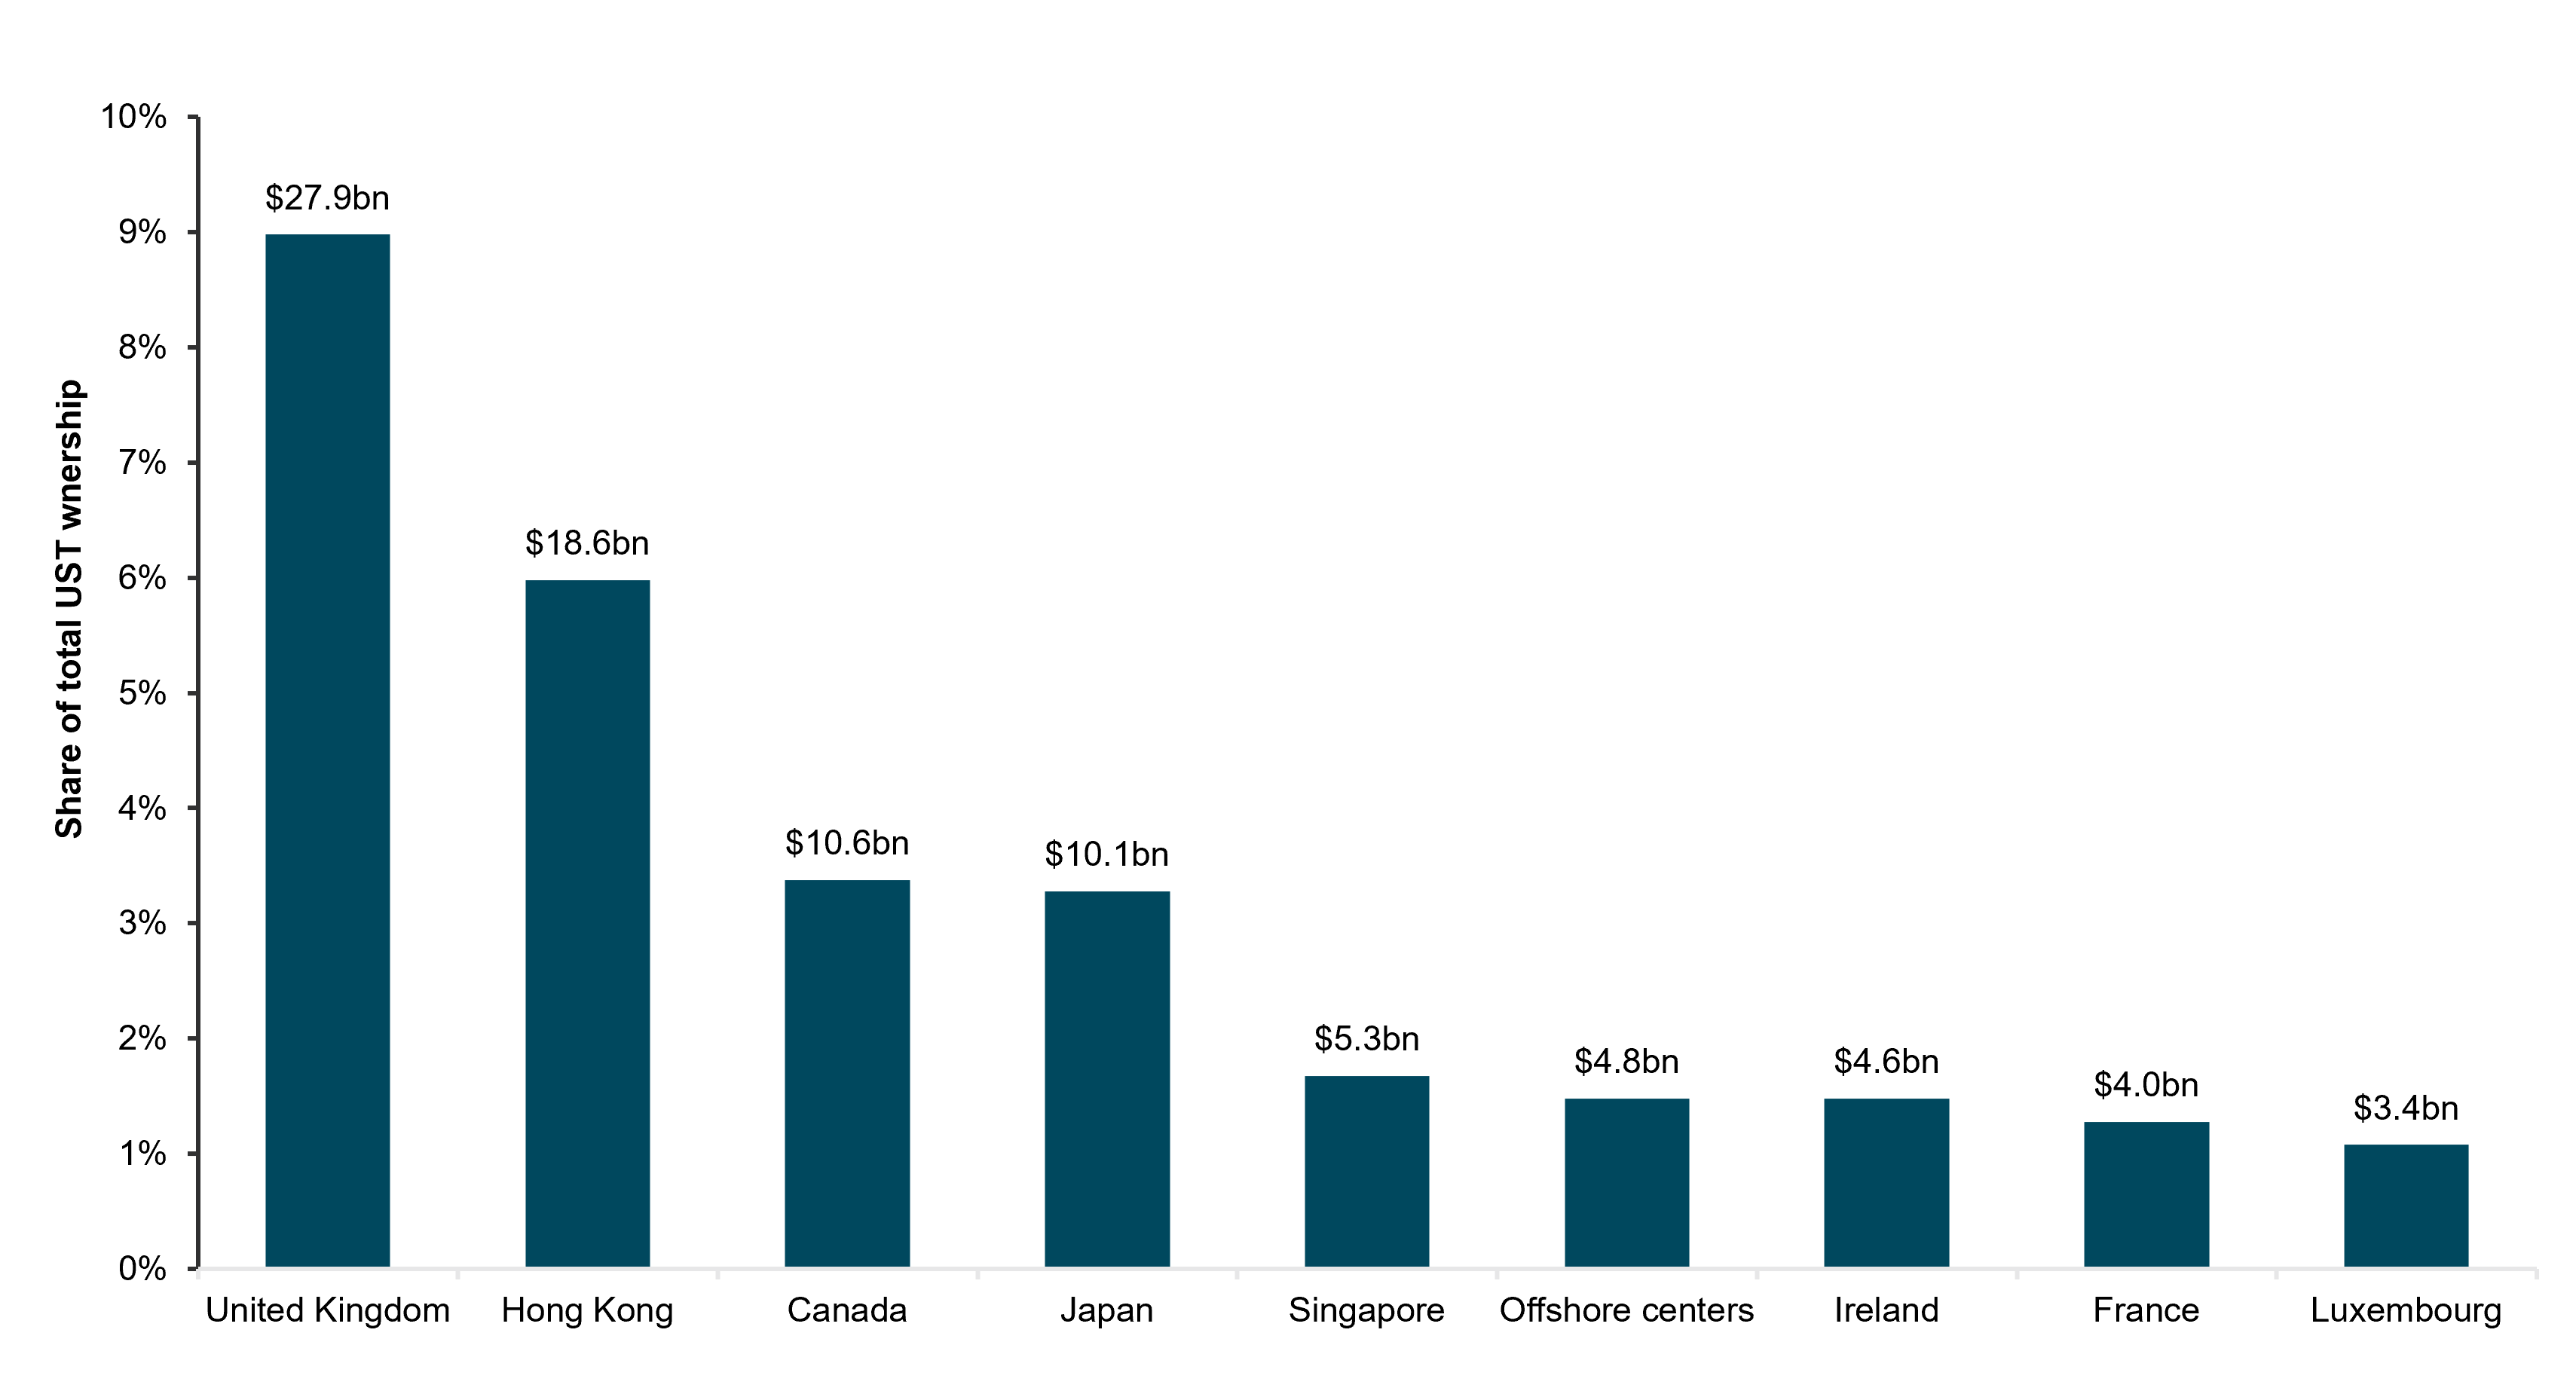
The U.K. leads holdings in our data, followed by Hong Kong. Japan remains an important source of demand beyond the portion visible through this platform, while China is underrepresented because much of its official-sector exposure is held through Federal Reserve custody and other custodial relationships particularly in Europe. These are custodial holdings as much as country-level ownership. The sizeable cross-border share means reserve management, currency intervention and regional liquidity needs can exert an outsized influence on marginal pricing.
EXHIBIT #2: BREAKDOWN OF EXTERNAL U.S. TREASURY HOLDINGS DOMICILE
Source: BNY
Duration lacks conviction: Broader bond flows remain indecisive, while gold-related assets express inflation concerns more clearly than duration. Front-end demand and limited appetite further out the curve are consistent with higher-for-longer rates and an elevated term premium.
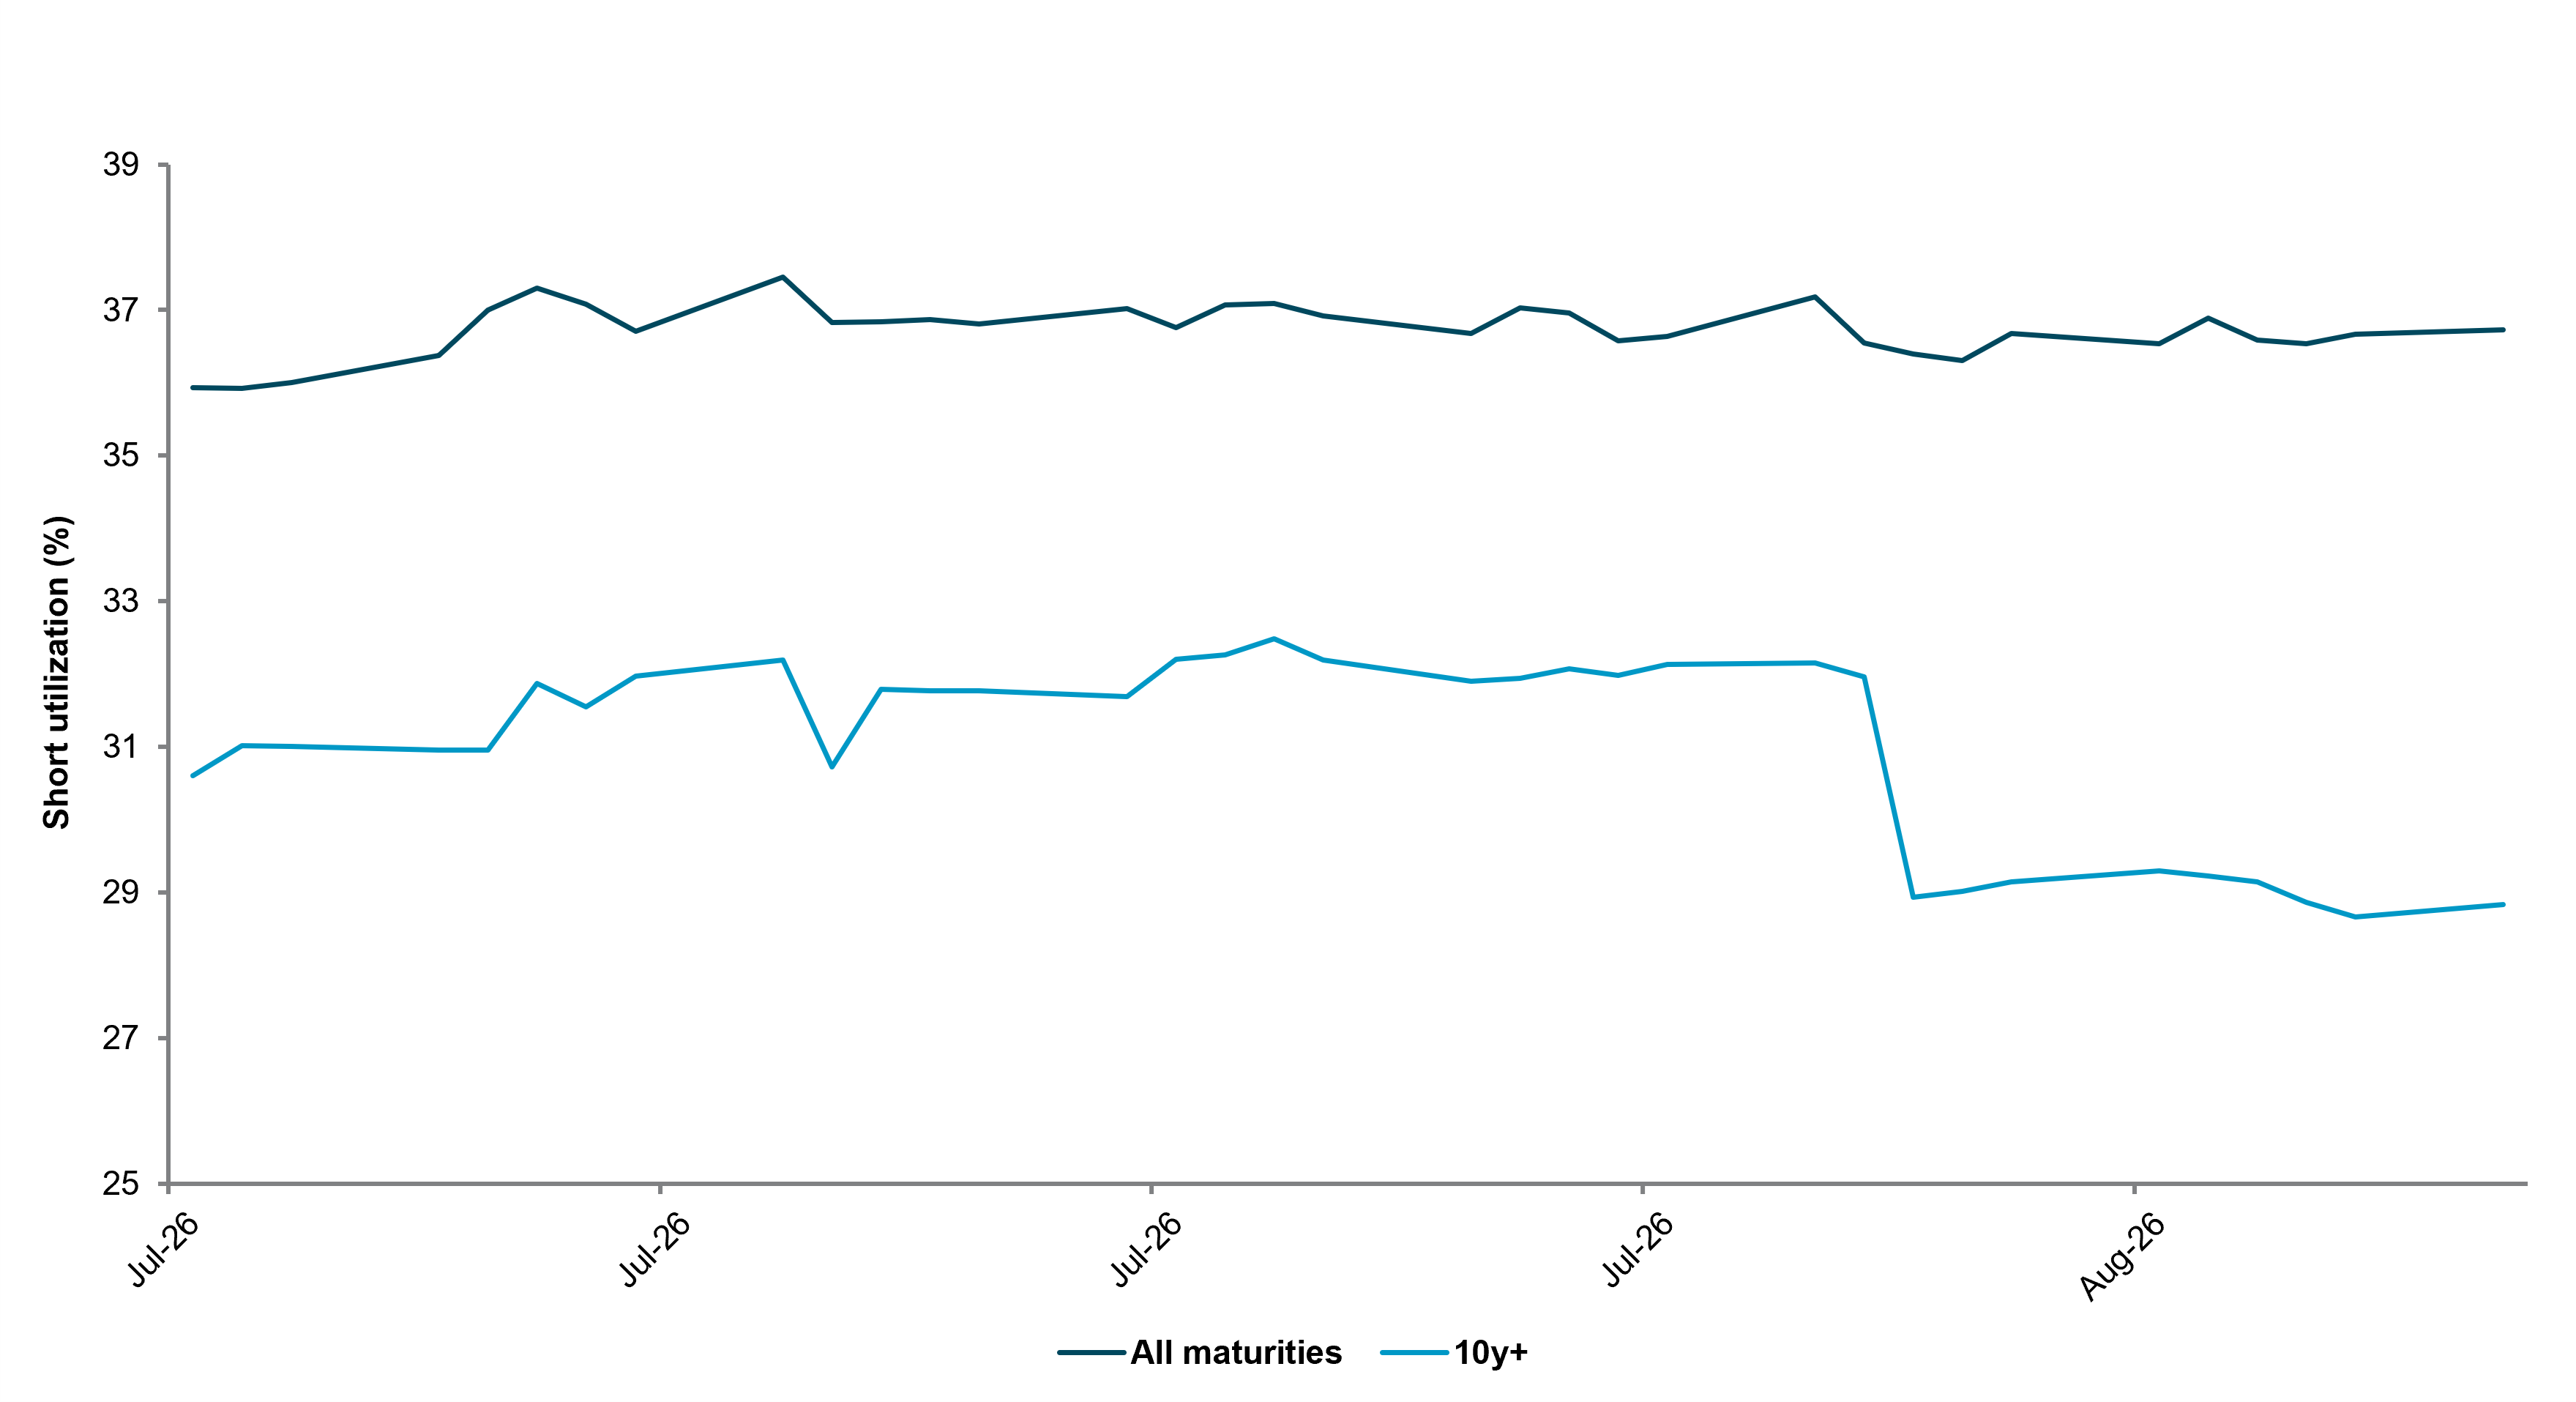
Long-end protection has fallen: Short utilization across Treasury maturities remains unchanged at 37%, while utilization in securities of 10 years or more fell by two percentage points — around 10% in relative terms — between the Fed meeting and late last week. Investors took profit on long-end protection and did not rebuild it as the curve steepened. The subsequent rally therefore cannot be explained solely by cash-Treasury short covering; crowded steepener exposure is more likely concentrated in curve and derivative positions. Limited protection could leave the curve vulnerable to renewed steepening if fiscal and inflation concerns persist.
EXHIBIT #3: MARKETS LESS HEDGED FOR STEEPENING IN LONG-DATED USTS
Source: BNY
Flattening still needs validation: iFlow suggests the initial flattening was partly positioning-driven rather than evidence of a durable shift into long-end duration. Buybacks could force further steepener unwinds, but sustained flattening requires long-end demand to strengthen alongside already robust demand for bills and cash.
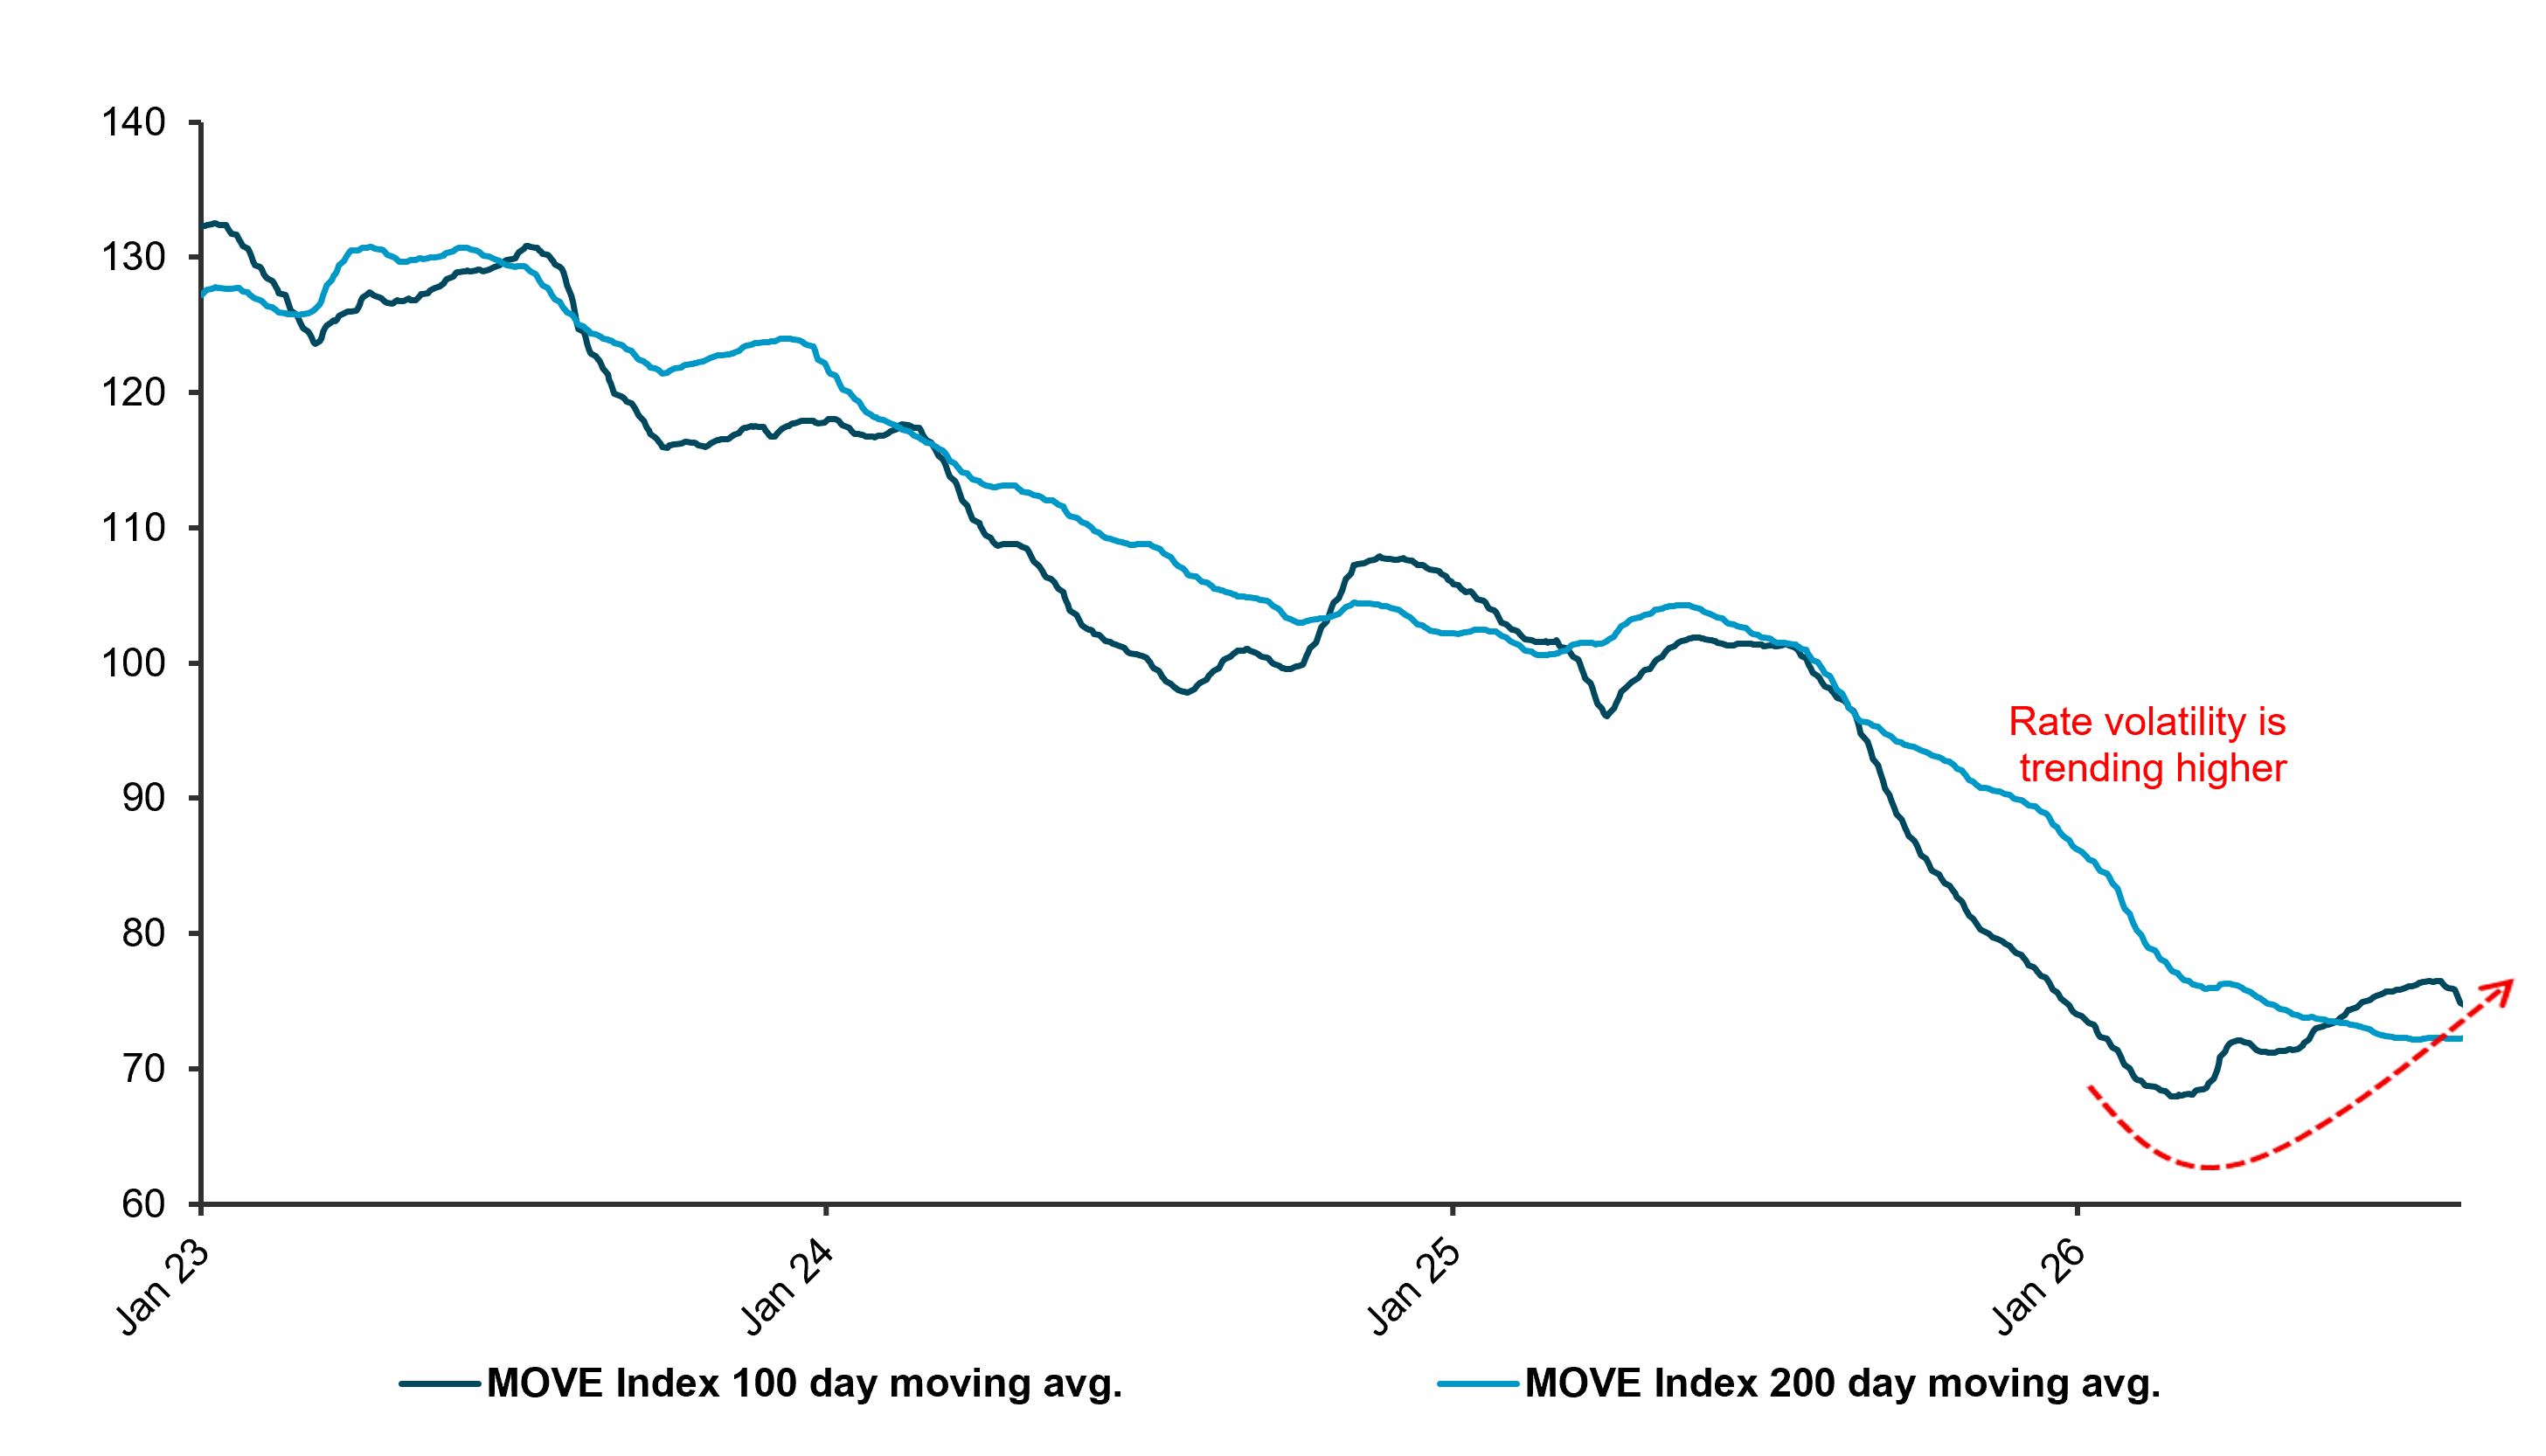
Rates volatility is at multiyear lows: The announcement complicates our view that the multiyear decline in rates volatility is approaching an end. Treasury can contain disorderly yield increases which should put short-term downward pressure on vol, but uncertainty over its reaction function (not to mention the Fed’s), inflation, fiscal supply and global liquidity could generate larger moves in both directions.
Equities remain exposed: As we’ve written, Since 2023, the S&P 500 has had an approximately -84% correlation with the MOVE Index, with similarly strong relationships across technology and semiconductor equities. Longer-duration growth assets are especially vulnerable if volatility rises, even if Treasury intervention initially supports equities.
EXHIBIT #4: RATE VOLATILITY CONTINUES RISE
Source: BNY, Bloomberg
The signal outweighs the size: The market response was considerably larger than the direct demand implied by the additional buybacks. Treasury’s willingness to adjust operations between scheduled refunding announcements supports near-term duration and curve flattening, particularly given stretched positioning.
FX pressures can reach Treasurys: International developments this year have demonstrated the Treasury market’s sensitivity to sudden liquidity demands. The energy-cost surge raised the risk that reserve managers would sell dollar assets to meet funding requirements. U.S. efforts to support the yen have since highlighted the connection between currency intervention and Treasury liquidity.
FIMA limits forced selling: Treasury Secretary Bessent’s request that the Federal Reserve expand the Foreign and International Monetary Authorities Repo Facility reflected this concern. Greater access would allow Japanese authorities to raise dollars against Treasury holdings rather than sell them to finance yen intervention.
How are they funding it? If buybacks are meaningful rather than merely a signaling tool, Treasury will need to fund them through increased issuance of bills or short- to medium-dated coupons, but most likely bills given their issuance patterns over the past several refunding cycles. We think they are unlikely to be sustainably funded by drawing down the TGA. This would support long-end liquidity while shifting funding to the front end, shortening the government’s effective duration and reinforcing curve flattening.
Real yields are the fault line: Dollar weakness and gains in gold and Bitcoin show how quickly markets respond to measures that could erode U.S. real yields. Those yields have been a central source of dollar support — and could become its principal vulnerability if investors question policymakers’ commitment to them.
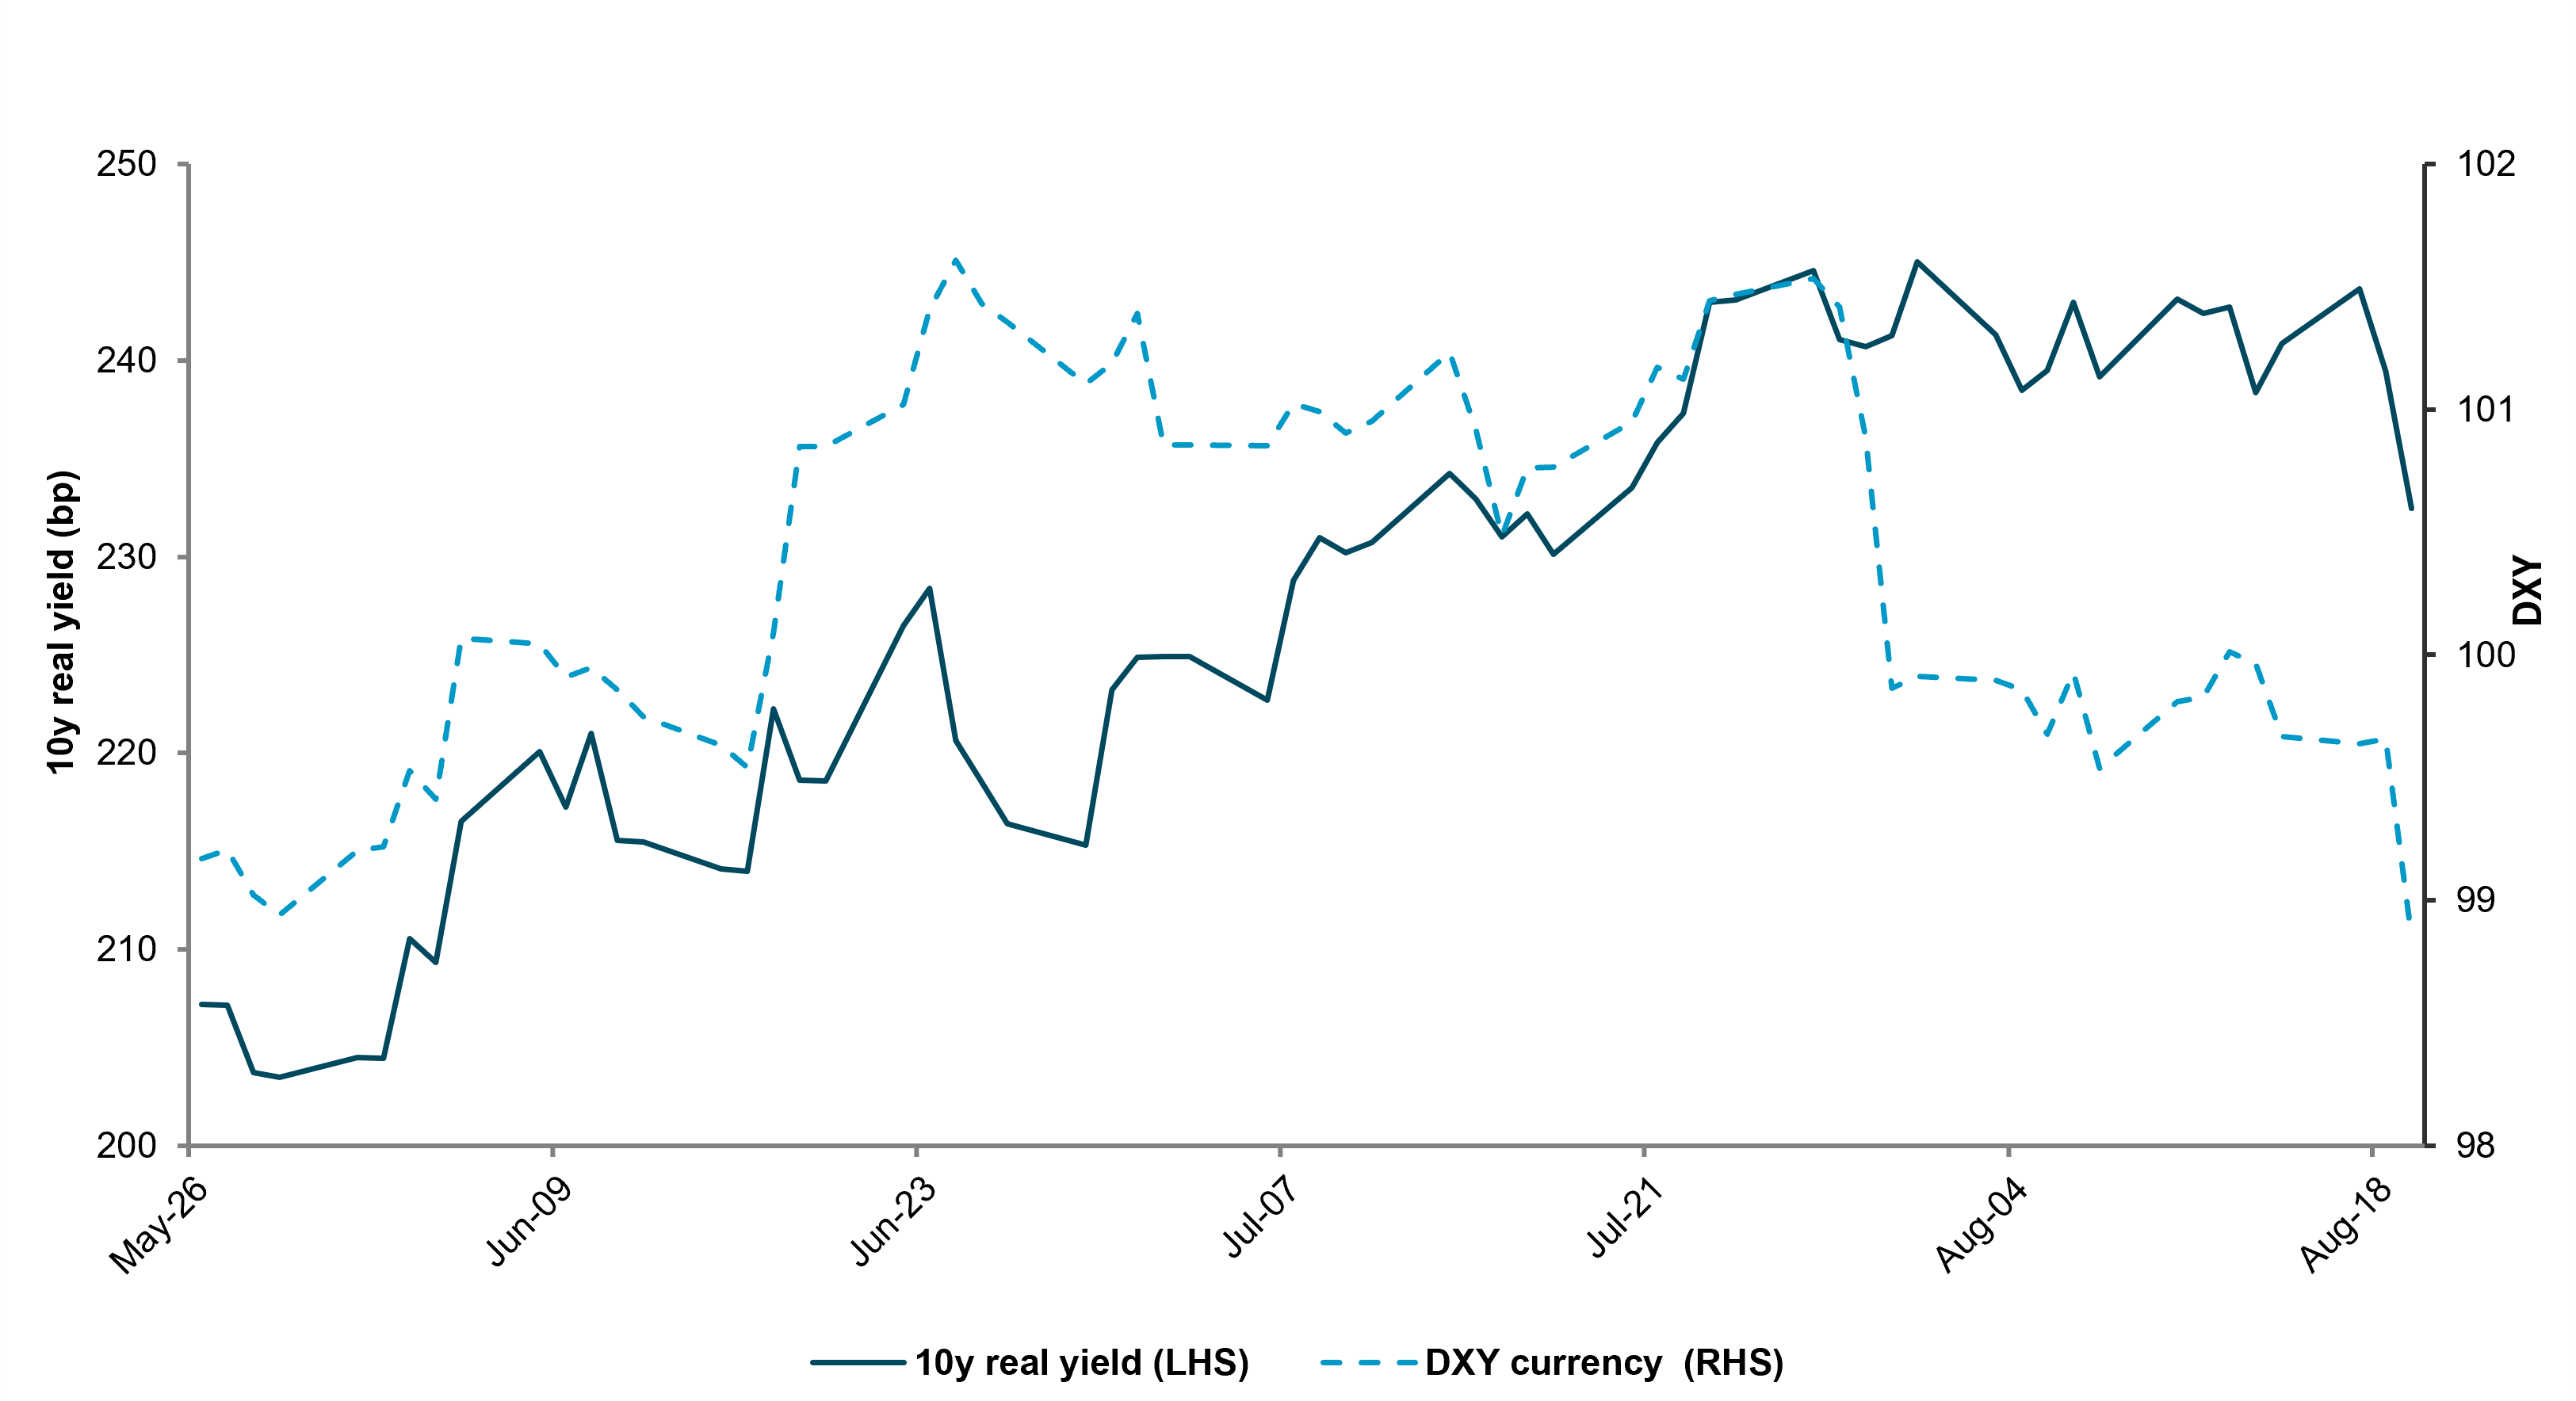
Inflation expectations are warning: The 5y5y forward inflation breakeven rose only around 15bp from pre-conflict levels through the first half of May and fully normalized after the June ceasefire. It then increased by more than 15bp in the second half of July and remains above its conflict peak. DXY’s relationship with the 10-year real yield suggests the dollar adjusted lower following the July FOMC, as front-end developments matter most for FX. Pressure on the long end compounds the threat to real-rate support.
EXHIBIT #5: THE DOLLAR HAS ALREADY ADJUSTED TO THE FRONT END
Source: BNY, Bloomberg
The dollar reaction is a warning: If efforts to contain nominal yields coincide with rising inflation expectations, real yields can decline even without a sustained fall in nominal rates. That would challenge the support high U.S. real yields and tighter financial conditions have provided the dollar during correlated asset sell-offs.
Tactically bullish duration: Treasury’s decision could extend the position-led long-end rally and curve flattening. Its importance lies less in purchase volumes than in the willingness to respond when liquidity deteriorates.
Watch real rates: Moves in the dollar, gold and Bitcoin show that efforts to restrain nominal yields may be interpreted as weakening the U.S. real-rate advantage, disrupting relationships between yields, risk sentiment and the dollar.
November is the test: An extension or further increase in buybacks at the November 4 refunding would strengthen perceptions of a policy backstop for the long end — but could deepen doubts about the durability of the dollar’s real-yield support.
Call to action: Maintain a tactical long-duration and flattening bias, but monitor long-end flows, real yields, inflation expectations and Treasury’s funding mix. Add if buybacks expand and demand strengthens; reduce duration if inflation rises and real yields or the dollar fall. The November 4 refunding is the key test.