Joint intervention buys time, not credibility
Special Report

Geoff Yu
Time to Read: 7 minutes
Bottom Line
Coordinated U.S.-Japan intervention has raised the stakes and can drive a tactical yen recovery, but it will not deliver lasting appreciation. That requires Tokyo to act decisively: give the BoJ room to normalise, restore fiscal credibility, and revive structural reform. Until that happens, markets will keep testing Japan’s resolve.
What Happened
Friday’s reported U.S. intervention alongside Japan was historic and confirmed as coordinated by both governments on Monday. Press reports said the Federal Reserve Bank of New York sold euros to buy yen on behalf of the Treasury after Japan’s unilateral intervention began on Thursday and after Treasury Secretary Bessent called the yen “very undervalued.” His later remarks about “close co-ordination” reinforced that message.
BIGGEST 2-DAY EURJPY MOVE YEAR-TO-DATE AFTER U.S. INTERVENES IN CROSS
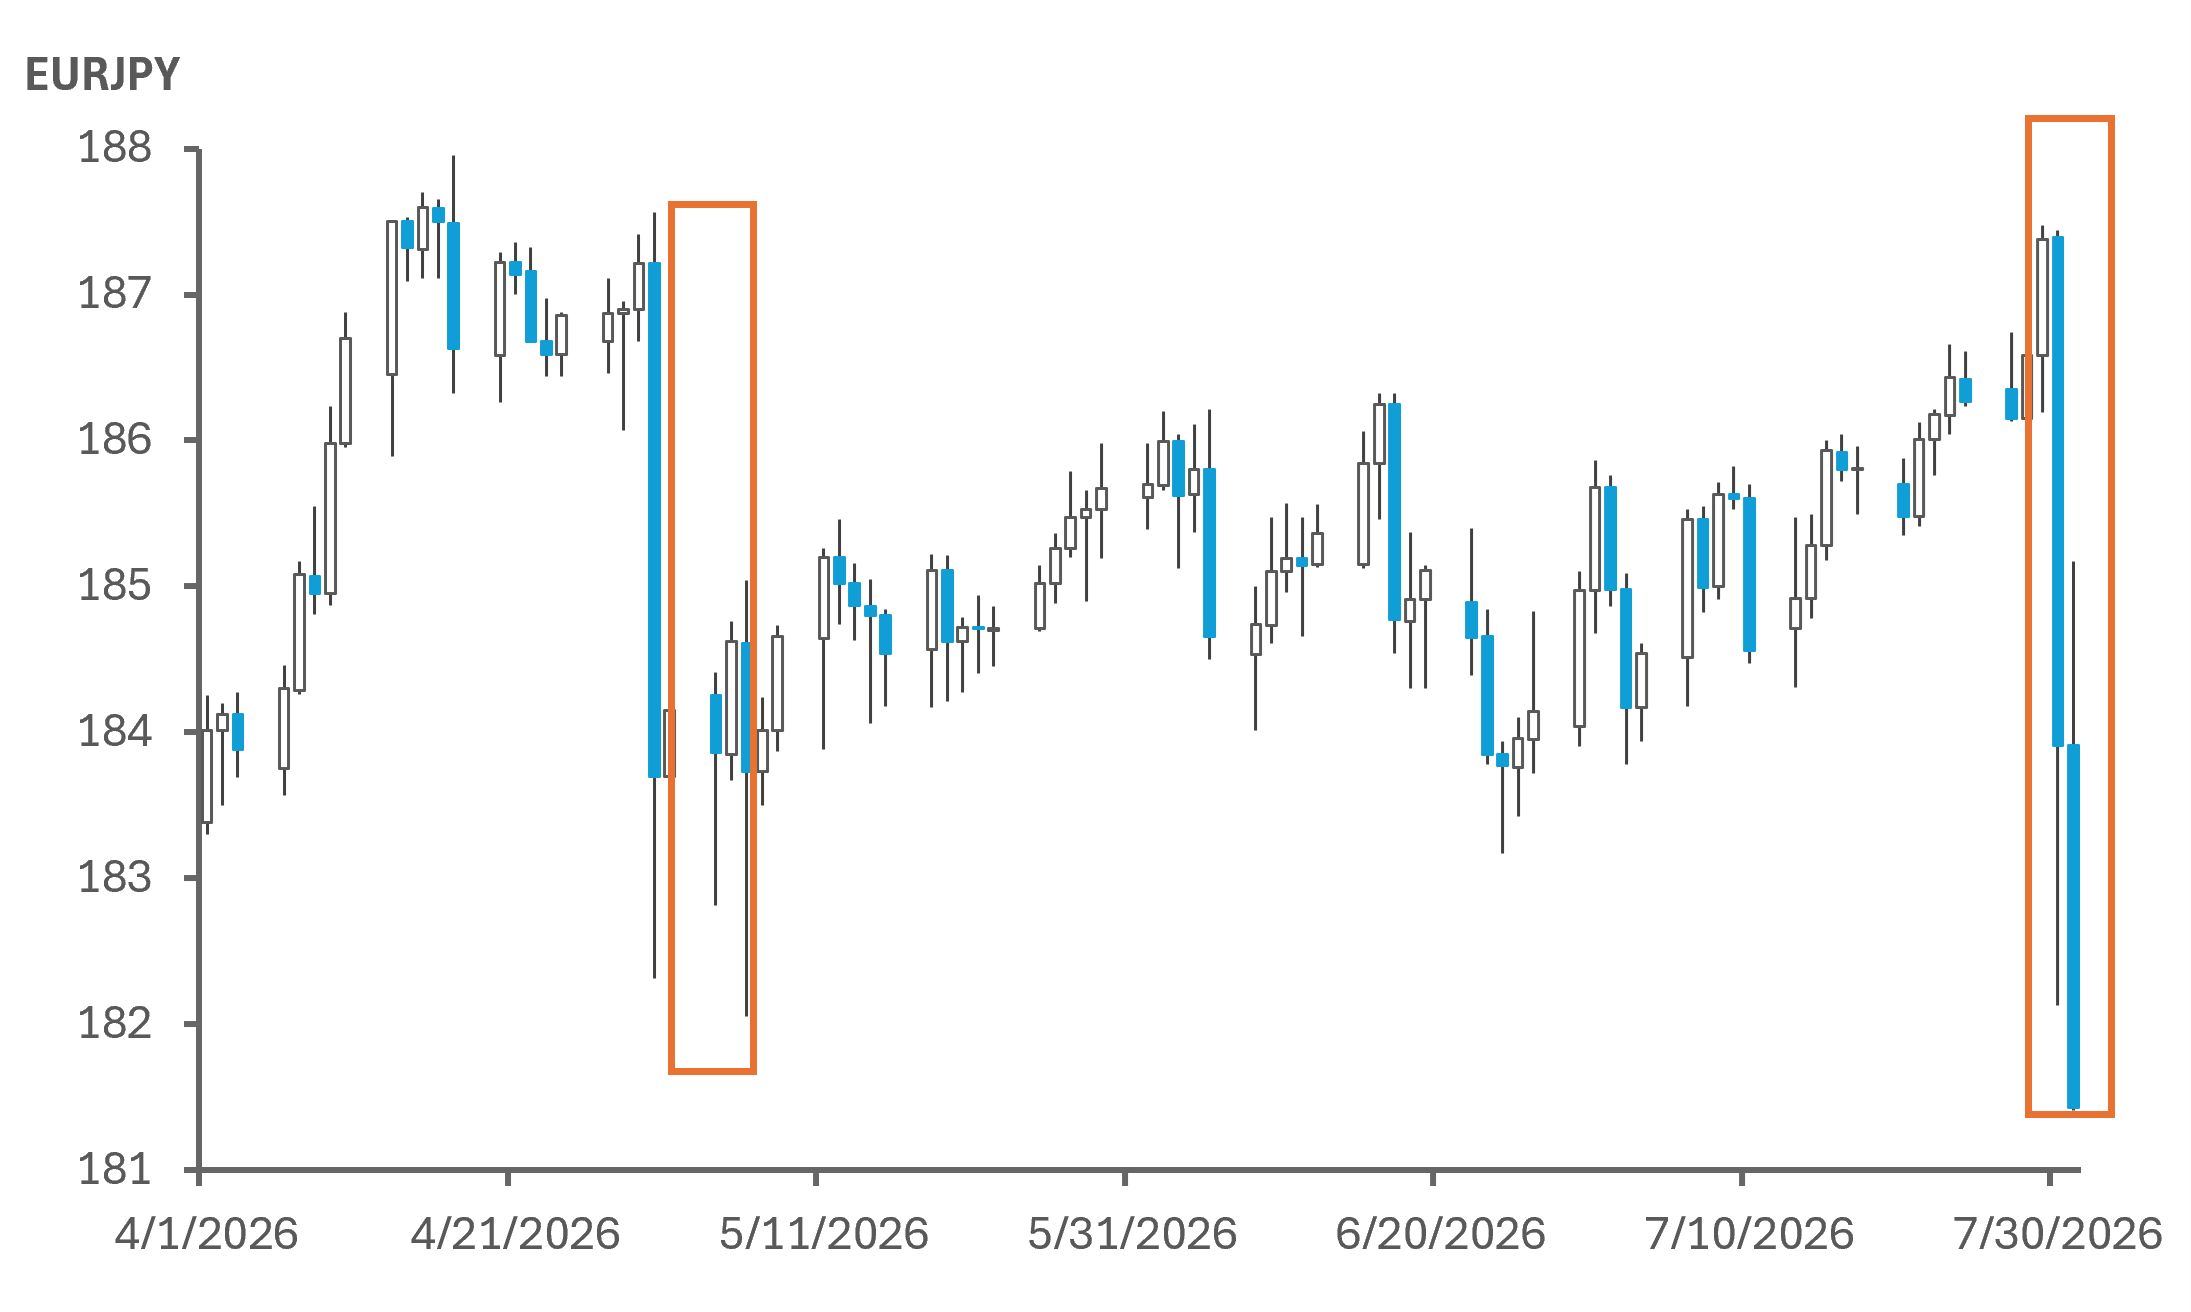
Source: BNY, Bloomberg; intervention phases highlighted
Why It Matters
This was a powerful signal, not a durable solution. EURJPY was the practical intervention channel because most deployable U.S. FX reserves sit in euros, and it avoided a direct USDJPY trade that would look like overt dollar weakening. But the Eurozone accounts for only 8.5% of Japan’s trade, so the move was more symbolic than economically decisive. Intervention can trigger a tactical rebound in the yen, especially with light positioning, but it cannot by itself deliver a lasting change in Japan’s effective exchange rate.
Treasury Constraints
The U.S. Treasury does not have the firepower to lead a sustained market fight. As of July 24, 2026, official U.S. reserve assets excluding gold totaled $250.9bn, but only about $37bn was liquid and directly usable for intervention, including just $14.4bn in euro securities, and $11.5 in euro deposits. Most of the rest sits in IMF-related positions that are not relevant here. Reuters news captured a hand-written note written by Secretary Bessent, aiming for $5bn - $10bn in JPY purchases as a “to do”. By contrast, Japan’s intervention on Thursday alone was estimated at roughly $53bn, on top of $73bn spent in May. The scale mismatch is decisive.
U.S. OFFICIAL RESERVE ASSETS STABLE BUT AT LOW LEVELS
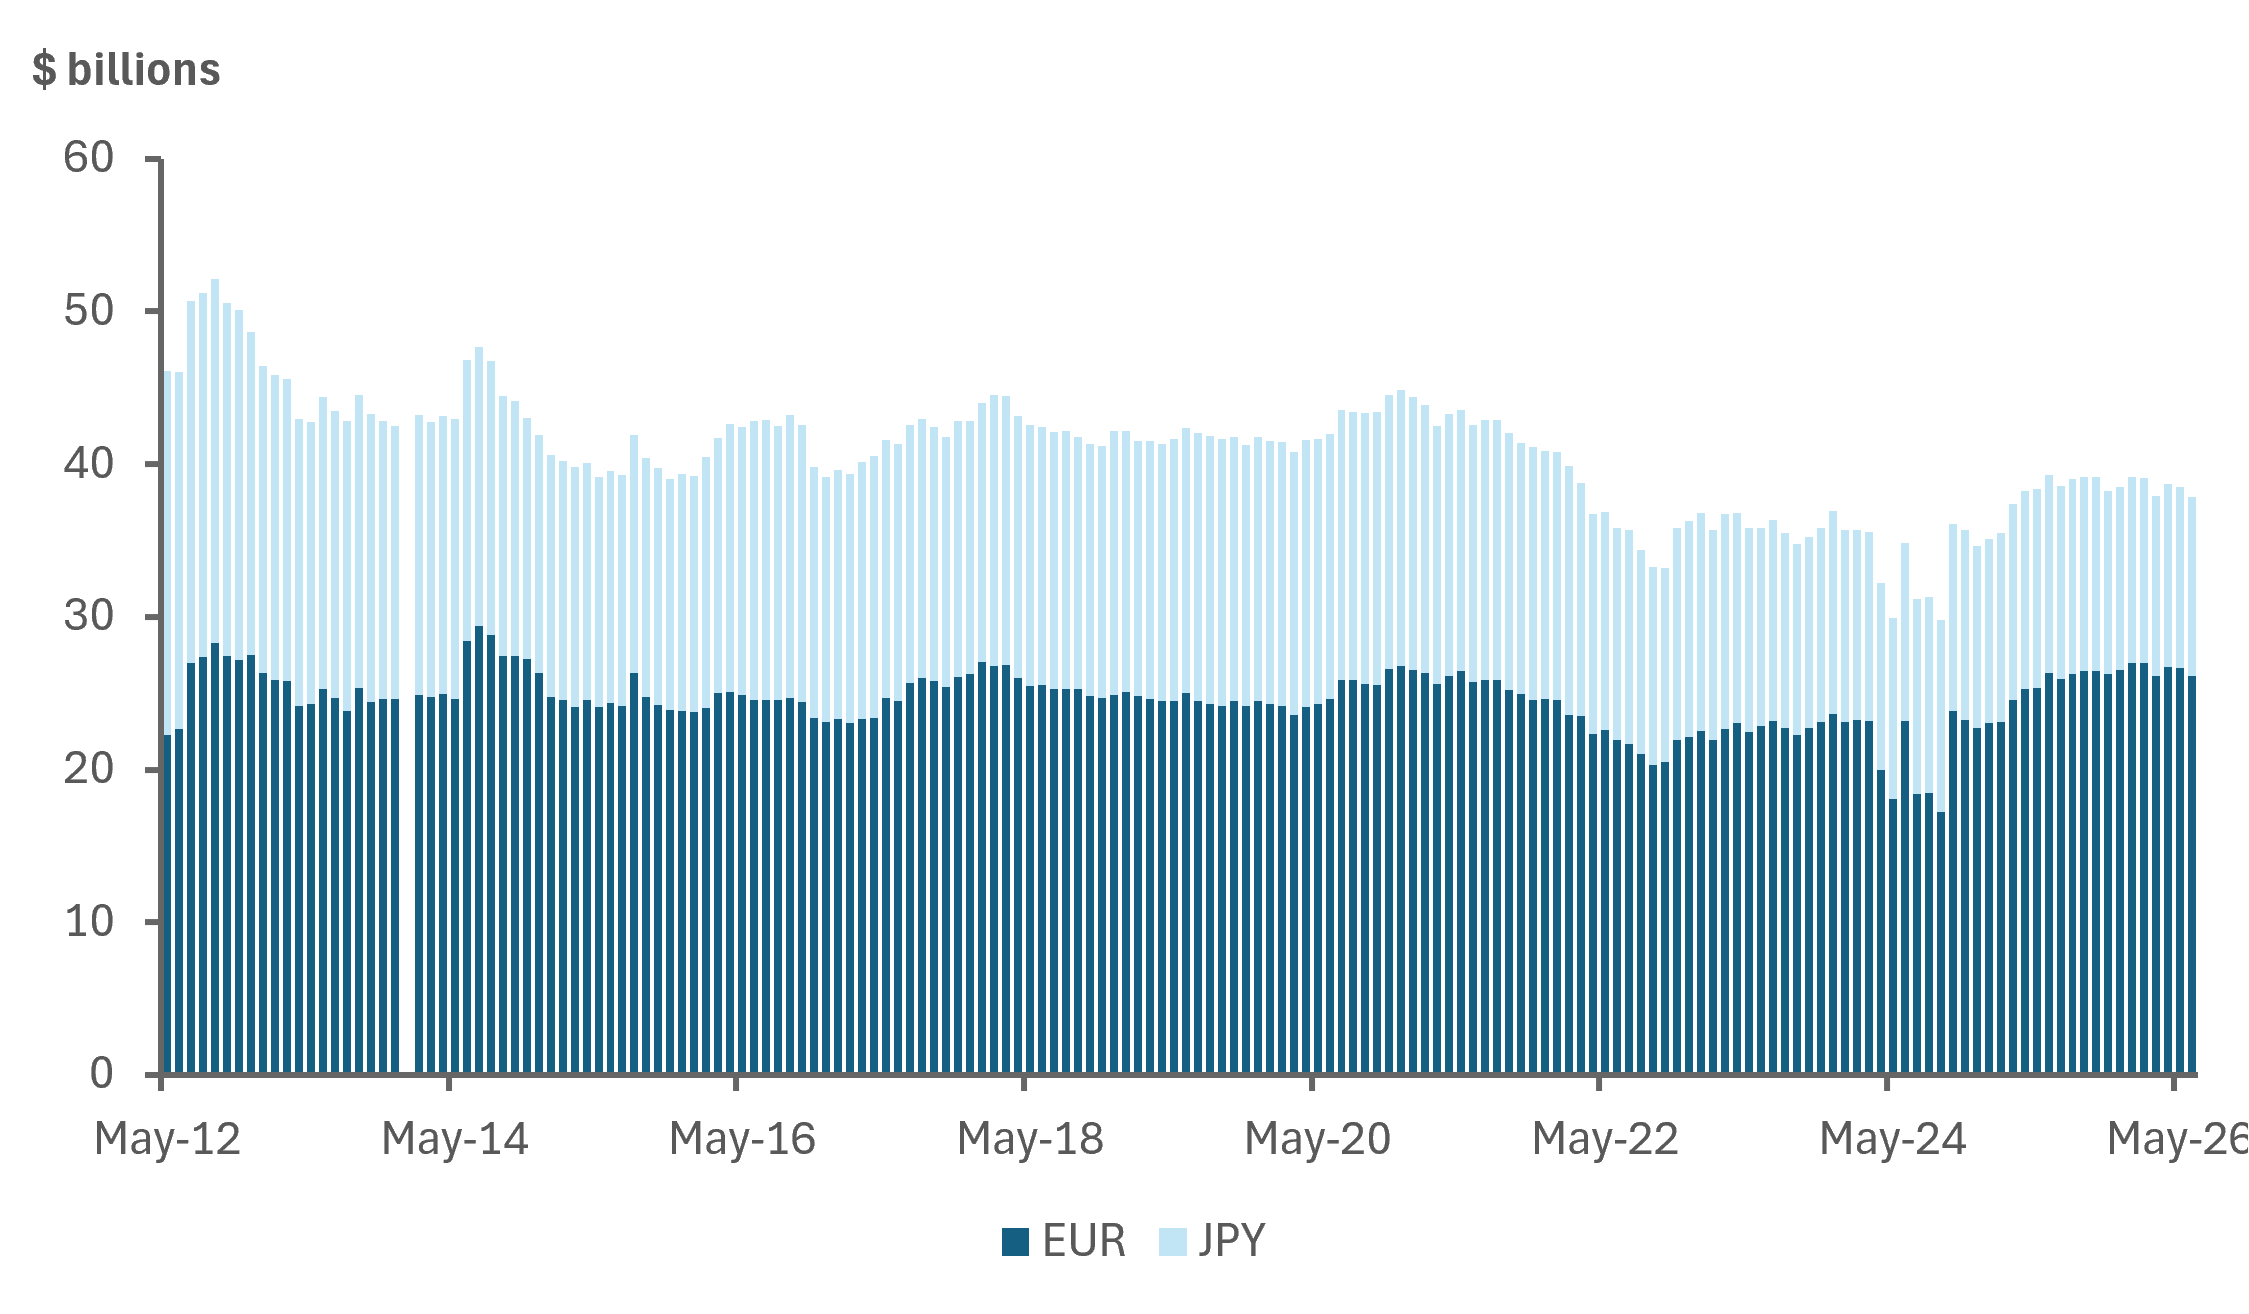
Source: BNY, U.S. Treasury
Operational Logic
EURJPY was the most expedient workable path, but it does little to change the bigger currency picture. Direct action in USDJPY would amount to weakening the dollar and would cut against the long-standing U.S. strong-dollar posture. Moving through EURJPY avoided that political problem and may have amplified Friday’s move, but it did not address the exchange rates that matter most for Japan’s trade competitiveness. A sustained yen recovery ultimately requires weakness in USDJPY and CNYJPY, and China is not joining that effort.
BASED ON SHARE OF TOTAL TRADE, EUROZONE NOT A MAJOR TRADING PARTNER FOR JAPAN
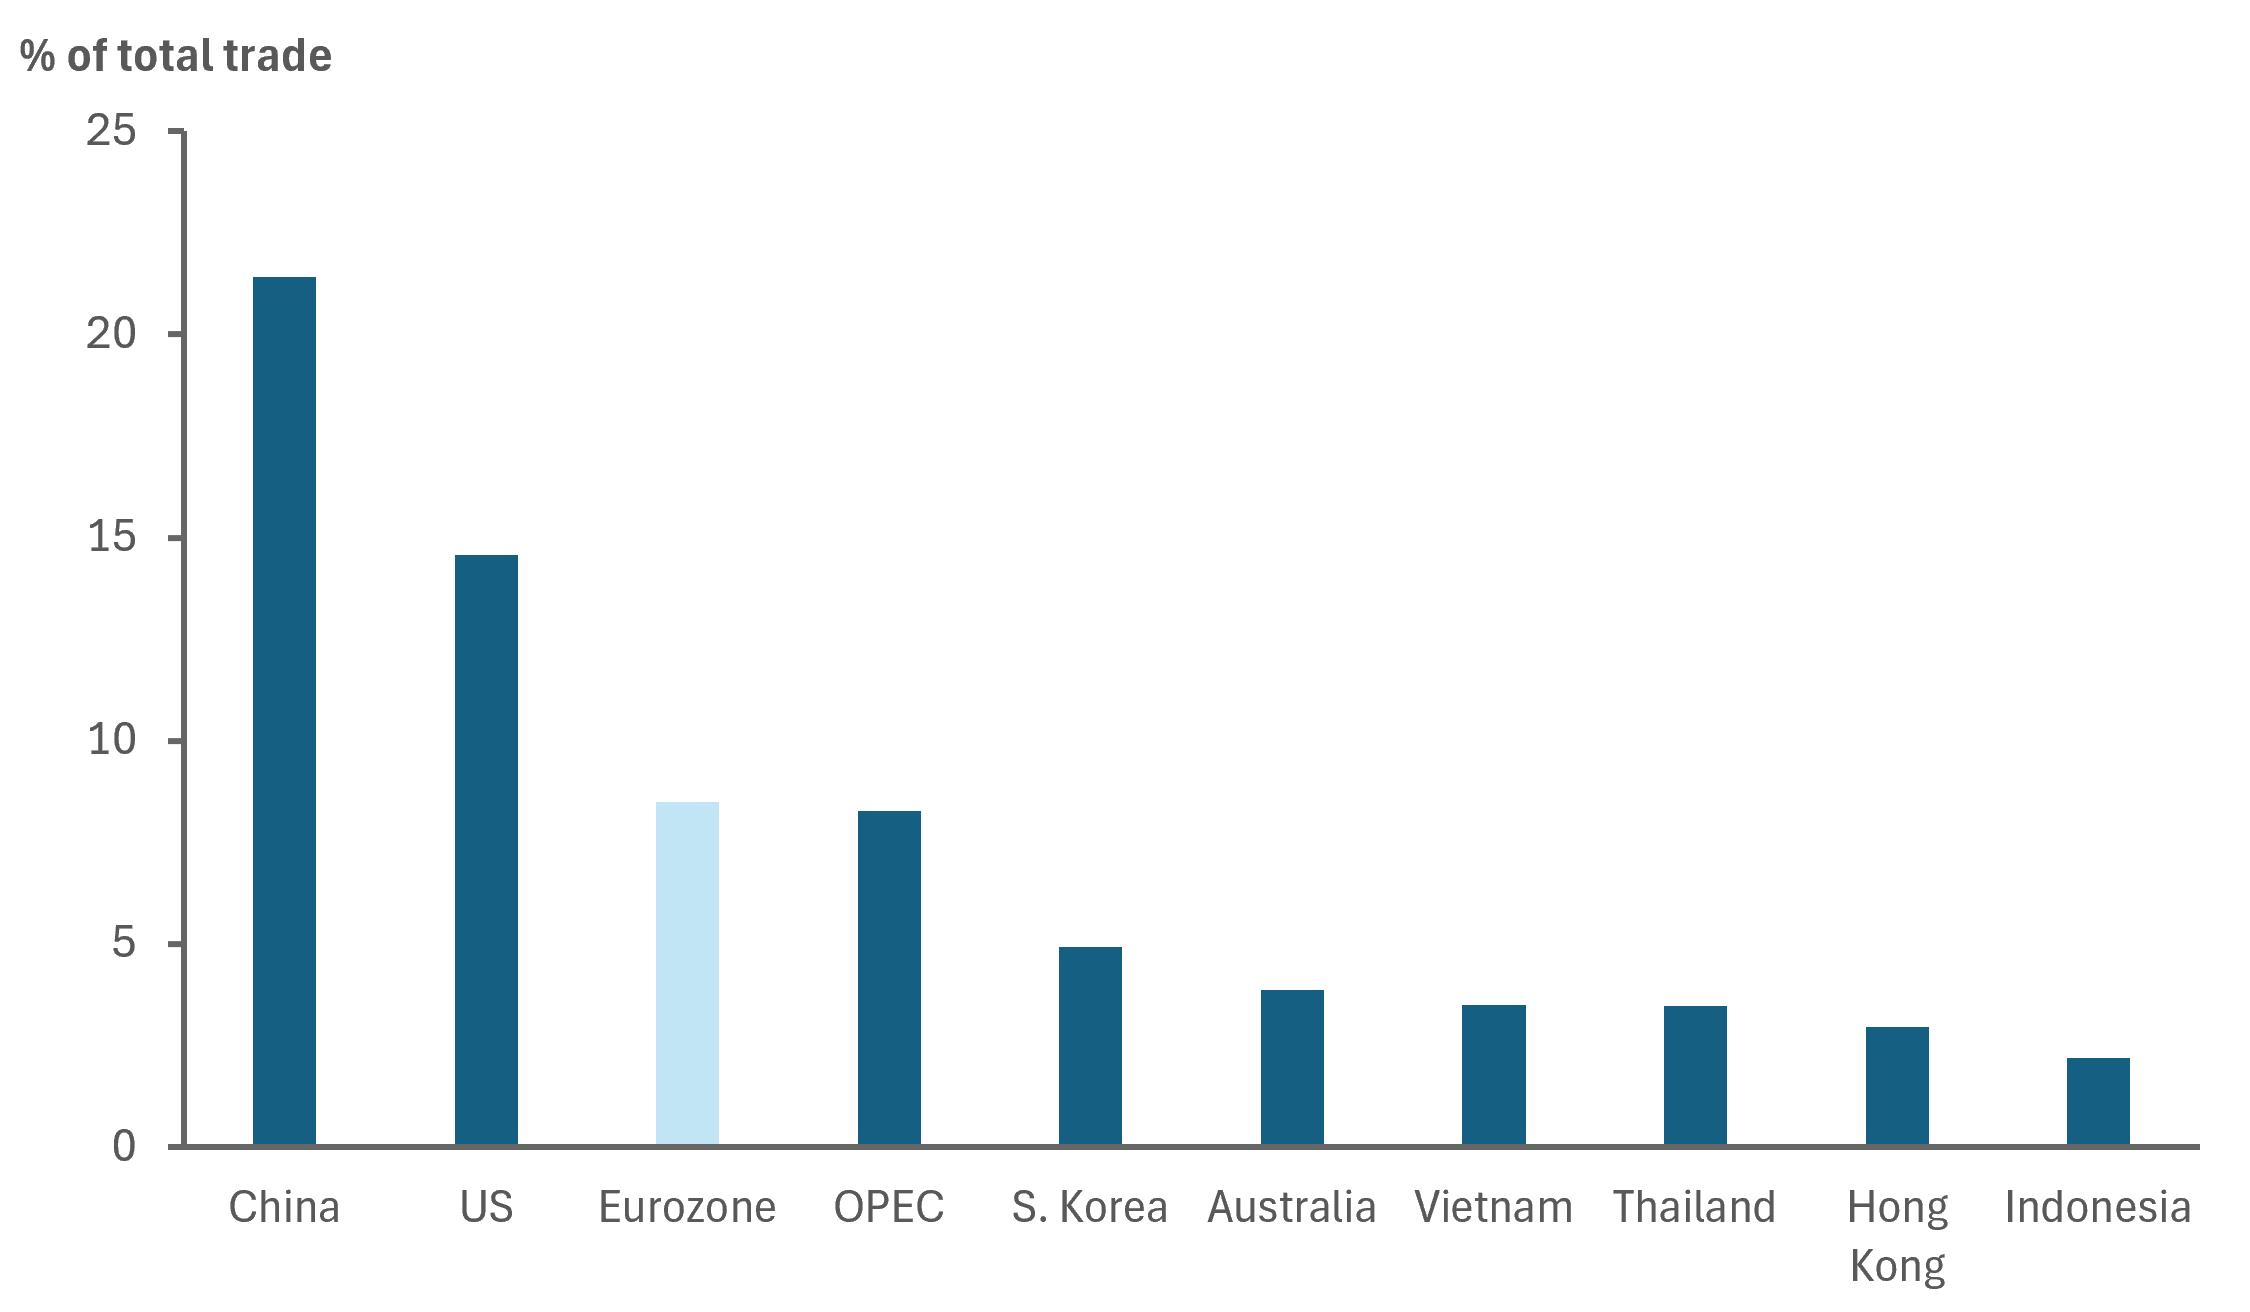
Source: BNY, Bloomberg
Treasury Market Signal
U.S. participation also helped calm fears around Japan’s Treasury holdings. Japan may have spent as much as $150bn of reserves defending the yen over the past three months, and it remains the largest foreign official holder of U.S. Treasurys at just over $1.1tn, roughly one-eighth of all foreign holdings. With China’s holdings falling and concern already building over marginal buyers of U.S. debt, a visible U.S. show of support reduced the immediate risk that Japan would need to sell Treasurys aggressively to fund intervention.
JAPAN THE BIGGEST OFFICIAL HOLDER OF TREASURYS; INTERVENTION PRESENTS LIQUIDATION RISK
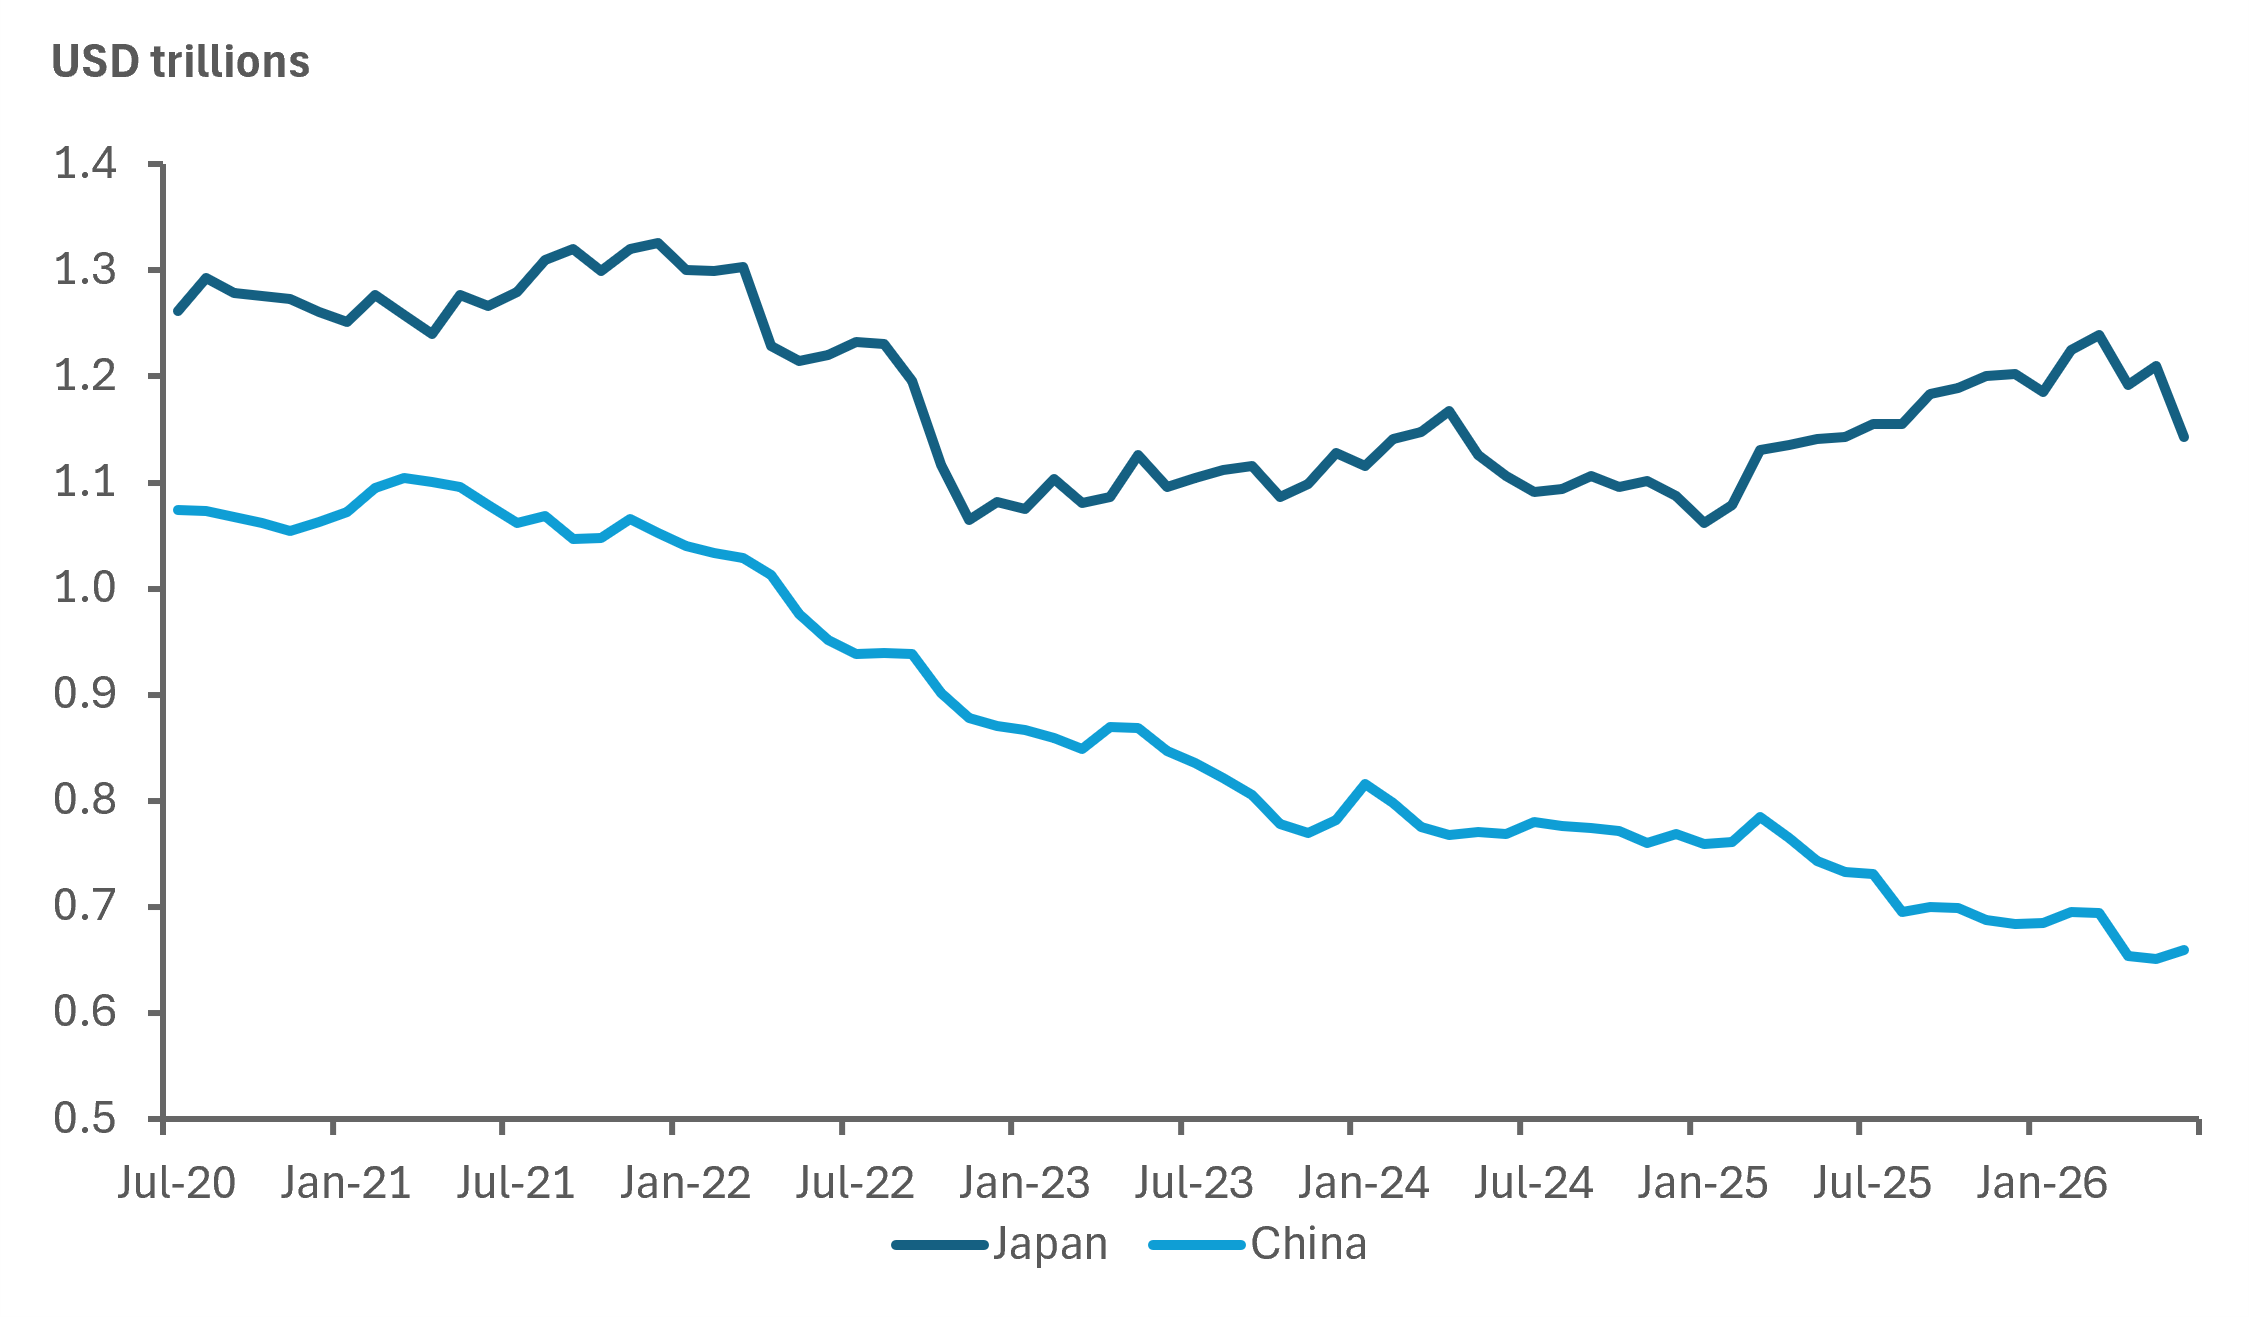
Source: BNY, Bloomberg, Federal Reserve
Positioning Setup
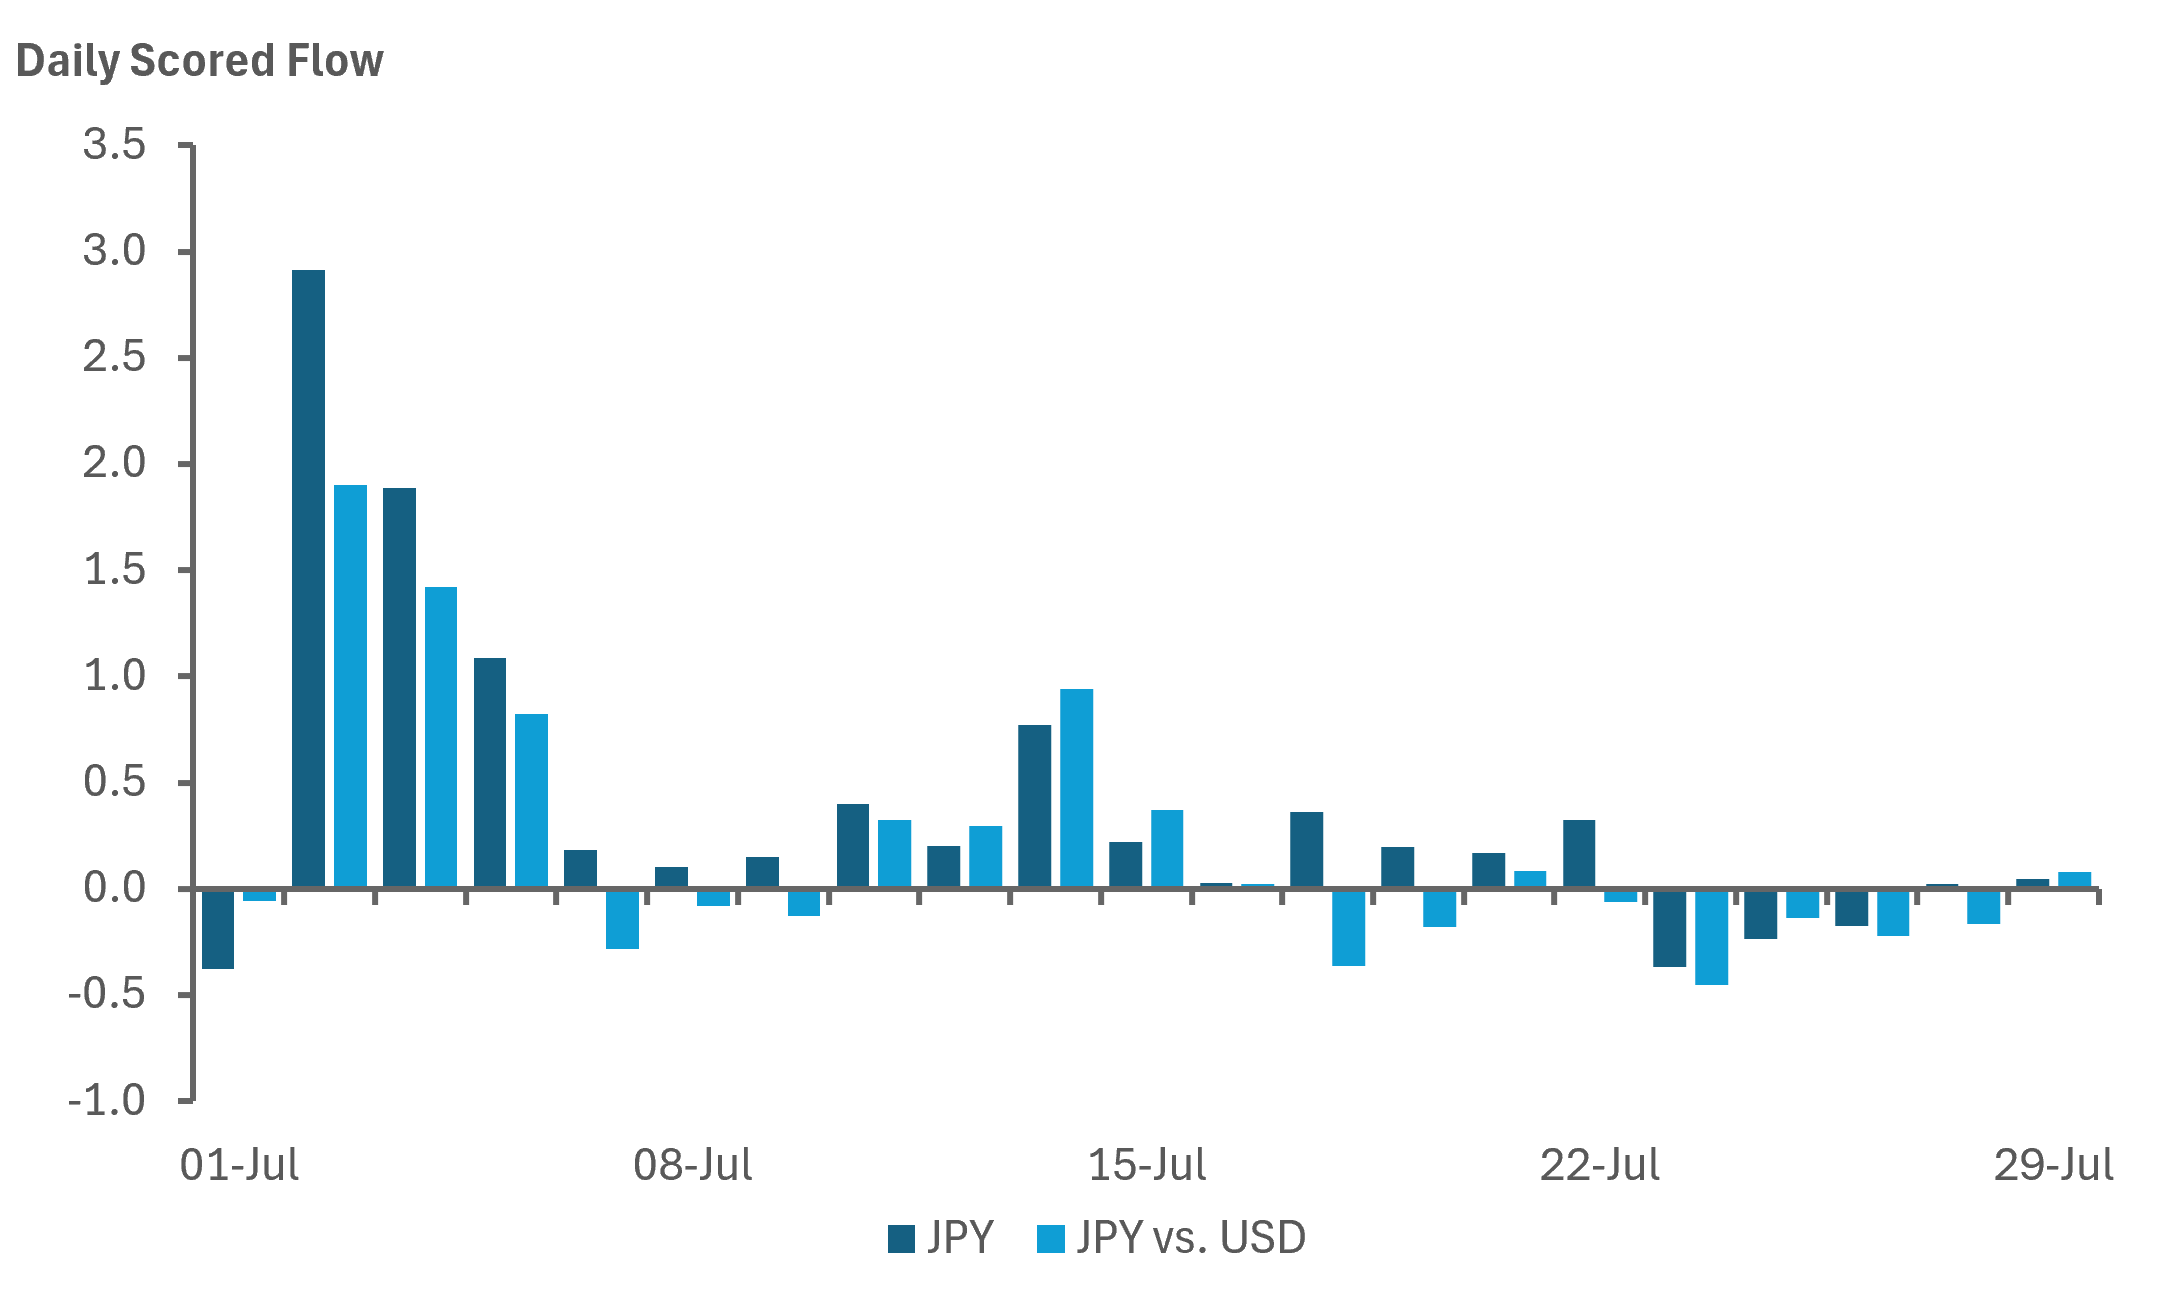
The backdrop was weak enough for intervention to have impact. The yen had already recovered close to 2% on Friday morning before the BoJ decision, underscoring how ineffective the previous day’s large-scale intervention had been on its own. Over the prior three months, aggregate JPY flows were mildly negative, USDJPY stayed better bid, and spot purchases lacked consistency. Foreign investors were still net long yen and net short USDJPY, but both positions had been cut roughly in half since June. That leaves room for investors to rebuild yen longs if authorities prove this was not a one-off.
LIGHT CROSS-BORDER JPY FLOWS AND POSITIONING AMPLIFIES INTERVENTION EFFECTIVENESS
Source: BNY
Liquidity Window
Soft volumes and light holdings increase the odds of a sharper short-term move. Foreign demand for cash and short-term Japanese instruments weakened sharply through June, recovered only unevenly in July, and turned back to meaningful outflows before the decision. Spot demand was modest and inconsistent, while FX volumes also softened. In that kind of low-conviction market, a historically significant U.S. intervention and the threat of follow-through can move price disproportionately. But price action must broaden into stronger buying across spot, forwards, and short-term instruments to last.
JGB Support
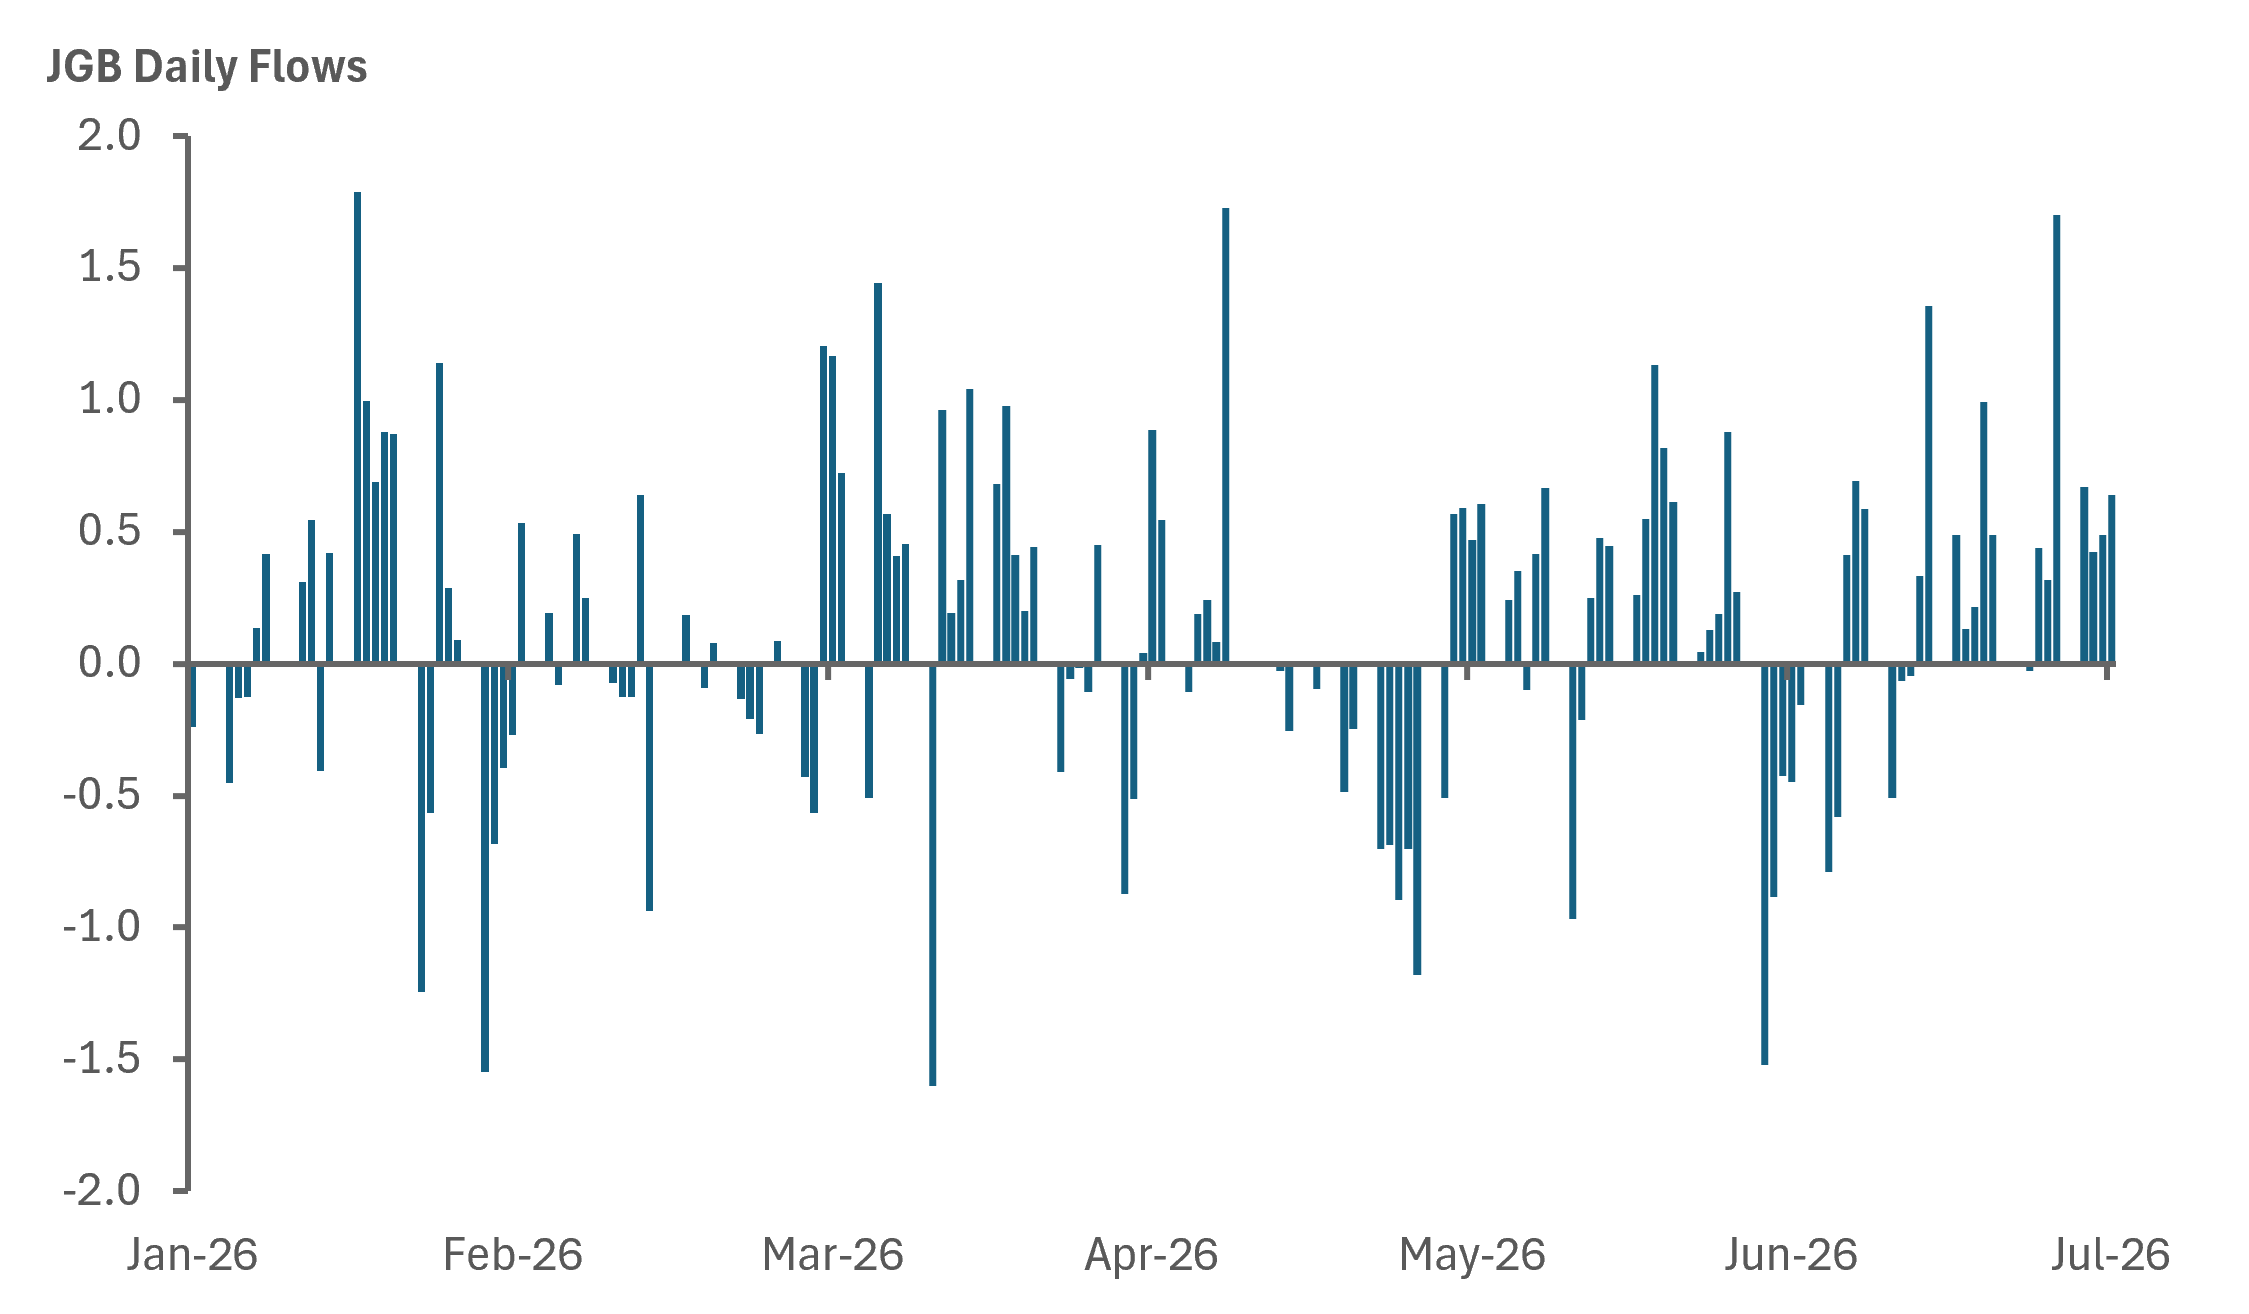
Japanese government bonds remain the clearest beneficiary. Higher long-end yields have attracted steady foreign buying even while yen and equity demand weakened. Much of that demand is hedged, which has limited direct currency support, but intervention changes that calculus by making unhedged or retained yen exposure less risky. Firmer BoJ language on inflation and a faster tightening path would reinforce that shift. If stronger yen dynamics also import disinflation and lift real yields, JGB inflows can become a more direct support for the currency.
CROSS-BORDER FLOW MOMENTUM IN JGBS GRADUALLY INCREASING
Source: BNY
Investor Mix
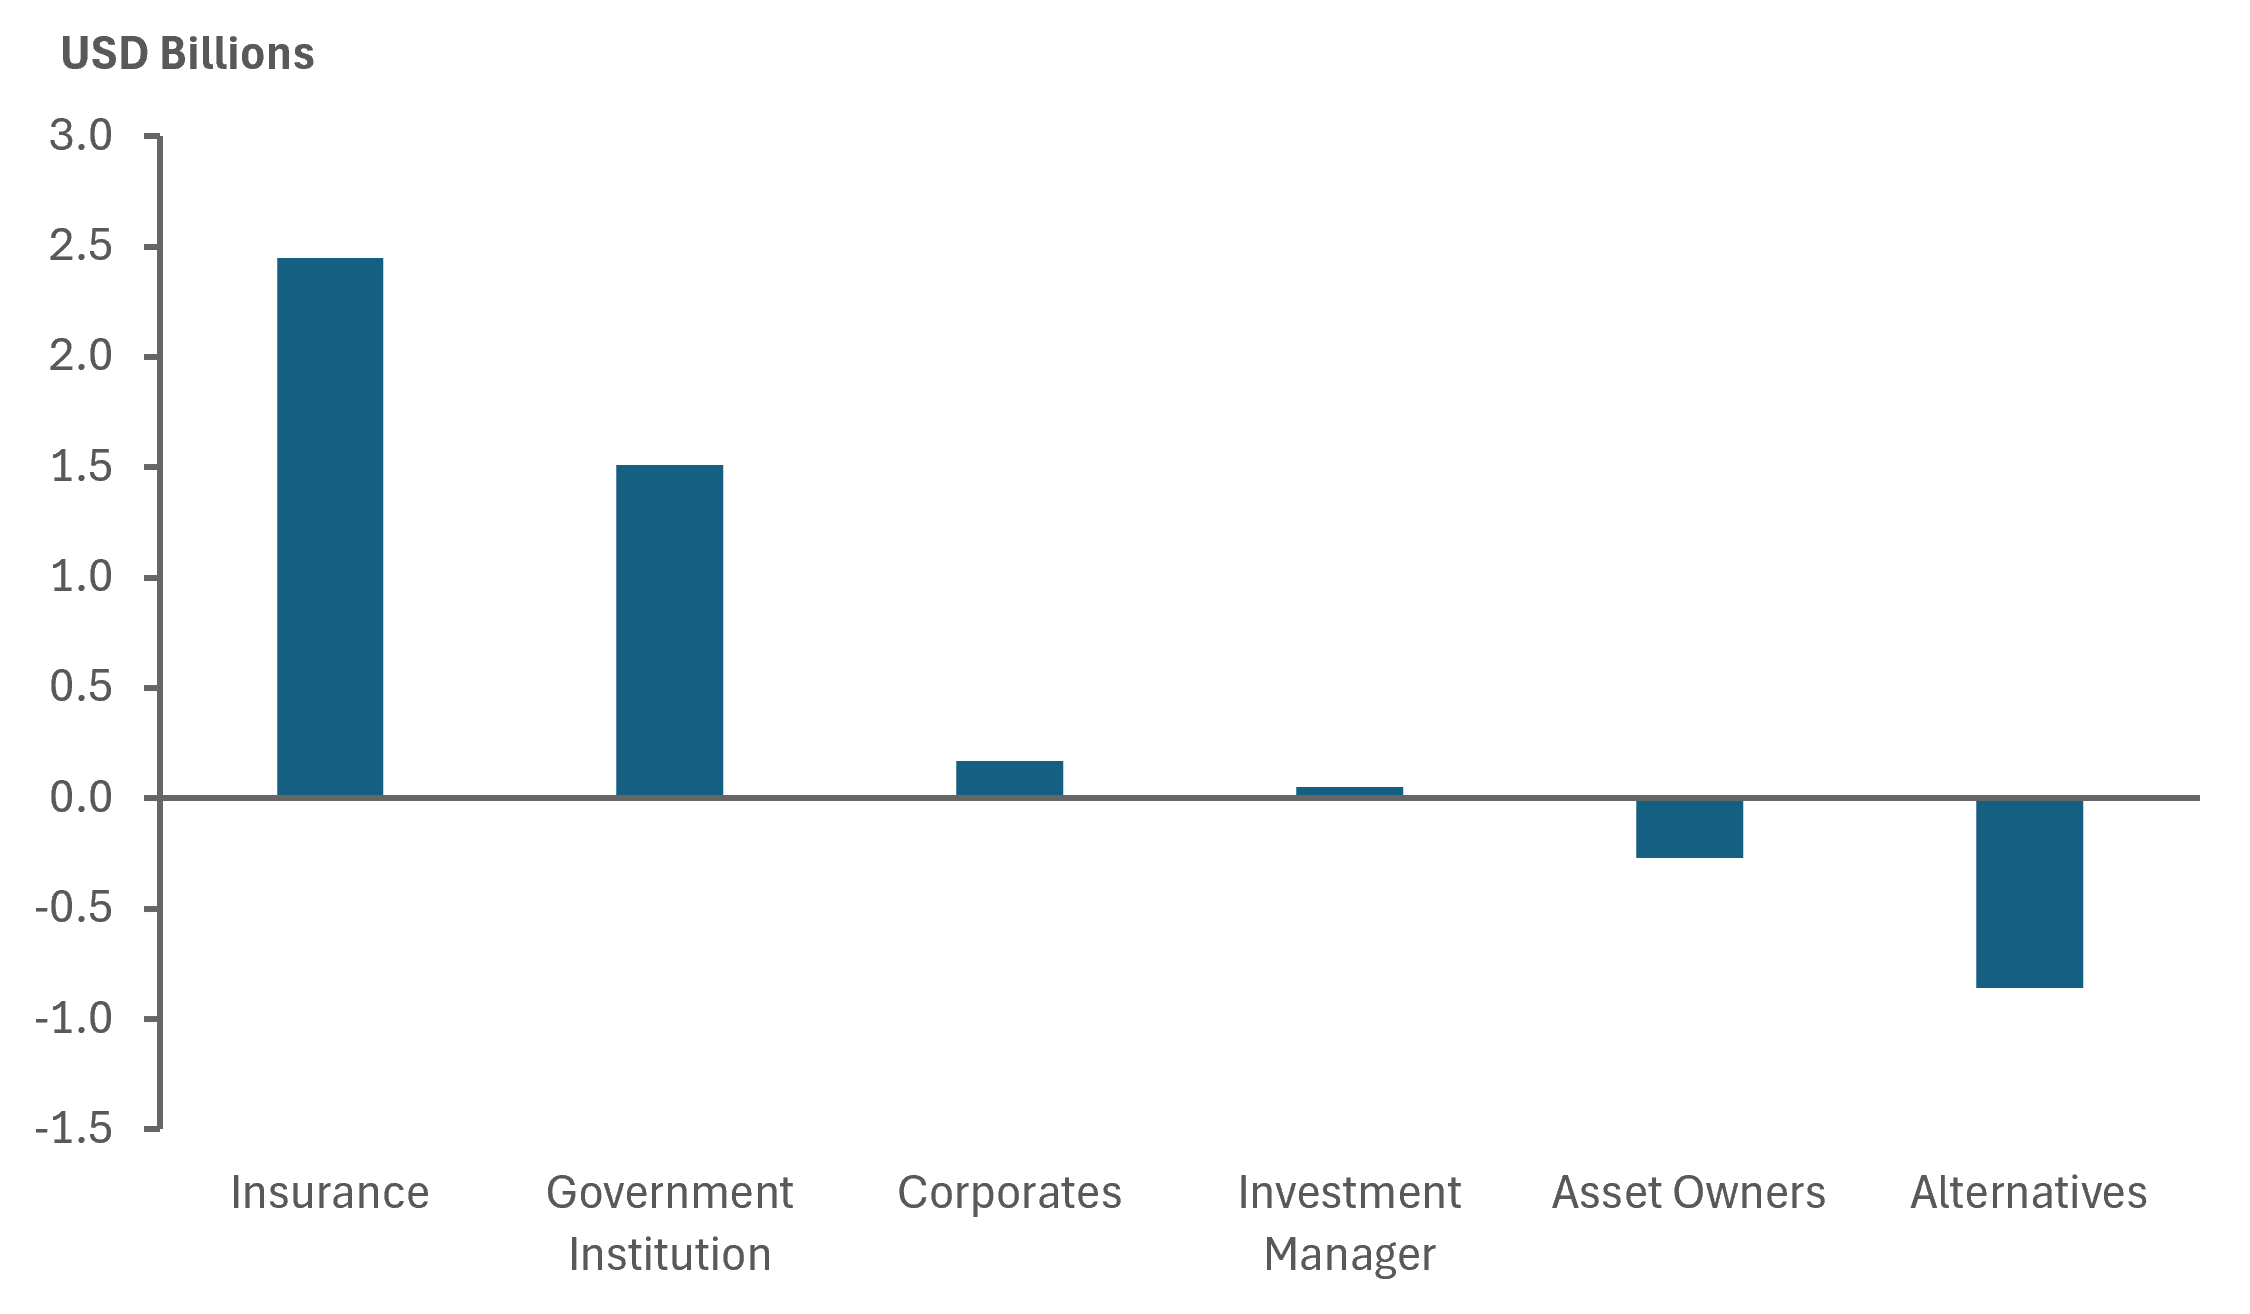
Foreign investors are driving the JGB bid. Outside banks and broker-dealers, insurance companies were the largest net buyers, adding $2.45bn, followed by government institutions at $1.51bn. Those gains came entirely from foreign-domiciled investors. At the aggregate level, foreign holders were the only domicile segment to add exposure, while domestic holders reduced it. Total holdings were concentrated in Alternatives, Insurance, and Investment Managers, each around 5% of the $191.2bn parent total. That confirms JGB demand is real, foreign-led, and still broadening.
REAL MONEY AND SOVEREIGNS THE MOST ACTIVE IN ADDING TO JGBS
Source: BNY
Equity Weakness
Japanese equities remain the weak link and are unlikely to join a broad risk-on rally. Foreign holdings are falling faster than elsewhere in developed APAC, reflecting Japan’s exposure to the wider unwind in AI, semiconductor, and technology trades. A stronger yen, higher domestic yields, and supply-chain pressure all add to the drag. The gap between equity and JGB positioning is now more than 20 percentage points versus rolling 12-month averages, leaving room for further rotation out of equities and into bonds. The likely near-term outcome is stronger yen exposure and sustained JGB demand, not a broad Japan equity rebound.
GPIF Limits
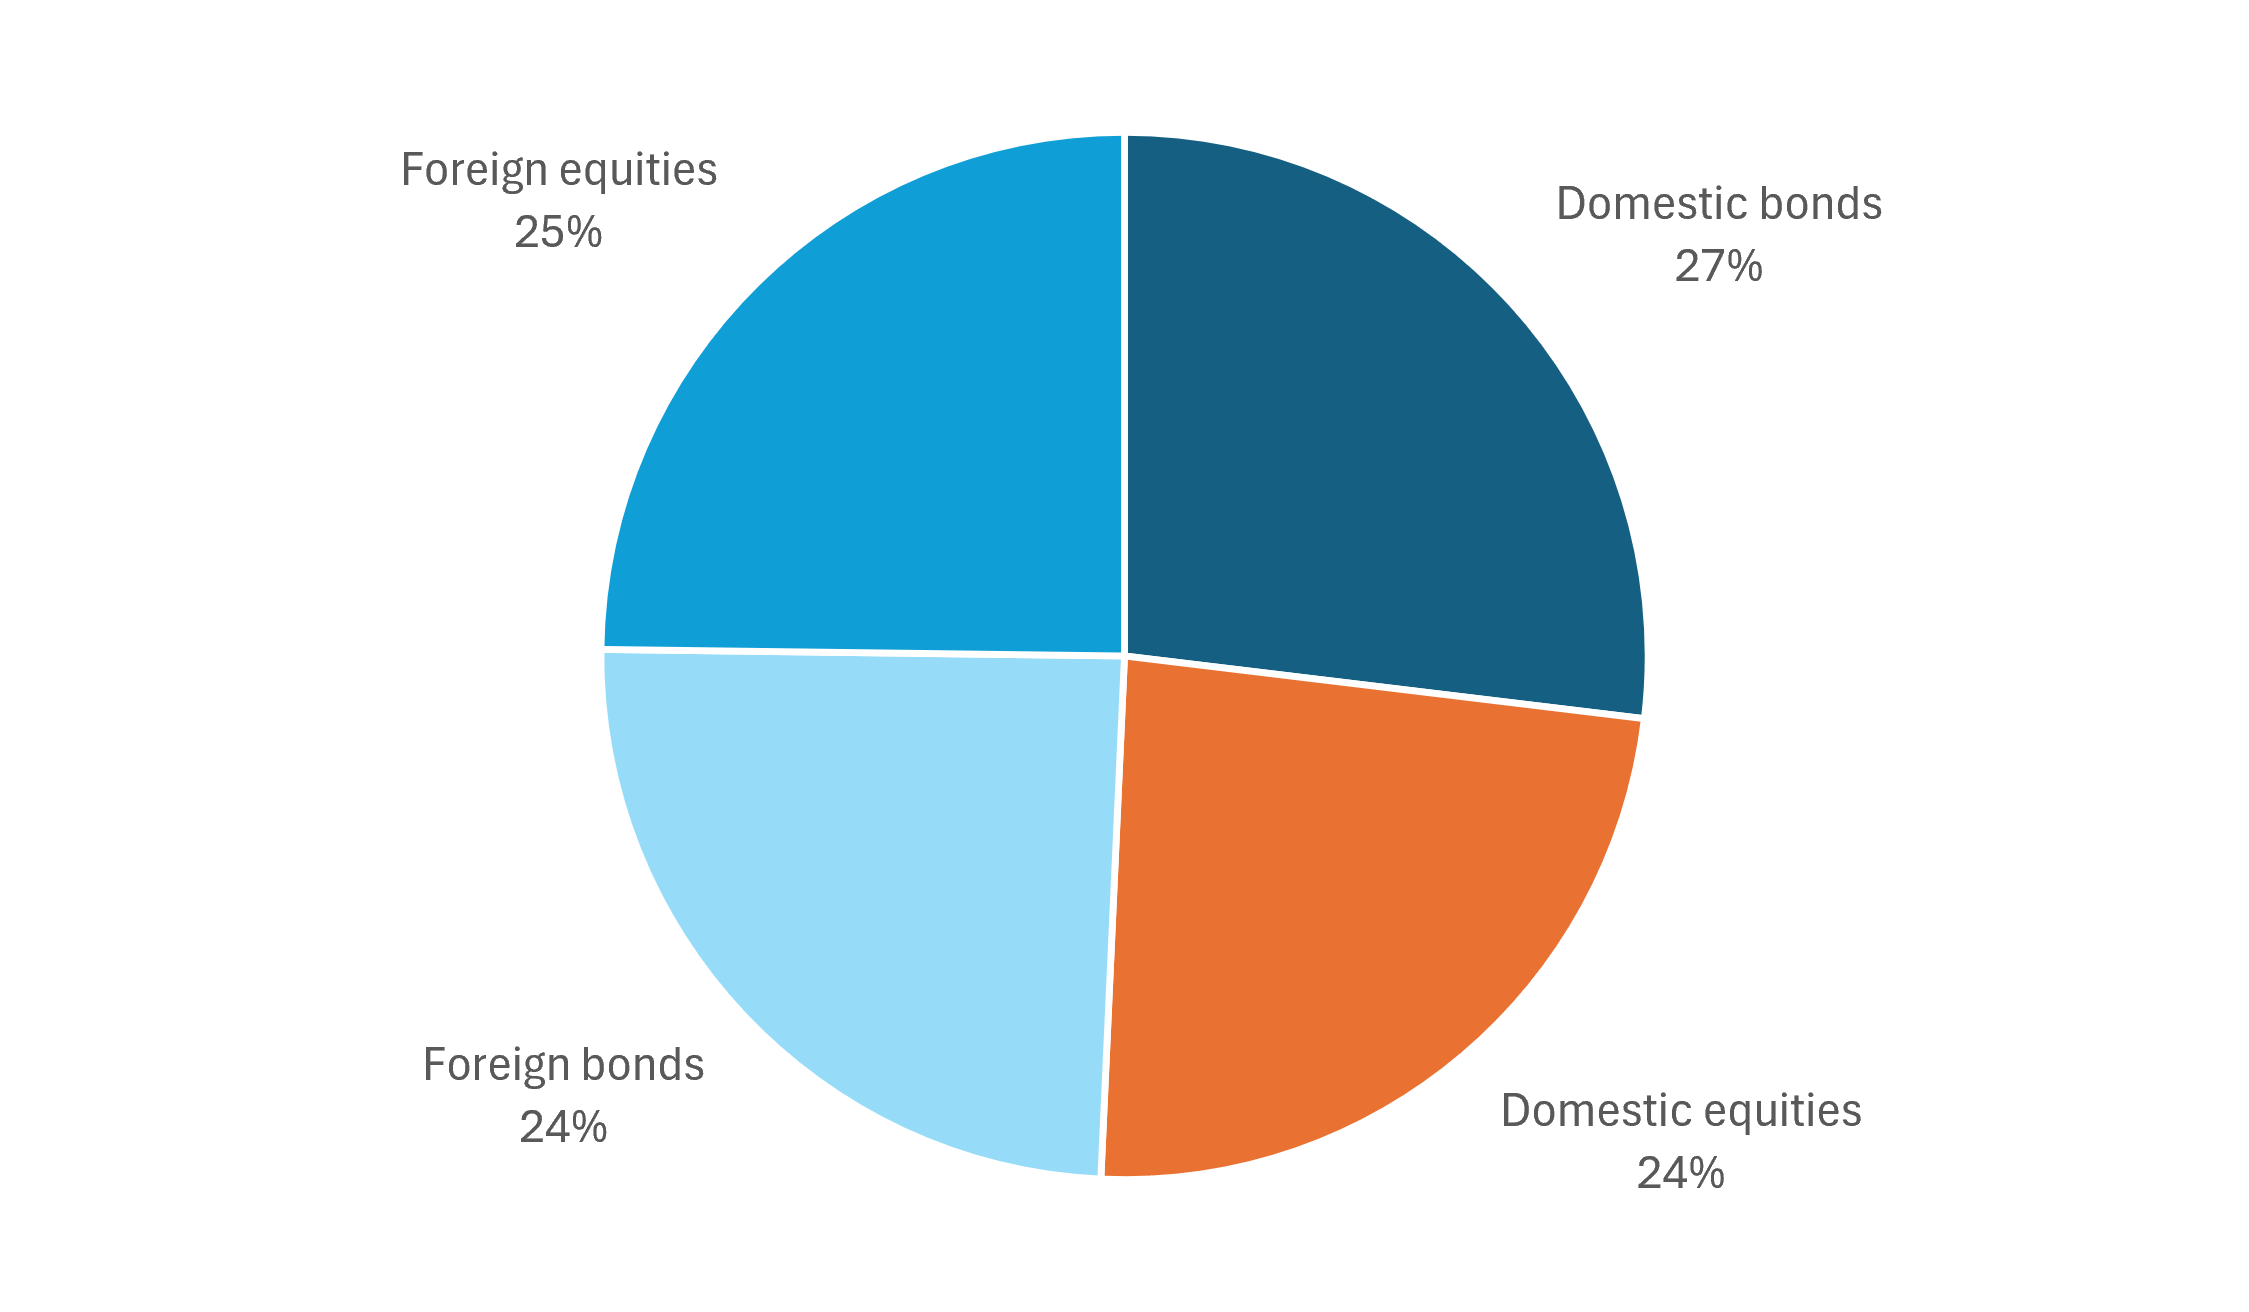
GPIF can help, but it cannot solve the problem. The policy debate has clearly shifted toward greater domestic allocation, and that matters. GPIF manages ¥299.8tn, or about $1.9tn, with an even 25/25/25/25 split across domestic bonds, foreign bonds, domestic equities, and foreign equities under its current policy mix. A gradual move toward domestic assets would support Japanese markets and regional currencies. But reallocation of existing assets is only a partial fix.
CURRENT GPIF ASSET ALLOCATION IS EVENLY BALANCED BETWEEN ASSETS AND LOCATION
Source: BNY, GPIF, total assets JPY 299.8 tln as of end-Q1 2026
Scale Problem
Even a large GPIF shift would not materially change Japan’s external position. A 10-percentage-point portfolio reallocation equals about $186bn, roughly just over two months of the Ministry of Finance’s May 2024 intervention pace. Japan’s ¥562tn net international investment position is vastly larger. Lasting yen strength requires newly generated domestic savings and balance-of-payments surpluses to stay onshore rather than continuing to be recycled abroad. That is a policy challenge, not an asset-allocation tweak.
Intervention Limits
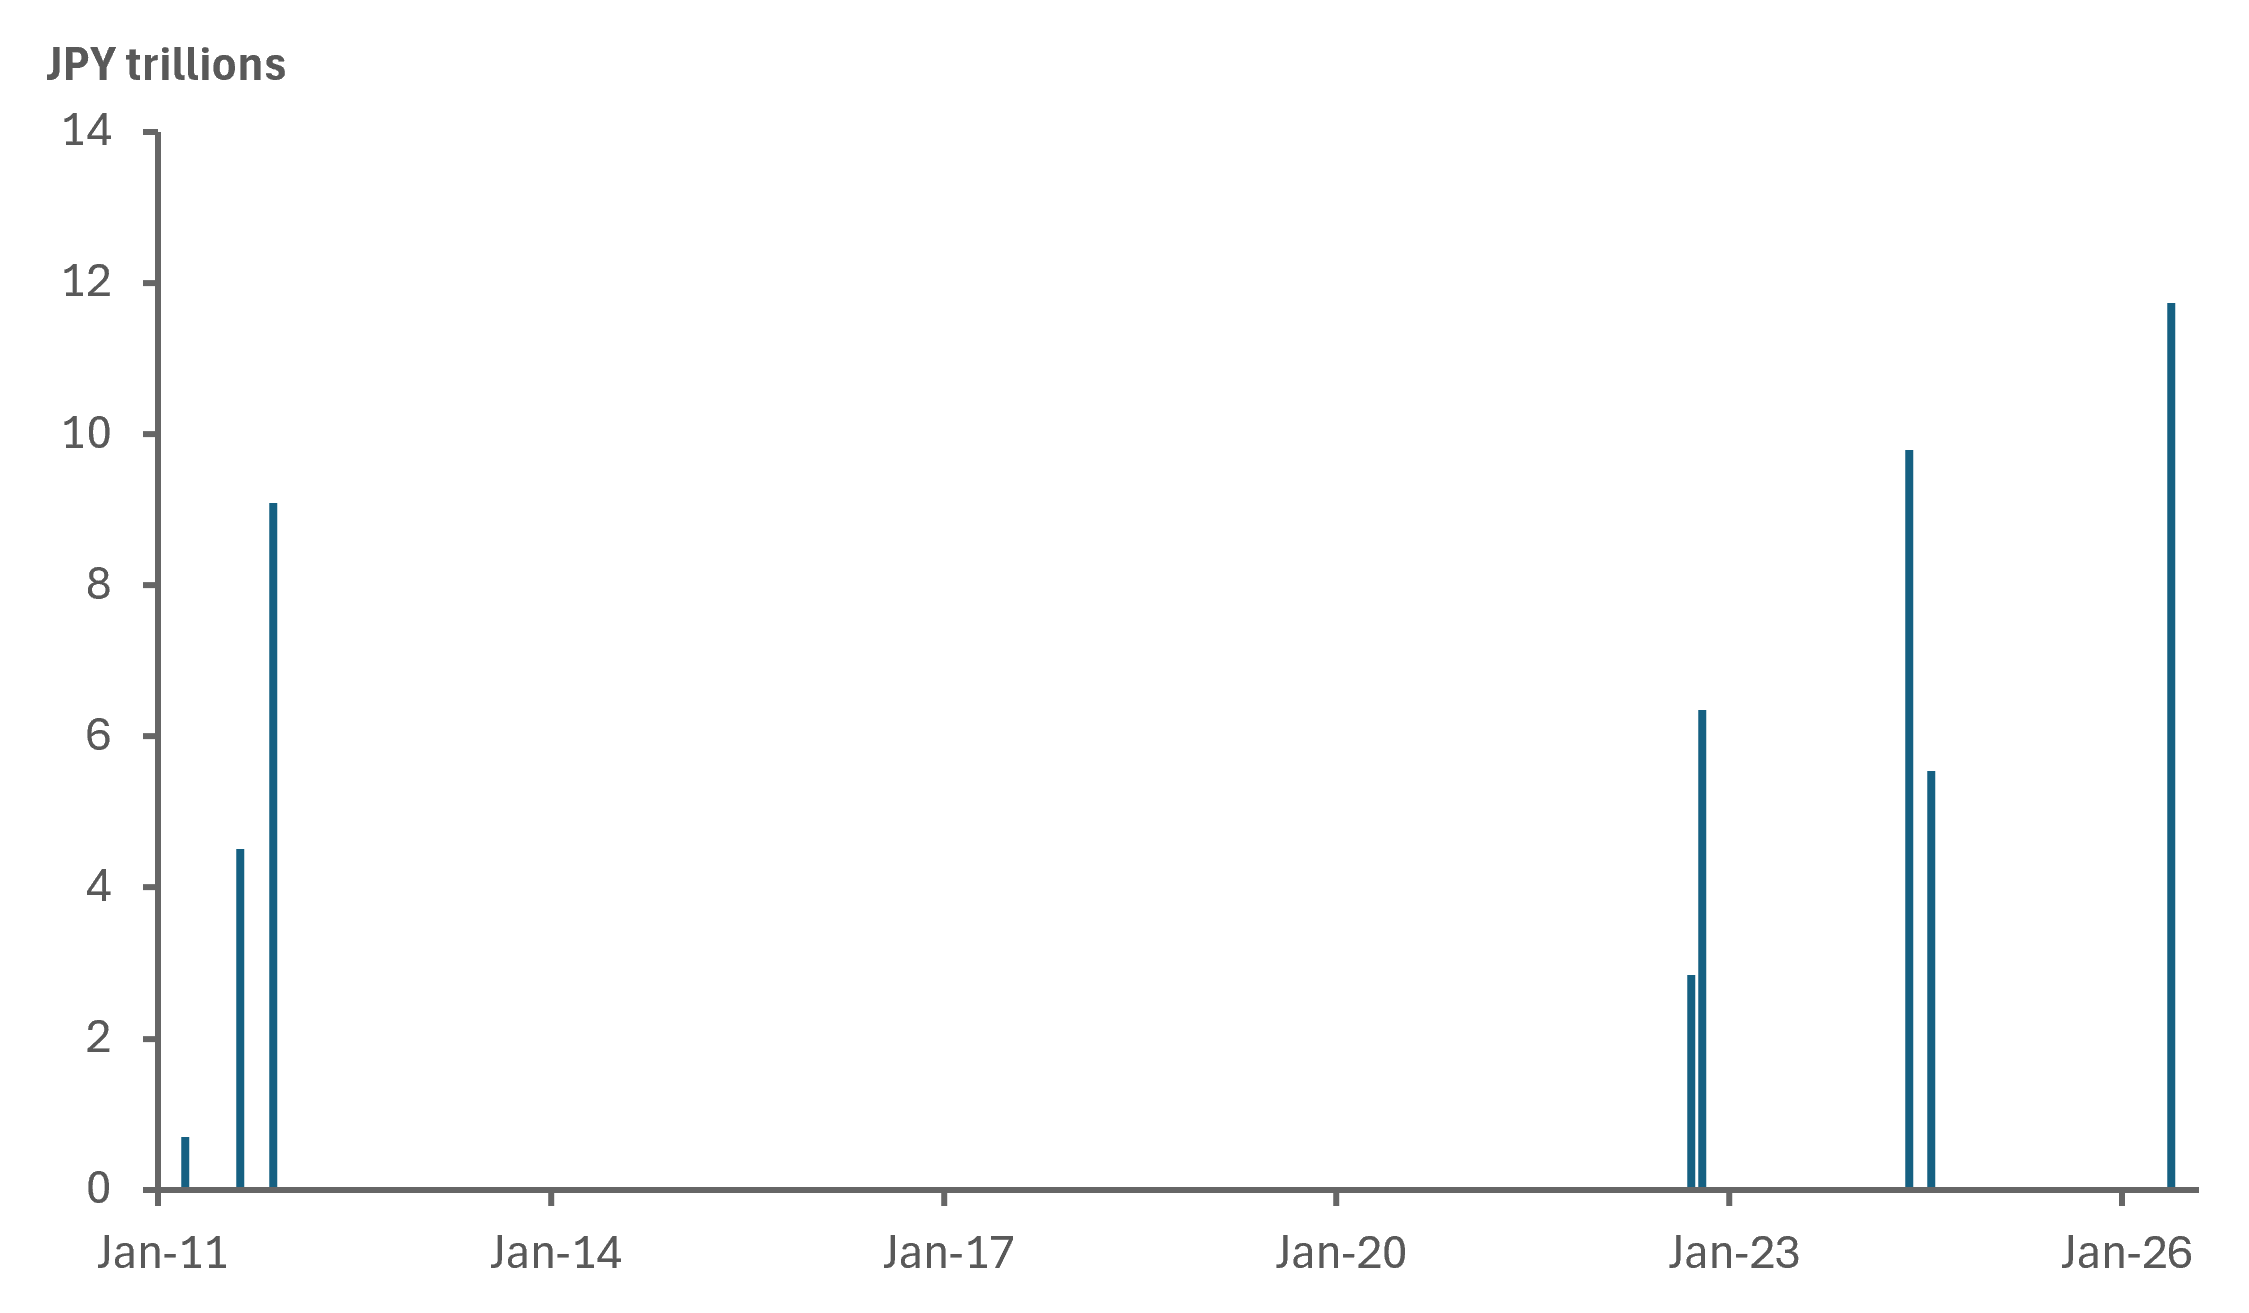
Tokyo is running into hard limits on how long it can keep intervening. Under IMF treatment of floating exchange rates, three days of intervention count as one operation, and Japan can conduct only three such operations in six months. Monday, August 3, would mark the third day of the second operation, after the first in April. U.S. support can help stretch the window, but it cannot remove the constraint. Tokyo may pause and preserve one last operation for late October or early November before the clock resets.
JAPAN INTERVENTIONS LARGE BUT INFREQUENT FOR NOW
Source: BNY, Bloomberg, Bank of Japan
Credibility Test
Japan’s real problem is policy credibility, not just currency weakness. Even if intervention or domestic reallocation drives a tactical recovery in the yen and Japanese assets, structural appreciation will fail without a credible macro framework. Comparisons between Japan’s latest “honebuto” budget and the U.K.’s 2022 mini-budget show how sharply credibility concerns have risen. Japan’s position is not identical and not reckless in the same way, but the warning is clear: markets will punish any perception that fiscal expansion is outrunning policy discipline.
BoJ Constraint
The market will keep buying USDJPY dips until Tokyo stops blocking normalisation. Governor Ueda has become more explicit about the inflationary damage caused by a weak yen, and frustration with political resistance is increasingly visible. The front end of the curve should continue to price more BoJ normalisation, while restored fiscal credibility would allow the back end to rally as term and fiscal-risk premia fall. Washington can raise pressure through rhetoric or trade threats, but it cannot do Tokyo’s job for it. Acknowledging intervention alone is not enough, Japan’s Deputy Finance Minister and top FX official Mimura stated on Monday that the government’s response to FX will be “in coordination with monetary policy”.
Final Imperative
Takaichi must revive Abe’s third arrow now. Abe’s legacy was never just easy money and fiscal activism; it also depended on structural reform. That is the missing piece. Tokyo must give the BoJ room to act, rebuild fiscal credibility, and address the supply-side weaknesses that have left Japan dependent on currency depreciation. Political room is narrowing as cost-of-living pressure fuels voter frustration and strengthens populist alternatives. That raises the urgency. If Takaichi wants to preserve Abe’s legacy, reform cannot be symbolic, delayed, or partial. It must be decisive enough to convince markets that Japan still has a strategy, and the will to execute it.

