Yields and rate expectations
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.

John Velis, David Tam
Time to Read: 5 minutes
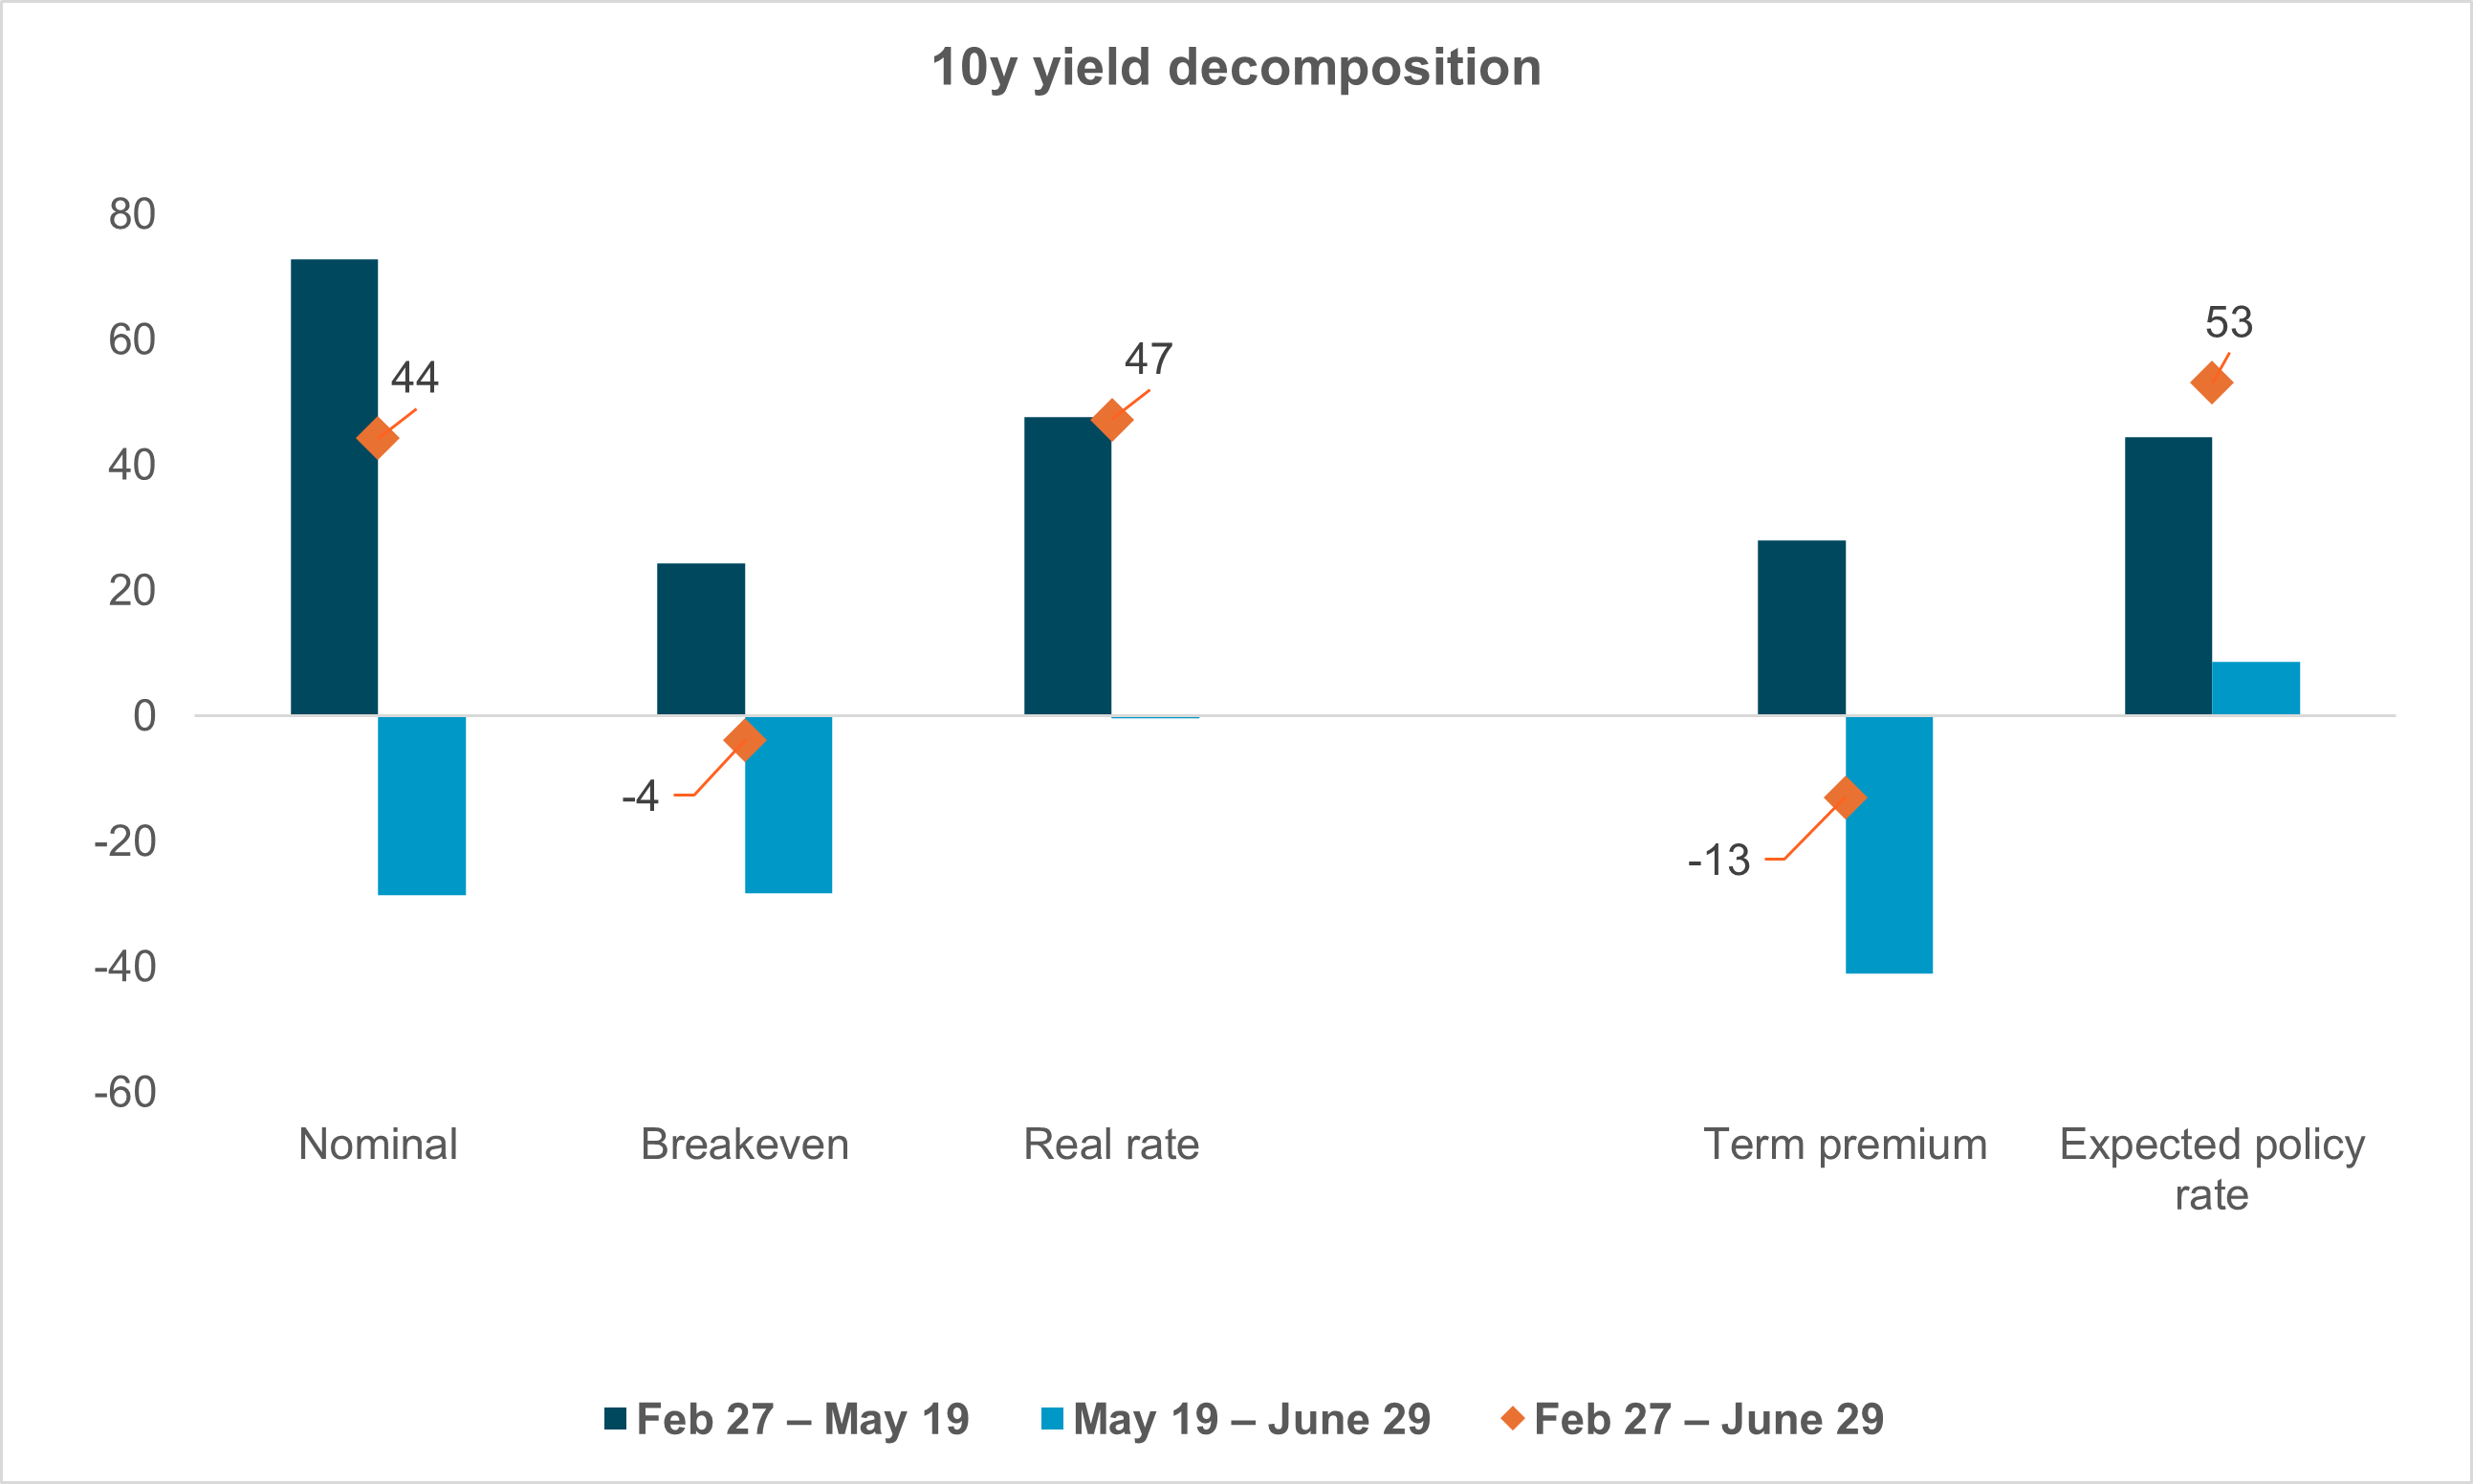
EXHIBIT #1: WHAT’S BEEN DRIVING THE 10Y YIELD?
Source: BNY Markets, Bloomberg, Federal Reserve Bank of New York
The 10y bond yield is nearly 30bp lower today compared to its recent high of 4.67% on May 19. Since February 27, the day before the conflict between the U.S. and Iran started, the yield is up 44bp overall. While it’s intuitive to blame higher oil prices and inflation expectations for the rise in yields, the data don’t support this view. Instead, the rise in yields at the long end – and really, across the curve – is due to expectations of higher policy rates.
In Exhibit 1, we show a simple decomposition of the 10y yield across two dimensions. To the left, we plot the change in nominal 10y yields, 10y breakeven inflation, and the 10y real yield. Toward the right, we plot the changes in the NY Fed’s estimates of the 10y term premium, as well as the market-implied average short rate priced into the curve for the next ten years. In addition, we show these changes for two periods: from February 27 through May 19, when bond yields reached their local maximum since the war started. While the nominal yield is up 44bp in total, the real yield is up by nearly 50bp, meaning that inflation expectations over the period are lower by around 5bp.
The term premium analysis reveals that although the perceived riskiness of the 10y note initially increased at the start of the conflict, with the premium up 28bp between February 27 and May 19, it subsequently fell by even more (approximately 40bp) since then. Overall, the term premium is around 12bp lower now versus its pre-war level. What’s higher is the expected average policy rate over the next 10 years, backed out of the NY Fed’s term premium model. It’s nearly 55bp higher, essentially moving from around 3.5% before the war up to about 4.0% now.
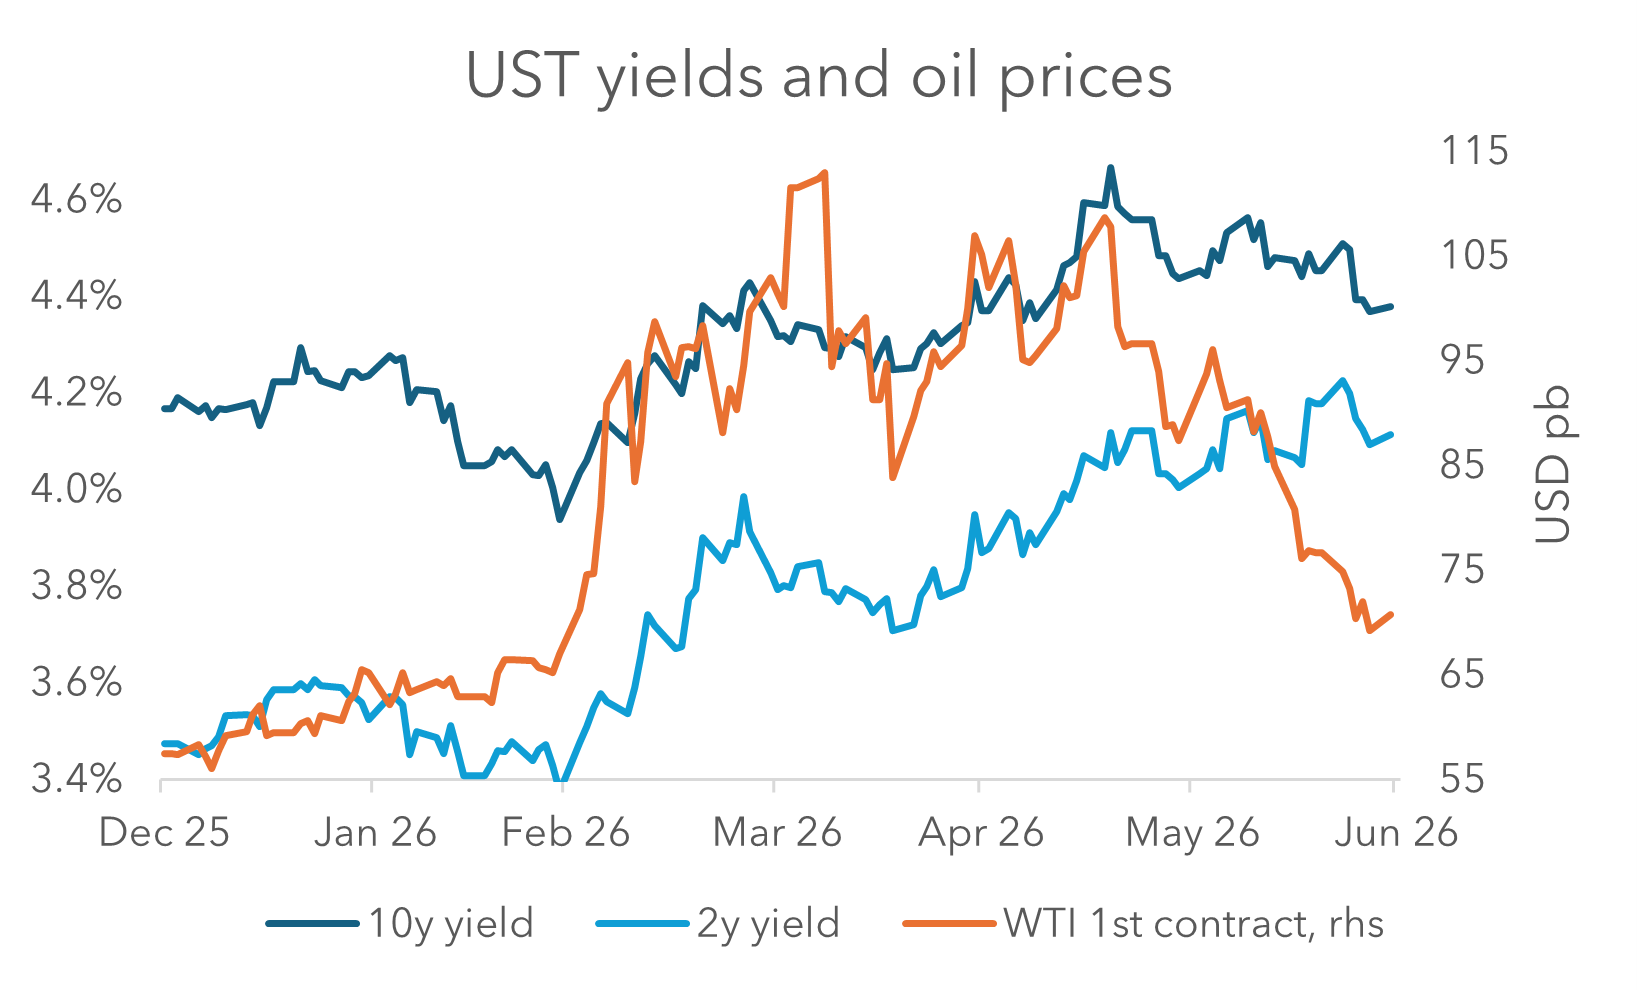
EXHIBIT #2: OIL PRICE DECLINE HASN’T BROUGHT YIELDS LOWER
Source: BNY Markets, Bloomberg
Consider these observations in the context of multiple factors: the war and oil prices, the arrival of a new FOMC Chair, and growth and inflation dynamics, among others. Long-term inflation expectations have been notably well-behaved even in the teeth of higher oil prices recently. The rise in rate expectations can be seen on both ends of the curve, independent of the inflation outlook. Exhibit 2 shows that even with the decline in oil prices – which actually began on May 19 – yields haven’t moved lower with them.
Our view is that the emerging AI boom is pushing up long-term notions of the neutral rate of interest. This is also something we argued recently and might represent a challenge to the contrary view that any impending productivity boom will be disinflationary, requiring lower interest rates. The increased demand for capital raises its cost. Higher real wages that result from higher labor productivity can lead to a consumption boom in the short run, creating the conditions for tighter Fed policy.
These implied real rates and long-term average short rates are important to watch. They could be signaling a change in the way the market is thinking about monetary policy, and by extension, productivity and financing costs, independent of inflationary developments, which are currently a tricky thing to assess. Energy prices and tariffs could be masking a more structural reinflation, particularly as evidenced by sticky services prices. Add to that our argument about capital investment driving up demand for and the price of capital, and higher rates than the market had previously assumed could be a new normal.
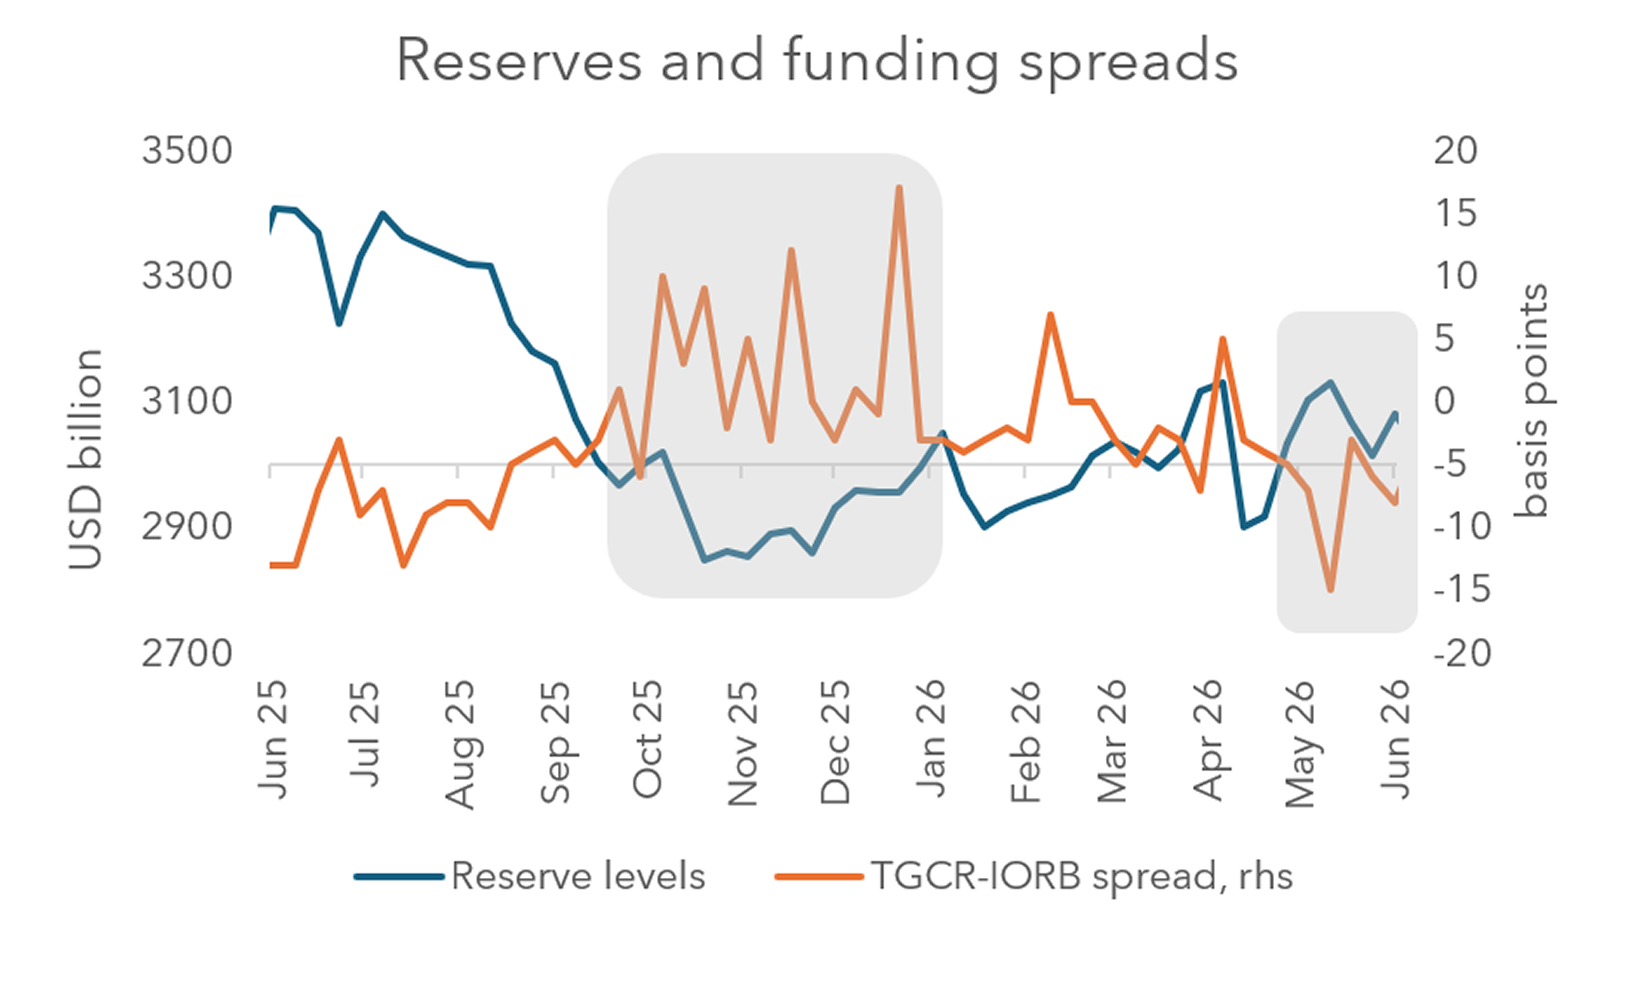
EXHIBIT #3: RMPS INCREASE RESERVES, TAMP DOWN REPO VOLS
Source: BNY Markets, Bloomberg, Federal Reserve Board of Governors
The addition signals that the FOMC is now more comfortable with the aggregate level of reserves in the system and the added qualifier “when appropriate” suggests that continued purchases might not be necessary going forward. As Exhibit 3 shows, elevated pressure in money markets, as measured by the spread between TGCR and IORB, has declined since Tax Day, even as the Fed has been reducing the size of RMPs. The Fed bought $2bn in T-bills just through RMPs since December, and this increase in system reserves has tamed last autumn’s rate volatility.
The additional language should also reinforce the idea that the Fed has broad latitude to change the size of RMPs on a month-to-month basis. Before the meeting, the NY Fed had already announced that it would pursue an additional $10bn in RMPs through the middle of July. It will be interesting to see if there is any change in the size of RMPs from then through mid-August. A further reduction or full-blown halt in RMPs would be at the very least evidence that the Fed feels the quantity of reserves is sufficient to maintain the ample framework.
However, either correctly or incorrectly, a pause of RMPs might also be interpreted as something more by the market. It would make sense if the Committee is comfortable holding reserve levels steady, but it would also likely immediately precede any hypothetical efforts to shrink the balance sheet. If the Fed were to pause RMPs next month, we imagine that speculation that the Fed was commencing balance sheet runoff would take off, even if the Fed’s intentions in pausing RMPs were narrower. We would look to Fed communication or the work out of the balance sheet taskforce for clarity if and when the Fed pauses RMPs but are concerned that this might not be forthcoming by next month.
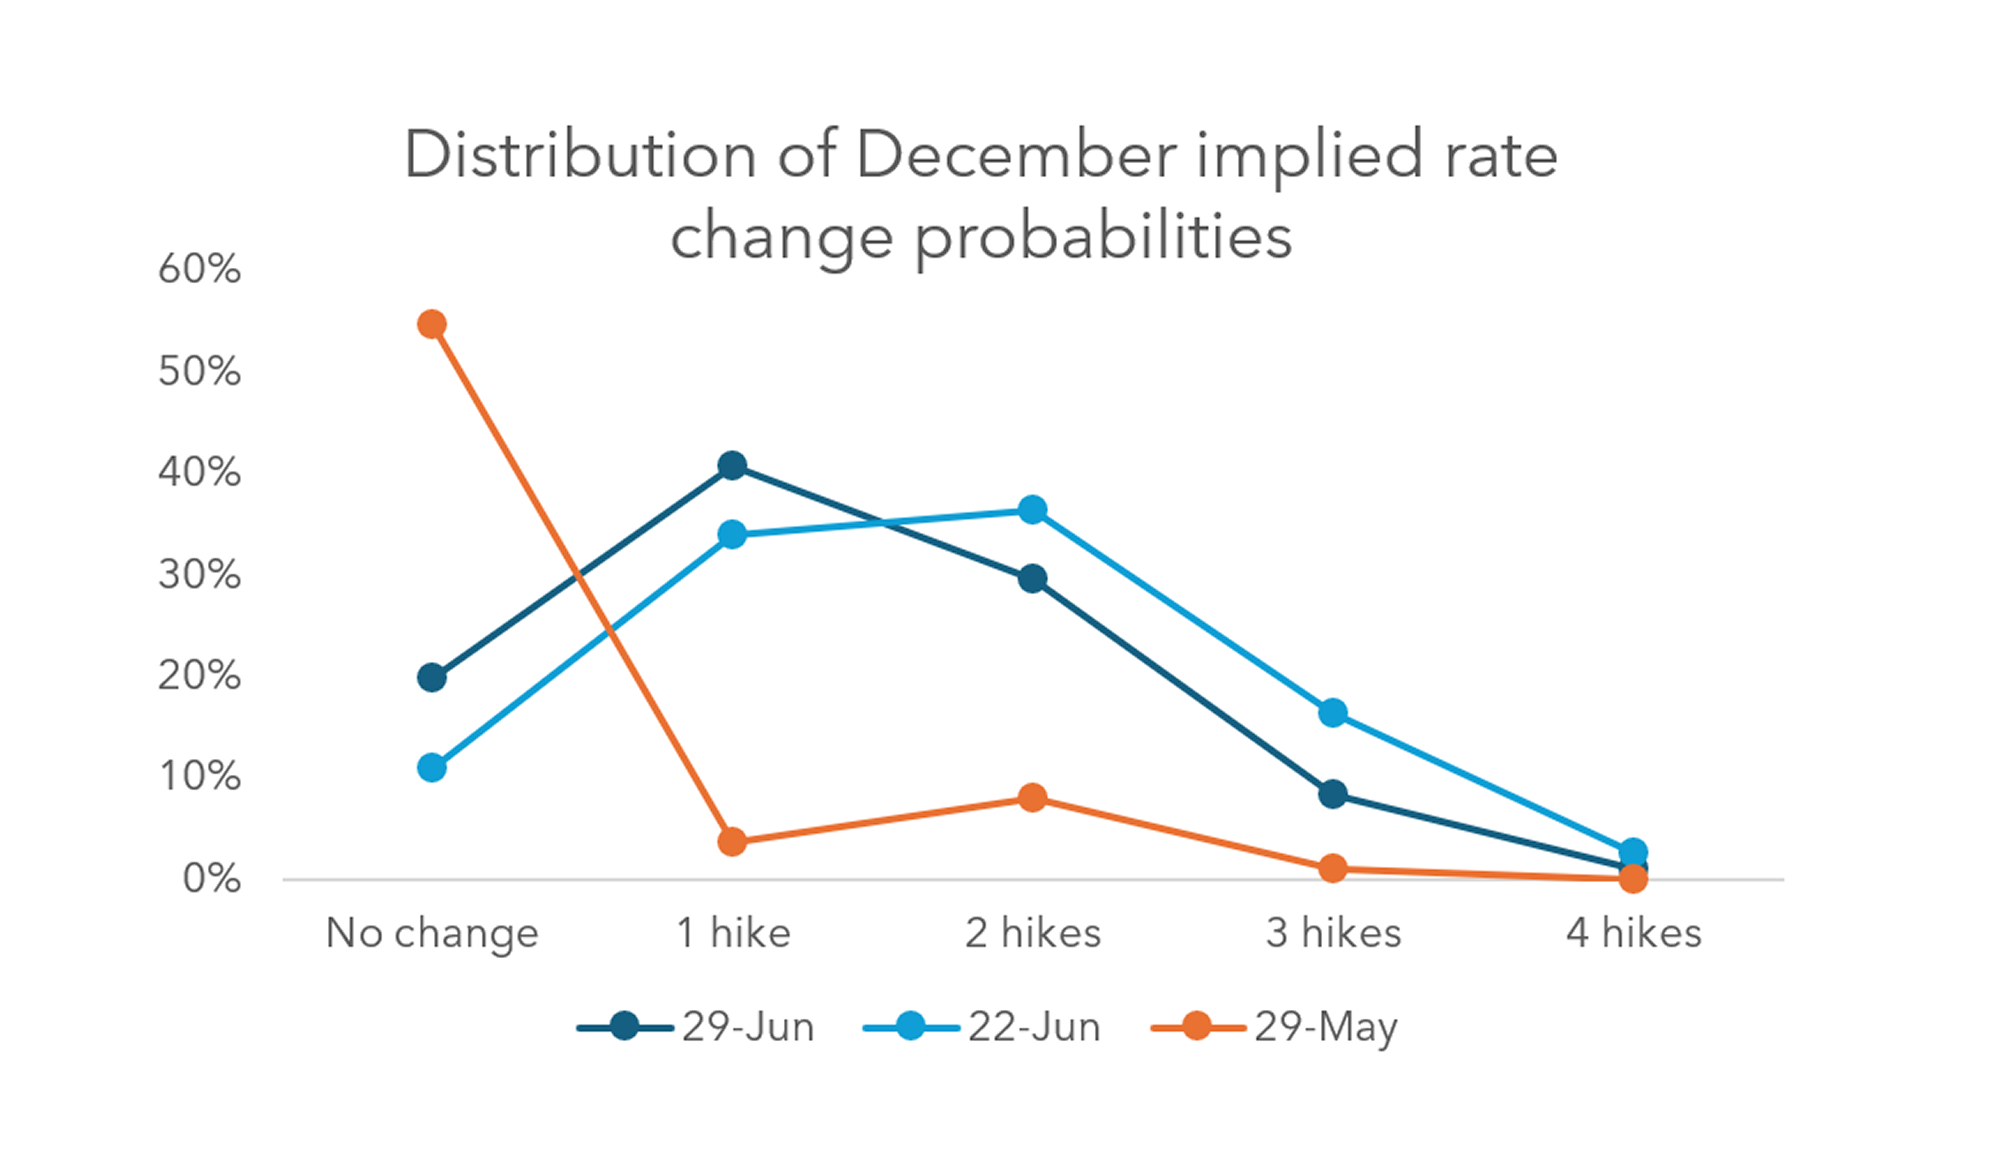
Rate expectations this week are a little softer than they were immediately after the June FOMC nearly two weeks ago. We presume that there was a degree of overshooting immediately after the meeting, and markets are slightly more settled now. Exhibit 4 shows the market’s implied probability distribution for the December 2026 funds rate as they appeared on Monday morning (dark blue line), a week ago (light blue line), and a month ago (orange). Clearly, the month-ago distribution represents a different view of the world before the June FOMC. Still, the move to the right (i.e., higher probabilities of larger rate hikes) has eased off a bit in the last two weeks. More noteworthy in Exhibit 4 is the width of the distribution, indicating that there is a lot still to be determined as we head toward December. Expectations are quite wide.
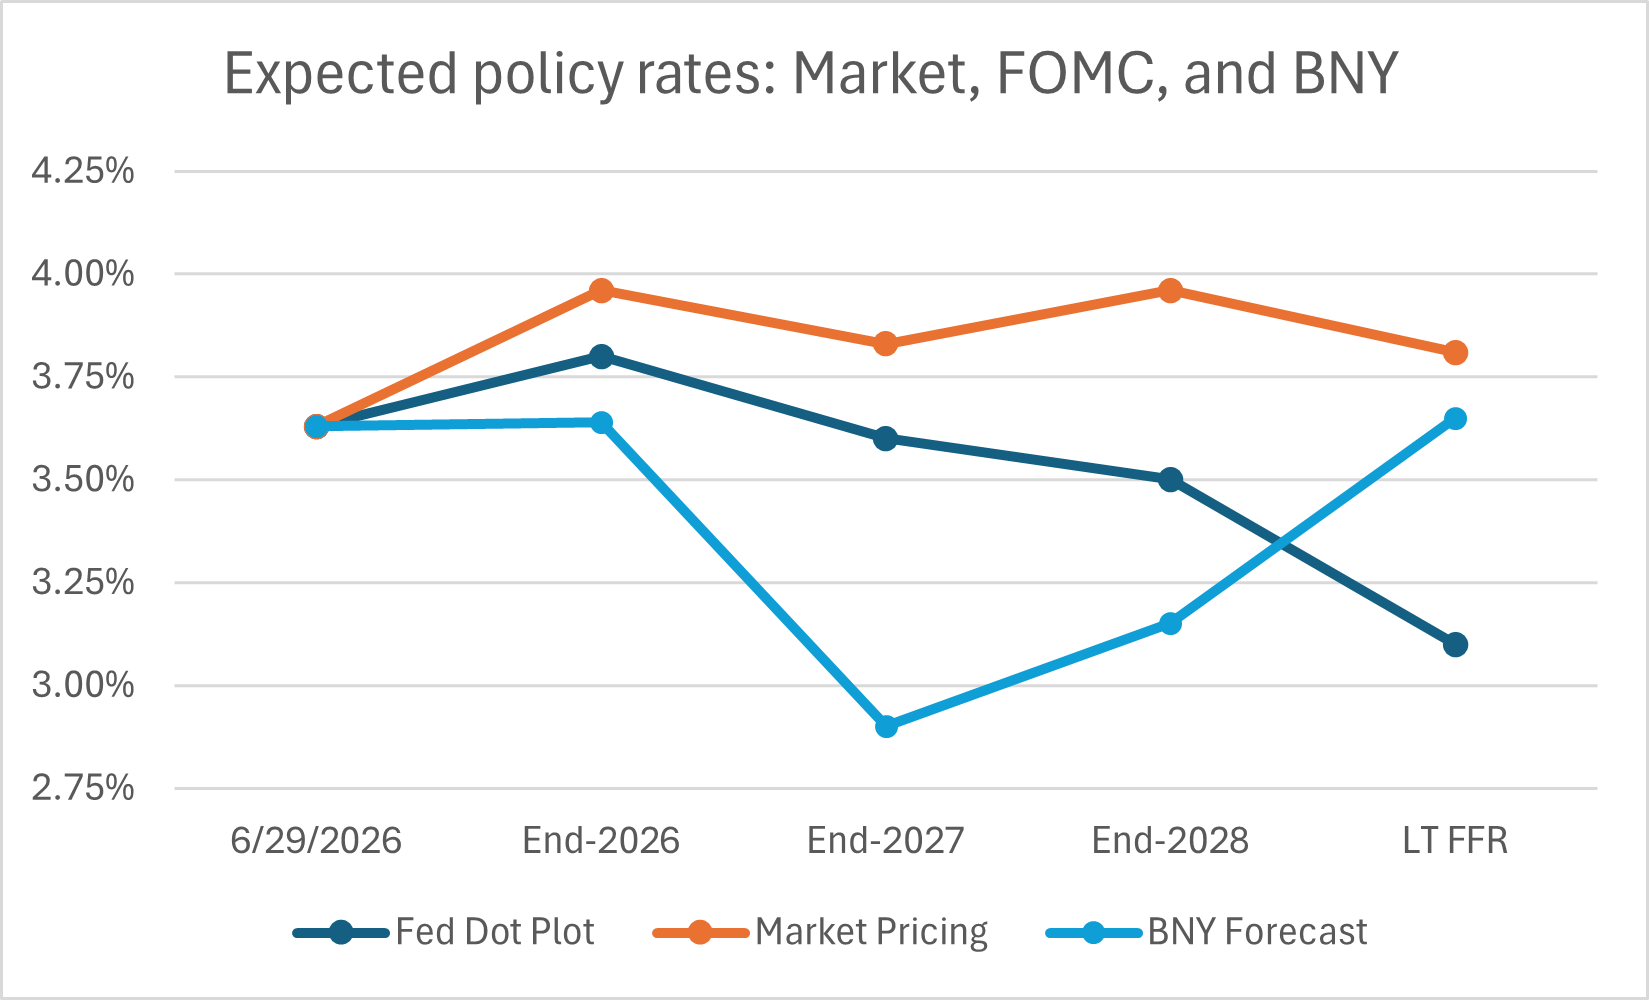
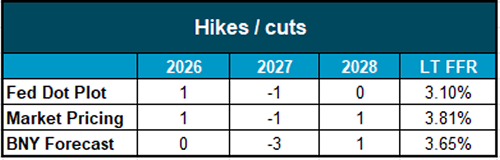
We maintain that the federal funds rate will stay unchanged for the rest of this year, although we acknowledge that the market is demonstrably more hawkish than we are. We’re cognizant of the persistence of inflation, while having limited visibility about its post-conflict evolution, especially if oil prices remain low. For example, sticky services prices – which should not reflect tariffs or oil – remain a concern.
However, the rates question will begin to focus on the strength of demand – especially the labor market. The job situation is much more promising than it was four months ago, with three straight significant jumps in nonfarm payrolls and June data looming this Thursday. We had previously been much more dovish, owing to what we saw as a moribund labor market prior to the March release. Now that labor demand looks to have stabilized, and is perhaps accelerating again, a fourth consecutive labor print above expectations could drive those expected funds rates higher from here and lead us to reconsider our view.
EXHIBIT #4: MARKET IMPLIED PROBABILITY DISTRIBUTION FOR DECEMBER FED FUNDS RATE