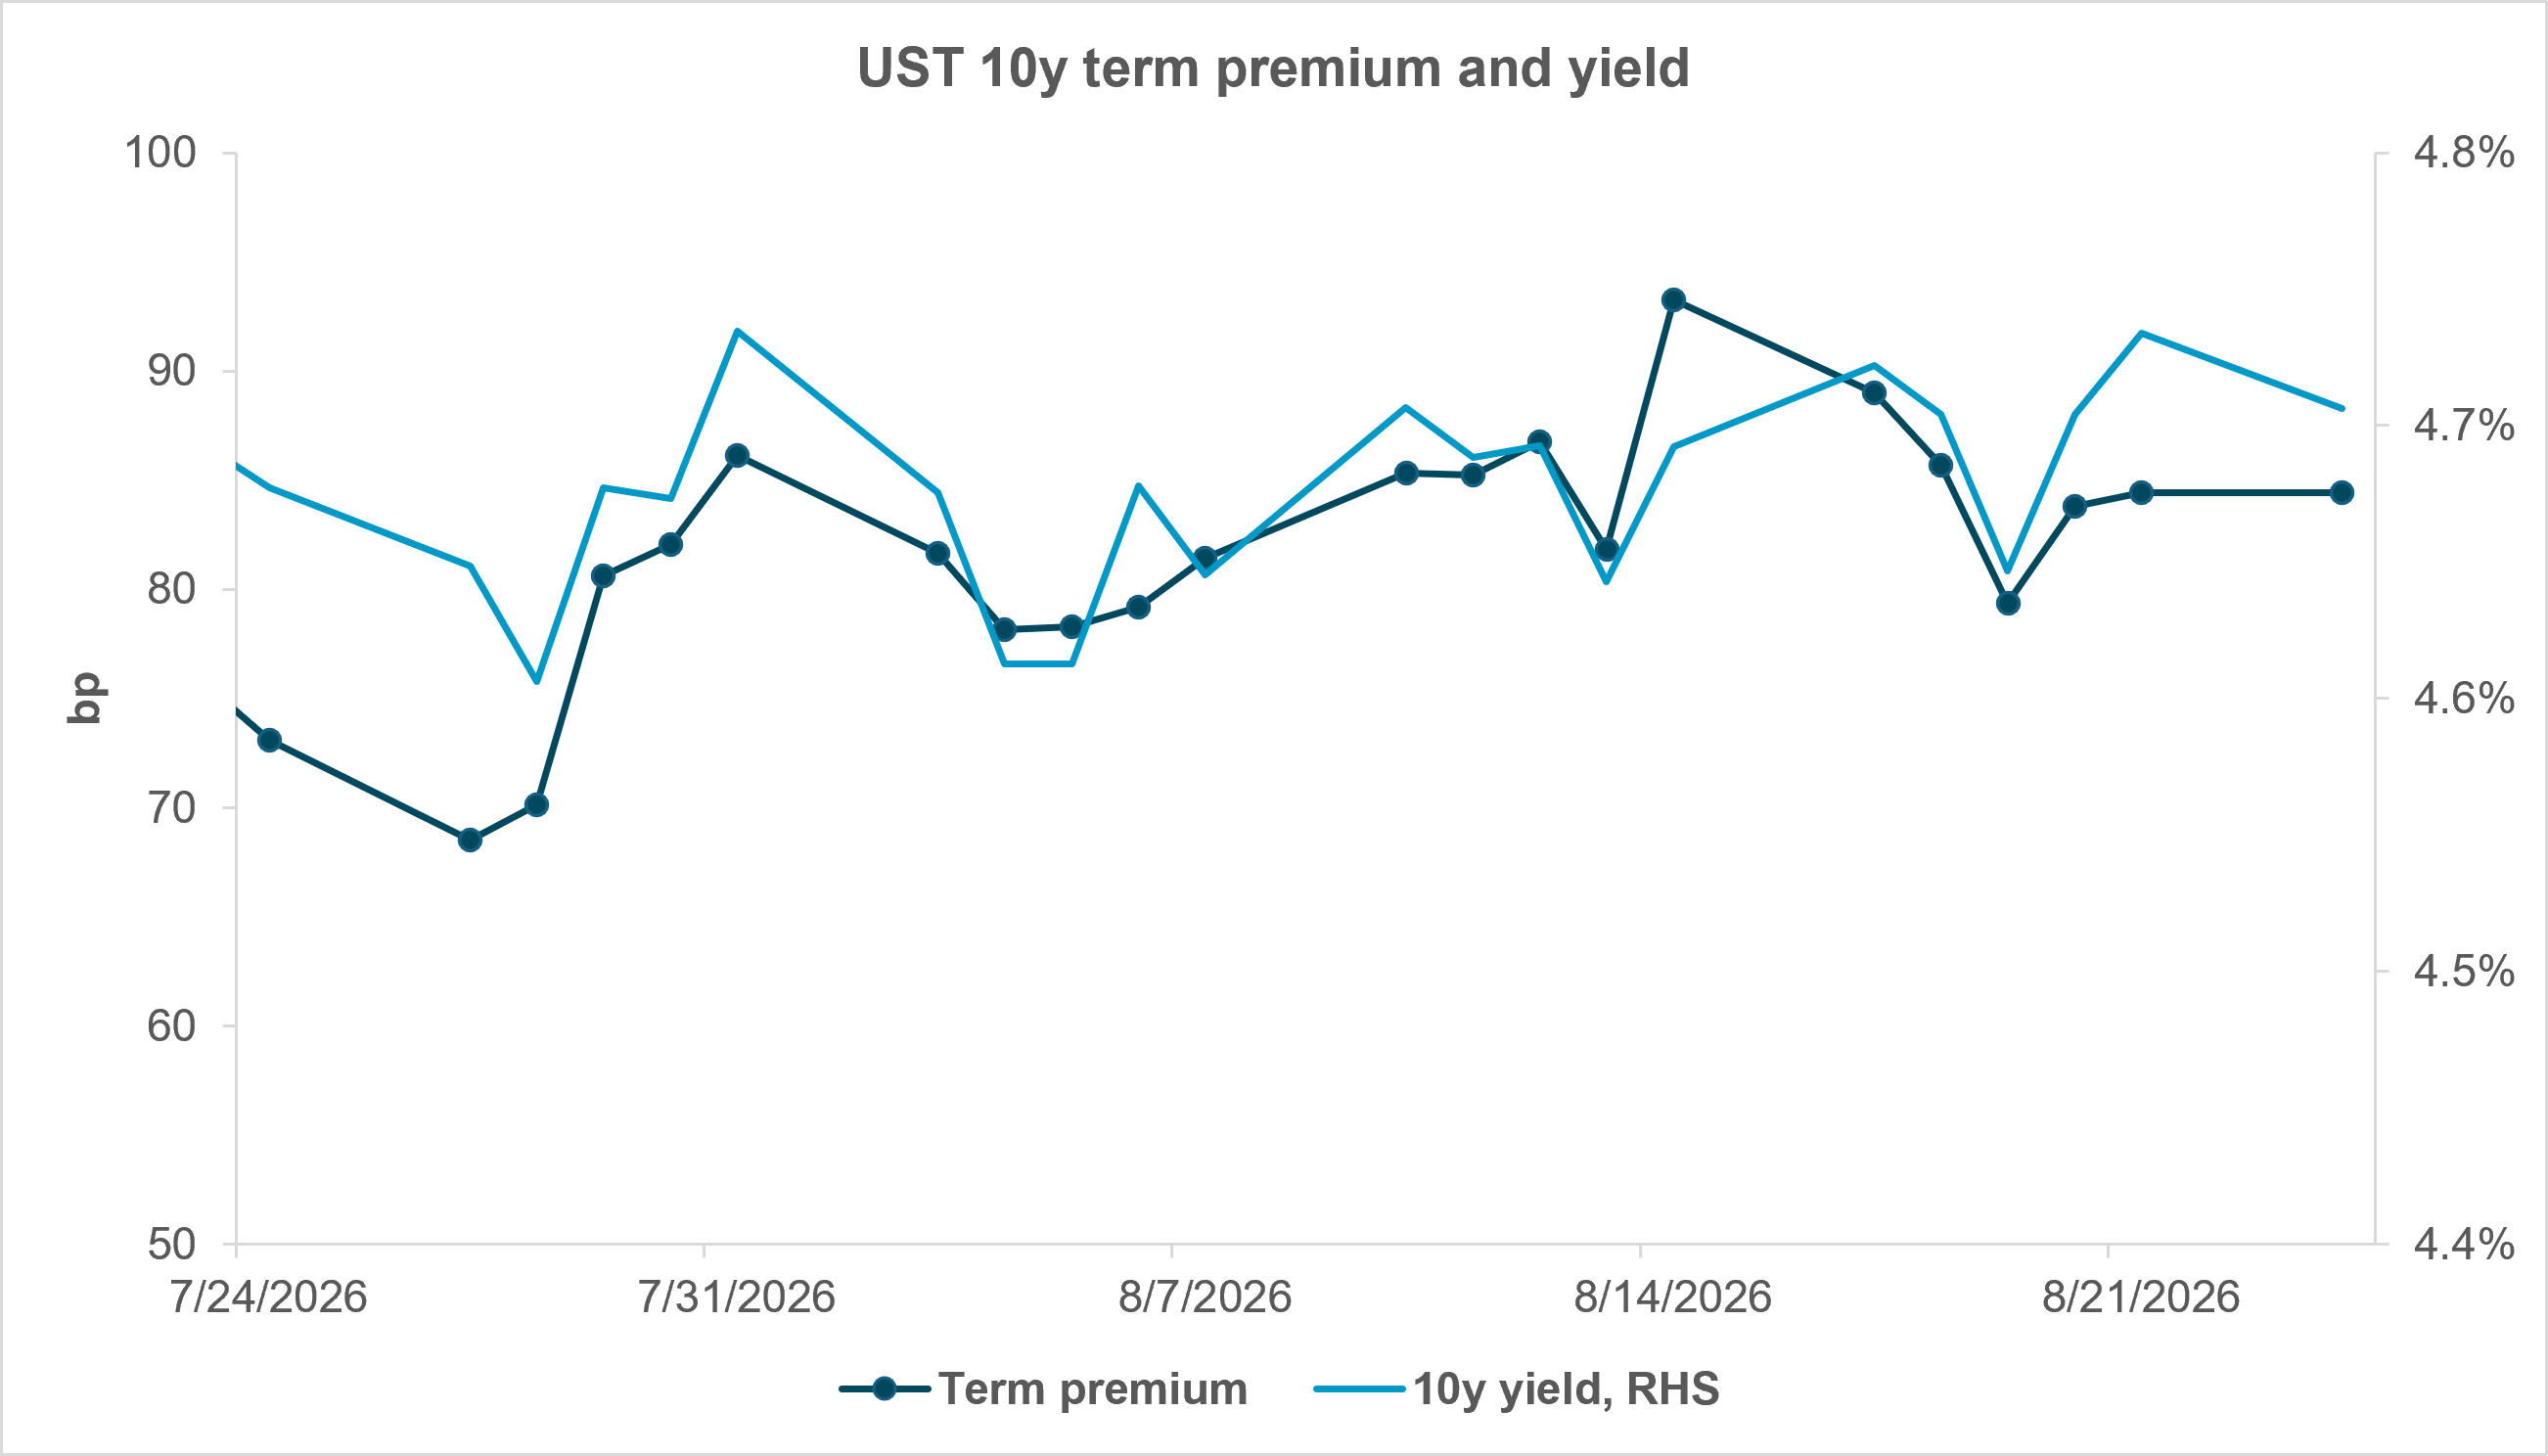
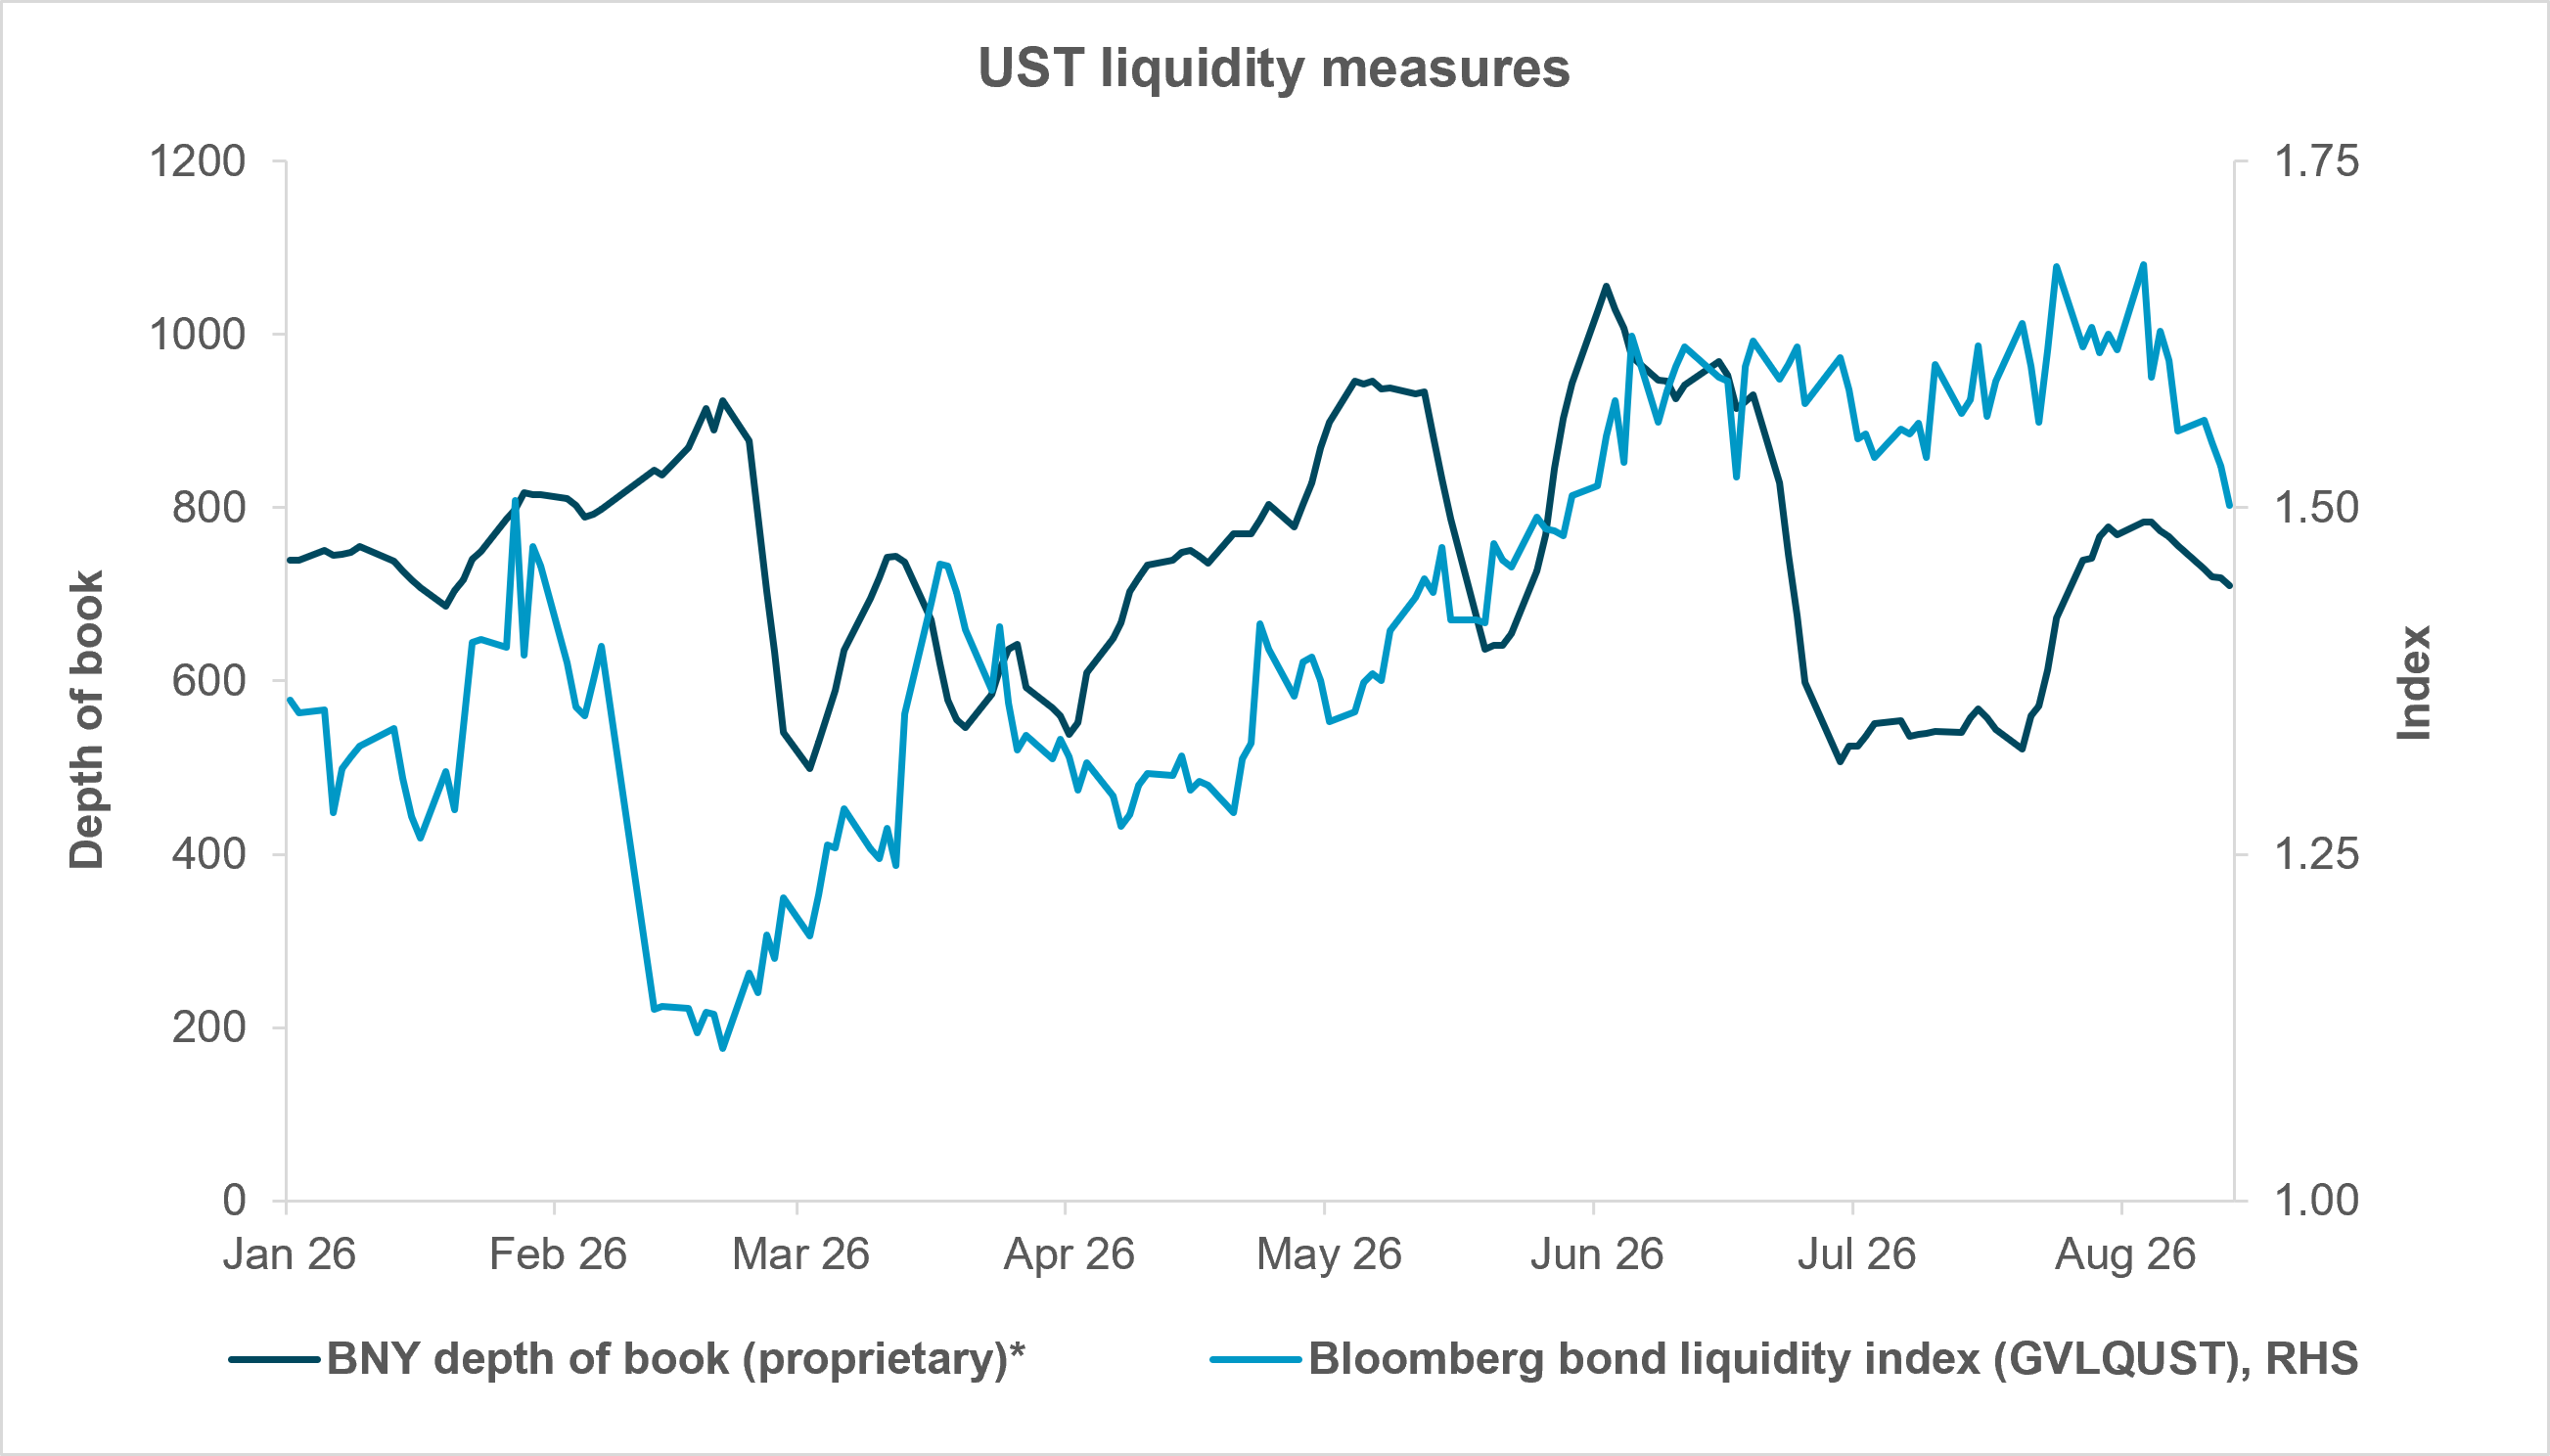
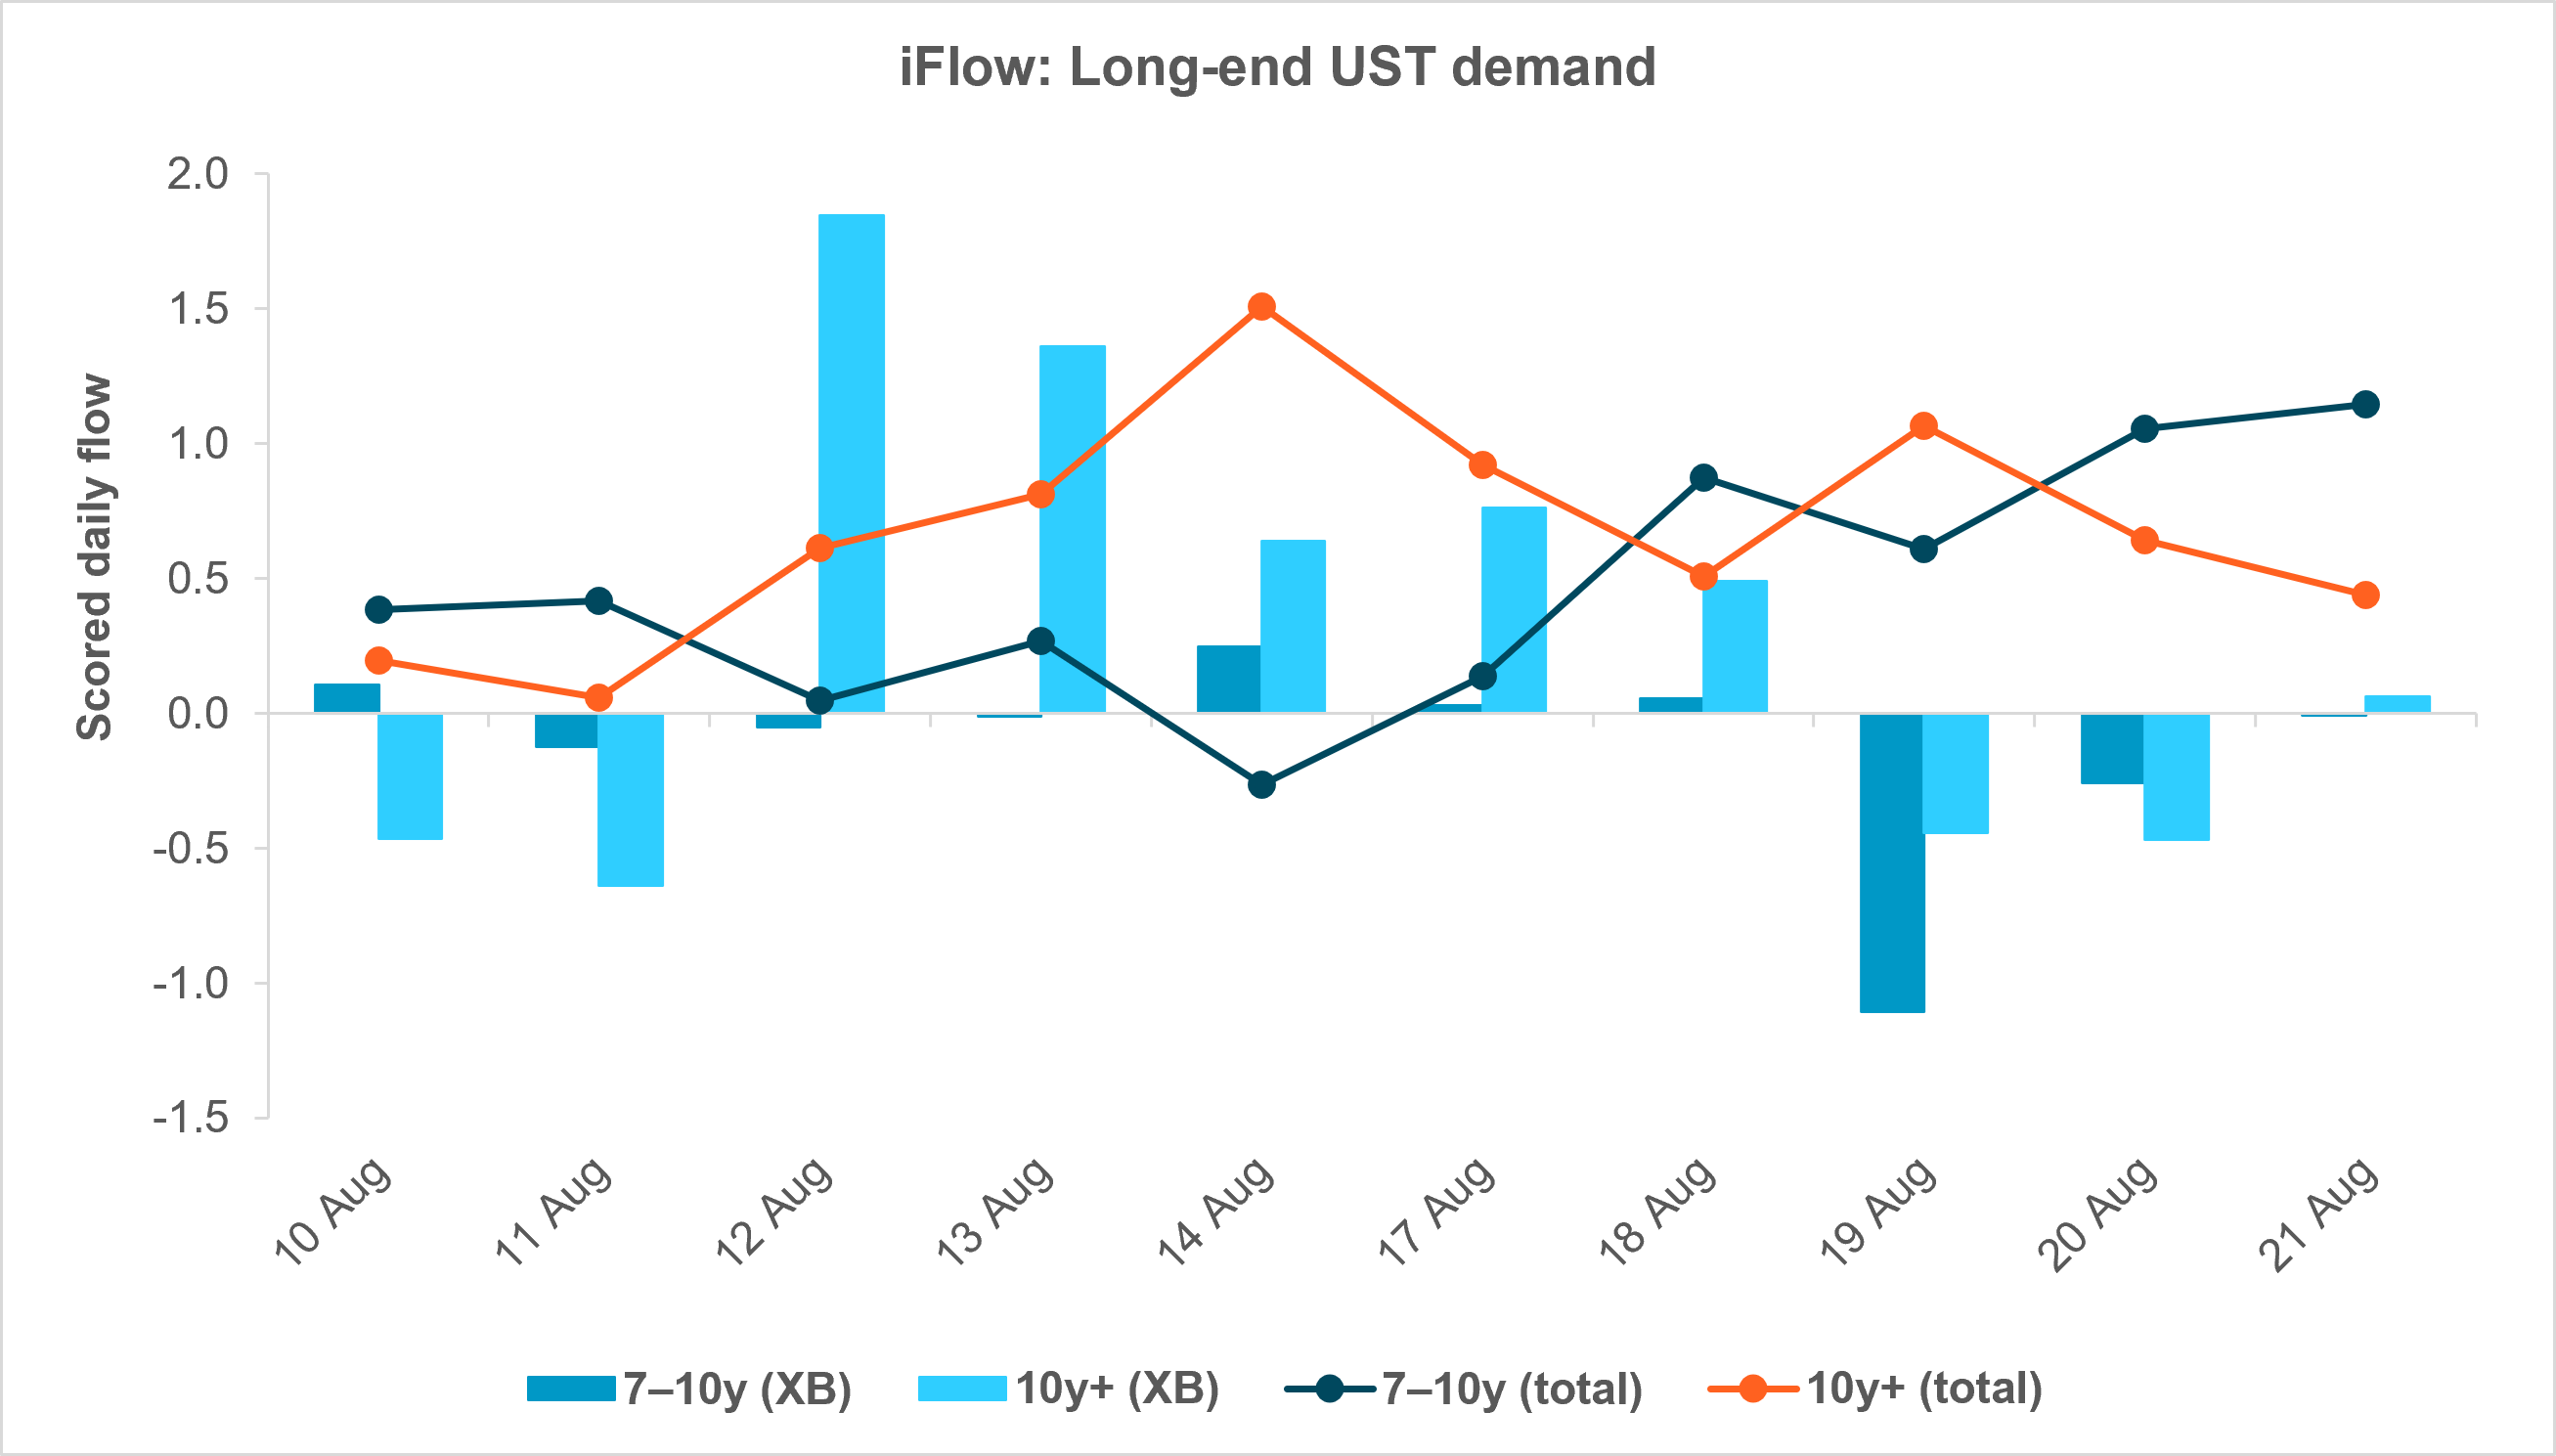
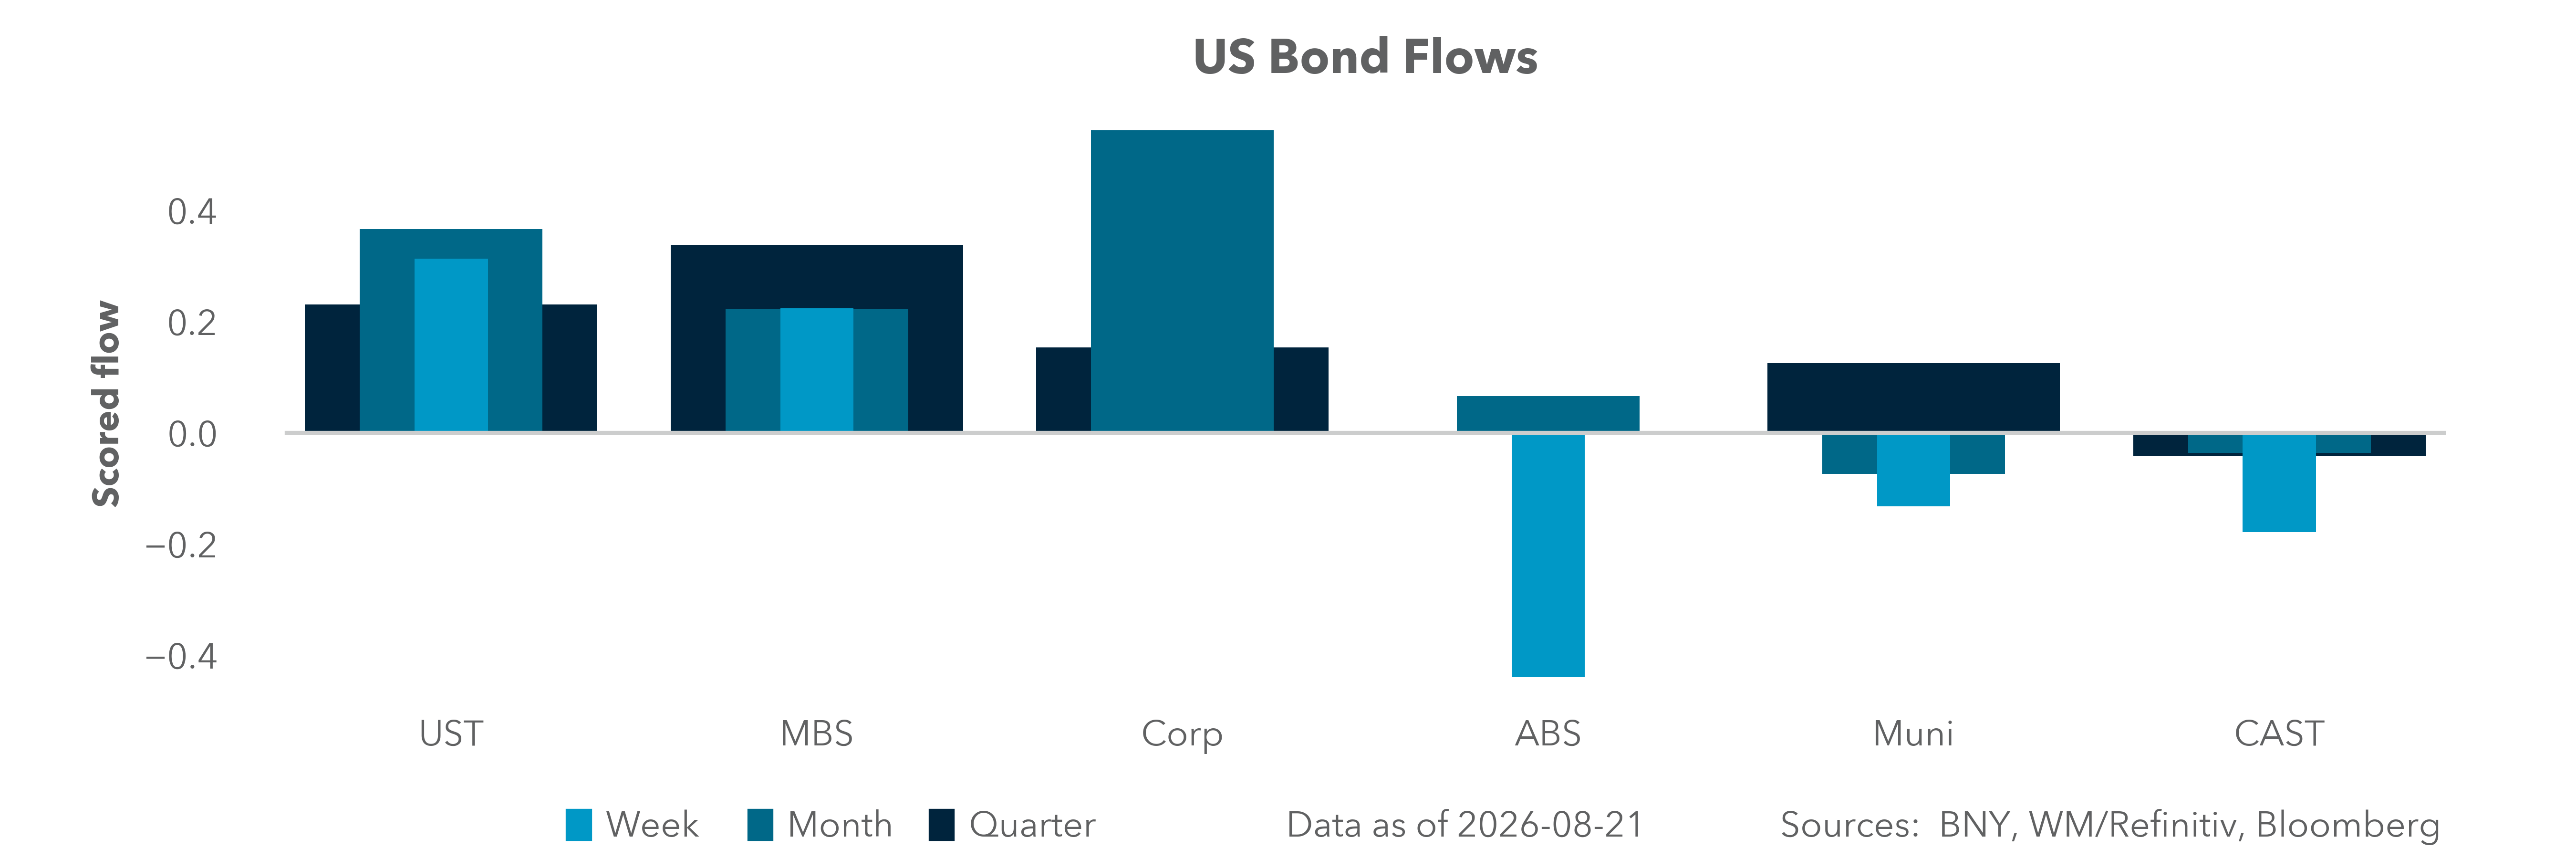
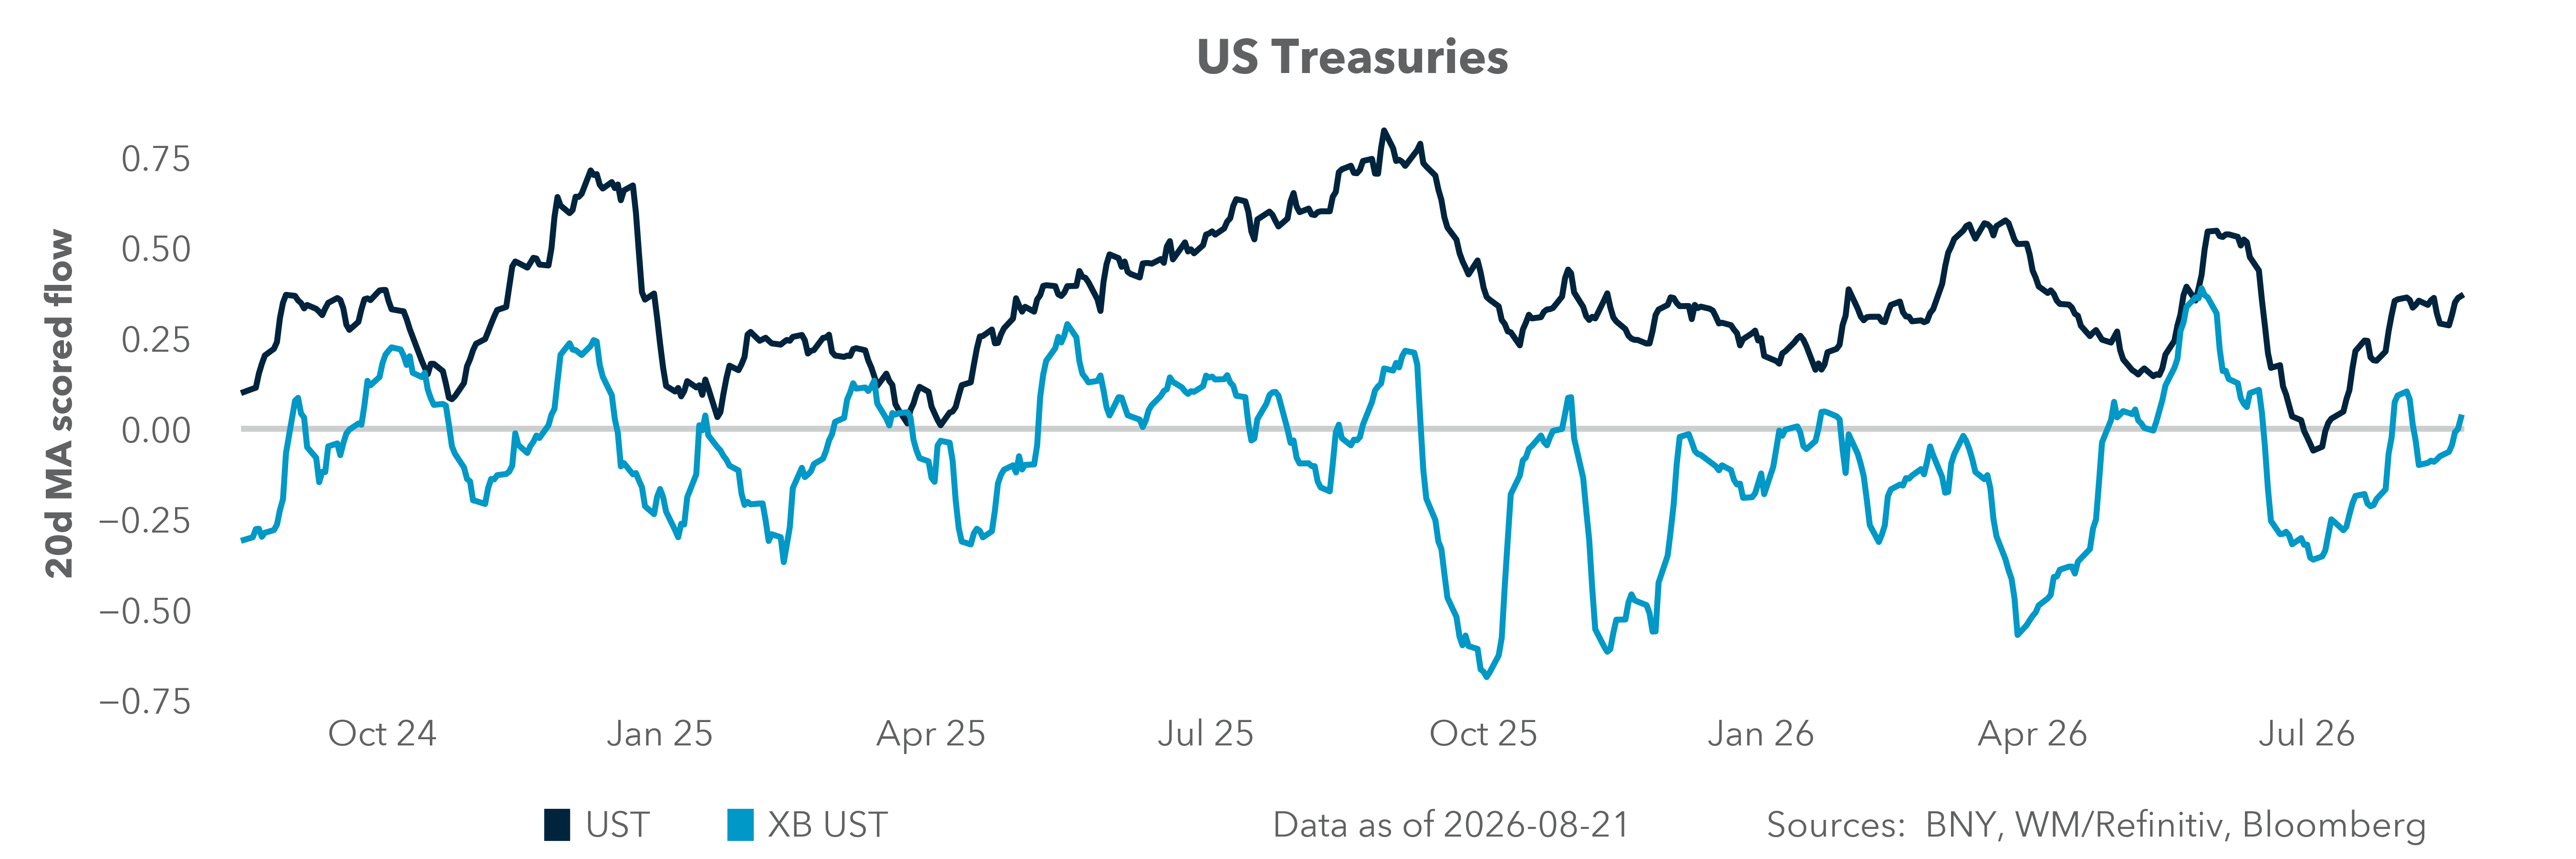
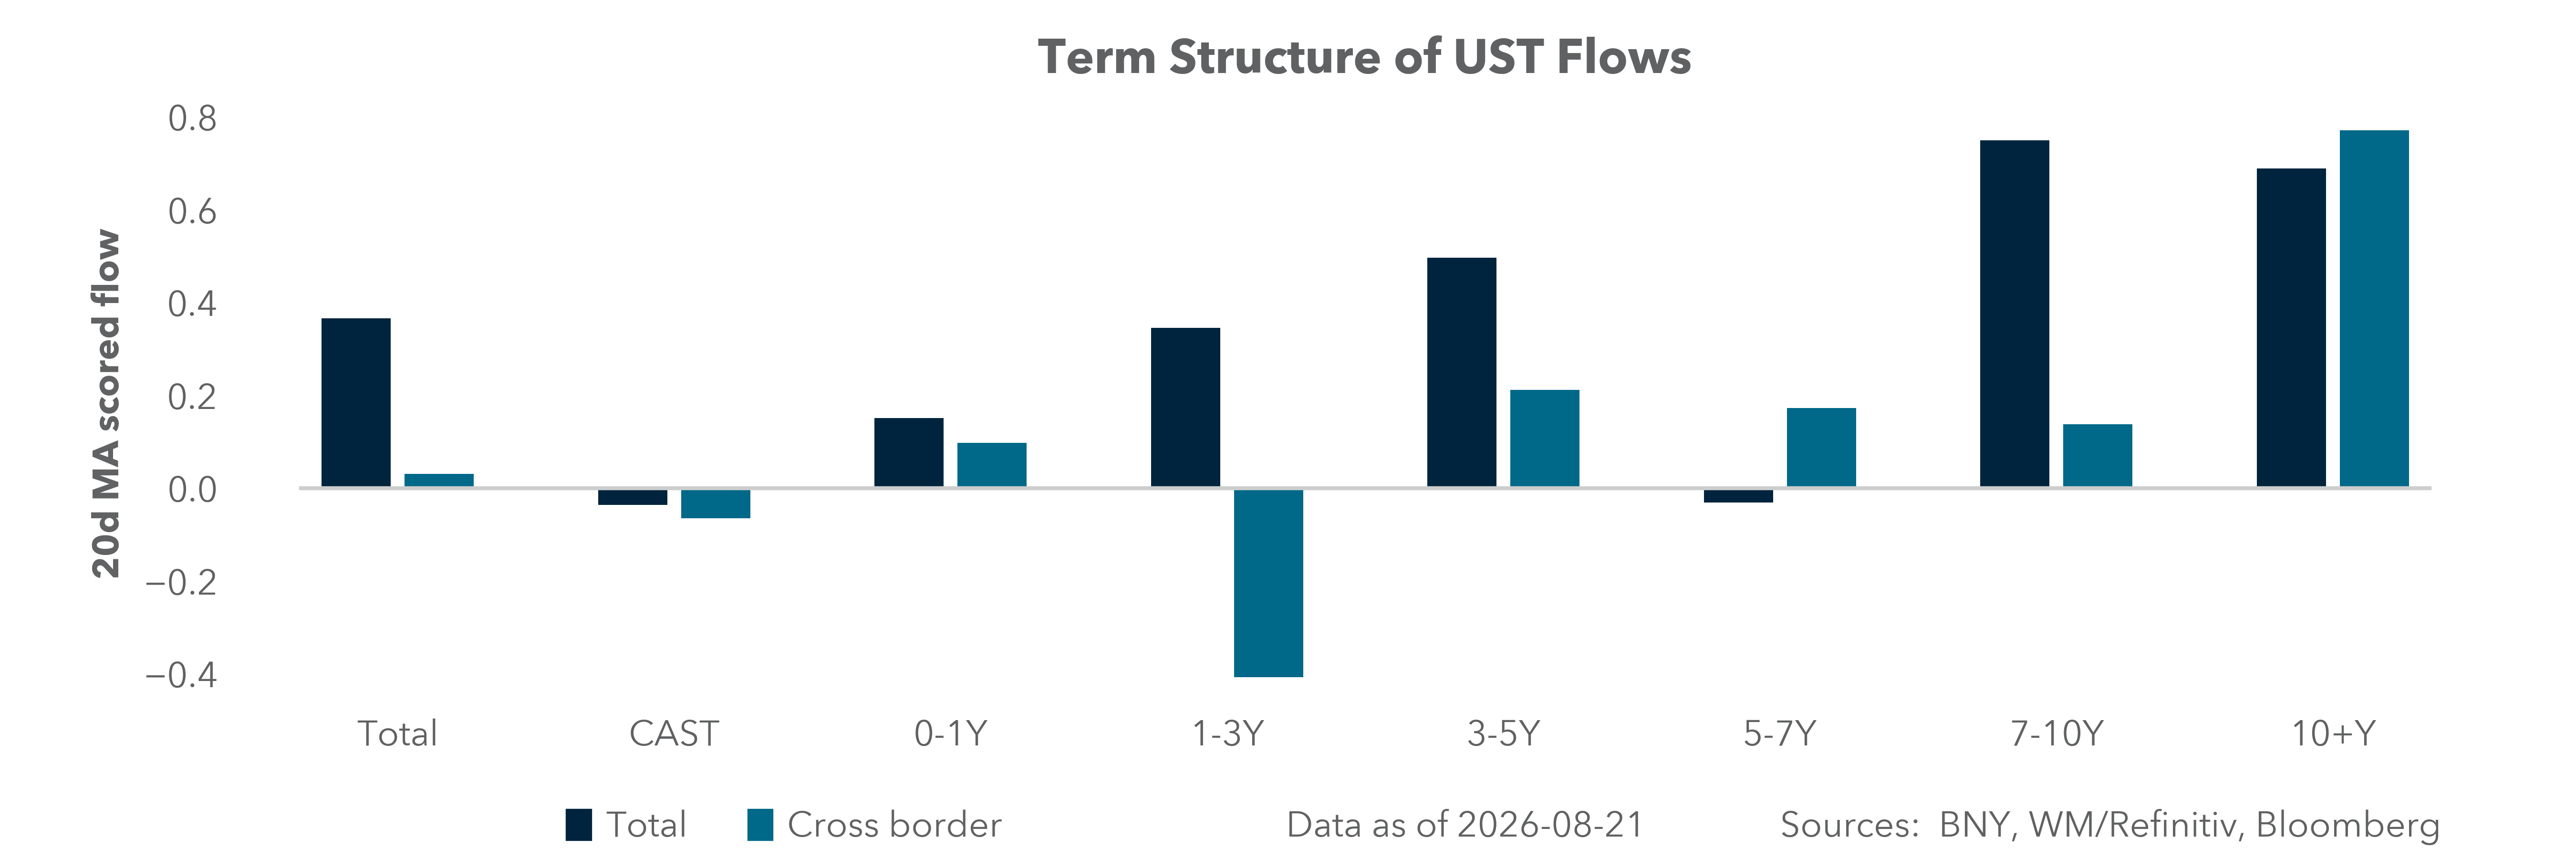
The brief rally and retrenchment in both yields and the term premium suggest that the operation, while potentially addressing a liquidity issue that may or may not exist, did little to change the overall negative tone at the long end of the curve. If the goal of the buybacks is to help contain long-end rates, then this maneuver looks to be too small in scope, and unlikely to alter the fundamentals that have led to higher yields at the back end in the first place. Fiscal concerns, waning foreign demand, increased demand for capital due to the AI capex story, and potential credibility concerns have weighed on long yields for some time now, and these considerations haven’t receded. Fundamentals matter. Interestingly, as Exhibit 3 shows, cross-border investors actually sold Treasurys on August 19, the day of the announcement, and demand hasn’t recovered since.
We view this development as dollar negative, not least because financing buybacks from the TGA would read to markets as fiscal expansion pushing the dollar lower. Furthermore, this “light” version of Operation Twist could result in further credibility concerns, especially if the action doesn’t materially alter the yield levels. Gold has rallied, almost mirroring broader dollar movement, reflecting those credibility concerns, especially the Treasury’s commitment to “regular and predictable” issuance across the curve. Indeed, if the operation doesn’t achieve its aim – which again, we’re told is liquidity support, but we infer is something more ambitious – the debasement trade could accelerate.