RMPs skipped for now, term premia keep rising
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
John Velis
Time to Read: 4 minutes
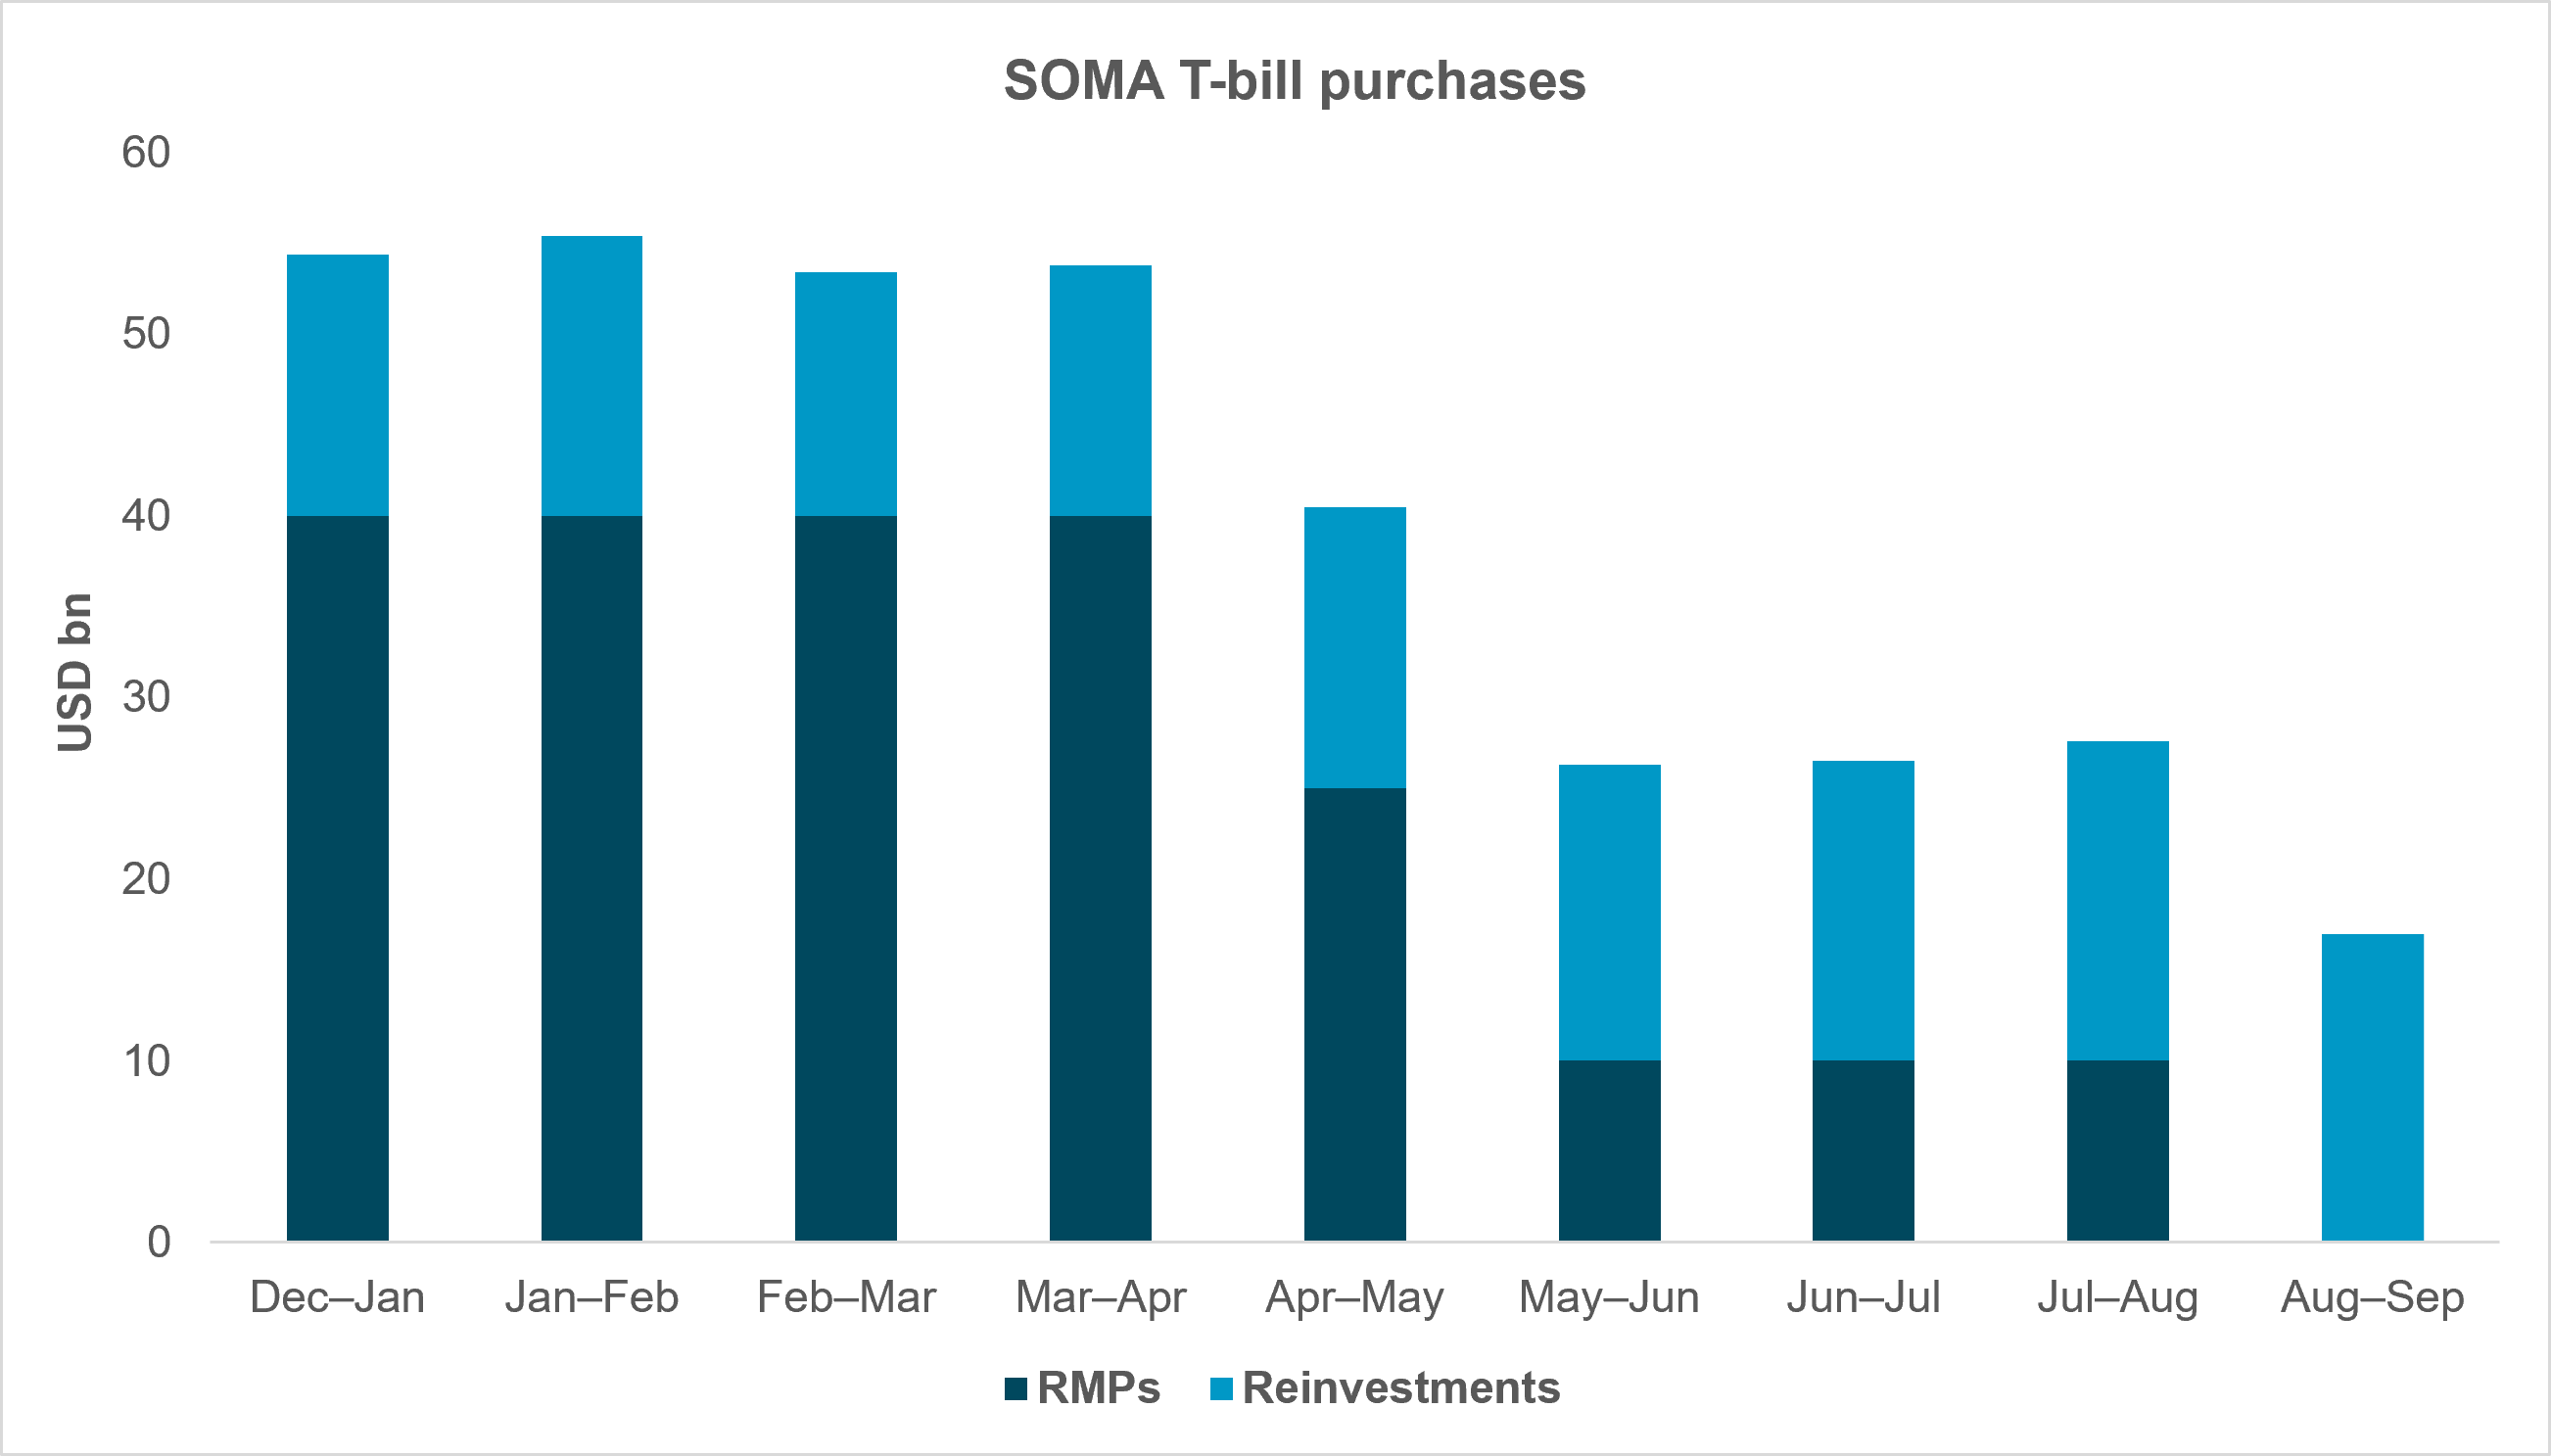
EXHIBIT #1: RMPS SUSPENDED IN AUGUST–SEPTEMBER PERIOD
Source: BNY Markets, Federal Reserve Bank of New York
Money markets are sufficiently liquid such that last week, the Federal Reserve Bank of New York declared that it wouldn’t engage in any reserve management purchases (RMPs) for the next four weeks. This is the first time since the RMPs started in December that the Open Markets Desk elected not to buy T-bills to prop up bank reserves. The Fed will still reinvest proceeds from maturing securities from the System Open Market Account (SOMA) into bills. This comes on the heels of a change in language on RMPs in the June and July FOMC implementation notes, which indicated RMPs would only be deployed “as appropriate,” indicating more flexibility in deciding to employ them.
Exhibit 1 shows the evolution of bill purchases by the Fed since December, split between RMPs and security reinvestment. Over that time, the central bank will have bought just over $350bn in securities, coming close to the $400bn we had estimated would be the minimum size of total bill purchases in 2026. We don’t think that the RMPs are completely finished, and they could restart this fall should liquidity conditions warrant. The Fed has always asserted that the RMP program would be flexible, with SOMA manager Roberto Perli declaring in early June that “temporary pauses in RMPs could occur if money market conditions warrant. That represents flexibility that the Desk could use in the future, for example if money market conditions eased again substantially.”
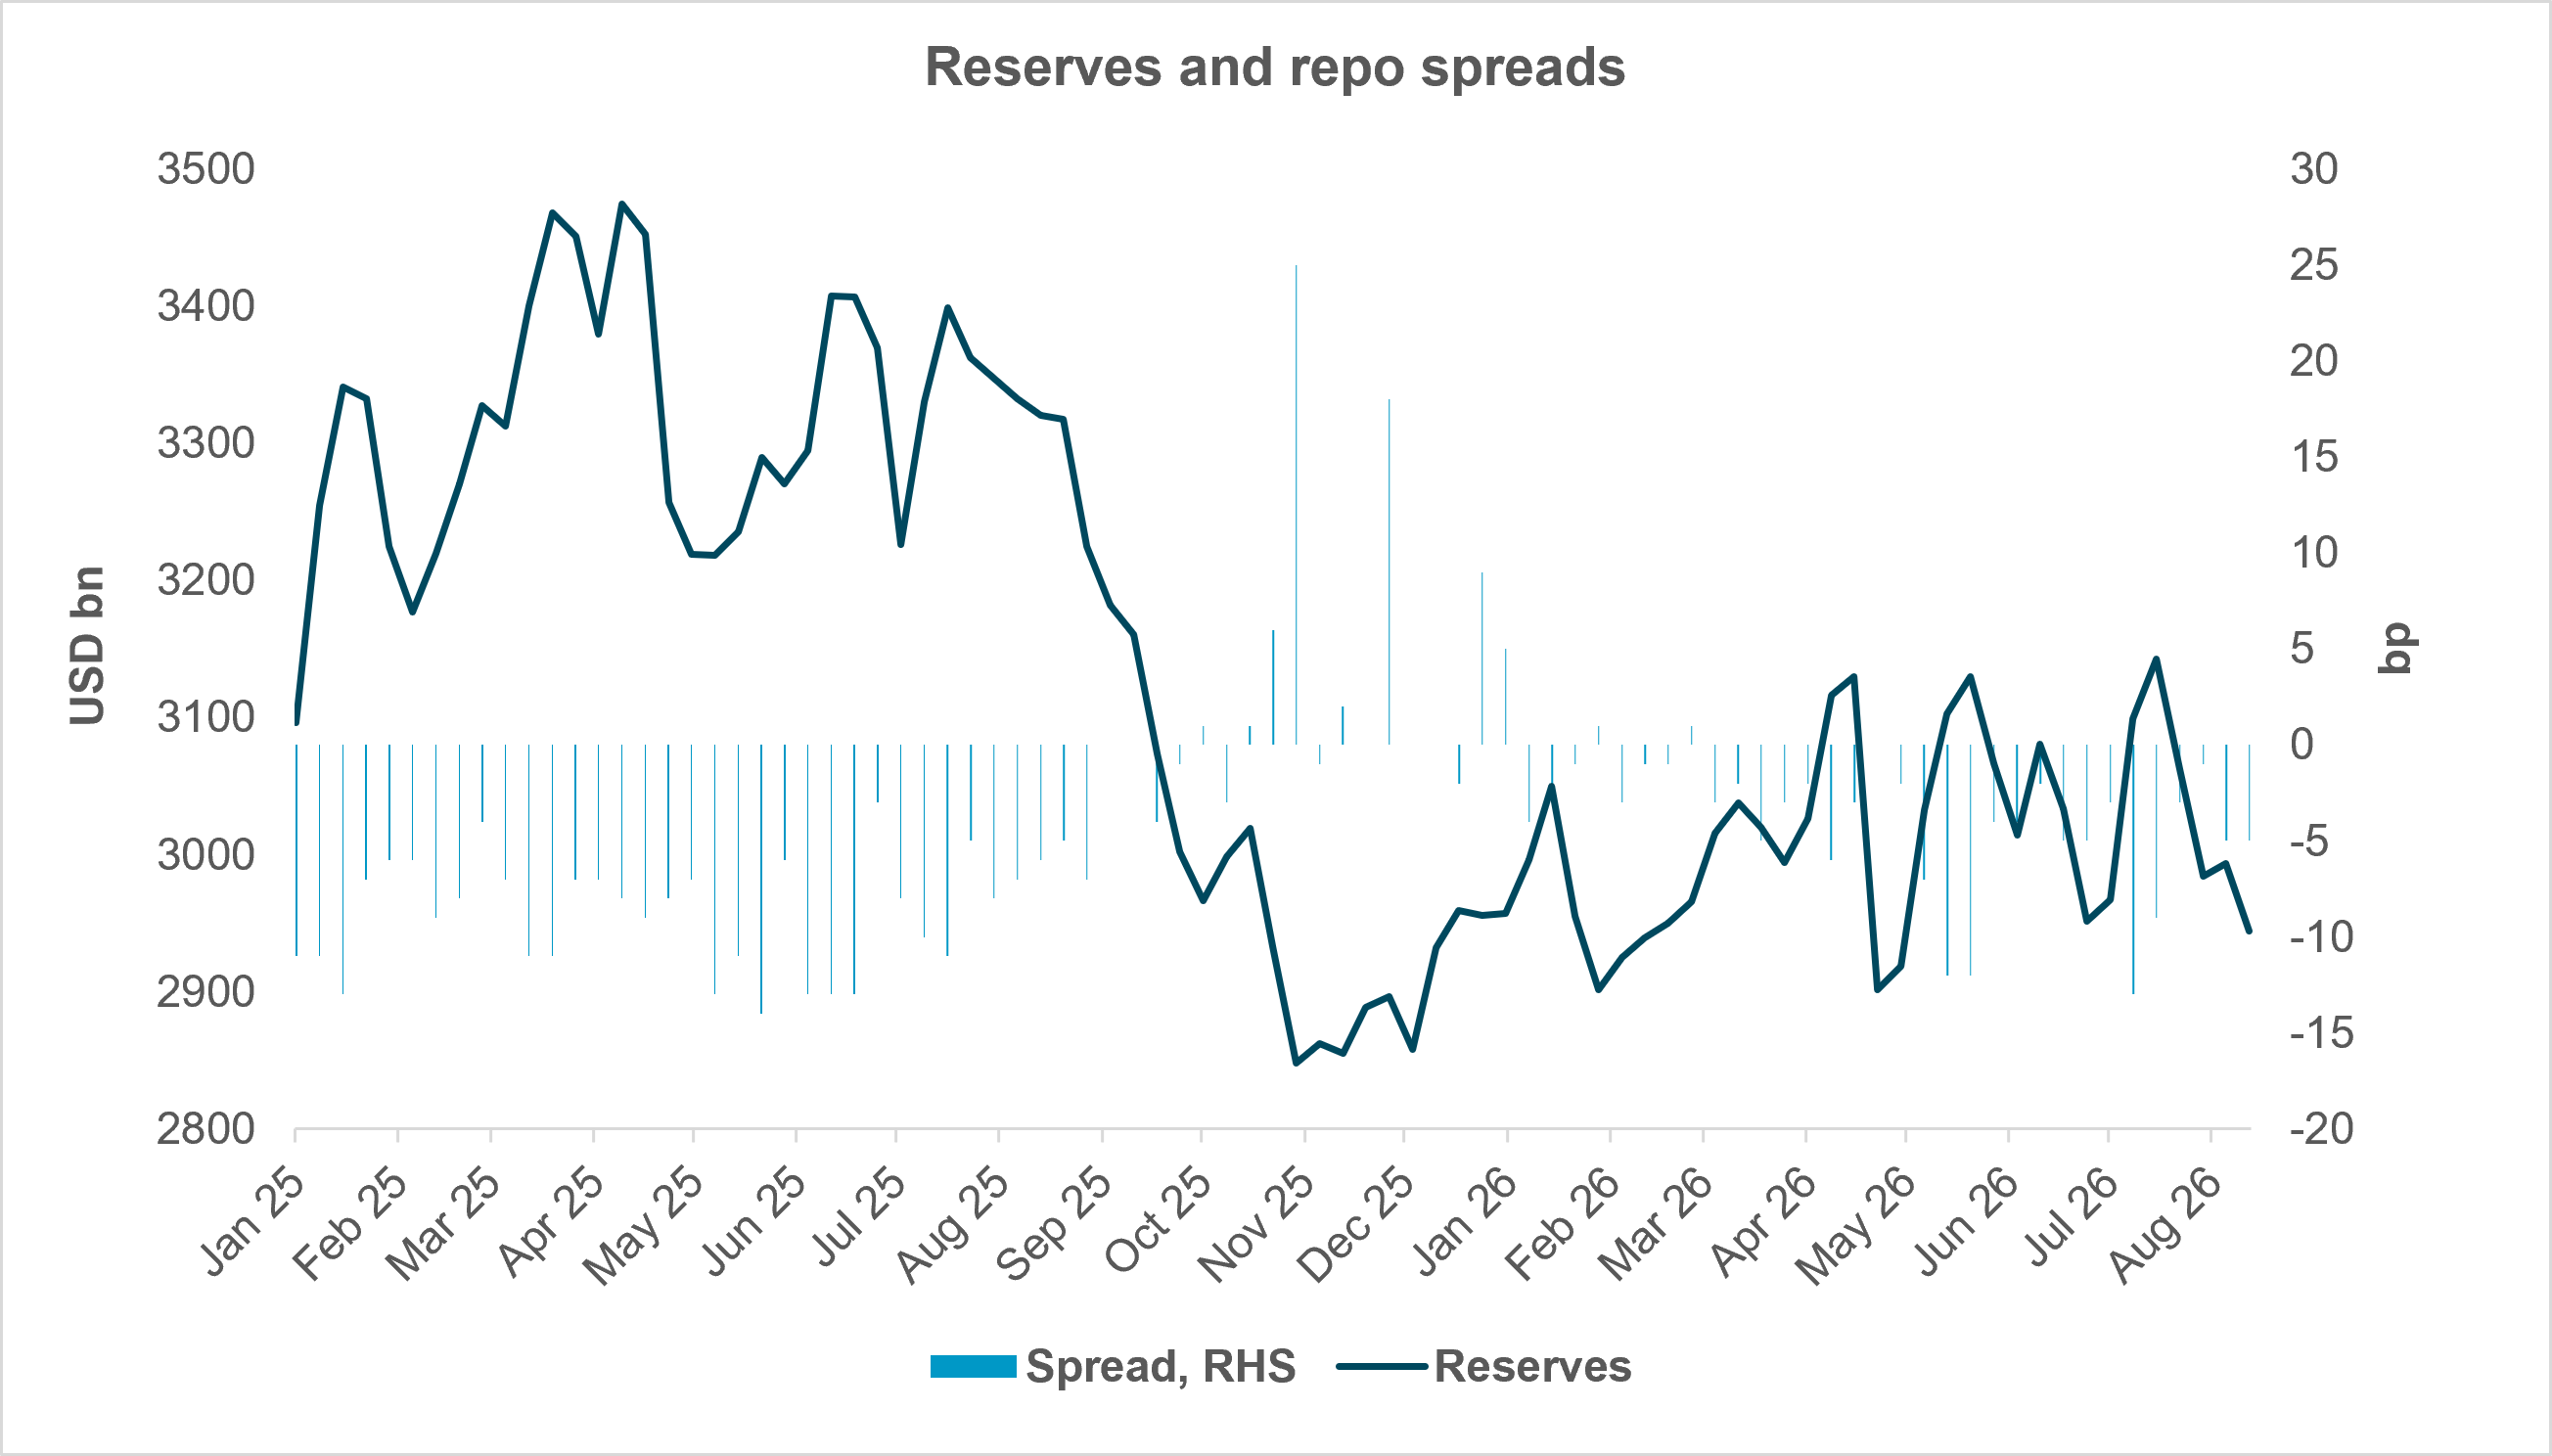
EXHIBIT #2: CLEAR RELATIONSHIP BETWEEN RESERVES AND FUNDING SPREADS
Source: BNY Markets, U.S. Treasury Department
To be sure, funding markets haven’t shown any signs of strain, with cash abundant and spreads narrow throughout most of the summer. Exhibit 2 shows the behavior of the TGCR spread over the interest rate on borrowed reserves alongside the quantity of reserves on the liability side of the Fed’s balance sheet. Note that last autumn, as reserves dipped well under $3tn, repo spreads widened out, prompting the initiation of the RMP program at the end of 2025. Currently, reserves are just below $3tn, but well above the $2.85tn observed at the end of last October.
We don’t know how liquidity conditions will evolve as we head into the last four months of the year, but we are comforted knowing that the Fed is actively managing liquidity even with reserves in an ample state. With the Treasury expected to issue over $1.3tn in T-bills through December (according to the latest financing estimates), liquidity conditions will not be static. Issuance drains reserves, all things equal, although redemptions and reinvestments by the Fed will blunt that to some degree. Nevertheless, we don’t think we have seen the last of the RMPs this year – it just may be a few months from now that they restart.
The last 10 days or so have produced a series of weaker economic data in the U.S., particularly in the form of a poor jobs report for July, a large drop in the University of Michigan’s Consumer Sentiment survey and soft CPI and PPI inflation prints. As a result, the front of the yield curve has rallied. The 2y note yield has fallen from a recent high of 4.35% in late July to just 4.17% today, and the swaps curve is now pricing in less than one full rate hike by the end of the year. However, we view with interest the fact that longer-maturity yields have reacted much less aggressively, with the 10y yield still around 4.7% and the 30y bond well above 5.2% for some time now.
That the longer end of the curve has missed out on the rally is notable and begs the question: why? We don’t think it’s inflation expectations, something which many observers default to as an explanation for the reticence of the long end to rally. We have been on record numerous times dismissing this argument, noting that inflation expectations over long horizons haven’t moved higher since the U.S.–Iran conflict started. Both market-based measures (like the 5y5y inflation swap or the 10y breakeven) and survey measures (like the New York Fed’s and the Conference Board) don’t show any meaningful pickup in expected inflation over the next five to ten years.
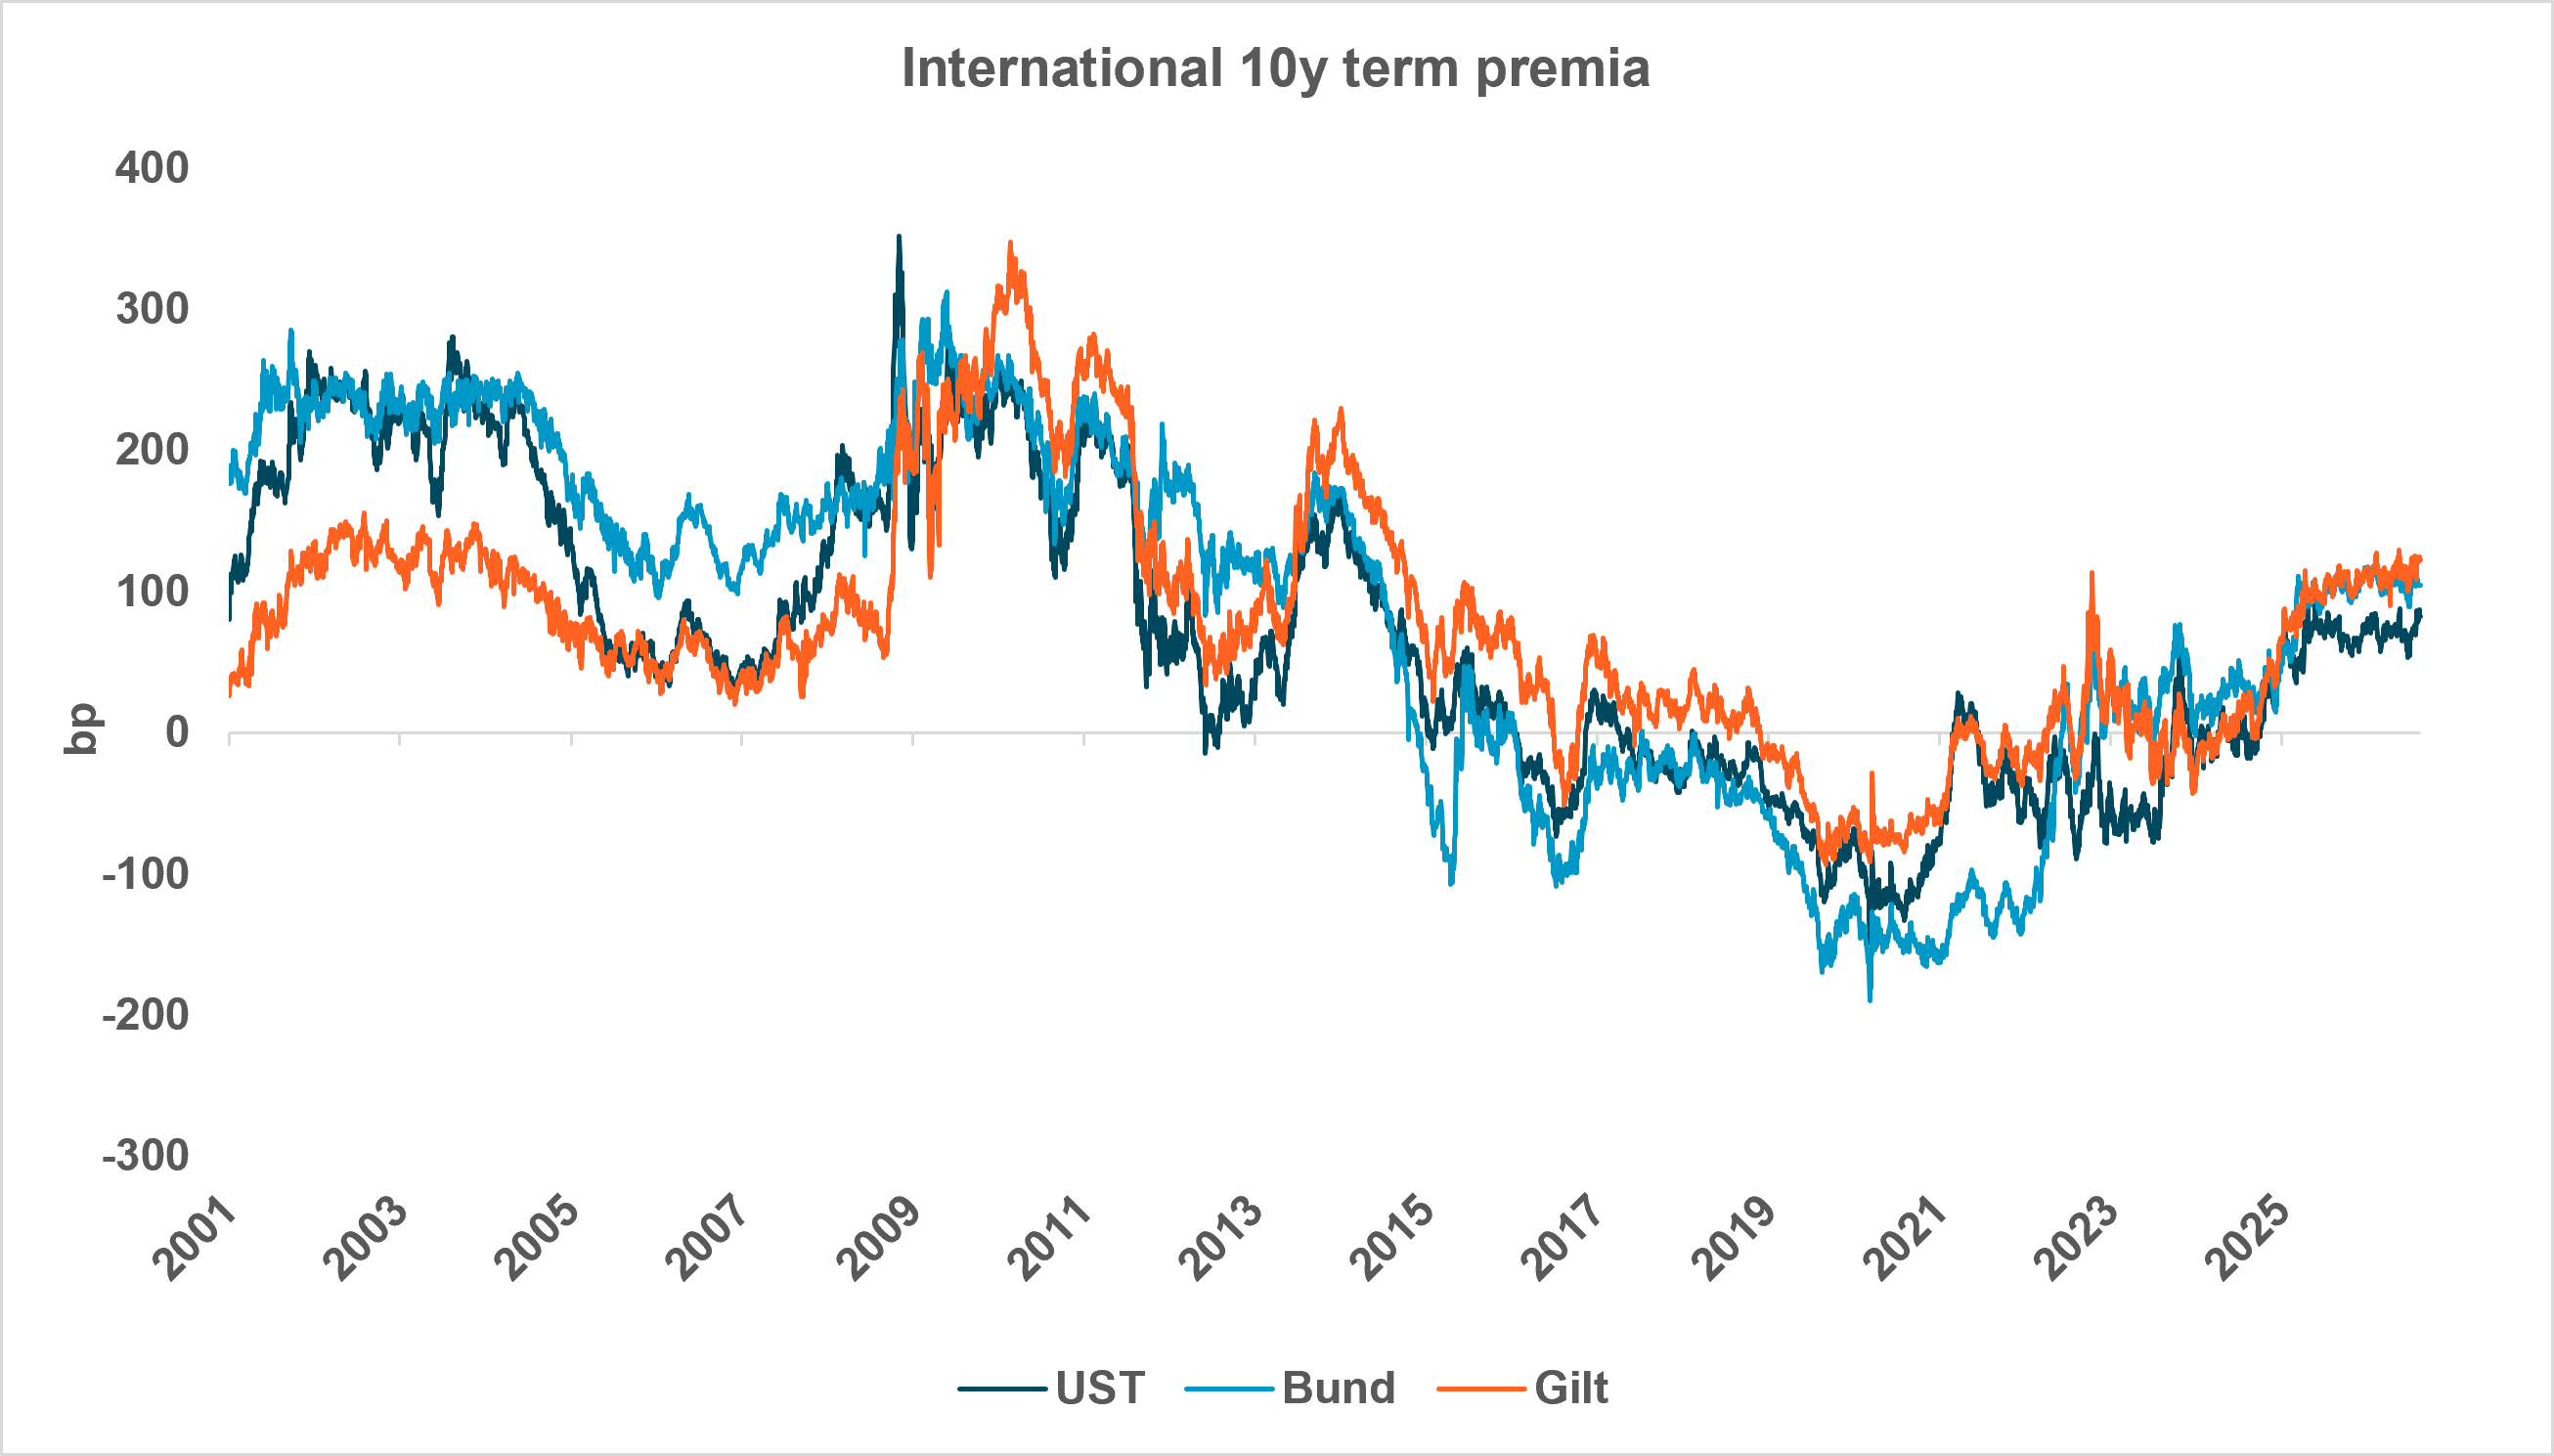
We instead attribute the elevated yields to the perceived riskiness of these securities. We can measure this through readily available estimates of the Treasury term premium. This concept quantifies the additional compensation that an investor requires for lending long to the government. When the term premium rises, it signals that investors are worried about things like liquidity, solvency, volatility, and general uncertainty. In the U.S., the 10y term premium is now around 80bp (according to the NY Fed’s estimate), the highest it’s been since the mid-2010s.
EXHIBIT #3: TERM PREMIA UP GLOBALLY
Source: BNY Markets, Bloomberg
This isn’t just a U.S. phenomenon, however. We can examine term premium estimates for the U.K. and Germany, and we plot them in Exhibit 3. Note that all three 10y benchmark bonds have displayed similar term premia increases over the same horizon. Is public debt becoming so worrying now that investors (i.e., sovereign lenders) need lower bond prices – and higher yields through real rates and term premia – to hold sovereign debt? We think this is a strong possibility.
December rate hike expectations continue to recede this past week thanks to well-behaved inflation data and a surprise drop in consumers’ retail spending. Current expectations for the end of the year show less than a full chance of a hike, while the very next meeting, September 16, has around 30% priced in, down from over 70% at the beginning of August. This reinforces our view of no moves this year, although there’s always a risk geopolitics will heat up further and send energy prices – and headline inflation – higher. While we continue to expect no hikes this year, we also continue to acknowledge that the risk is to the upside, especially with hawks on the Committee publicly pushing for hikes.