Propping up the UST market
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.

John Velis
Time to Read: 5 minutes
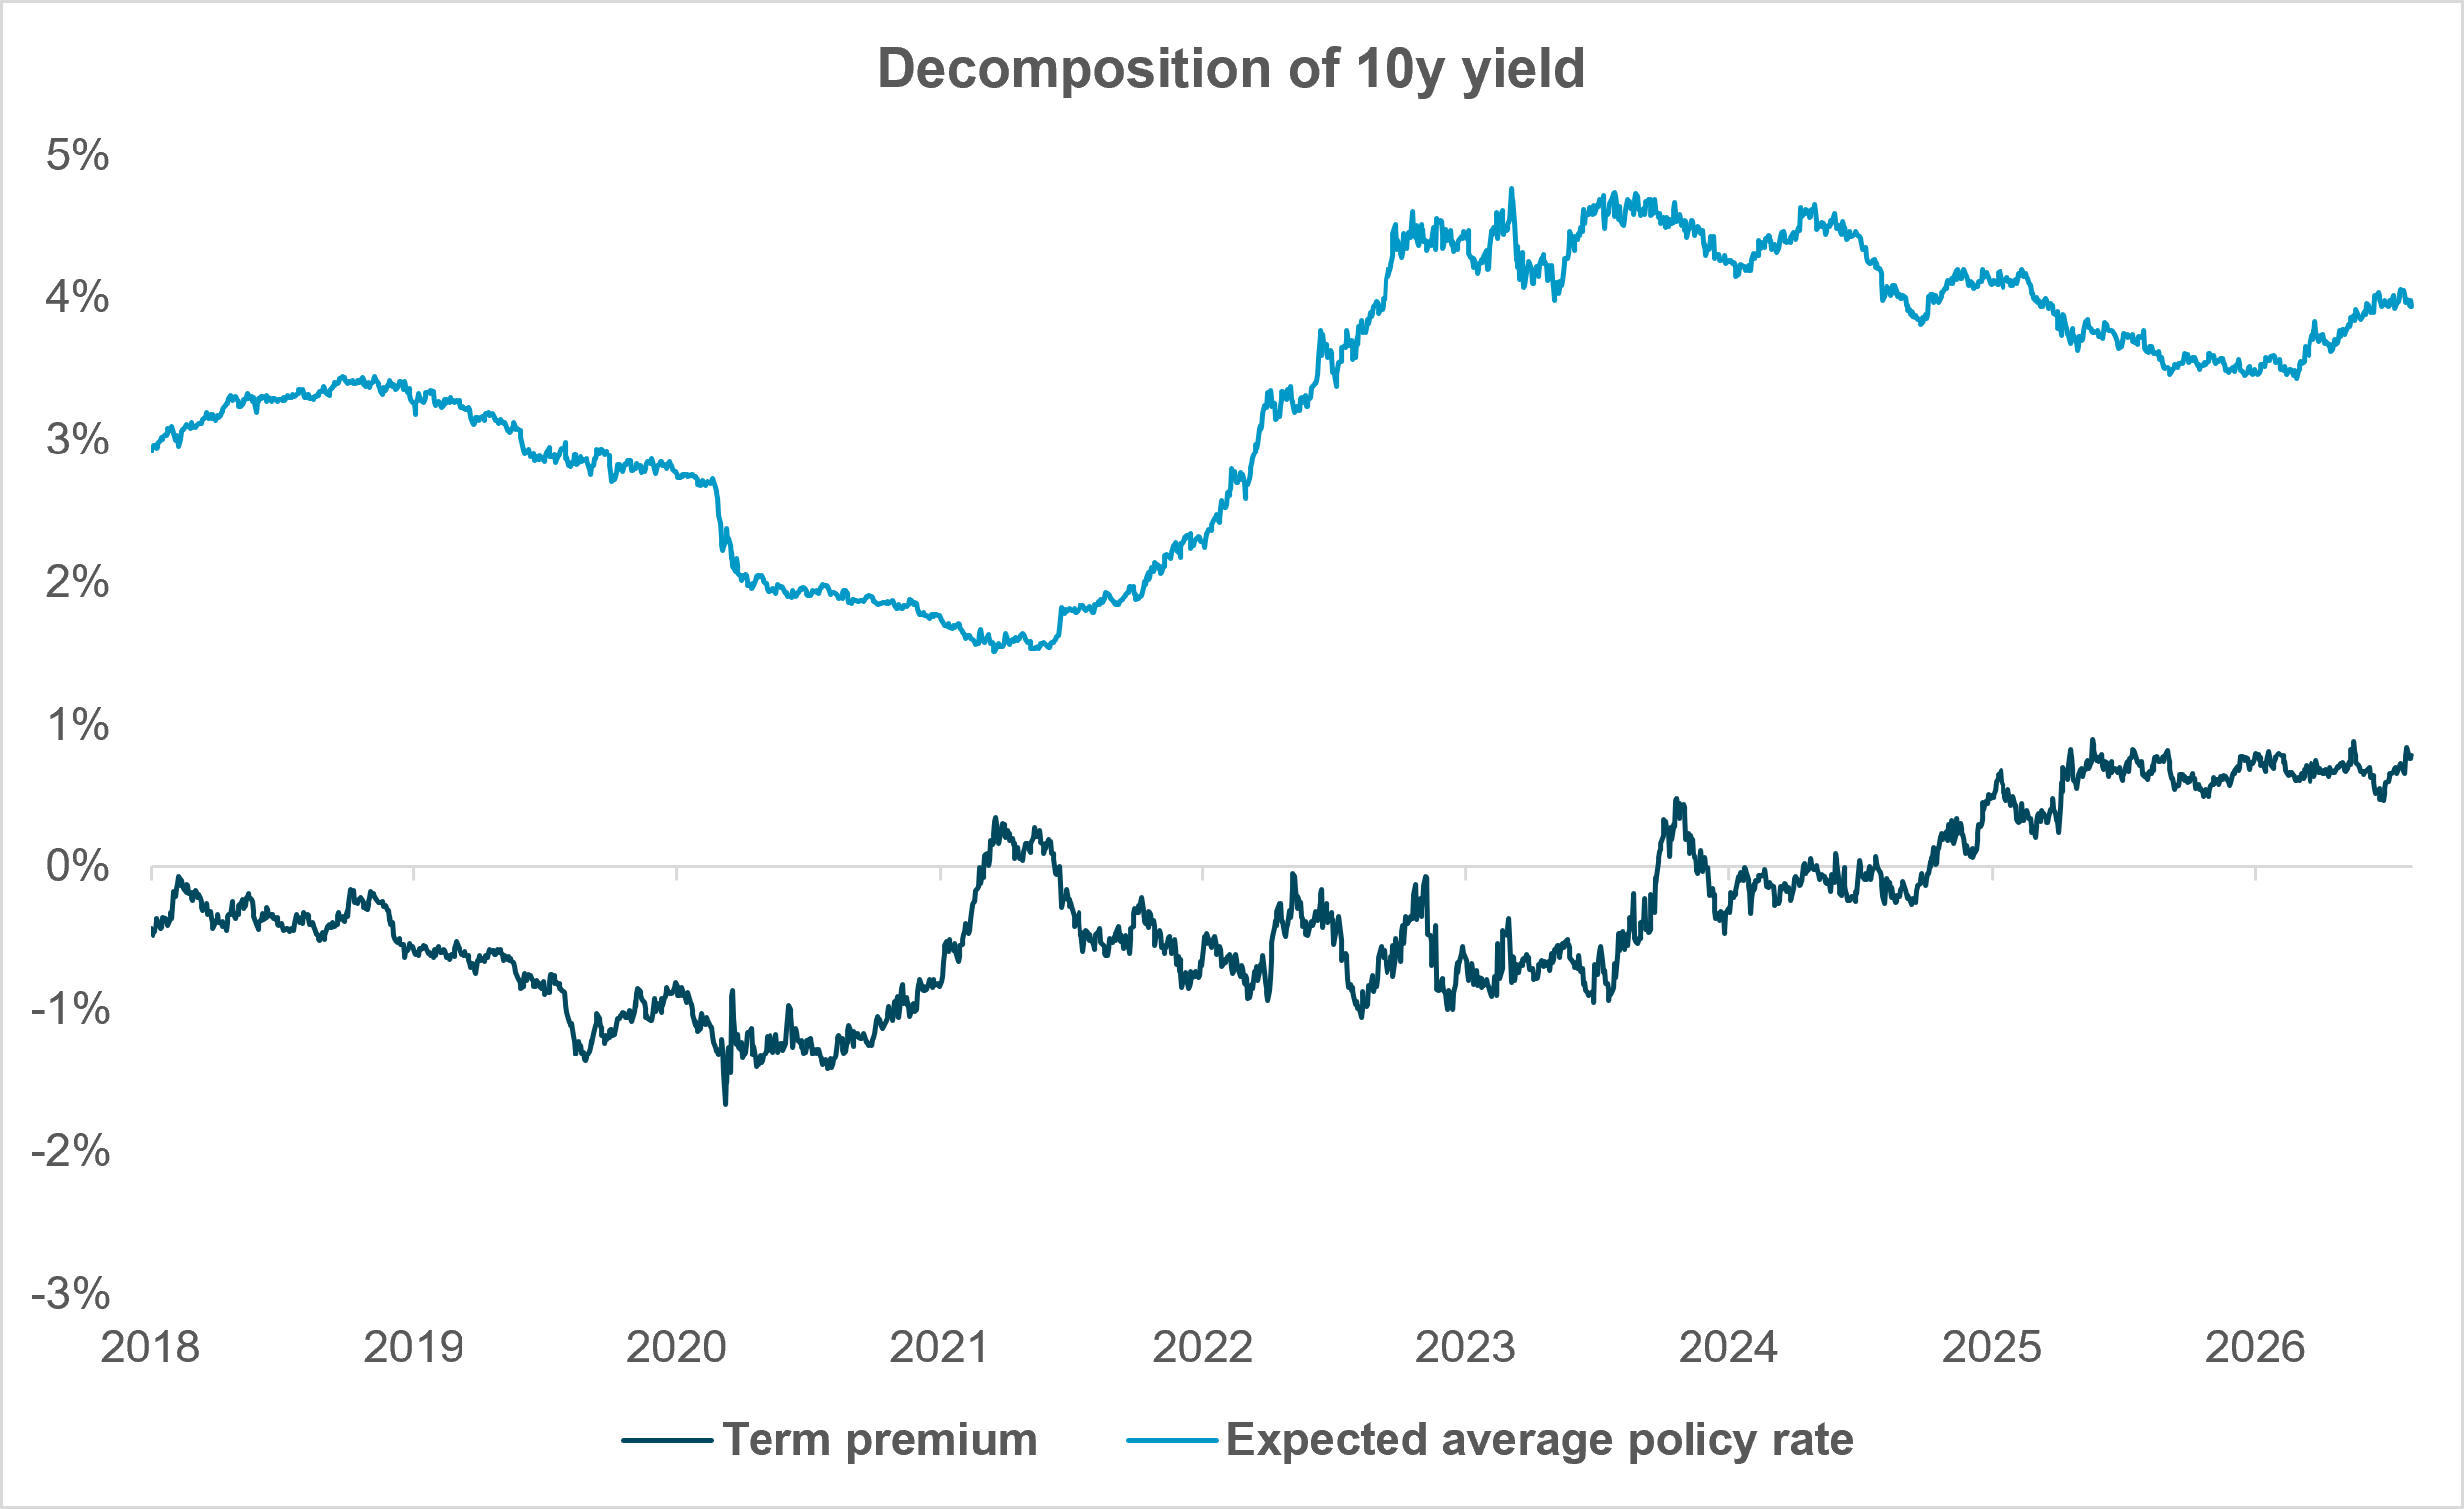
EXHIBIT #1: HIGHER EXPECTED SHORT RATES, HIGHER RISK PREMIUM
Source: BNY Markets, Federal Reserve Bank of New York
The Treasury’s quarterly funding announcement was notable for a subtle change in language around the future path of coupon issuance after this quarter, prompting some discussion about financing plans in 2027 and whether coupon issuance remains unchanged in subsequent quarters. Combined with the details of the U.S.’s coordinated intervention to support the move by Japan’s Ministry of Finance (MOF) to reverse the yen’s steep decline on Friday, July 31, questions have emerged about the Treasury’s willingness to tolerate large-scale sales of longer-dated notes and bonds.
Let’s first discuss the quarterly financing policy statement, released last Wednesday. All the borrowing increases this coming quarter will be via T-bills, with no change in coupon auction sizes. This wasn’t unexpected and is in keeping with Treasury policies under Secretary Scott Bessent. In the statement, it was asserted that (italics ours) “Looking ahead, Treasury continues to evaluate potential future changes to nominal coupon and FRN auction sizes…” In previous policy statements, the line had referred to “potential future increases” in coupon offerings.
Furthermore, the Treasury Borrowers Advisory Committee (TBAC) noted in its most recent minutes that it “continues to believe that increases in coupon issuance could be warranted in FY2027 and discussed potential changes to the forward guidance for Treasury to consider.” We would agree that some increase in note and bond issuance is necessary with an expected revenue shortfall in coming quarters, and the proportion of T-bills as a percentage of total marketable debt above 20% and likely to stay that high. But for the first time in this current administration, Treasury elected to soften the language related to future auction sizes and leave it ambiguous for now.
Related to the joint yen intervention at the end of the previous week, it was notable that while the MOF sold U.S. dollars directly to fund JPY purchases, Treasury sold euros out of its Exchange Stabilization Fund (ESF) to buy yen, opting not to use dollars – presumably to preserve USD in the ESF and not increase the global supply of dollars. By supporting the Japanese intervention, Treasury alleviated the MOF’s need to undertake U.S. sovereign bond sales to raise more dollars to sell into the market and prop up the JPY.
After the intervention that Friday, Bessent suggested that Japan could use the Fed’s Foreign and International Monetary Authorities repo facility (FIMA repo) to pledge USTs as collateral in return for USD funding, with which the MOF could intervene to buy yen, obviating the need for Japan to sell USTs into the open market to raise dollars to sell for JPY. FIMA repo, a facility introduced by the Fed in 2021with a $60bn counterparty limit, offers liquidity in return for UST collateral, subject to an interest rate of IORB plus 25bp. Bessent last week posted his desire to see the Fed “upsize” the facility, presumably to encourage Japan to use it for intervention as opposed to outright UST sales.
Do these statements and actions suggest that there is concern about the long end of the UST curve? We have commented on the rise in 10y and 30y yields and our belief this represents both concern over the U.S.’s fiscal trajectory and the need for equilibrium policy rates to be higher over the long term. Exhibit 1 shows a common decomposition of the 10y yield calculated by the Federal Reserve Bank of New York. The darker line represents the term premium – the additional compensation in the form of higher yields that an investor requires to lend to the U.S. government over a ten-year period. It represents investors’ view on fiscal reliability and sustainability, inflation and liquidity uncertainty, and the time value of money. At almost 80bp currently, it’s at its highest level since 2014. The expected short rate is also rather high relative to the last decade, close to 4%, indicating the market’s view about the natural rate of interest, r*.
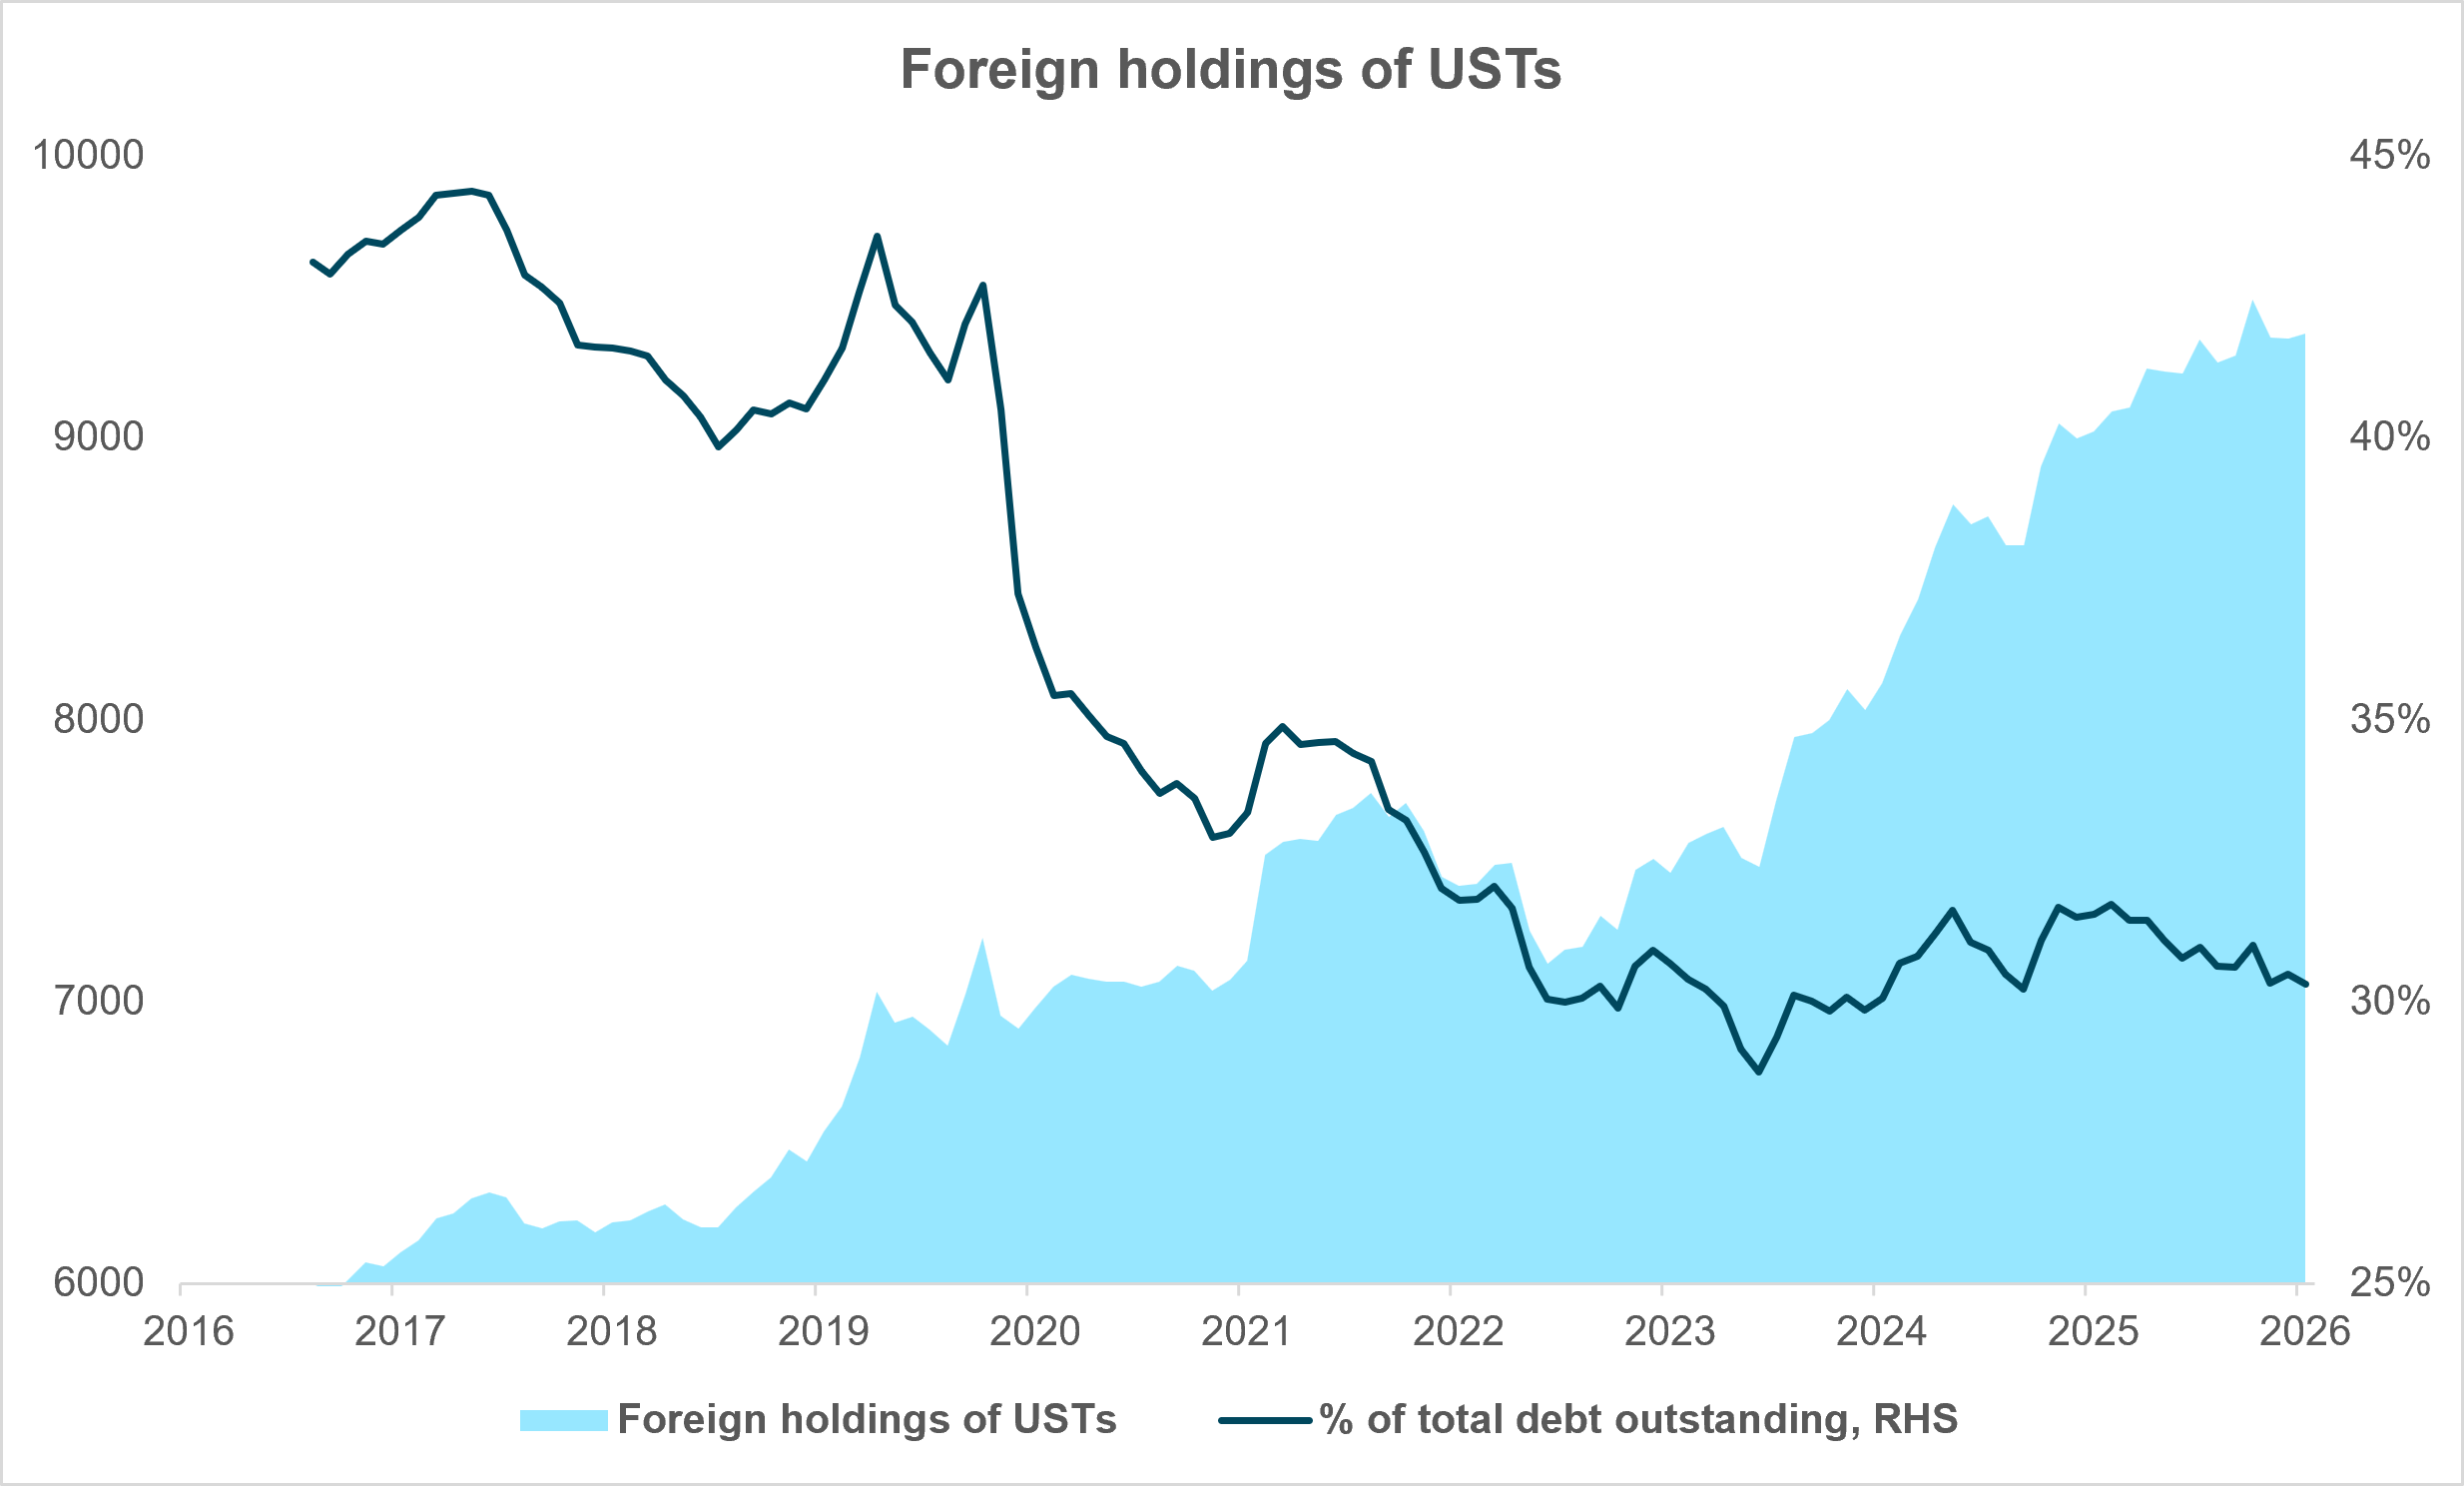
EXHIBIT #2: FOREIGN HOLDINGS OF USTS INCREASE, BUT NOT AS A PERCENT OF SUPPLY
Source: BNY Markets, U.S. Treasury Department
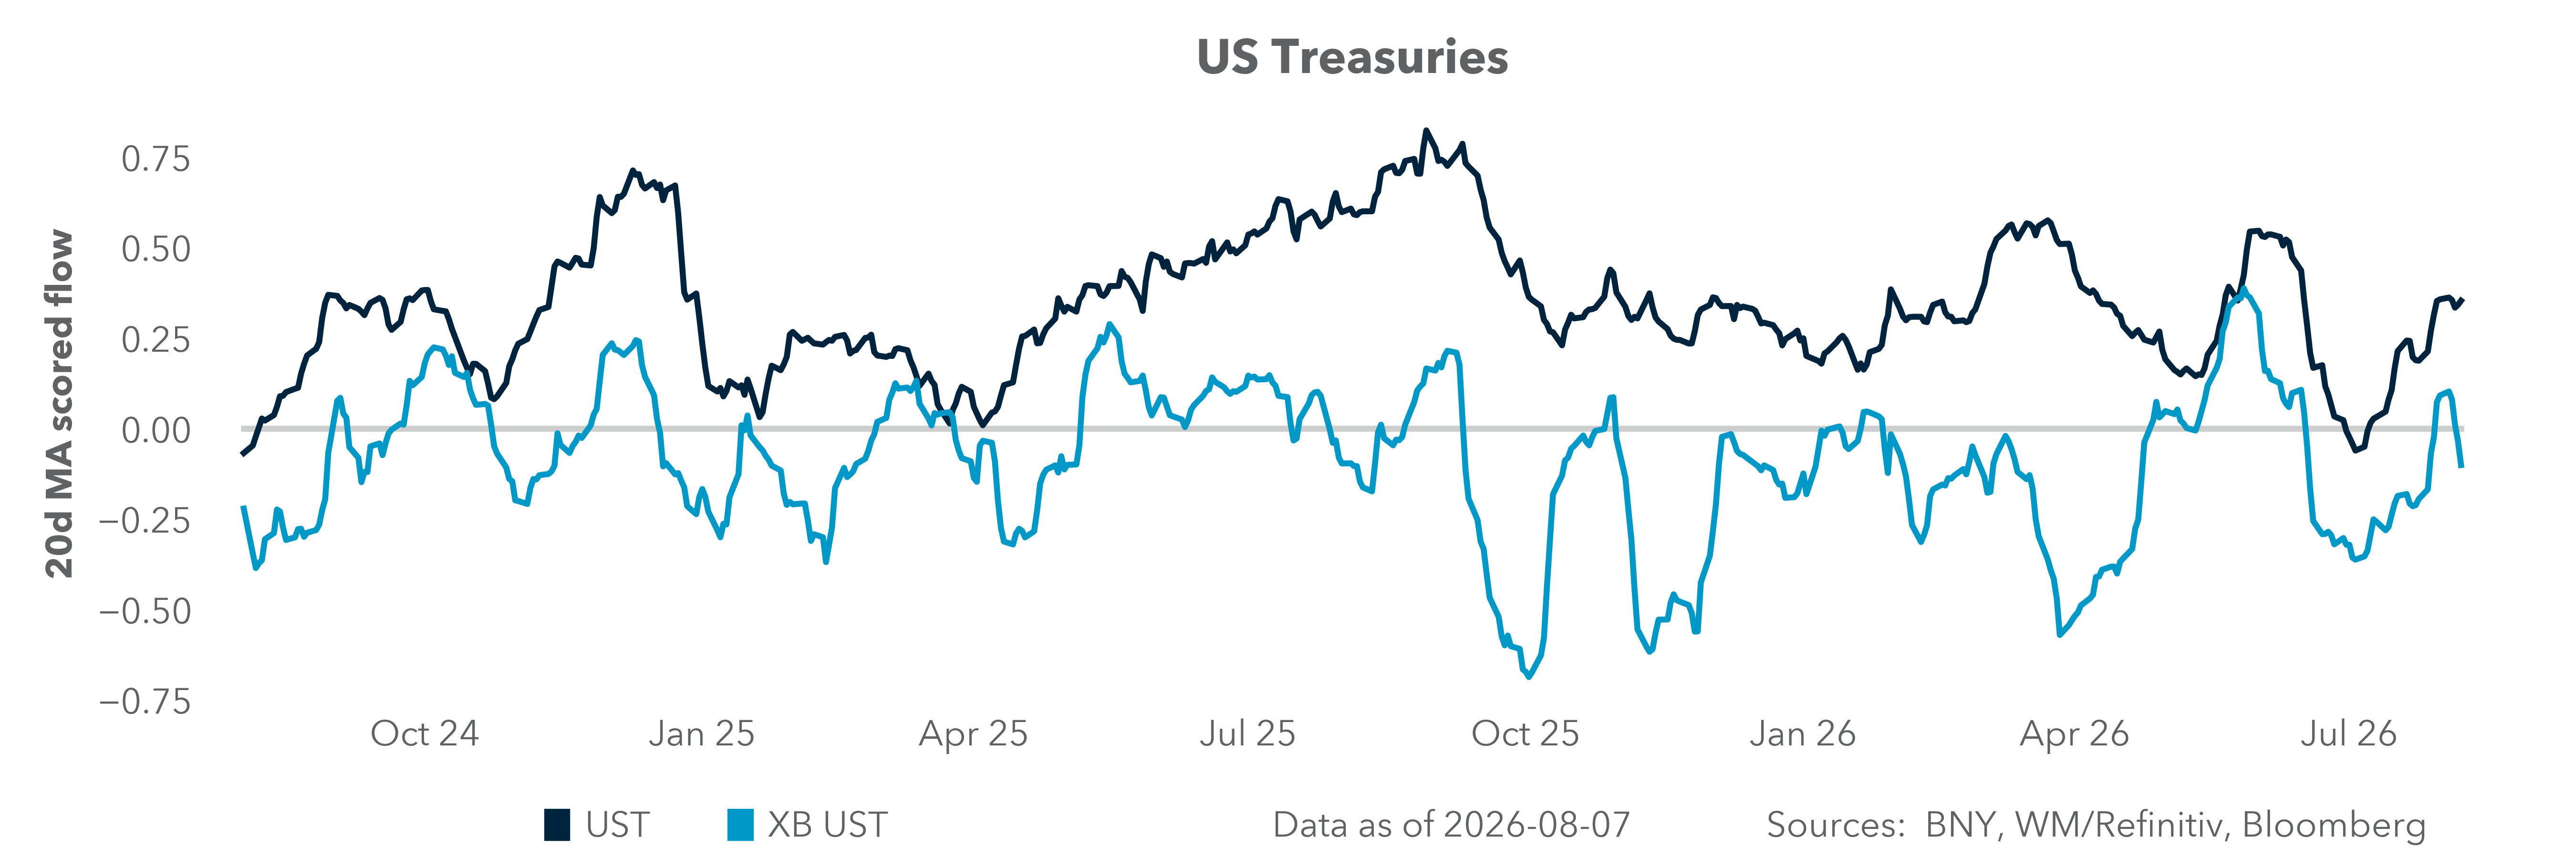
Foreign demand for USTs has been relatively flat since COVID, as Exhibit 2 shows. It plots the U.S. Treasury’s TIC data and displays foreign holdings (both as a total and a percentage of USTs outstanding held abroad). While total holdings have grown since the pandemic, foreign holdings as a percent of all U.S. sovereign debt are down from nearly 50% a decade ago to below one-third through May 2026.
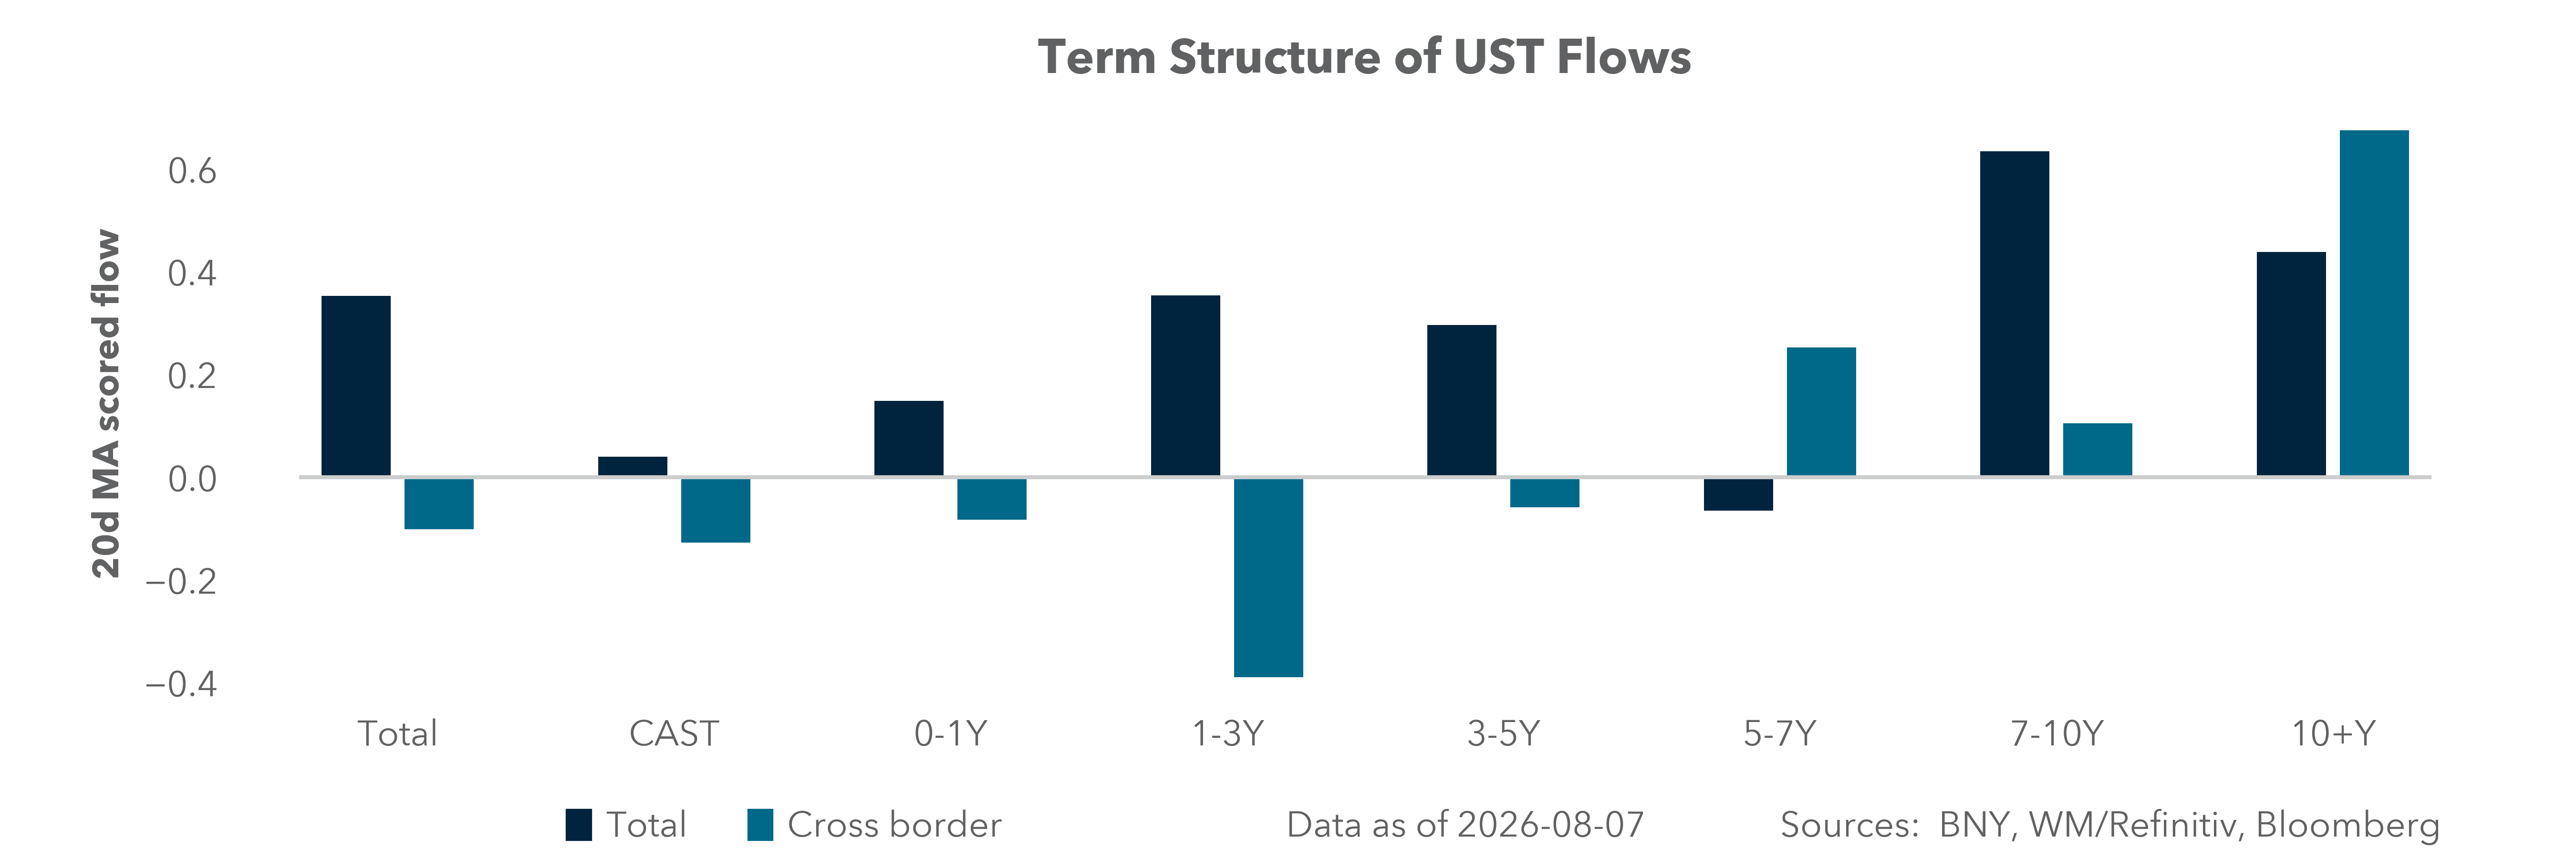
We have long argued that public demand for T-bill issuance is close to inelastic; both money market funds and real money institutional investors tend to buy what’s supplied. However, we have been equally concerned that coupon issuance could have trouble being digested by the market, especially out past the belly of the curve, say seven years or longer. This week sees a $42bn auction of 10y notes on Wednesday and another $30bn in 30y bonds on Thursday. We’ll be watching for signs of indigestion.
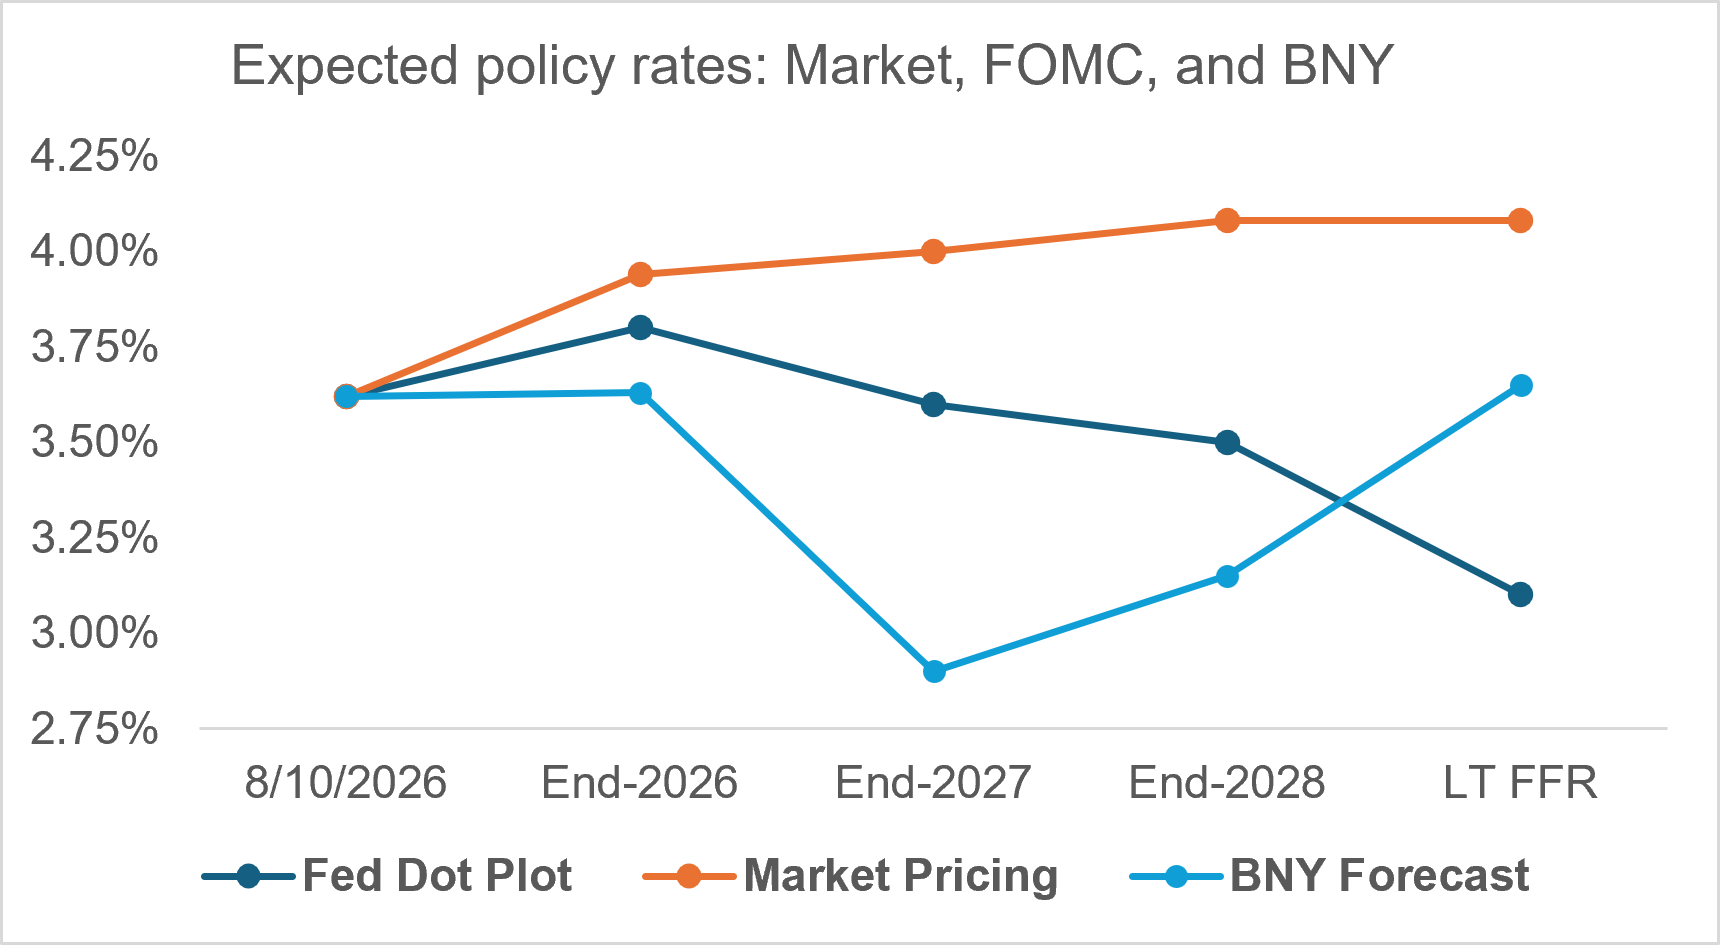
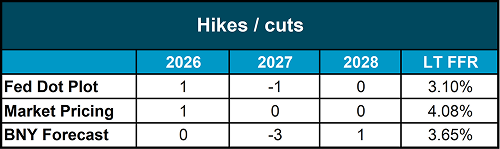
We maintain that there will be no rate hikes from the Fed this year, even though we acknowledge that the risk is to the upside. Last week’s poor jobs report contributed to a slightly more dovish expectation for the funds rate. chance The probability of a September hike has fallen from more than 70% at the end of July to around 50-50 as of this writing. Further out the curve, the market has also taken out some tightening – from more than two hikes by this time next year to something below that now, closer to 1.8 by next July. However, the jobs report wasn’t sufficient by itself to fully squelch the rate tightening expectations; 31bp are priced in for the December meeting.
Inflation is clearly the more important variable for the Fed to consider in its rate deliberations, and we’ll get more news on that this week with CPI and PPI to come out on Wednesday and Thursday respectively. Our view is that despite the “noise” in the CPI’s “supercore” sub aggregate due to the Iran conflict, inflation should continue to move slowly in the right direction. Looking at that “supercore” measure, its yearly rate of change is still running nearly a full percentage point above pre-COVID levels. Much of that is due to higher medical care and education costs – not necessarily something that monetary policy can actually impact, as well as higher airfare prices thanks to the energy shock. Should we see some disinflation later this week, we would expect the curve to reprice more dovishly.