Productivity, rates, hedge funds and repo markets

iFlow > Short Thoughts

Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.

Subscribe to Our Publications

In order to start receiving iFlow, please fill out the form below.

Subscribe
arrow_forward
BNY iFlow Short Thoughts,BNY iFlow Short Thoughts

Key Highlights

  • Warsh’s argument that higher productivity leads to lower inflation has some pushback.
  • Growing hedge fund repo borrowing could drive a wedge between secured and unsecured markets.
  • On the cusp of a heavy data week, we maintain our call for no rate changes this year.

Productivity and interest rates

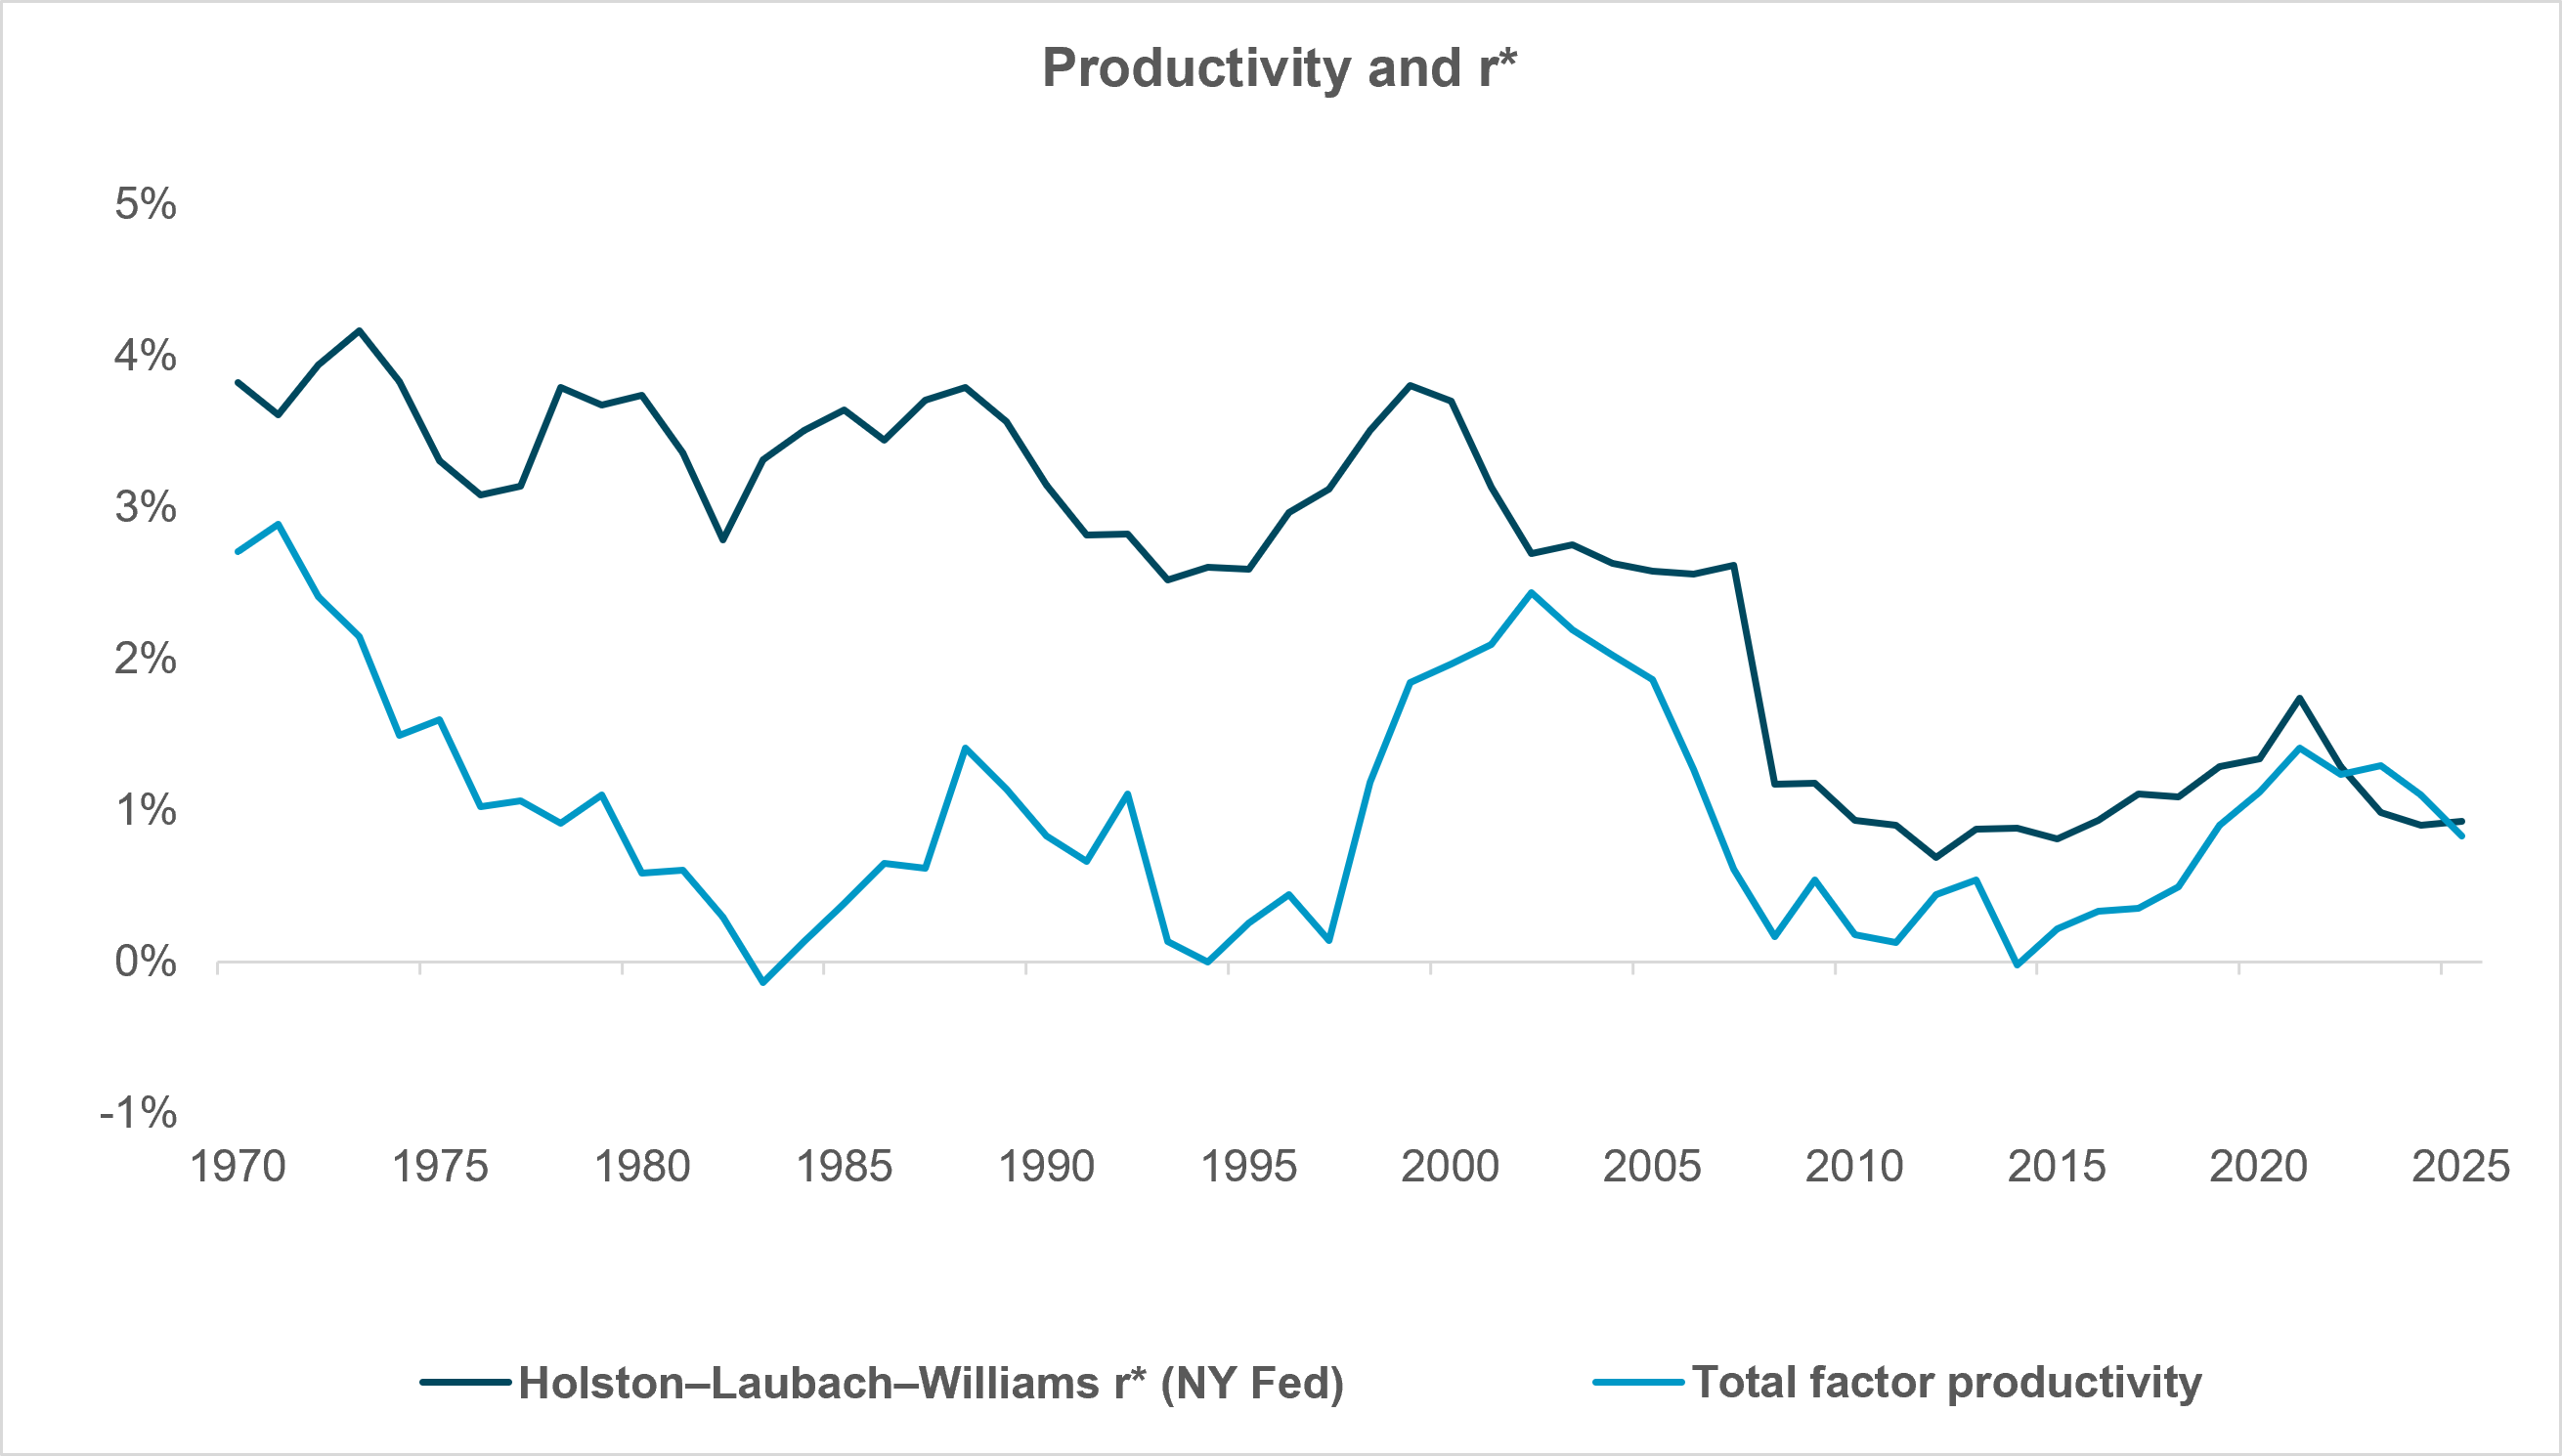
EXHIBIT #1:  PRODUCTIVITY AND THE NATURAL RATE OF INTEREST MOVE TOGETHER OVER TIME

Source: BNY Markets, Federal Reserve Bank of New York, Federal Reserve Bank of San Francisco

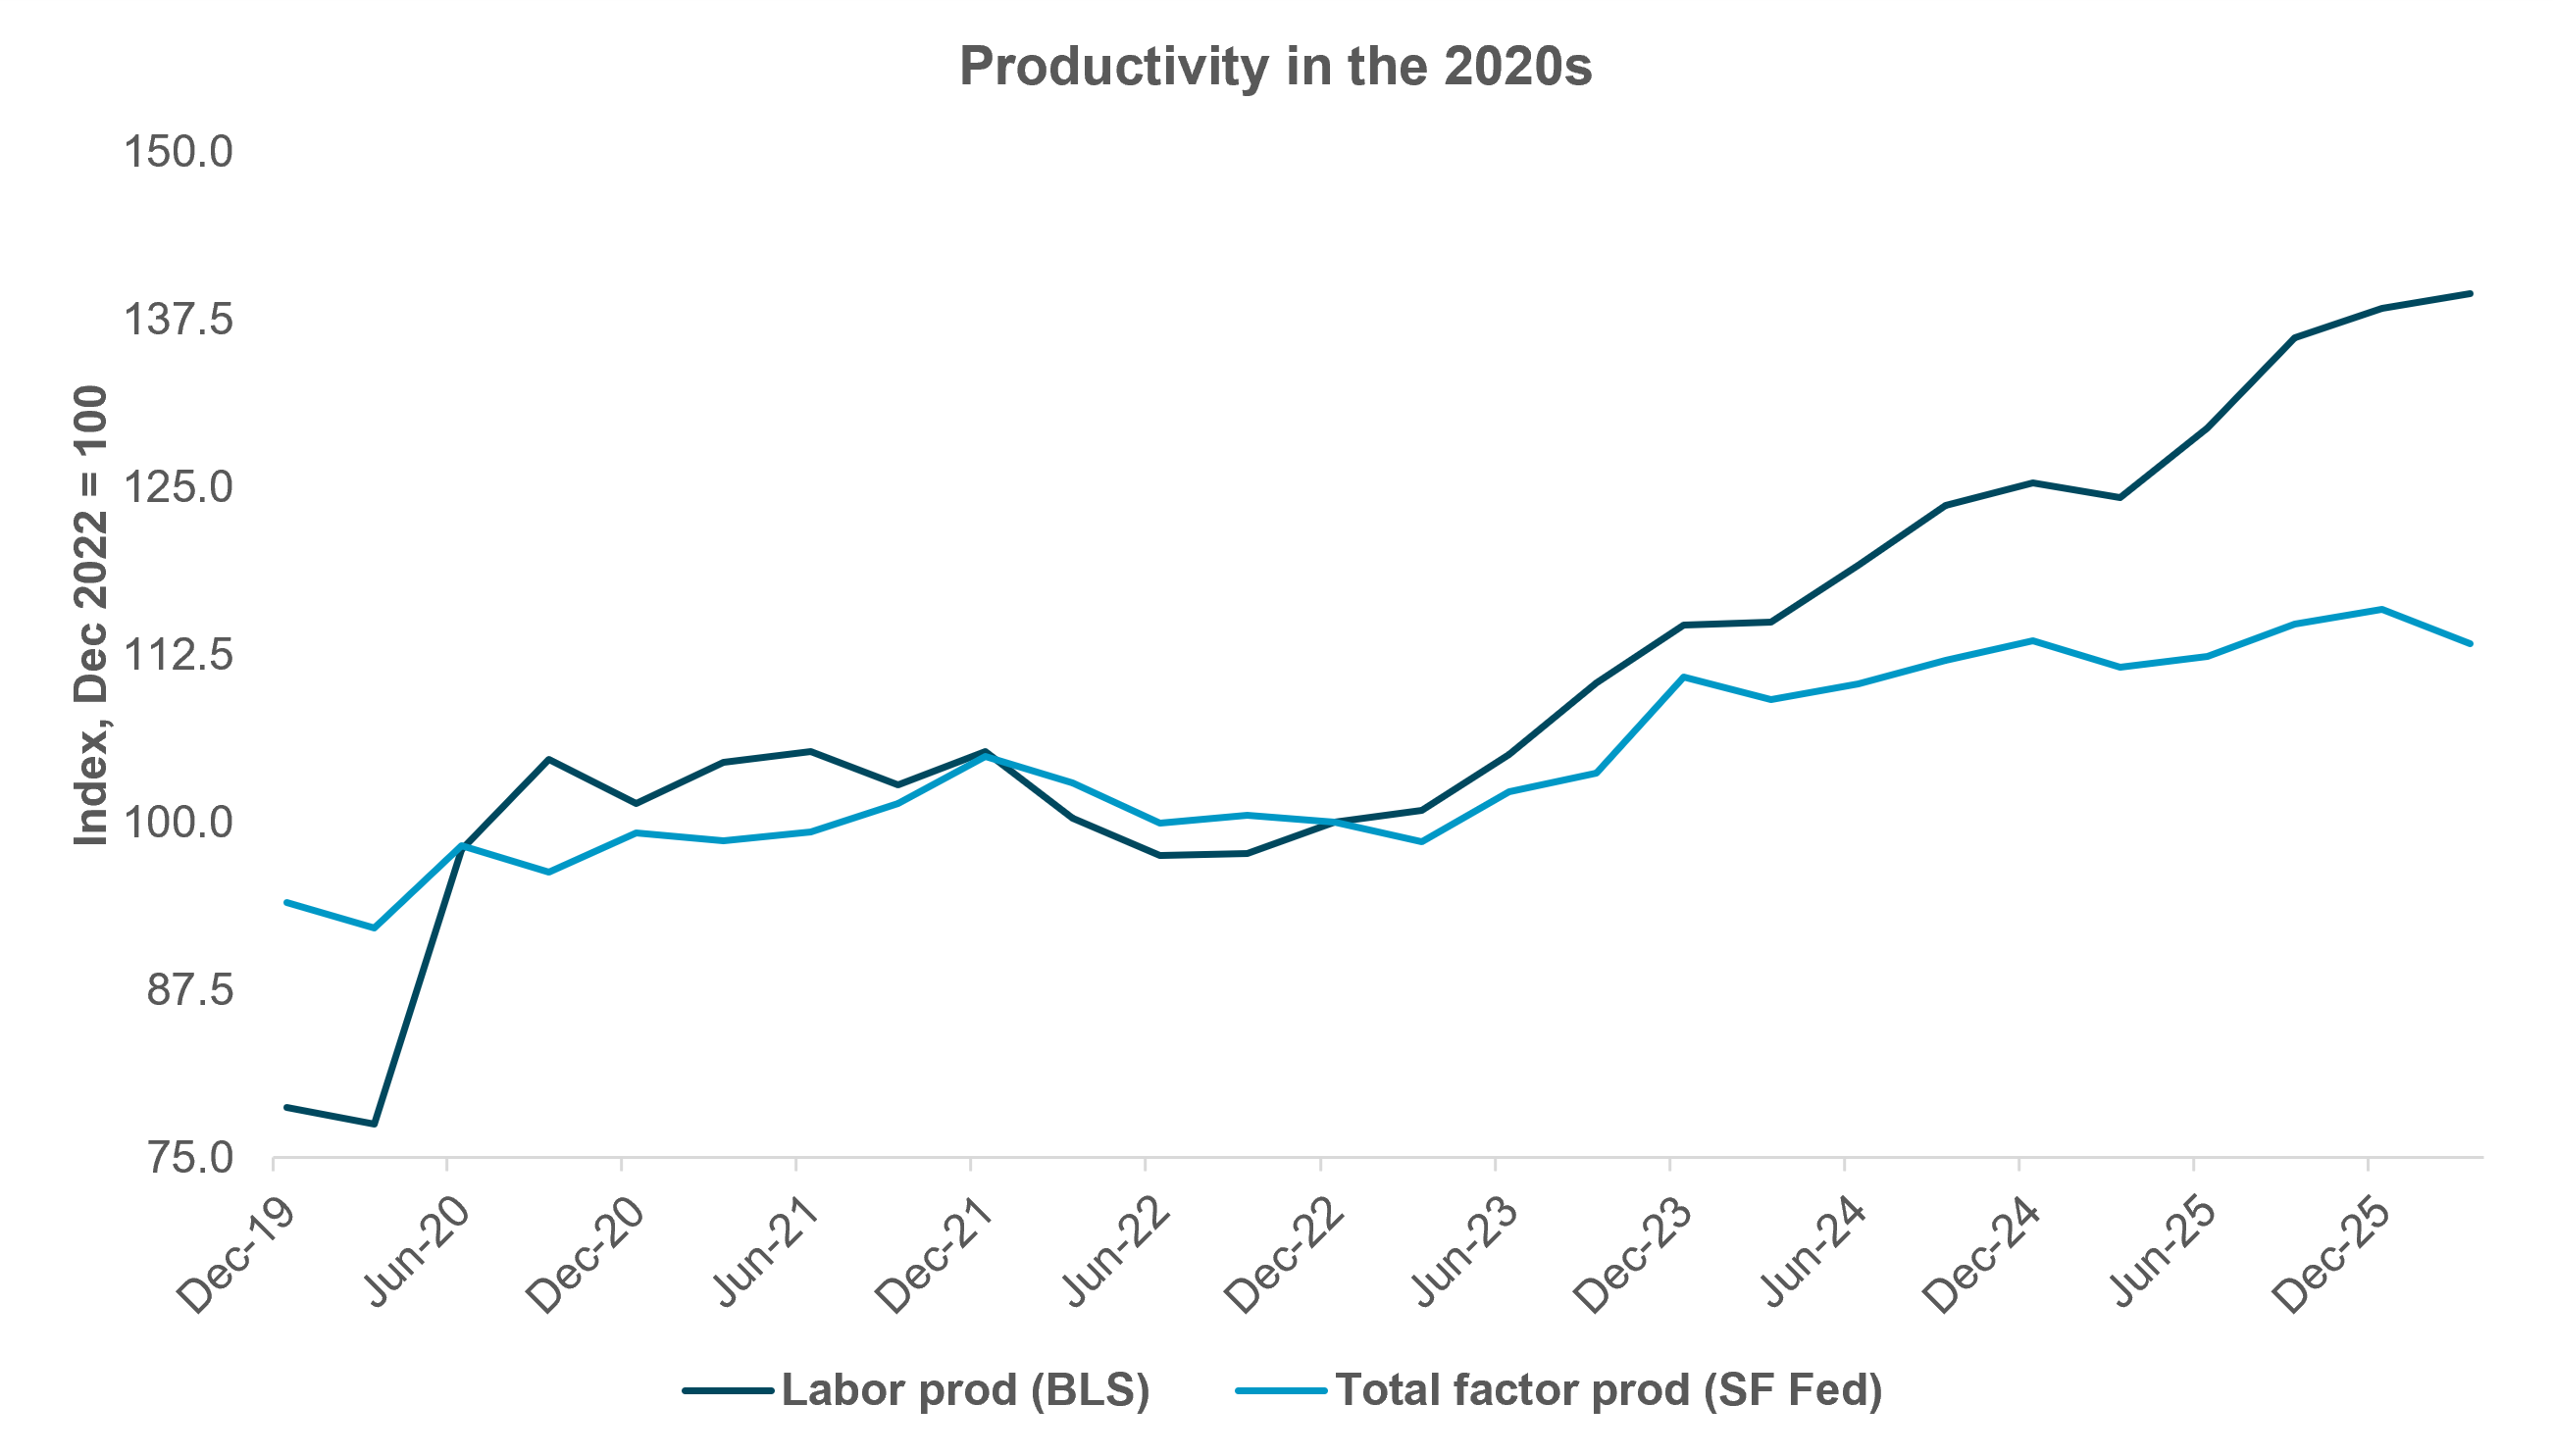
EXHIBIT #2:  ARE WE IN A PRODUCTIVITY BOOM NOW? 

Source: BNY Markets, Federal Reserve Bank of San Francisco, Bureau of Labor Statistics

Although the short- to medium-term monetary policy outlook is still murky due to the uncertainty stemming from the Middle East conflict, new Fed Chair Kevin Warsh has been advocating that the ensuing productivity boom will allow the economy to grow more rapidly without price pressures, implying structurally lower policy rates. The intuition is appealing, as it suggests that a sustained period of higher productivity can spearhead longer-term disinflation if the economy can produce more of the same amount – or even fewer – inputs, leading to increased output at lower prices.

The story may not be as simple as it appears. Some recent commentary from FOMC members argues that it’s not necessarily axiomatic that productivity boom lowers inflation, hence lowers equilibrium interest rates; the relationship is more ambiguous. For example, if the economy were to find itself on the cusp of a productivity boom, firms and households – anticipating higher gains from productivity growth – could be encouraged to spend more on capital investment and consumption, respectively. Higher demand for investment capital could drive up borrowing costs as the market’s demand for financing increases, pushing risk-free rates higher. Anticipating higher wages from higher returns to productivity could lead to increased consumption at present, leading to demand-driven inflation, requiring higher policy rates.

Exhibit 1 shows the Federal Reserve Bank of New York’s widely accepted estimate of r*, the “natural” or neutral rate of interest over time, alongside the Federal Reserve of San Francisco’s quarterly measure of total factor productivity. Note the late 1990s, when productivity boomed thanks to the internet and broader telecommunications expansion. The New York Fed’s estimate of r* also increased. During this period, then-Fed Chairman Greenspan held off from raising rates, but didn’t cut them after 1995. Indeed, we actually witnessed rate hikes in mid-1999.

Measuring productivity is another challenge for monetary policy. Exhibit 2 shows two different productivity measures, reflecting two different concepts. The blue line represents nonfarm labor productivity, essentially the ratio of output growth divided by growth in labor inputs (defined as hours worked). Setting the December 2022 level to 100, we calculate the cumulative growth in labor productivity since just before the pandemic – it displays impressive growth over the last six years. However, the orange line, which measures total factor productivity (TFP), reveals much more modest growth over the same period. TFP measures how much output grows given changes in the total productive capacity of the economy, not just labor inputs. This includes capital, infrastructure and other intangibles that can create broad productivity gains.

One reason labor productivity has grown so much faster than TFP is the post-Covid dynamics of the labor force. As the economy reopened in 2021, and more so in 2022, the economy was characterized by rapid employment growth as firms sought to add labor to meet the increase in demand. This period of rapidly rising output coincided with rapid increases in labor inputs, and the labor productivity numbers were actually quite mediocre – the numerator of the productivity ratio (GDP growth) didn’t grow much relative to the denominator (hours worked). After 2023, labor demand stabilized, and labor supply also flattened out. As GDP grew, labor inputs didn’t, so the labor productivity ratio leaped ahead. By contrast, TFP hasn’t moved much faster than its trend implies. This contrasts with the 1990s, when both series moved higher, almost in lockstep.

We’re not so naïve as to argue that there is no productivity boom to come. It’s quite likely to show up in the data before long. We’re saying it may be too early to conclude it’s already upon us; all things being equal, rates can fall. We may be mismeasuring productivity currently, and the anticipation of the coming boom could be altering investment and spending behavior, leading to higher pressure on both rates and inflation.

Growing hedge fund footprint in repo

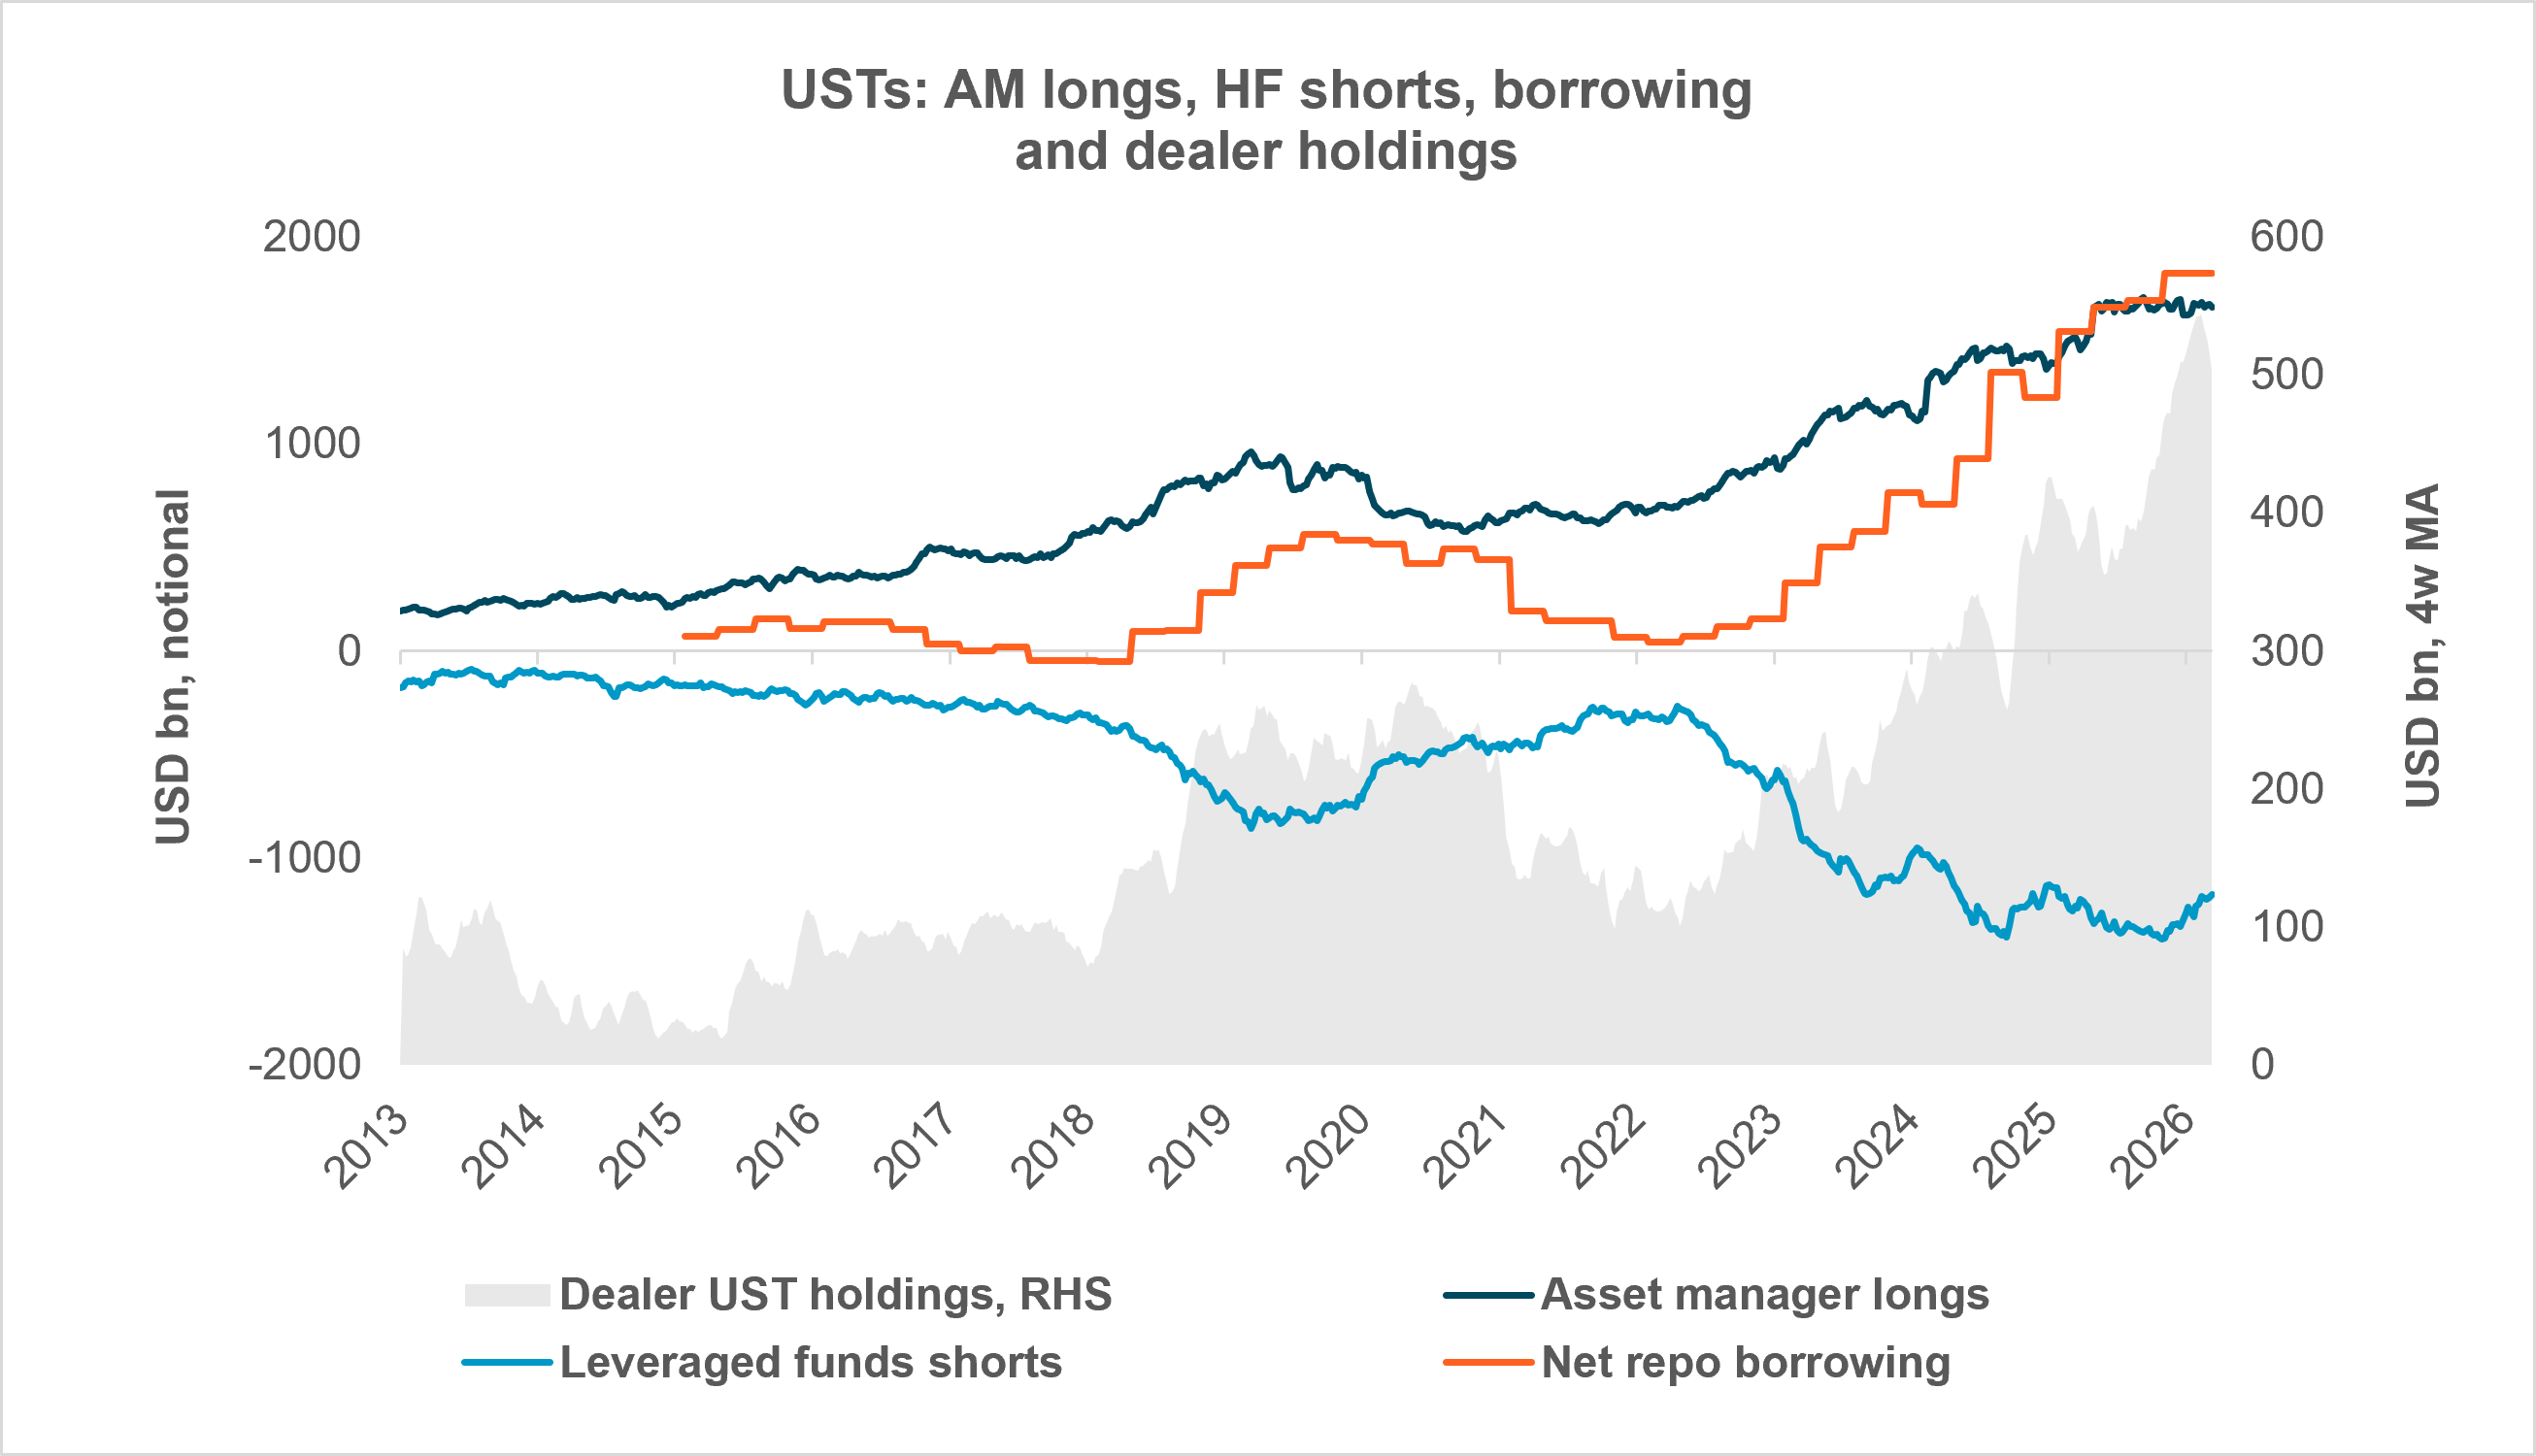
EXHIBIT #3:  BIGGER HEDGE FUND FOOTPRINT IN REPO AS BASIS TRADE GROWS

Source: BNY Markets, Office of Financial Research, CFTC, Federal Reserve Bank of New York

Last week, the Dallas Fed published a research note examining the increase in hedge fund repo borrowing alongside the growing importance of the cash-futures basis and swap spread trades. In the piece, the authors argue that the “increased repo borrowing has been associated with a sizable widening in the spread between secured and unsecured rates.”

Hedge funds leverage their short positions by borrowing in repo, placing funding demand on dealers who must source that funding. This has required dealers to increase UST holdings – raising dealer balance sheet costs, and (all other things equal) driving up secured funding rates relative to administered rates. With this increase in collateralized market usage, funding pressure doesn’t pass through to unsecured rates, driving a wedge between them. Furthermore, it wrests an element of control of the effective federal funds rate (EFFR) from the central bank.

Exhibit 3 shows the steady and continued growth in the hedge fund basis trade since 2013 (light blue line) by plotting notional short exposure of leveraged funds in USTs (data from the Commodity Futures Trading Commission – CFTC). Asset managers’ (i.e., long only funds) positions, shown in darker blue, have grown in an almost mirror-like way over the past 13 years. Also shown are data on hedge fund borrowing in repo (orange line), which has increased from negligible levels before Covid to over $1.8tn through Q1 2024, more than their notional level in UST shorts (around $1.2tn). Note the increase in dealers’ holding of USTs over the same period, describing the process through which hedge fund borrowing requires larger inventories of Treasury securities on bank balance sheets.

Back in September, Lorie Logan, the President of the Dallas Fed, suggested the Fed consider moving its operating target away from an unsecured interbank lending rate like EFFR and toward a secured, market-determined funding rate like Triparty General Collateral Repo (TGCR). The arguments in the Dallas Fed’s research note last week reinforce hers. If the structure of the repo market is such that unsecured rates (like EFFR) don’t reflect actual demand for cash and supply of collateral, but the secured rates like TGCR do, then there is an argument that the EFFR is not the appropriate target for policy.

Other effects could emerge from this equilibrium. One effect is that during times of funding market stress, financing these leveraged positions becomes more expensive and could lead to some slowing – if not outright reversal – of the basis and swap spread trades. If this were to happen suddenly, Treasury markets could come in for a period of stress should hedge funds have to close out their positions and sell their long holdings of cash Treasurys. On the other hand, reducing leverage in the Treasury market may not be undesirable – and as the balance sheet shrinks (one of Warsh’s policy priorities), higher funding rates could provide a natural brake to the continued buildup of these leveraged positions.

Furthermore, there is also a potentially self-reinforcing mechanism at work here. A smaller central bank balance sheet requires either more frequent open market operations or the acceptance of elevated money market volatility. More of the latter could cause hedge funds to stop growing – or even reduce – their exposure to these leveraged trades, requiring a lower presence in repo and leading to broker-dealers holding fewer Treasurys. This could free up reserve demand, helping move the demand curve left and allowing the balance sheet to shrink further.

Rates outlook

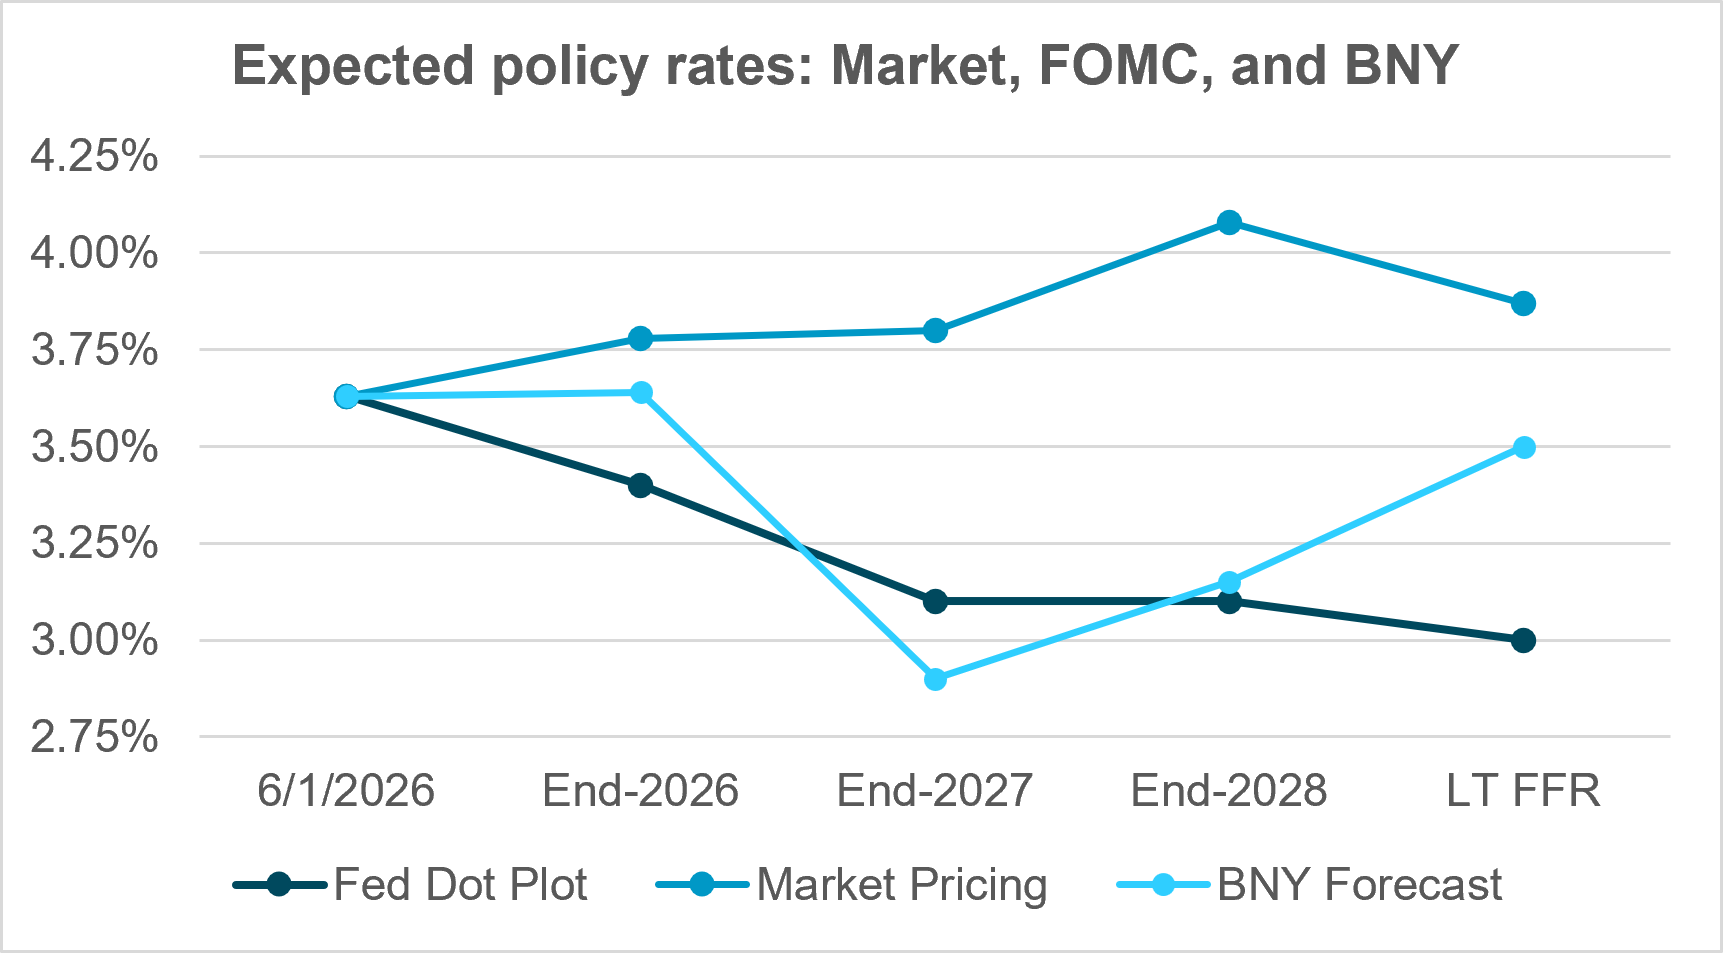
Last week, nominal U.S. Treasurys were generally lower across the curve and market-implied near-term rate expectations shed as many as 15bp of anticipated hikes by March 2027 on optimism around a possible 60-day U.S.–Iran ceasefire. The moves were likely welcome news to Warsh in his first full week at the helm, as markets took some of the most hawkish rate hike scenarios off the table.

Yet as the new week starts, and amid reports that Iran is halting communications with the U.S., it feels like Groundhog Day, with no end in sight for the conflict. With markets buffeted from Iran headline to Iran headline, this week should offer some tangible evidence of the state of the U.S. economy in May. Friday’s NFP print will be the highlight of a data-heavy week for the U.S. that also features JOLTS data today and ISM Services, Durable Goods Orders, and the release of the Fed’s Beige Book midweek. We’ve already seen evidence of ongoing strength in the manufacturing sector with Manufacturing PMI printing at 55.1, the highest level since 2022, and ISM Manufacturing coming in at 54, beating consensus expectations. Strong data the rest of the week would show a resilient economy for May even as traffic through the Strait of Hormuz was halted.

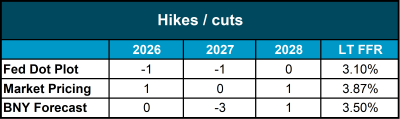
Markets are currently pricing in around 16bp of hikes by year end, and strong data this week would likely firm up rate hike expectations. The Fed could still hike given ongoing geopolitical uncertainty, though a timely resolution to the conflict – and the reopening of the Strait – could moderate inflation later in the summer or fall. Our view continues to be that the Fed is in a holding pattern and will remain so the rest of the year.

Chart pack

Media Contact Image
John Velis
Head of Americas Strategy
john.velis@bny.com
Media Contact Image
David Tam
U.S. Rates Strategist
david.tam@bny.com

Ready to grow your business? Speak to our team.