July FOMC: Family fight leaves markets guessing

iFlow > Short Thoughts

Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.

Subscribe to Our Publications

In order to start receiving iFlow, please fill out the form below.

Subscribe
arrow_forward
BNY iFlow Short Thoughts,BNY iFlow Short Thoughts

Key Highlights

  • FOMC decision raises uncertainty on the rate path
  • Three dissents indicate sharpening differences on the FOMC
  • Quarterly funding announcement puts coupons vs. bills in focus

Murkiness and ambivalence

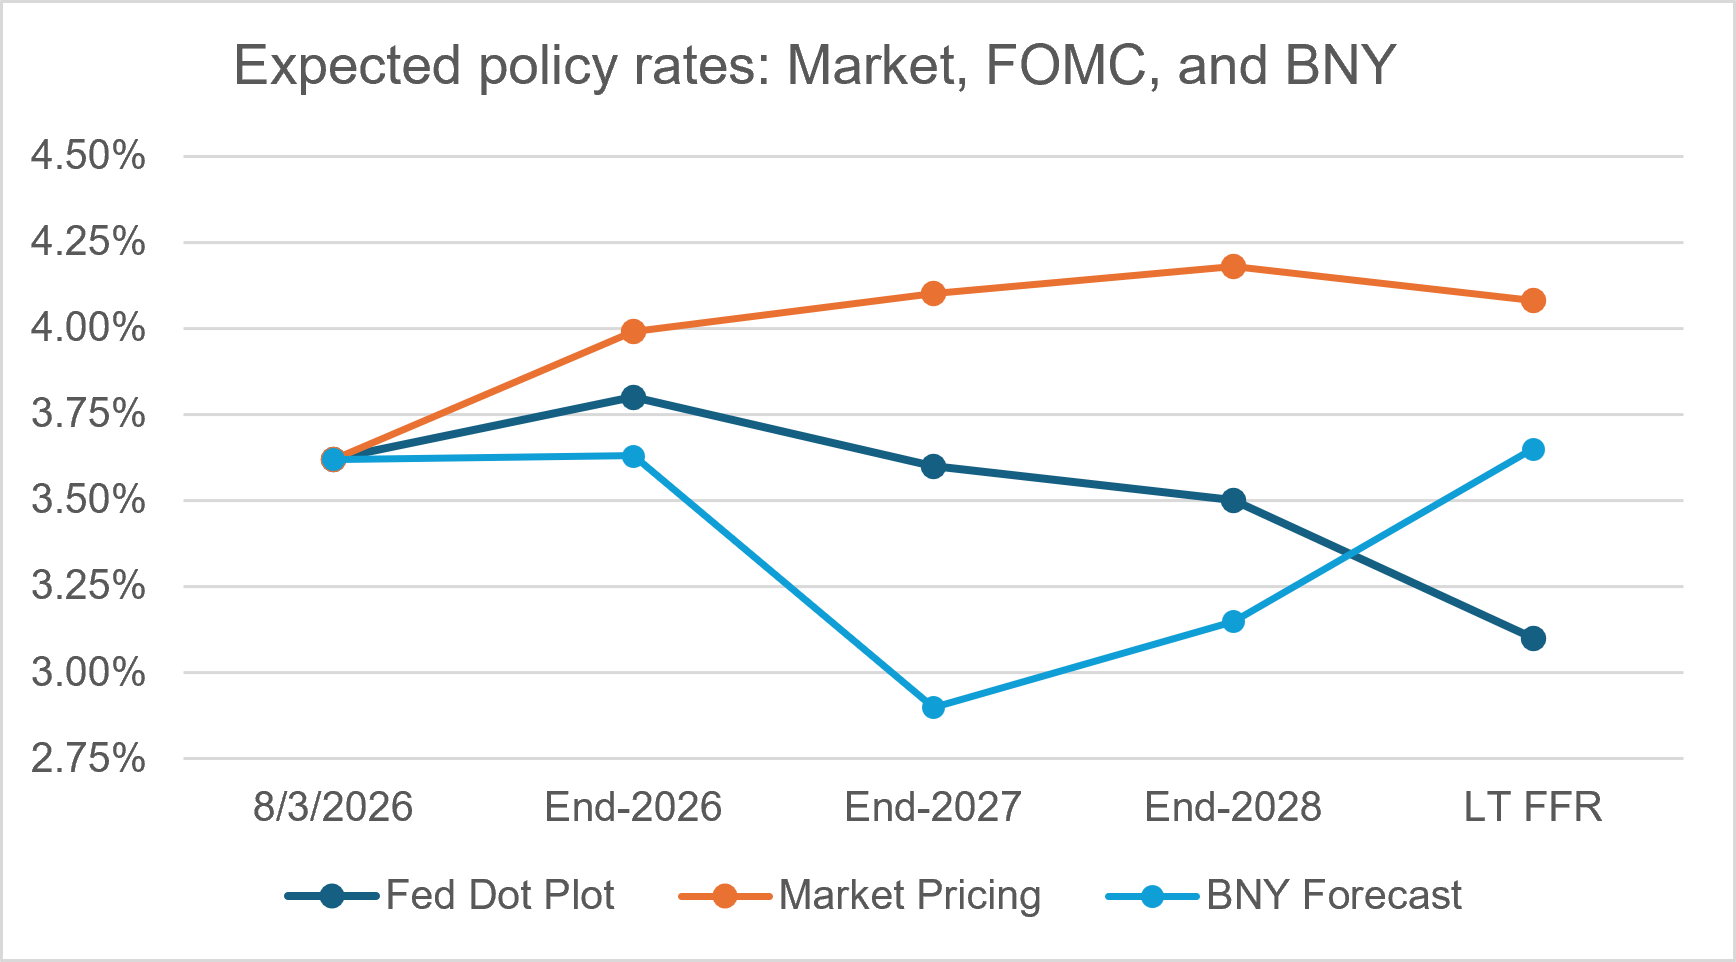
EXHIBIT #1: MARKET NOW PRICES SLOWER, LONGER HIKING CYCLE

Source: BNY Markets, Bloomberg 

The FOMC’s decision last Wednesday to leave the policy rate unchanged was not much of a surprise, but the market’s reaction since then suggests the Fed might be running into a credibility risk. The 2y yields – which are a good proxy for the market’s rate outlook – fell, 10y yields rose, and the yield curve re-steepened. We interpret the rate moves to imply a lower shorter-term path for rates (recall that our own outlook is for no change in rates this year), but a higher longer-term one. If the Fed stays on the sidelines much longer, it may need to raise rates further later, so the thinking goes. Inflation expectations, as measured by short-term breakevens, are not materially higher at long maturities; the increase in 10y yields is all due to term premium and real rates.

Exhibit 1 shows the subtle change in market expectations on a meeting-by-meeting basis before and after the July FOMC. The current expected rate path is lower than it was before the meeting, but rates are seen as continuing to rise – albeit slowly – into 2027, while pre-FOMC, the outlook for the middle of next year featured a downtrend in policy going into H2 2027.

Fed Chair Kevin Warsh, as expected, gave no forward guidance, nor much of an assessment of the inflation and growth outlook going forward. He deferred many of the monetary policy questions to the Fed task forces – see our perspectives on three of the five here, here and here. Lorie Logan of the Dallas Fed, Beth Hammack of Cleveland, and Neel Kashkari of Minneapolis dissented, which wasn’t unexpected. Nevertheless, the critical mass of the Committee is moving more hawkish. 

While Warsh repeatedly emphasized the Fed’s commitment to price stability and the 2% target, little was offered to back that commitment. So, we have the prospect of a split within the Committee, without knowing the Chair’s own preferences, except those that were revealed Wednesday: no hike now and no guidance for the future. On the one hand, the inflation target is sacrosanct and inflation is currently too high; on the other, we don’t know what the Fed will do to get to the target or under which circumstances. This leads to rising uncertainty premia in markets and even perhaps the hint of a looming credibility issue.

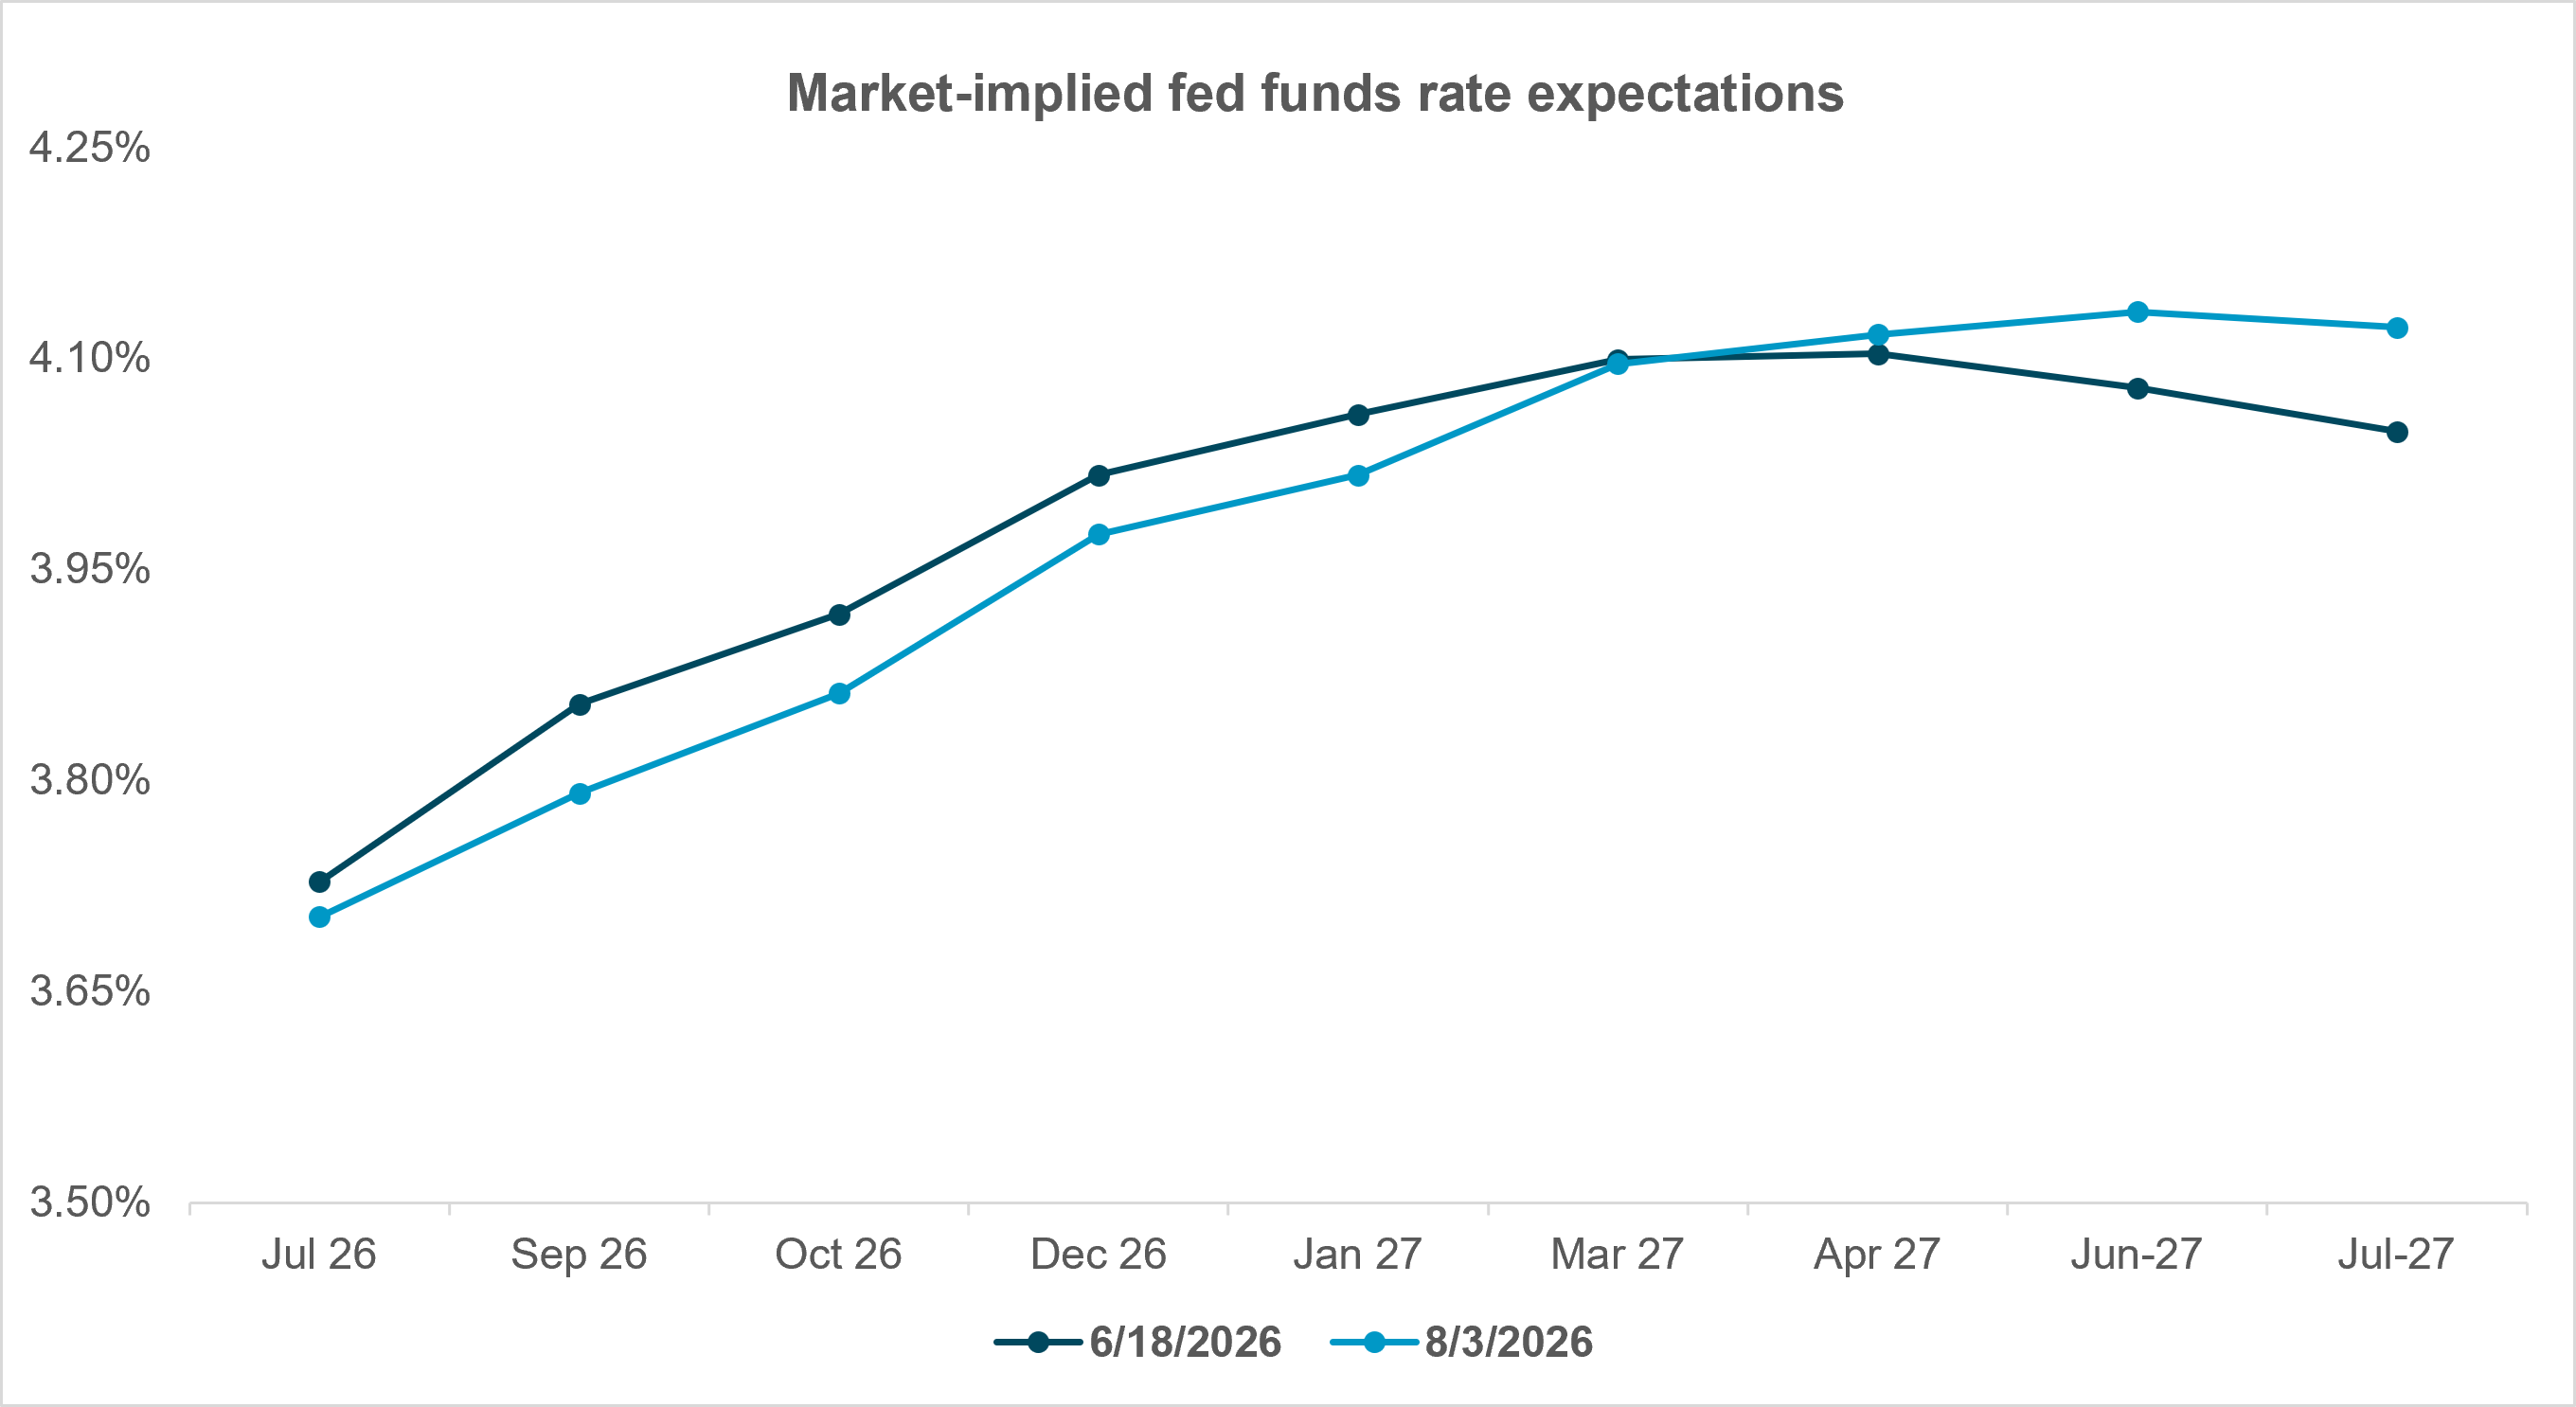
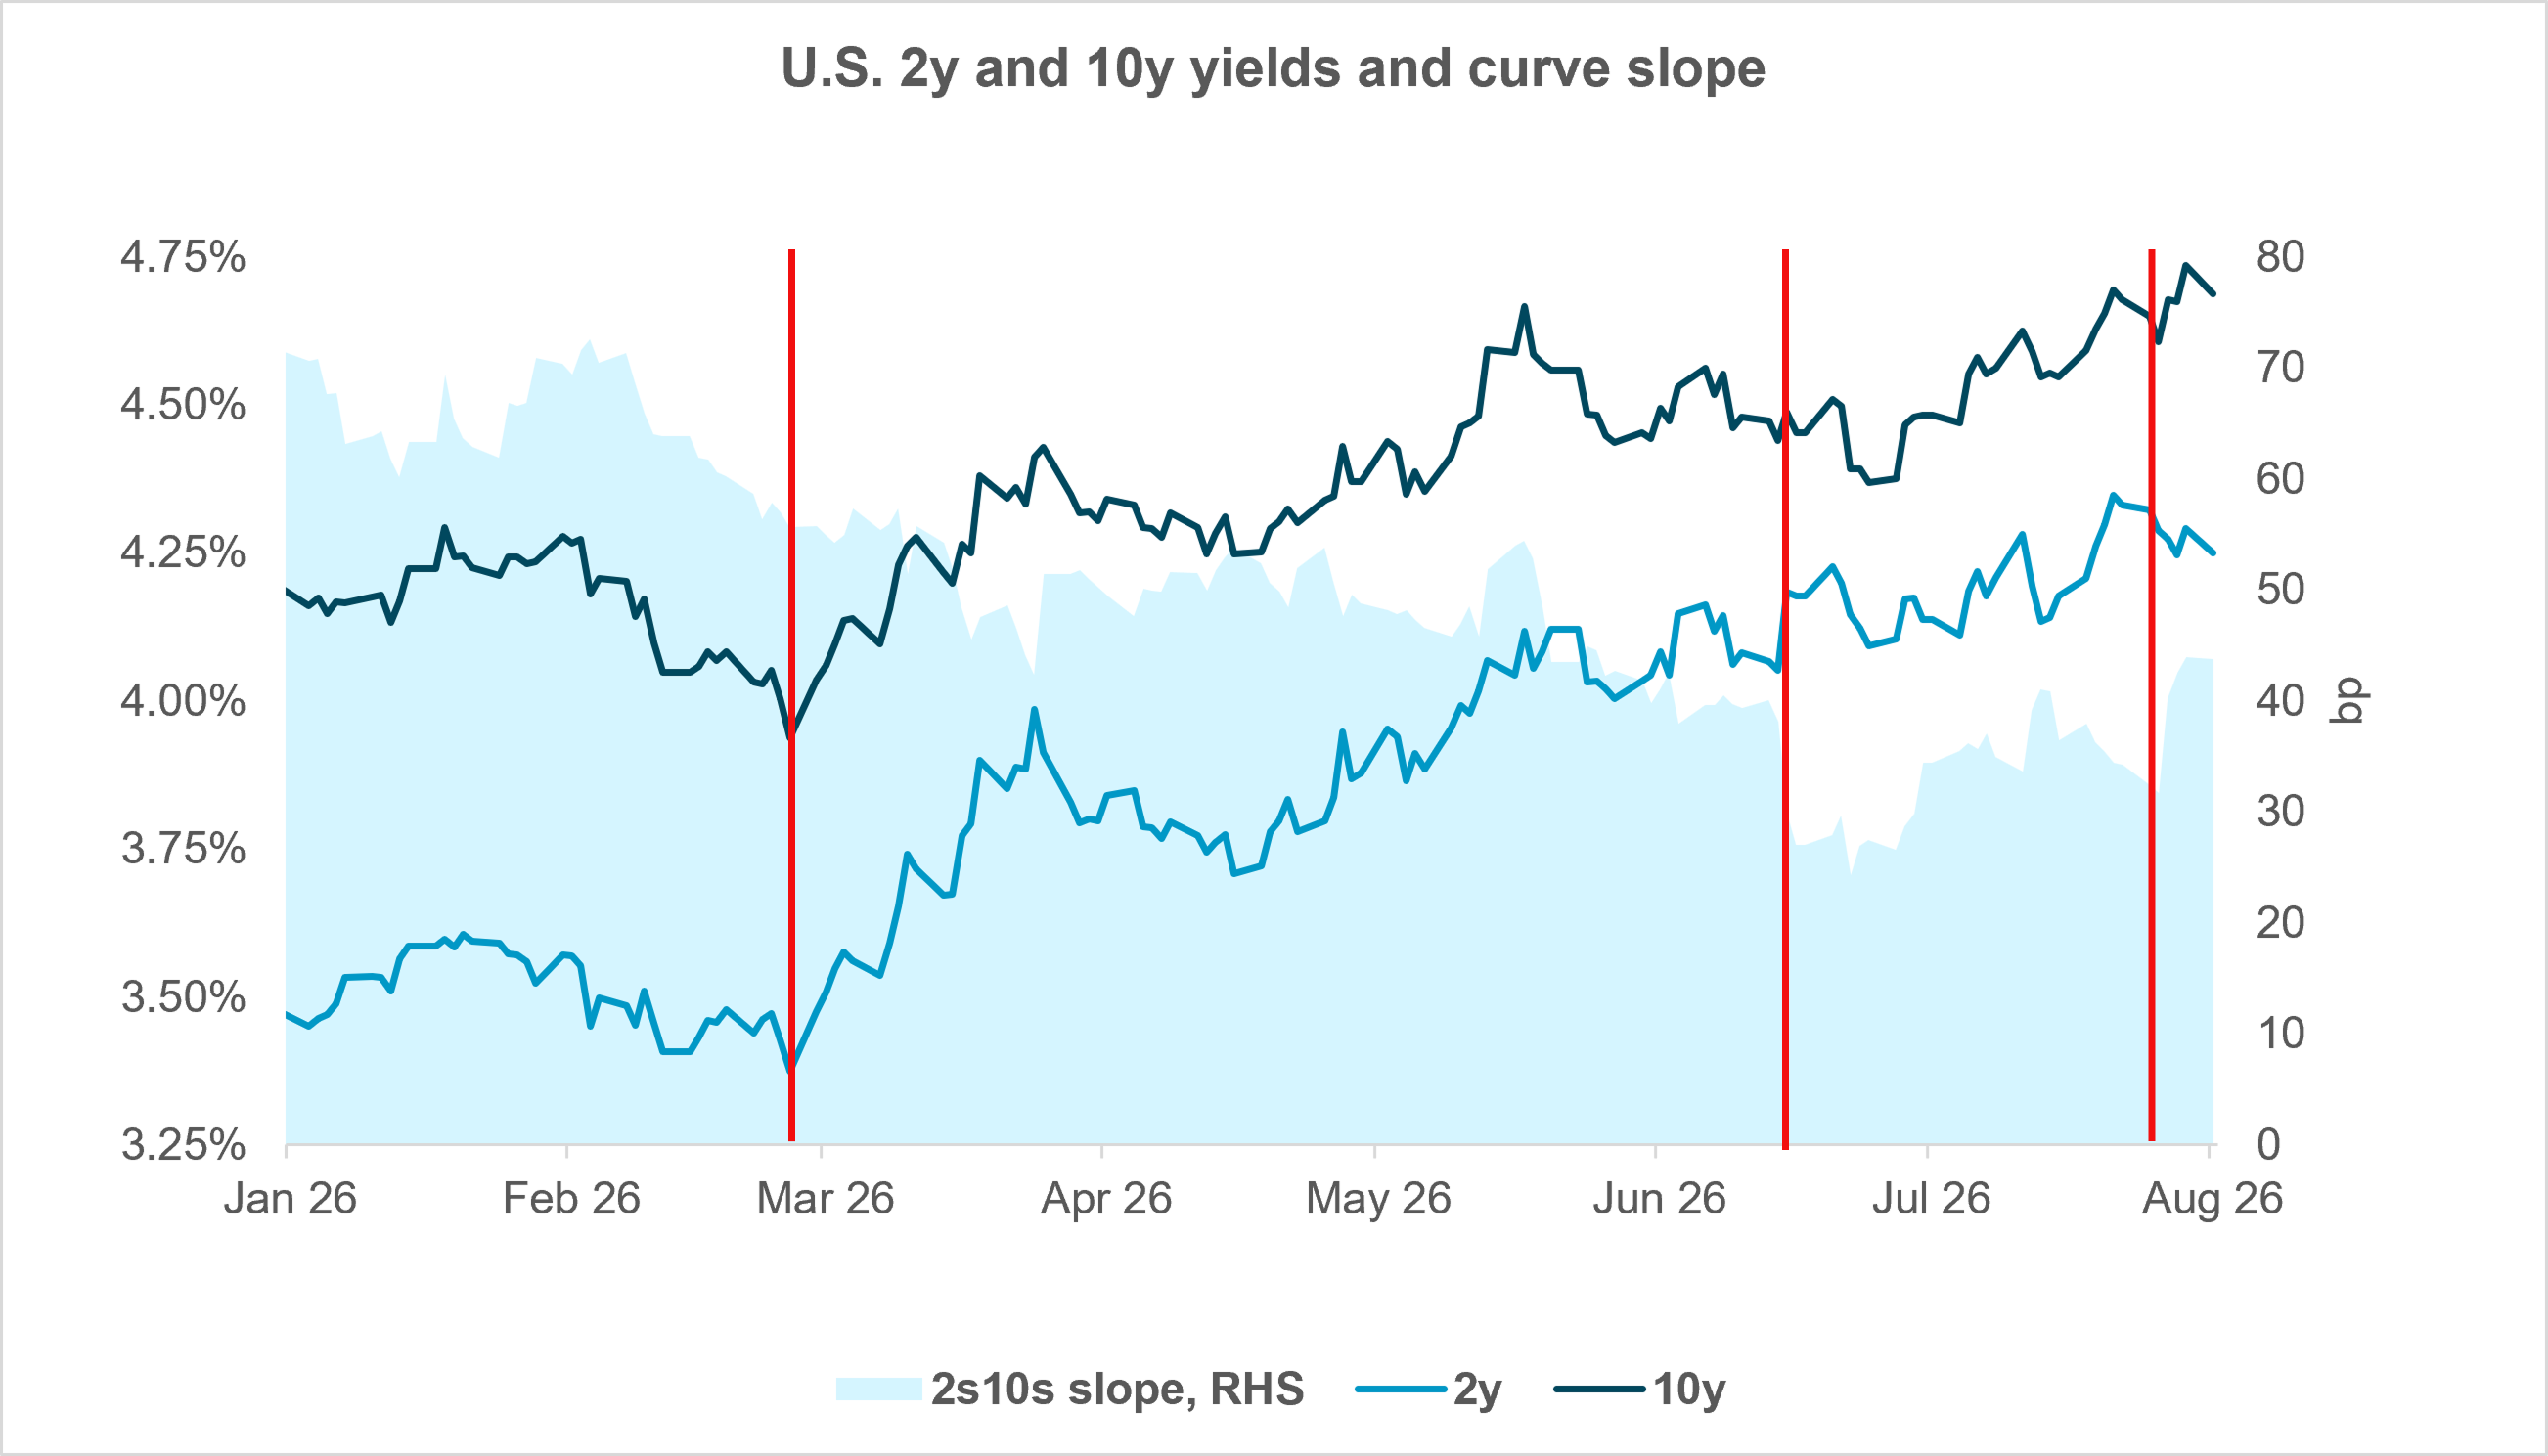
EXHIBIT #2: YIELD CURVE TELLS TWO STORIES ACROSS JUNE AND JULY FOMCS

Source: BNY Markets, Bloomberg

Take Exhibit 2, for example, where we plot the 2y and 10y yields along with the 2s10s yield slope. The first vertical line indicates the start of the Iran conflict, after which rates across the curve jumped, and there was a degree of bull flattening as the 2y yield rose proportionally more than the 10y. The second vertical line marks Warsh’s first FOMC in June, which was regarded as hawkish, given his frequent appeal to price stability. The 2y rose, the 10y fell, and the curve flattened from both ends to a mere 30bp. This flattening was completely given back after the last FOMC, and the mixed message coming out of the meeting.

Quarterly refunding: More long-end pressure ahead

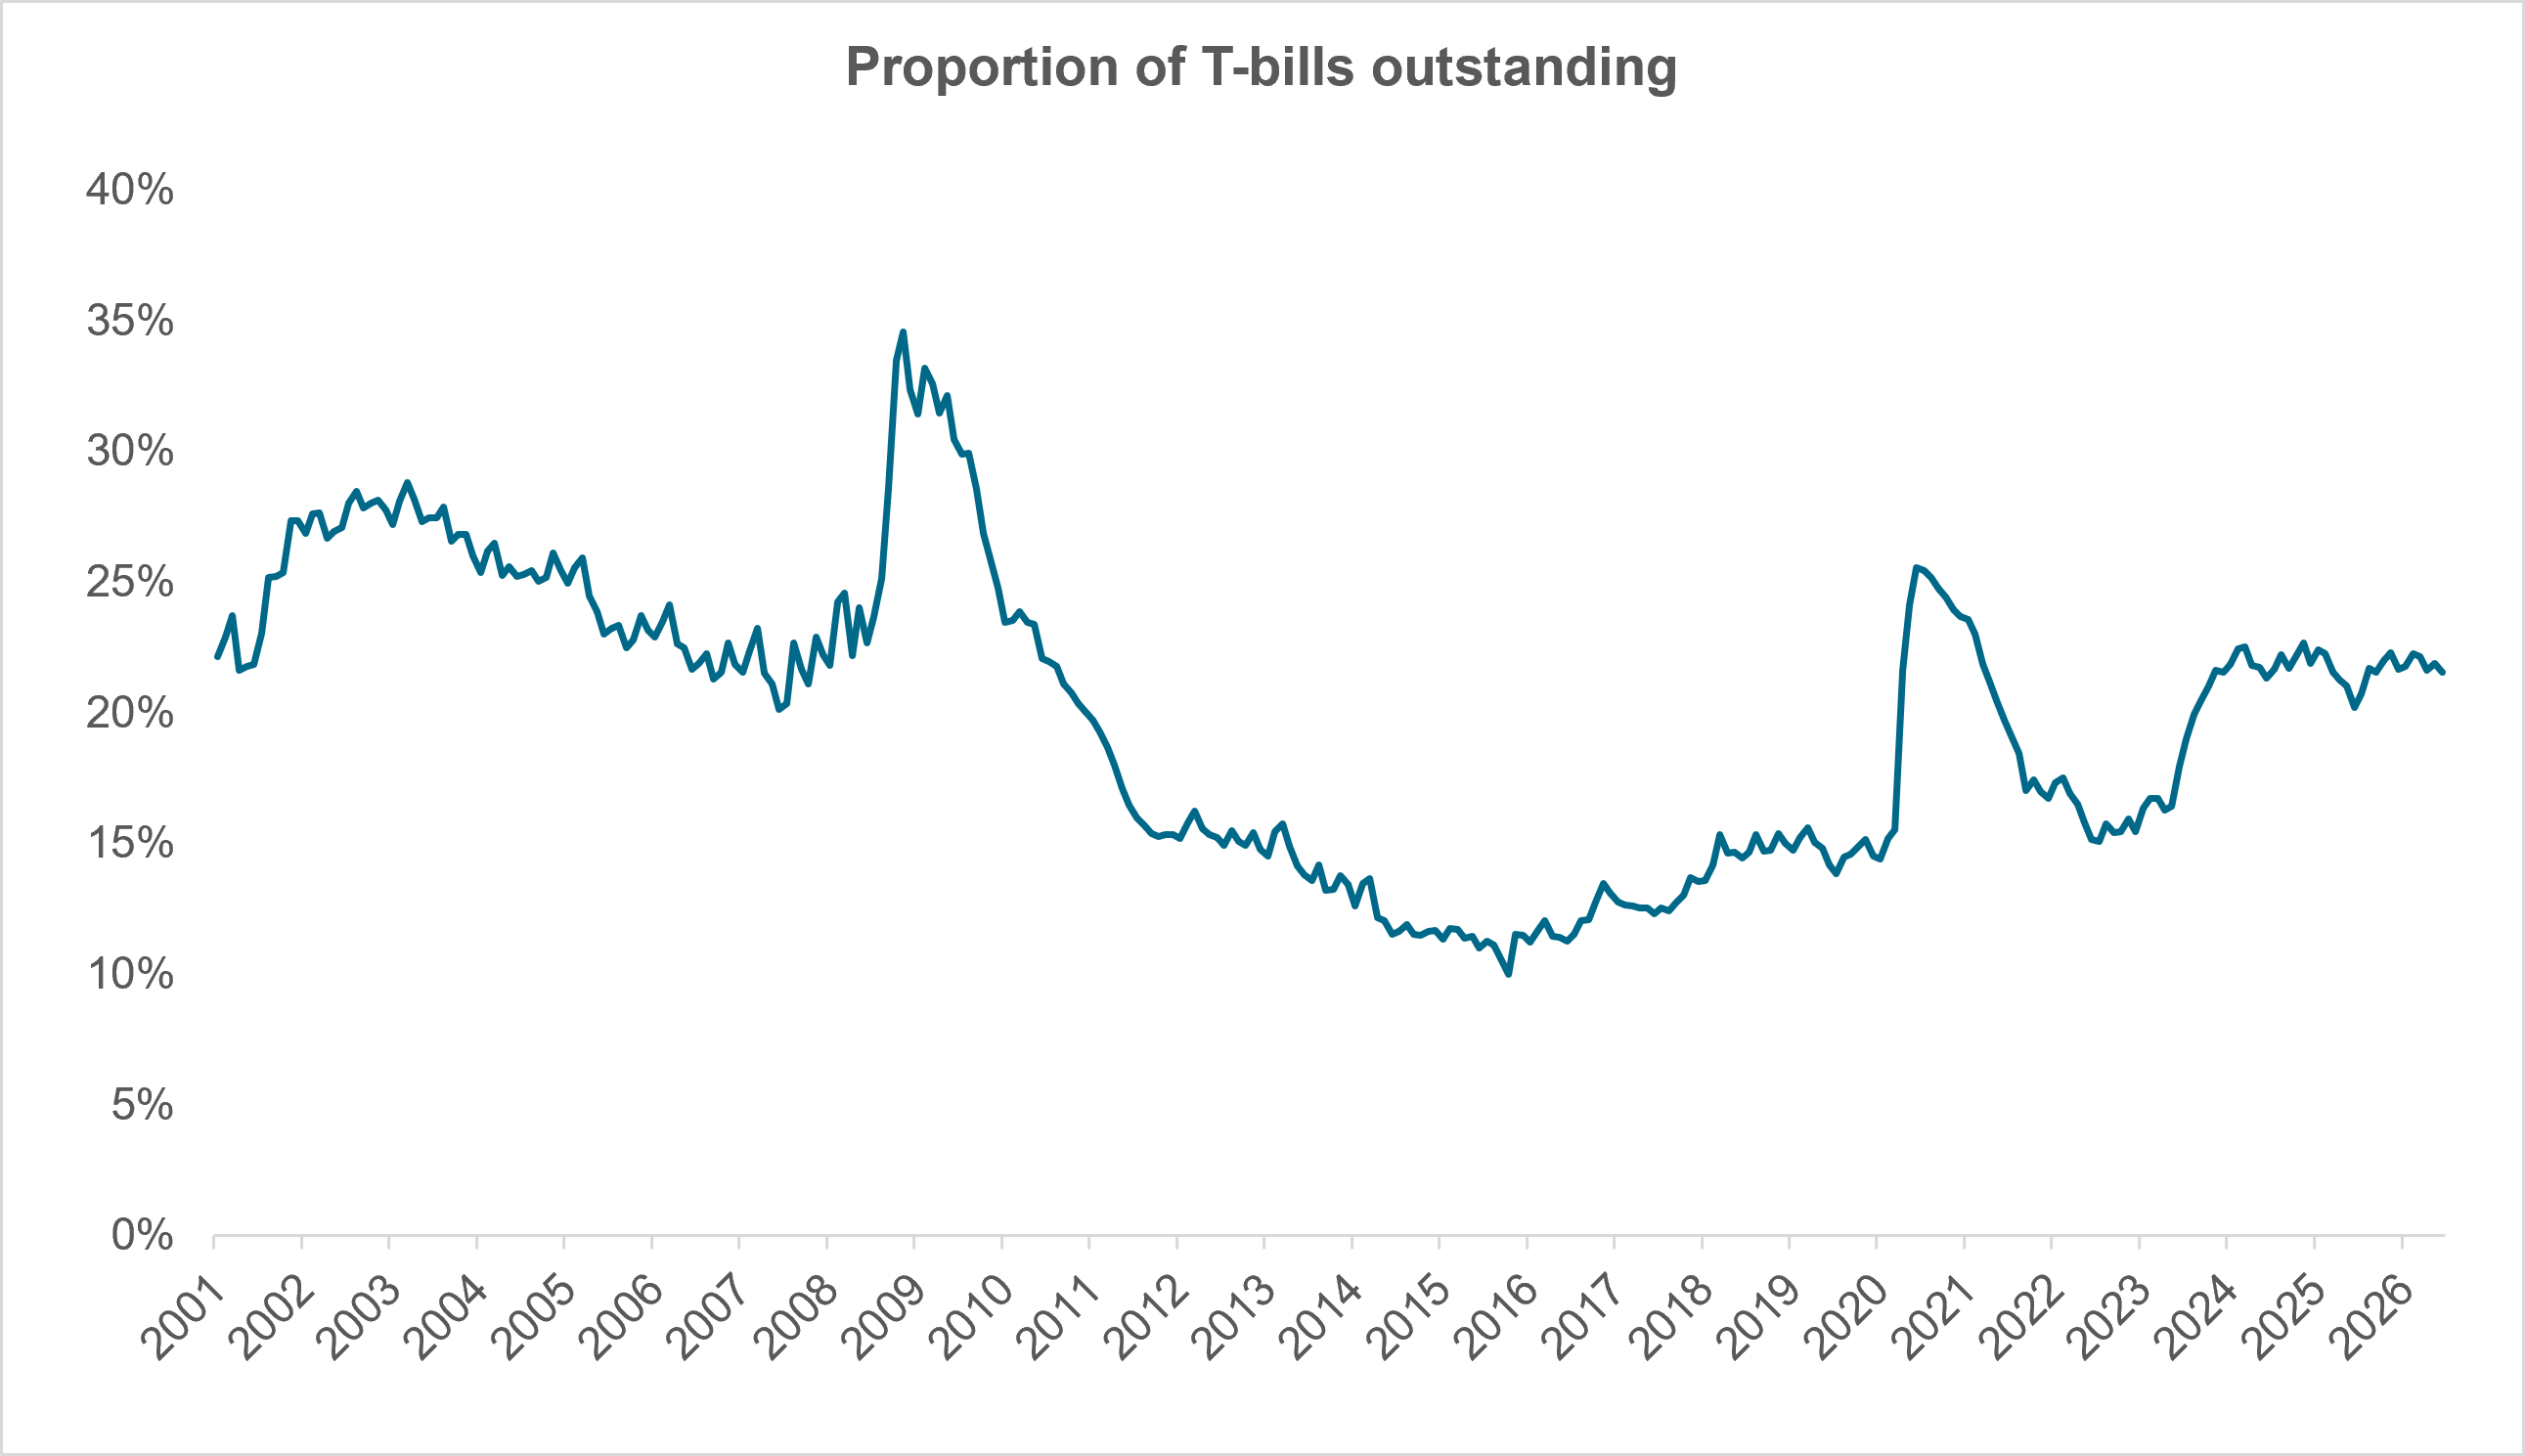
EXHIBIT #3: T-BILLS’ SHARE OF TOTAL DEBT PLATEAUS NEAR 21%

Source: BNY Markets, U.S. Treasury

Moving a few blocks to the east, from the Fed’s Eccles Building to the Treasury Department, we’re watching two releases this week with interest. The borrowing requirement for the current quarter (i.e., through the end of September) was raised by $87bn to $739bn, along with a commitment to keep Treasury General Account (TGA) balances at $950bn. For the following quarter, Treasury has announced a total borrowing estimate of $628bn, assuming a slightly lower end-of-period TGA at the end of December.

On Wednesday, we’ll learn about the Treasury’s expected funding mix in the August–October quarter and possibly some hints for subsequent quarters. Since Secretary Bessent has been at the helm, his Treasury has pinned the bulk of new issuance at the front end of the curve; T-bills outstanding now eclipse 21% of all public debt, a proportion that hasn’t moved much since the end of 2023 (see Exhibit 3). With borrowing requirements expected to increase, the expectation is that Treasury will have to term out the funding mix at some point, leading to higher coupon issuance – leading, in our opinion, to more upward pressure on yields eventually, above and beyond what we’ve seen so far since the beginning of the year.

As we have frequently argued, the rise in yields at the back of the curve – the 30y bond’s current ~5.2% yield is the highest since before the GFC – has little to do with inflation expectations and more to do with the market’s sense of a higher terminal fed funds rate, as well as increasing uncertainty and rising risk perceptions around supply and the fiscal outlook. We don’t argue that all of the rise in the 10y-term premium is due to fiscal concerns. There is a general rise in uncertainty associated with the new Fed and its inflation credibility and upward pressure on yields due to the voracious private sector demand for capital for the AI build. We don’t expect this to relent any time soon, and Wednesday’s announcement of the borrowing policy can add to that.

TGA repo lending still in play

The U.S. Treasury is continuing to explore the idea of deploying Treasury General Account (TGA) cash into the repo market. After first floating the prospect to Treasury Borrowing Advisory Committee last quarter, Treasury again raised the proposal in last month’s quarterly survey and meetings with primary dealers that precede the quarterly refunding announcement.

In May, we argued that operational hurdles would likely outweigh the benefits, although modest gains might be possible. Crucially, repo rates would need to exceed IORB for the exercise to be profitable given the Fed–Treasury consolidated balance sheet – every dollar that Treasury lends into repo would create a dollar in the banking system that would earn IORB, which ultimately would not be remitted to Treasury. Notably, repo rates are more likely to exceed IORB in the scarcer reserve regime we expect Warsh to favor, subject to what the Balance Sheet Policy task force finds.

Such a program could actively help the Fed reduce its balance sheet. The Fed’s QT efforts stalled last year after funding pressures began to pick up. One could imagine an alternative scenario where similar money market volatility was dampened by TGA cash strategically entering the market.

TGA repo lending makes a lot of sense to those who anticipate the Fed shrinking its balance sheet and wish to see a return to the taxpayer, or who actively feel the Fed should have a smaller footprint in the market.

noimage
iFlow

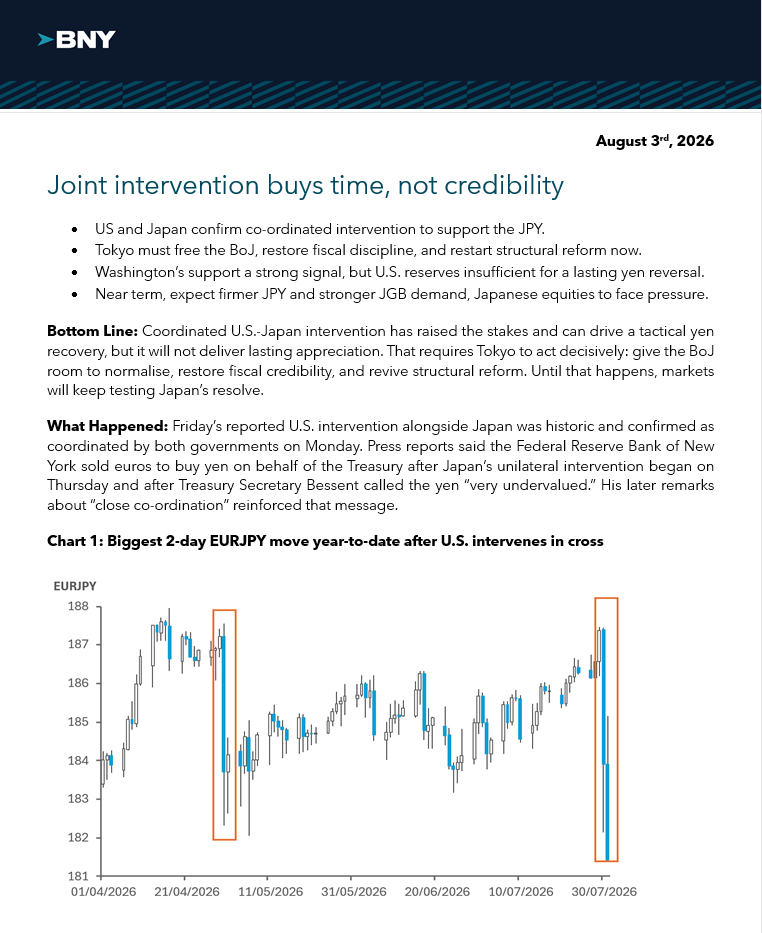
Special Report: Joint intervention buys time, not credibility

U.S.-Japan intervention buys time, not lasting yen strength. Durable appreciation requires Tokyo to normalize policy, restore fiscal discipline, and reform.

Rates Outlook

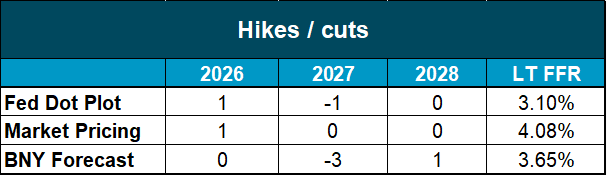
As noted, we don’t expect any hikes this year, despite the three dissents pulling the FOMC in a more hawkish direction.

This week features the July Nonfarm Payrolls (NFP) report on Friday, and market expectations currently see around 80,000 new jobs. We don’t think the payrolls “breakeven rate” is much above 50,000 per month, if that. It currently doesn’t require large monthly employment gains to keep the unemployment rate steady, thanks to a much slower labor force growth than before the pandemic. A print below 80,000, especially if it’s sub-50,000, could depress rate hike expectations further and lower the 2y yield, while we don’t think the back end moves very much.

An additional NFP print and two more CPI releases follow Friday’s NFP report. Warsh’s speech at Jackson Hole at the end of the month is another key event, although given his short track record so far, we won’t be holding our breath for much specificity on rates. The market – and economists – continue to learn about the Warsh Fed.

Inflation is sticky, but it’s also being whipped around by supply shocks. The AI build is raising questions about the capex outlook and its impact on jobs and productivity. Labor supply is restrained, making inferences about the job market fraught, and the new Fed is still being revealed. All in all, a tricky mix of factors for the market to price, and it’s unlikely we’ve reached a steady state yet. 

Chart pack

Media Contact Image
John Velis
Head of Americas Strategy
john.velis@bny.com
Media Contact Image
David Tam
U.S. Rates Strategist
david.tam@bny.com

Ready to grow your business? Speak to our team.