July FOMC a close call
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
John Velis & David Tam
Time to Read: 6 minutes
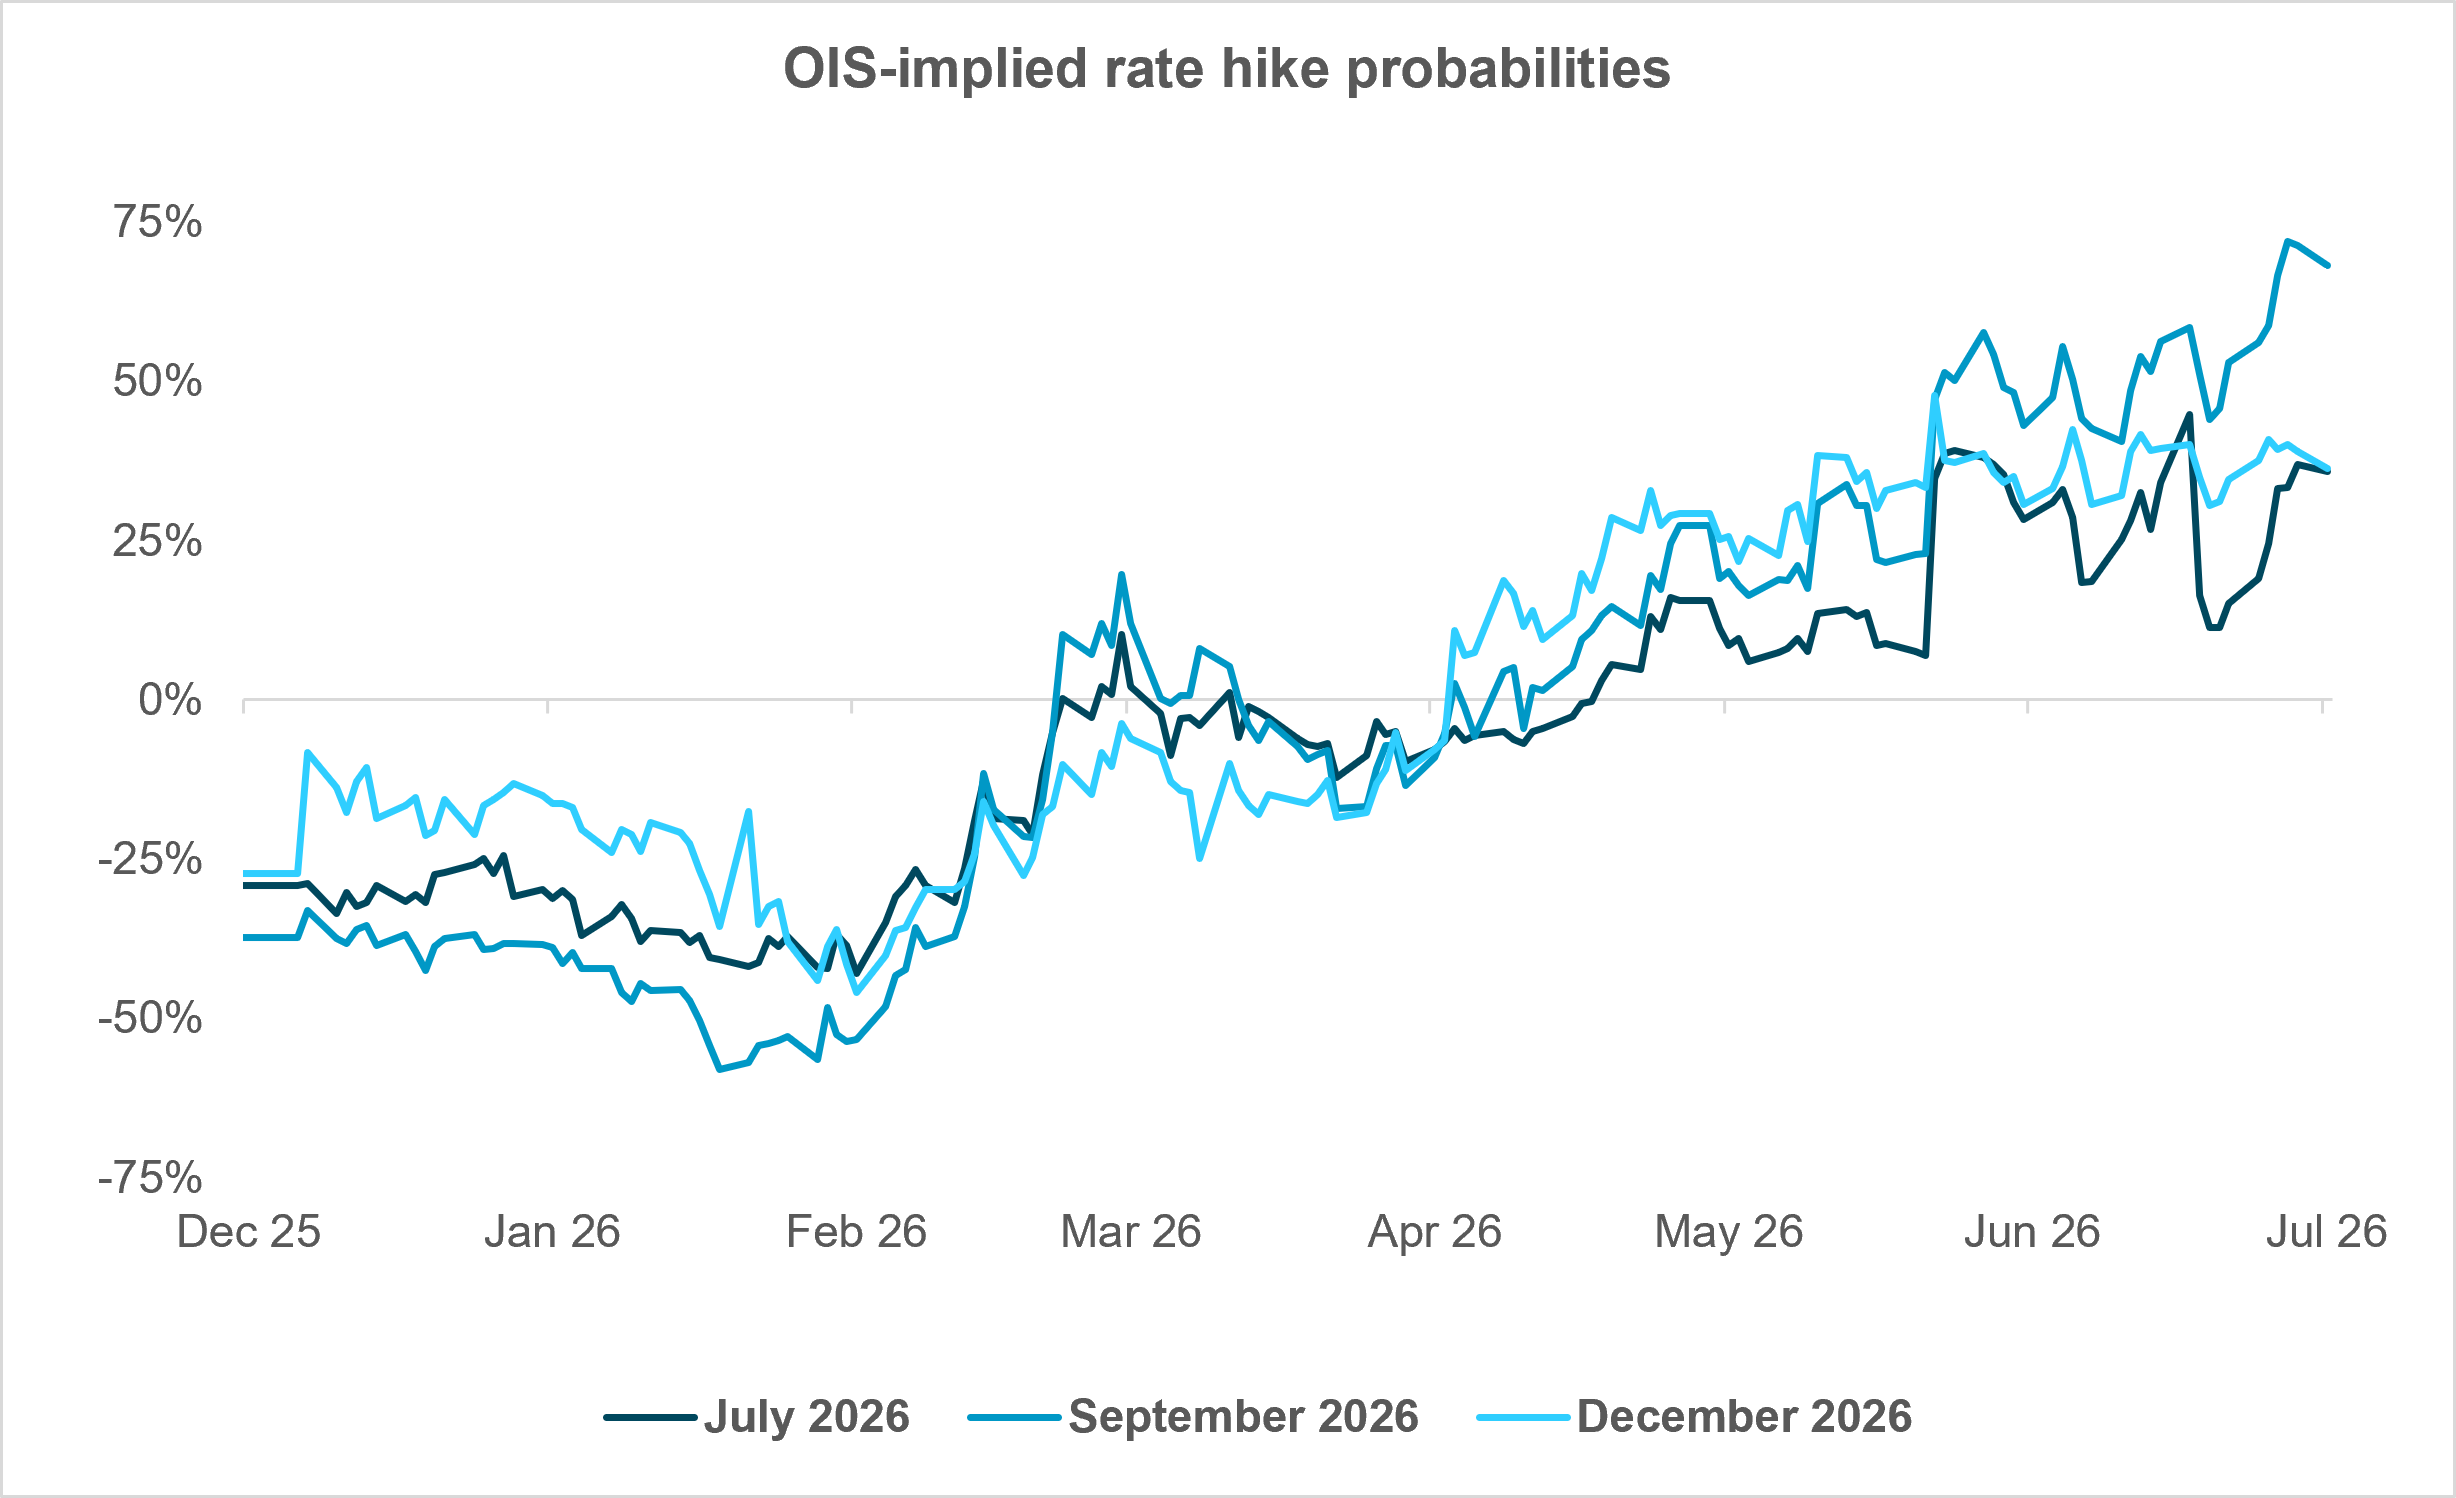
EXHIBIT #1: MARKET EXPECTATIONS BETTING IN A HIKE BY SEPTEMBER
Source: BNY Markets, Bloomberg
We don’t expect a change to the federal funds rate this week, even though we acknowledge it’s finely balanced. If we’re right, hawkish dissents are likely; if the FOMC does tighten, expect a dissent or two in favor of holding.
Market expectations, as shown in Exhibit 1, assign slightly more than a one-third chance of a hike this week. September pricing puts a hike at nearly three-in-four, and combined, July and September pricing suggests the Fed will hike at least once before then, with little expected beyond that.
Many market observers have commented that if the market is already primed for slightly higher rates by the beginning of the fall, the Fed should just go ahead and raise the policy rate this week. We don’t find this answer compelling and observe that implied rate hike probabilities can switch quickly – as evidenced again in Exhibit 1, which shows how quickly the outlook shifted between Q1 and Q2. The geopolitical situation in the Middle East remains intractable and unpredictable, and with that uncertainty, energy prices and inflation expectations might adjust quickly.
In addition, proponents of the “hike now” argument contend that with September pricing so high and the 2y bond yield now at over 4.3%, the Fed risks being forced by the market to hike. Again, this doesn’t by itself sway us. Markets have been highly reactive to data and Fedspeak, and the trailing volatility of the 2y yield is at pre-GFC levels. Given that the Warsh Fed provides precious little forward guidance, this volatility is to be expected. The moves in short coupon yields might render them a poor guide for the markets and the FOMC itself.
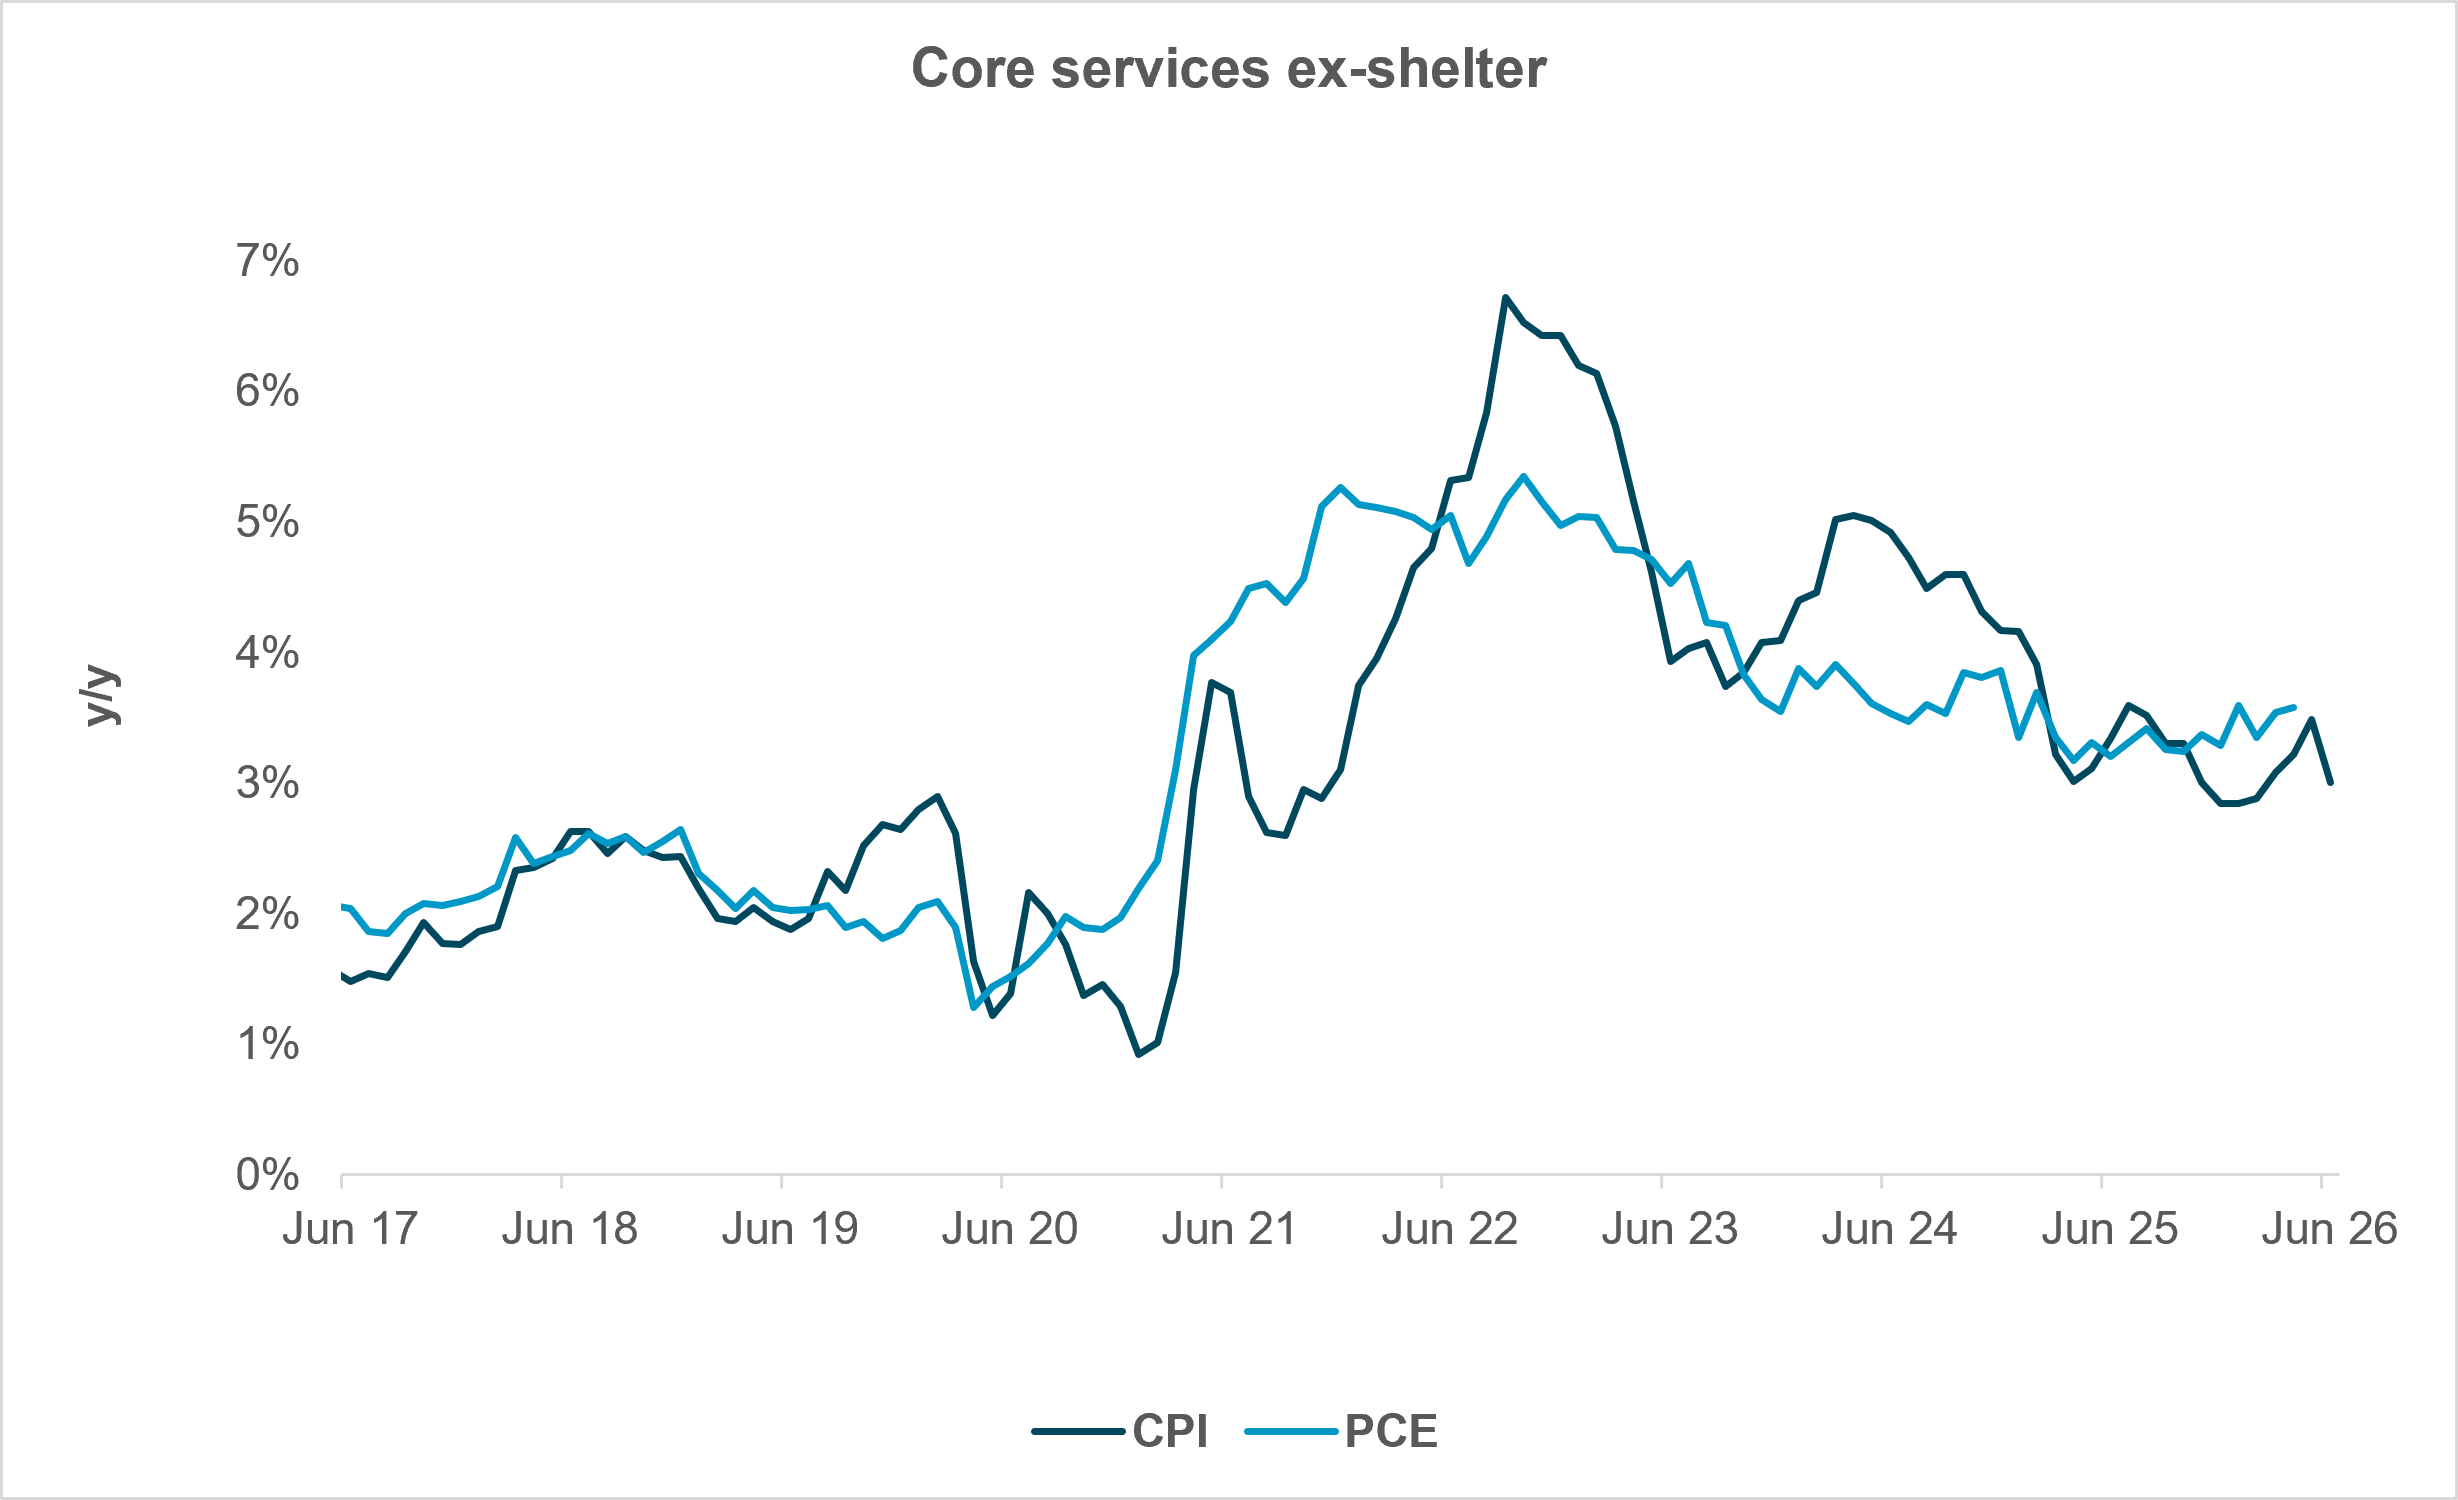
EXHIBIT #2: SUPERCORE COMPLICATES THE INFLATION OUTLOOK
Source: BNY Markets, Bureau of Labor Statistics, Bureau of Economic Analysis
The most compelling argument for a rate hike remains the inflation rate. We don’t view Chair Kevin Warsh’s frequent (of late) references to price stability to axiomatically indicate a new hawkish direction from the Fed, but we do acknowledge that other speakers have gone on record that they view inflation as not only too high but also reflecting upward pressures beyond mere tariff effects and the supply shock from the Middle East. We share that concern, and note that since mid-2023, so-called “supercore” (i.e., core services inflation ex shelter) has been running at nearly a percentage point above its pre-COVID pace. See Exhibit 2.
So why, then, not raise rates this week? First, we don’t find the arguments for a hike completely persuasive, although we acknowledge (again) that the meeting is a close call and supercore inflation has caught our eye for a while. While we don’t dismiss sticky supercore inflation, it’s steady and hasn’t been rising. The CPI-based supercore was up 3.0% in June, one of its lowest post-pandemic prints. The May PCE data for the same category (June’s result will be published this Thursday, after the Fed meets) show a 3.6% increase.
Furthermore, much of the increase in this important inflation subcategory is from transportation services – notably airfares, which are obviously affected by the energy shock. Other components keeping the pressure on services are health care costs – representing rising insurance premiums, themselves impacted by reduced Obamacare subsidies – and financial services. Transportation and health care together contribute 0.7% to the 3.0% increase in supercore. None of these are particularly sensitive to tighter monetary policy.
With the recent resumption in Middle East hostilities, we expect many energy-related components to push higher, including those elements of supercore (like transportation) that are impacted by supply chain shocks. However, we see relief in many other categories not related to energy prices. Two more CPIs and two more PCE deflators will be published before September 16, and they are likely to move the needle definitively one way or the other. We think it prudent for the Fed to wait to see both the depth and breadth of renewed higher energy prices on the aggregate indices.
If we’re right and the Fed elects not to change rates, we’d expect the market reaction to depend on how such a hold is presented. Will it be a “hawkish hold” that leaves the market expecting September to be a sure thing, or will the Warsh Fed be reticent to hint at what’s coming? We think the latter, given the new Chair’s recent comments. If the market concludes that the outlook calls for a hike in September, we think that yields could rise across the curve. However, we expect that increase to be muted, considering where pricing already stands. Mere confirmation of the market’s suspicion is unlikely to create much movement. However, if there is nothing to infer about future Fed policy on Wednesday, we would expect at least a short-lived bout of rates and currency vol, with the upcoming inflation data key to the next move in market expectations. If we’re wrong and the Fed “zigs,” contrary to our expectations of a “zag,” all bets are off, and we could see a rather bearish reaction.
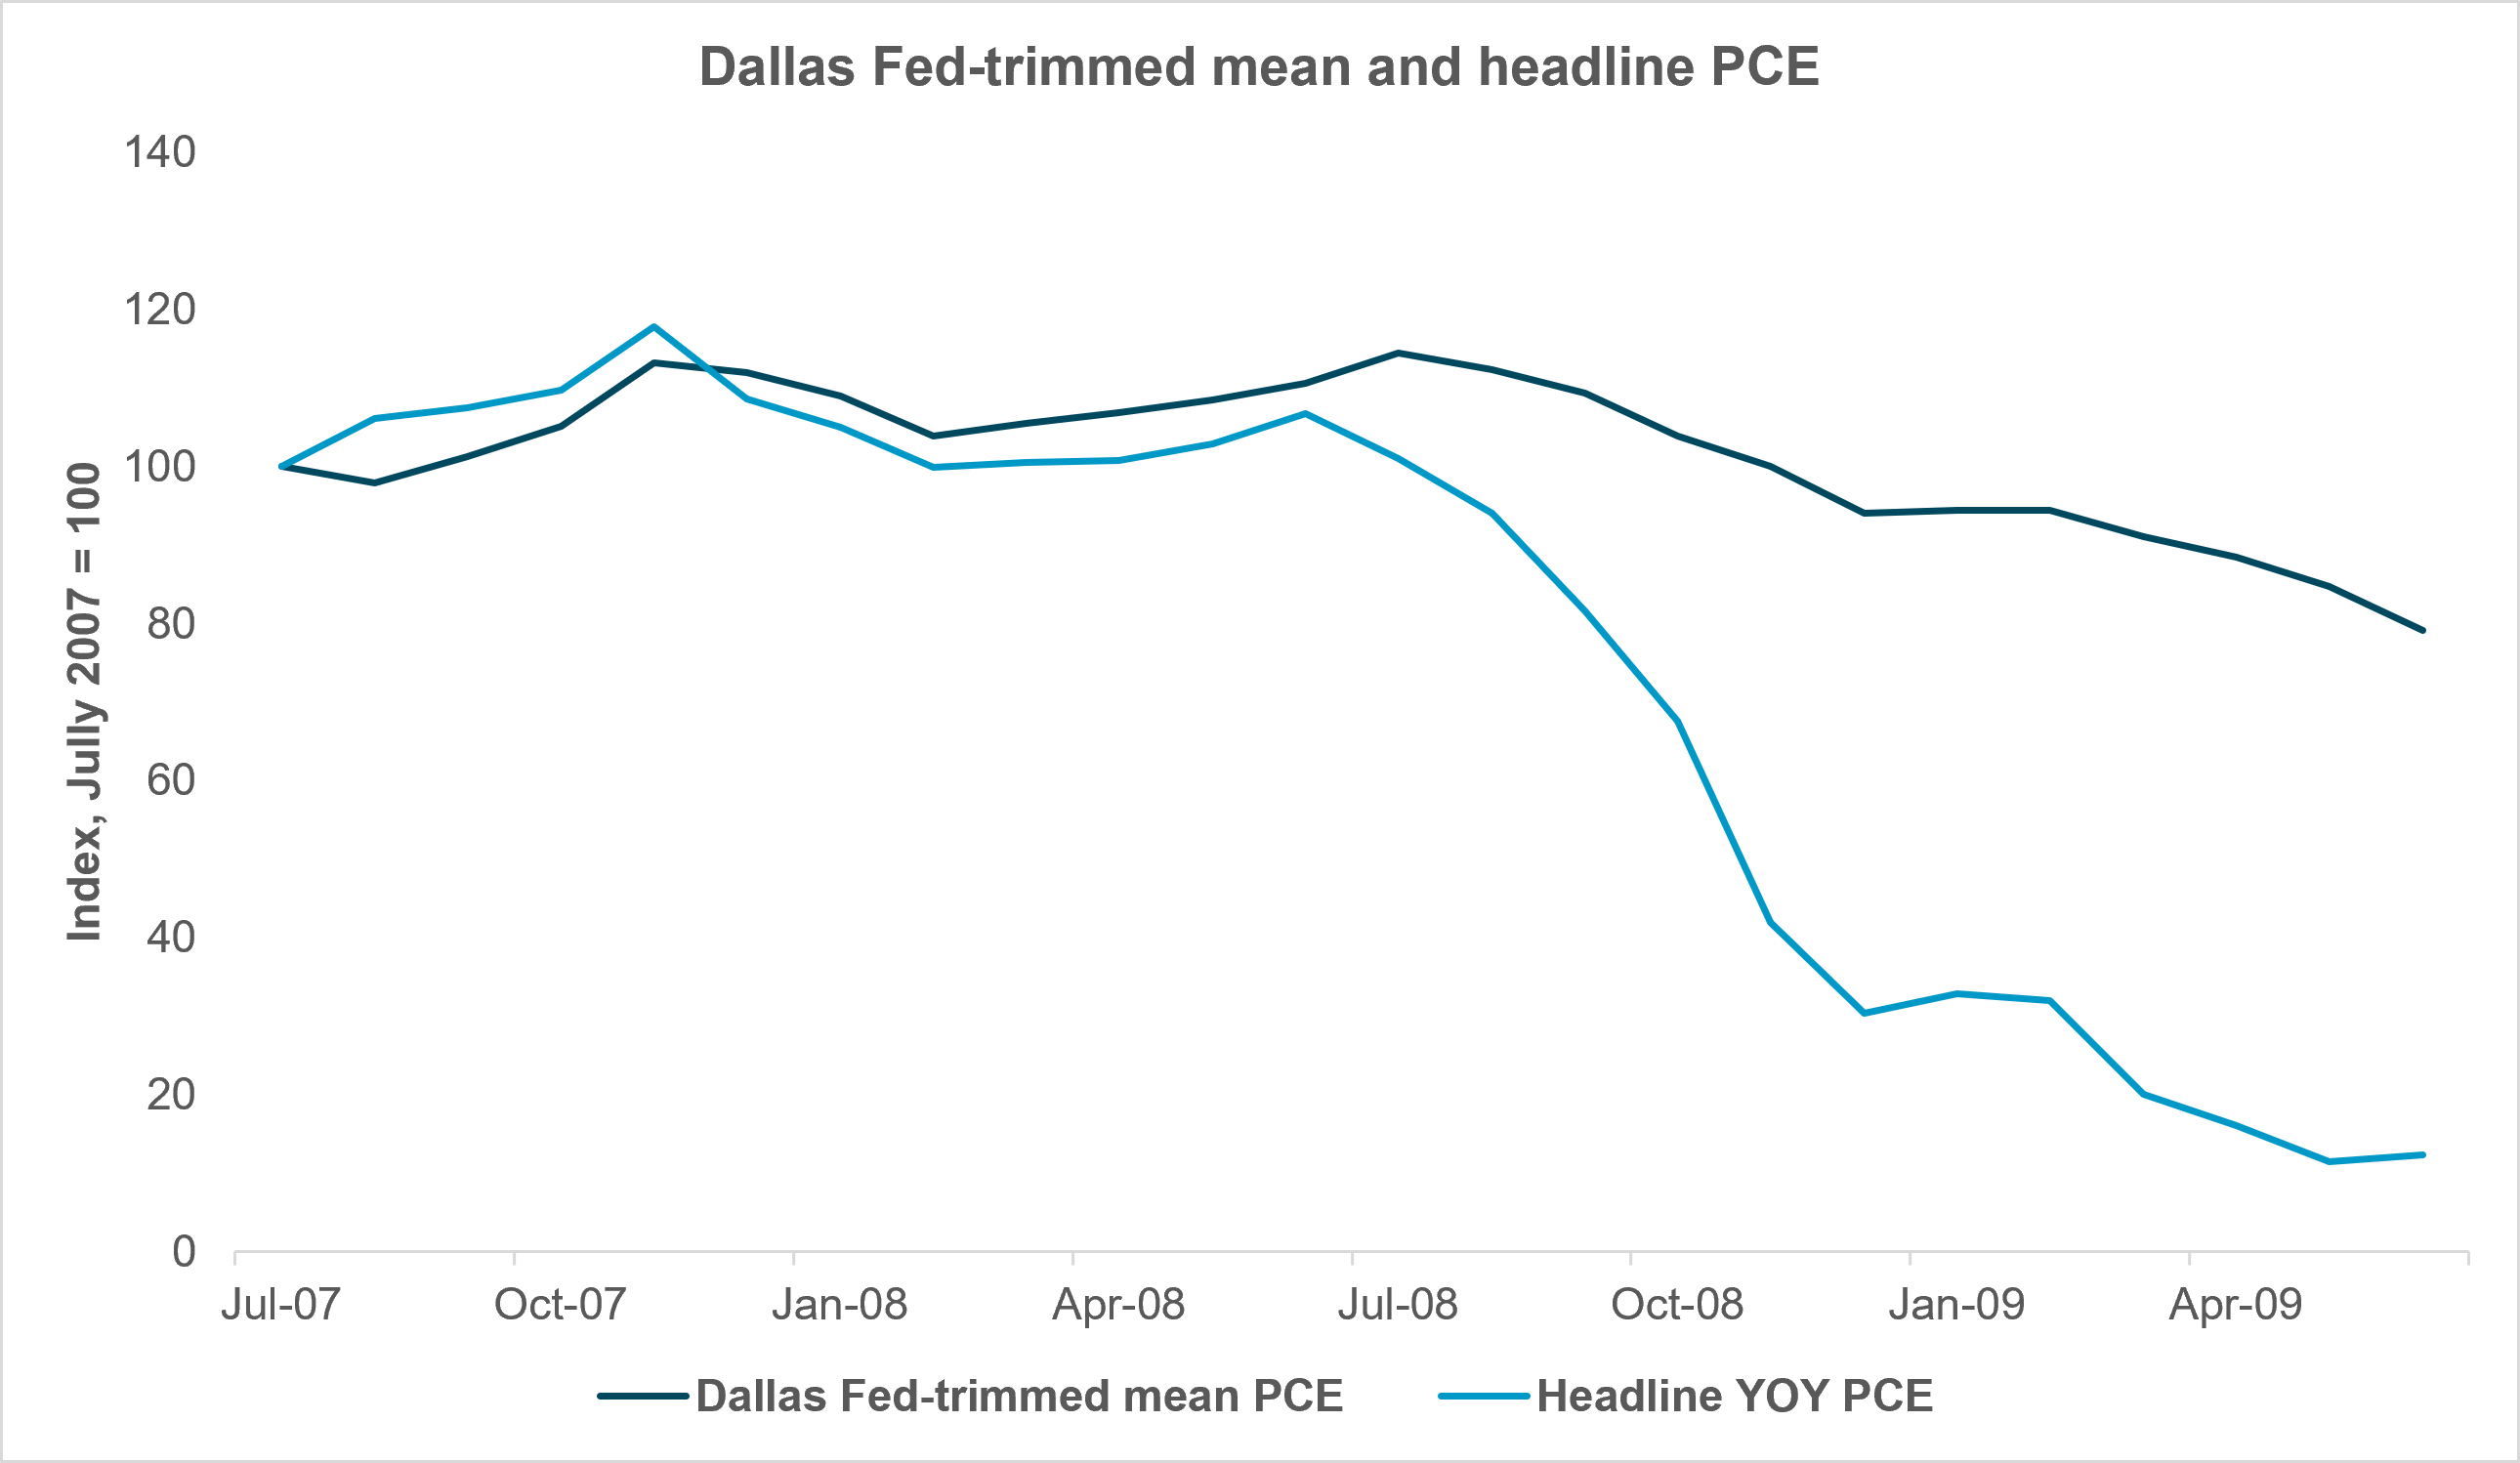
EXHIBIT #3: TRIMMED MEAN WOULD HAVE MISGUIDED THE FED DURING THE GFC
Source: BNY Markets, Bureau of Economic Analysis, Federal Reserve Bank of Dallas
Warsh has said that the Inflation Frameworks Task Force will examine “the drivers of inflation, first principles, and weigh the full range of ideas for delivering price stability in a changing economy.” The use of “first principles” is noteworthy because, though the Fed formally targets headline PCE, Warsh has at times signaled that he favors other measures, such as a form of trimmed mean inflation.
Trimmed mean inflation removes the most extreme monthly price moves, making it smoother and more inertial than headline or core measures. During the post-COVID inflation surge, this feature generally caused trimmed mean measures to print below conventional gauges. The two oft-cited measures, produced respectively by the Cleveland Fed and Dallas Fed, use slightly different methodologies but both strip out the noisiest items. The academic debate rests on whether they throw the baby out with the bathwater and also strip out the earliest or most persistent signals of a shift in the trajectory of inflation.
Crucially, while trimmed mean inflation understated rising inflation in the aftermath of COVID relative to core y/y PCE, it need not always be dovish. In a period of disinflation driven by specific volatile components, trimmed mean would also understate disinflation. In the wake of the global financial crisis, it did just that as shown in Exhibit 3, with headline inflation falling quickly in late 2008, while the Dallas trimmed mean took until mid-2009 to show a similar decline.
More recently, when pressed at his Humphrey Hawkins testimony, Chair Warsh distanced himself from the trimmed mean methodology, calling it “a very good measure of underlying inflation,” and suggesting “If I had a preferred measure, I wouldn’t have called for a task force to go back to first principles.”
The three task force leaders have said little on trimmed mean inflation. All are well-regarded academics, and two have previous policy-making experience. Greg Mankiw, who previously chaired the Council of Economic Advisers, has written on the limits of the Phillips Curve and sticky prices. Thomas Sargent, a Nobel laureate, has written on how central banks could build inflation-fighting credibility and how high inflation can end quickly under the right regimes. William White, a former BIS adviser, has argued that central banks have been too focused on short-run inflation.
Above, we presented our views on this week’s rate decision, which we narrowly mark down as a hold, albeit with significant uncertainty. What happens later in the year is largely a function of what comes out of the Eccles Building on Wednesday. Frankly, whatever the decision on rates is, we don’t expect to be able to infer much of anything about the rate path into September, leaving the market to navigate data and the Middle East conflict on its own.
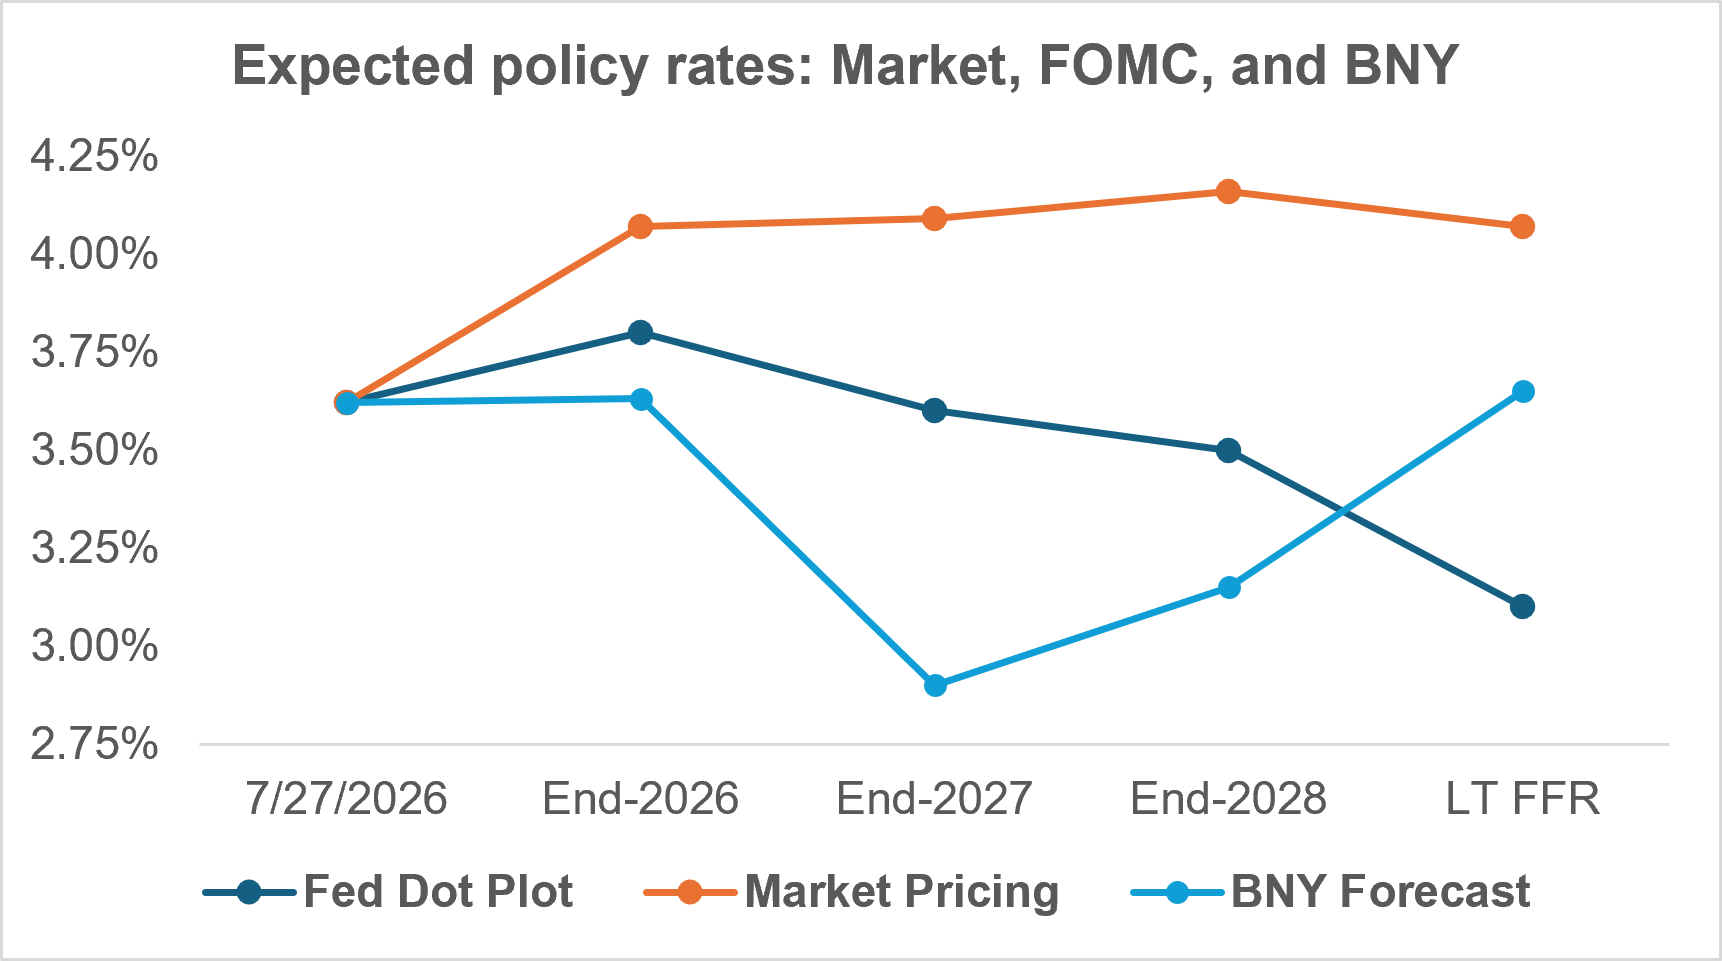
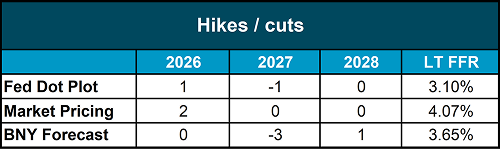
For now, we hold on to our “steady-as-she-goes” view; policy rates won’t change this year, which would imply that the front end of the curve is cheap. However, given the uncertainty going into Wednesday and the lack of forward guidance, we don’t think receiving rates at the moment is the best way to play this. Markets will likely be volatile – especially in the front end – no matter what comes from the FOMC this week. We’d prefer to wait for some clarity on both the geopolitical backdrop and the inflation outlook.