IPOs, liquidity and funding markets
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.

John Velis, David Tam
Time to Read: 5 minutes
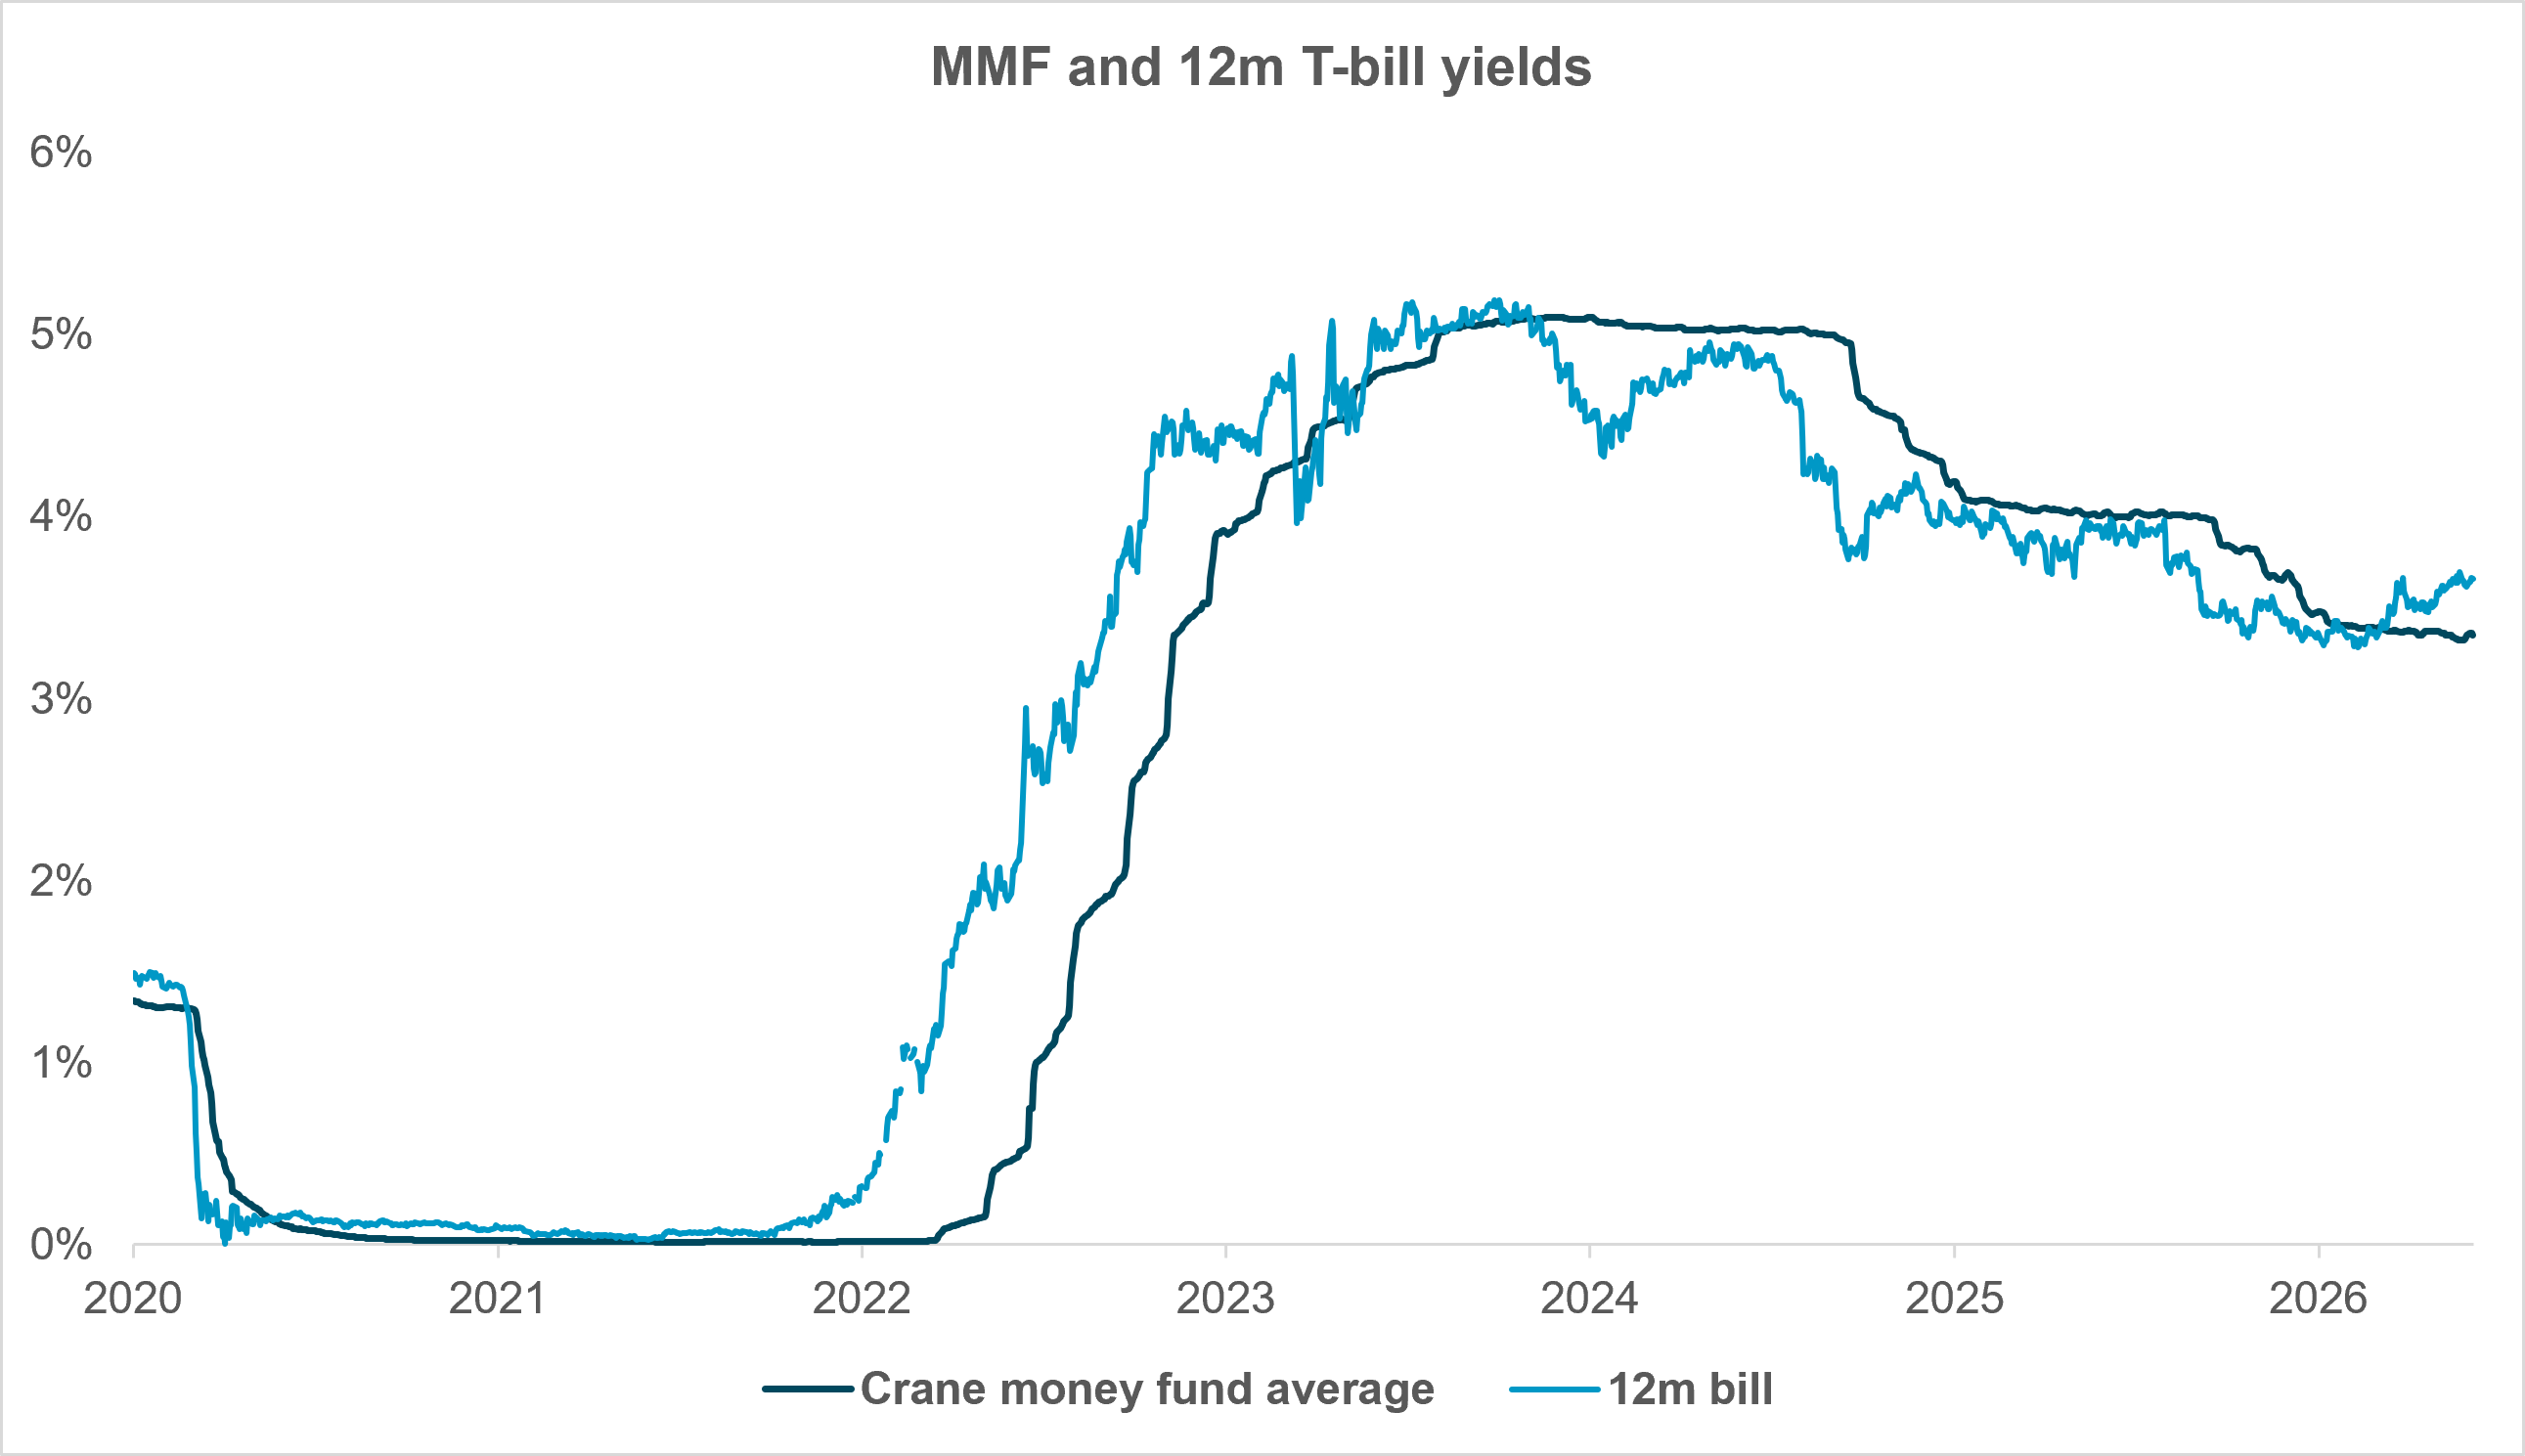
EXHIBIT #1: MMF YIELDS LAG INTEREST RATES – SET TO RISE?
Source: BNY Markets, Crane Data LLC, Bloomberg
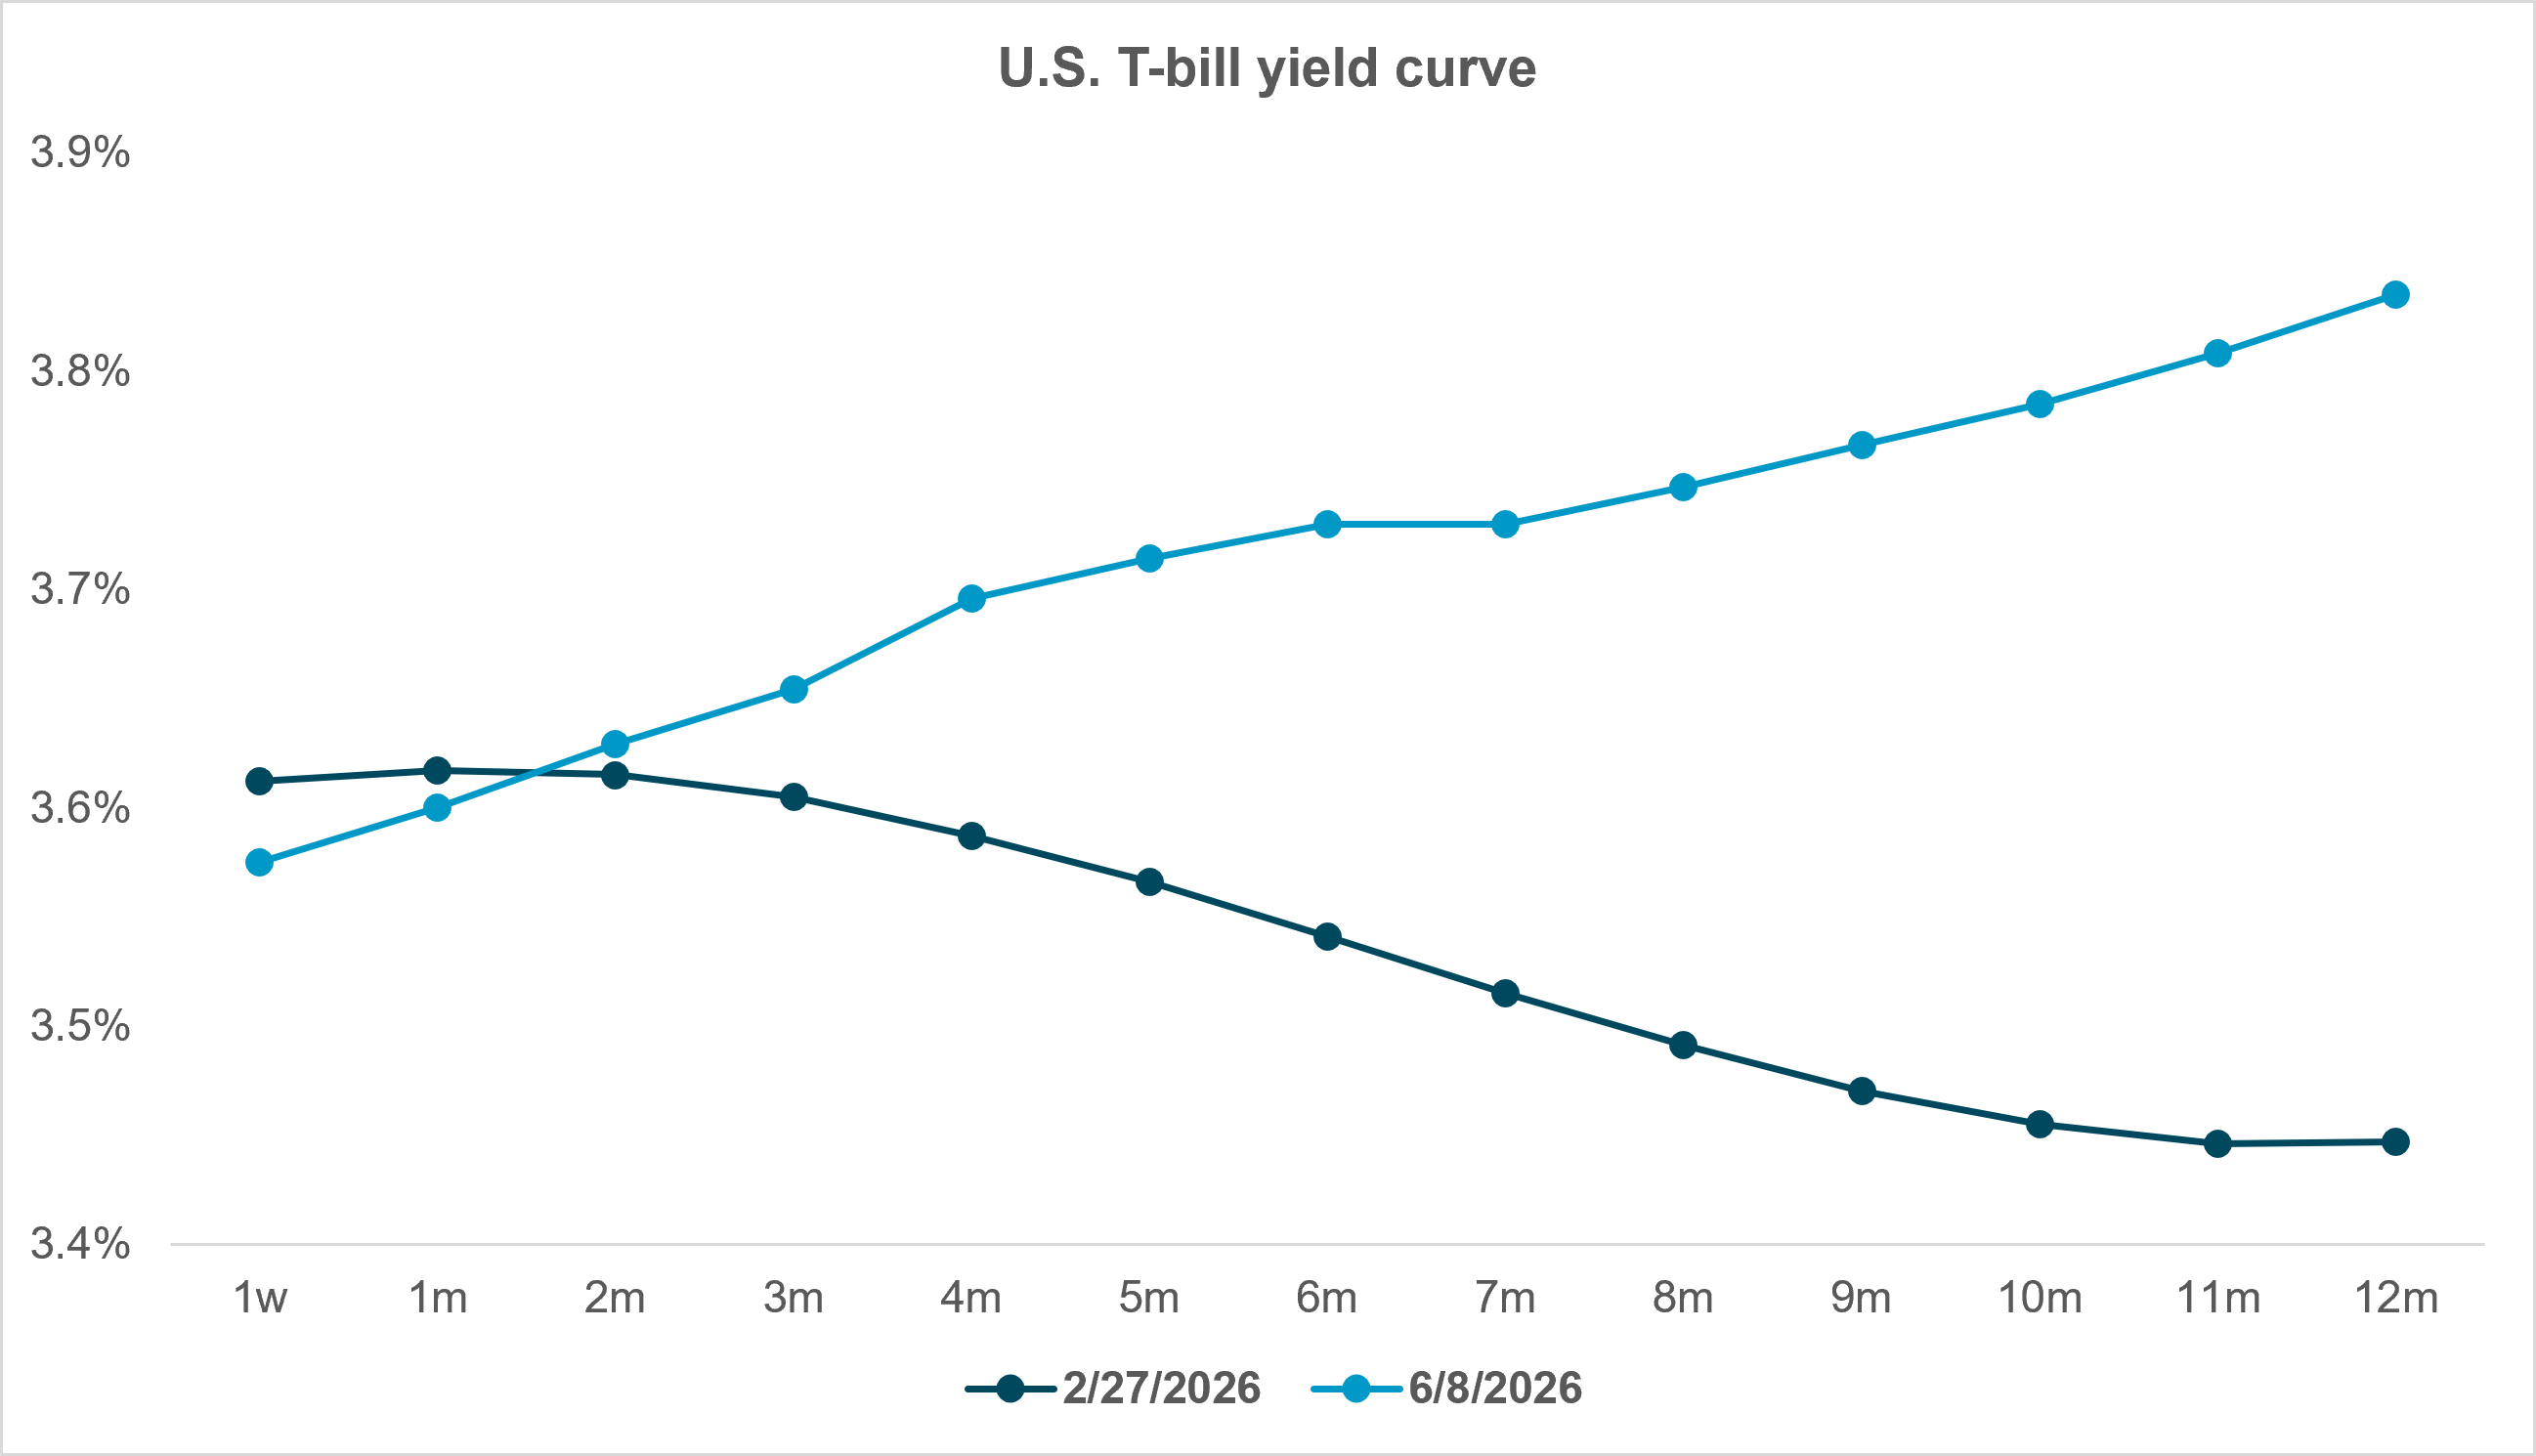
EXHIBIT #2: T-BILL CURVE STEEPENS
Source: BNY Markets, Bloomberg
According to the Investment Company Institute (ICI), money market mutual funds (MMFs) increased their assets under management by more than $109bn in the week ended June 5, rising to a total of $7.89tn, a record high. All told, last week was only the eighth since 2020 during which ICI’s measure of MMF AUM swelled by over $100bn. Crane Data’s broadest money fund index, which includes more funds than ICI, shows a record $8.45bn in AUM through last Thursday. Since its recent low on April 24, just after tax week, the Crane total has increased by over $330bn.
It’s tempting to explain this MMF asset increase as a yield play – the prospect of Fed rate hikes is growing (especially after a second consecutive strong jobs print last Friday – see below in the Rates Outlook section), and investors are anticipating higher MMF yields as a result. With the 1y T-bill now yielding around 3.7% – the highest rate since last September –MMF yields could rise along with more hawkish monetary policy expectations.
However, that’s not happening yet. As Exhibit 1 shows, MMF yields (here, we plot the Crane Money Fund Average seven-day yield) have stayed around 3.35% for a while, even as T-bill rates have increased since the start of the conflict in the Middle East, with an increasingly hawkish rates outlook. There is often a lag between MMF returns and T-bill rates as can be seen in the exhibit, and the current situation is in line with that behavior. Should rate hike expectations merely stay where they are – with the OIS market implying nearly 100% probability of a rate hike by this December – and T-bill rates remain elevated, yields could start to rise later this year.
The T-bill curve has shifted from an inverted slope just before the war started to a steeply sloped and more elevated term structure now, as shown in Exhibit 2. Ordinarily, this might induce funds to move further out the curve in their Treasury allocations to realize additional basis points of yield, but that hasn’t happened in any significant way either. Weighted Average Maturity of the average fund of all types (treasury, government, prime; either retail or institutional) has barely budged since the beginning of the year, despite the sharp changes in T-bill rates.
EXHIBIT #3: RETAIL CASH AT BROKER DEALERS ISN’T EXCESSIVE
Source: BNY Markets, Federal Reserve Board of Governors, Bloomberg
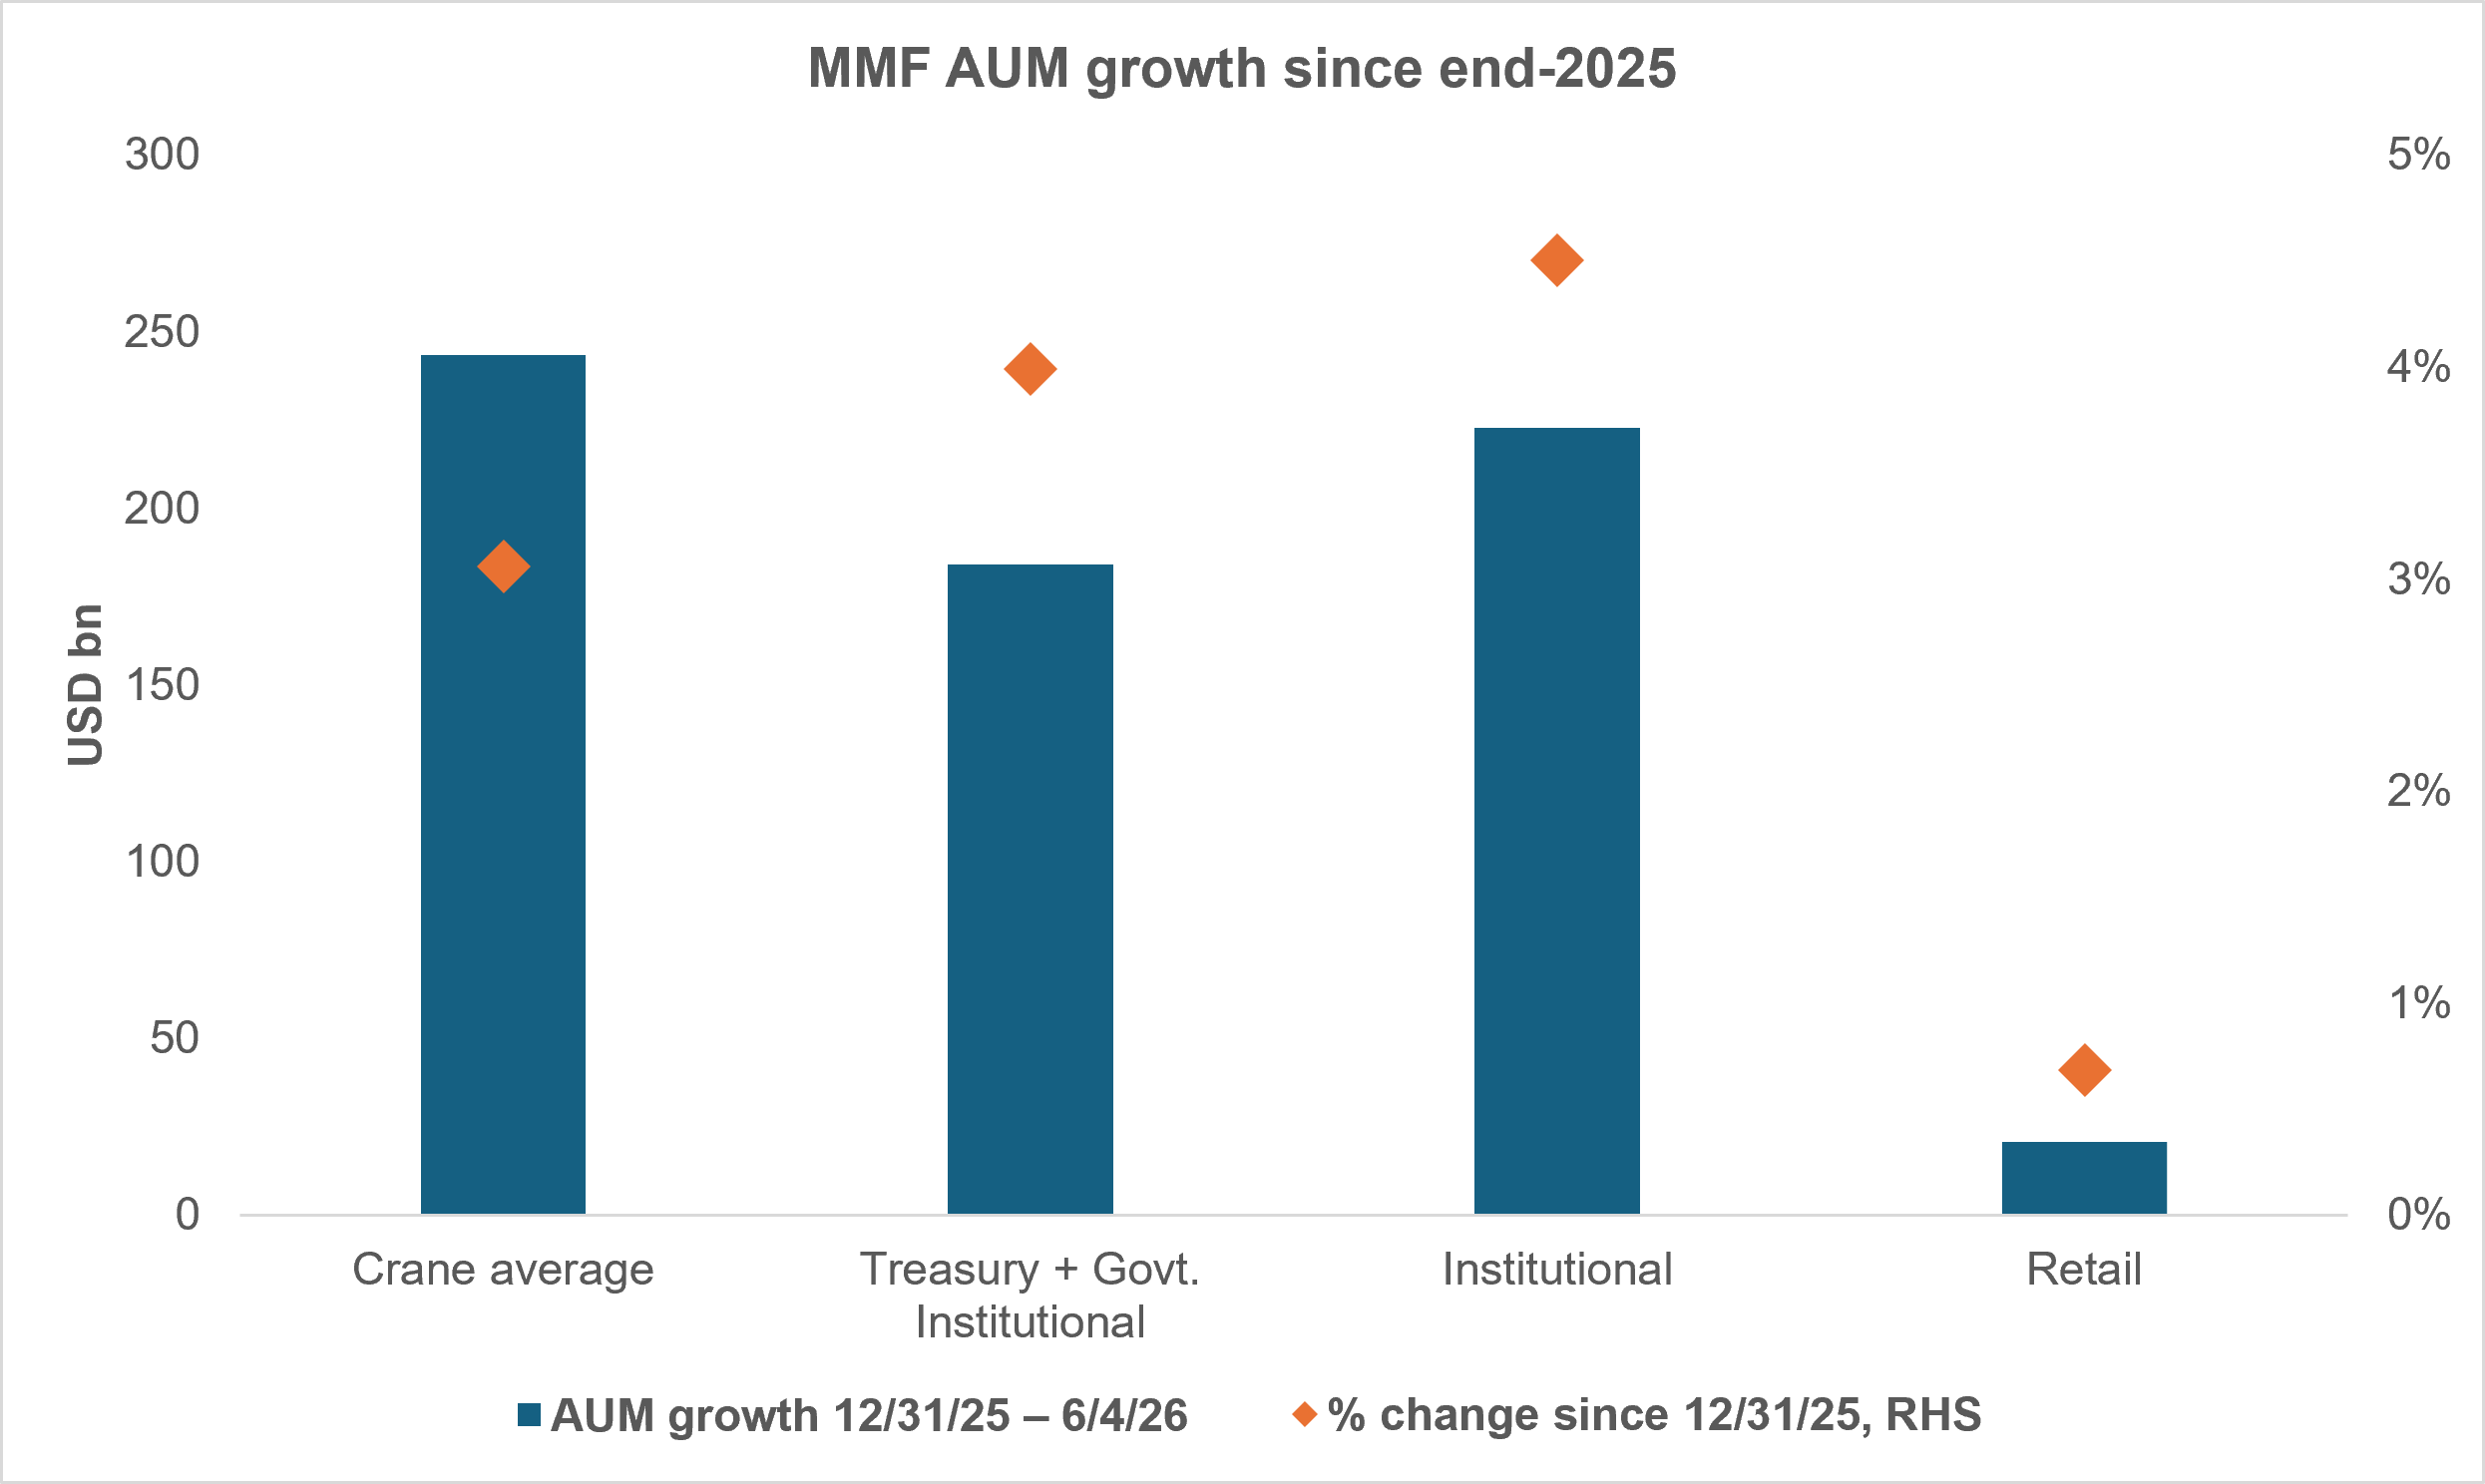
EXHIBIT #4: RETAIL MMF GROWTH SUBDUED VS. INSTITUTIONAL
Source: BNY Markets, iFlow
Another potential explanation – perhaps somewhat underappreciated by observers – is that institutional investors could be building cash balances in anticipation of upcoming tech IPOs. SpaceX could generate $150bn in demand for its share offering later this week, as it is presently reported to be 2x oversubscribed. Other large and high-profile IPOs remain in the pipeline.
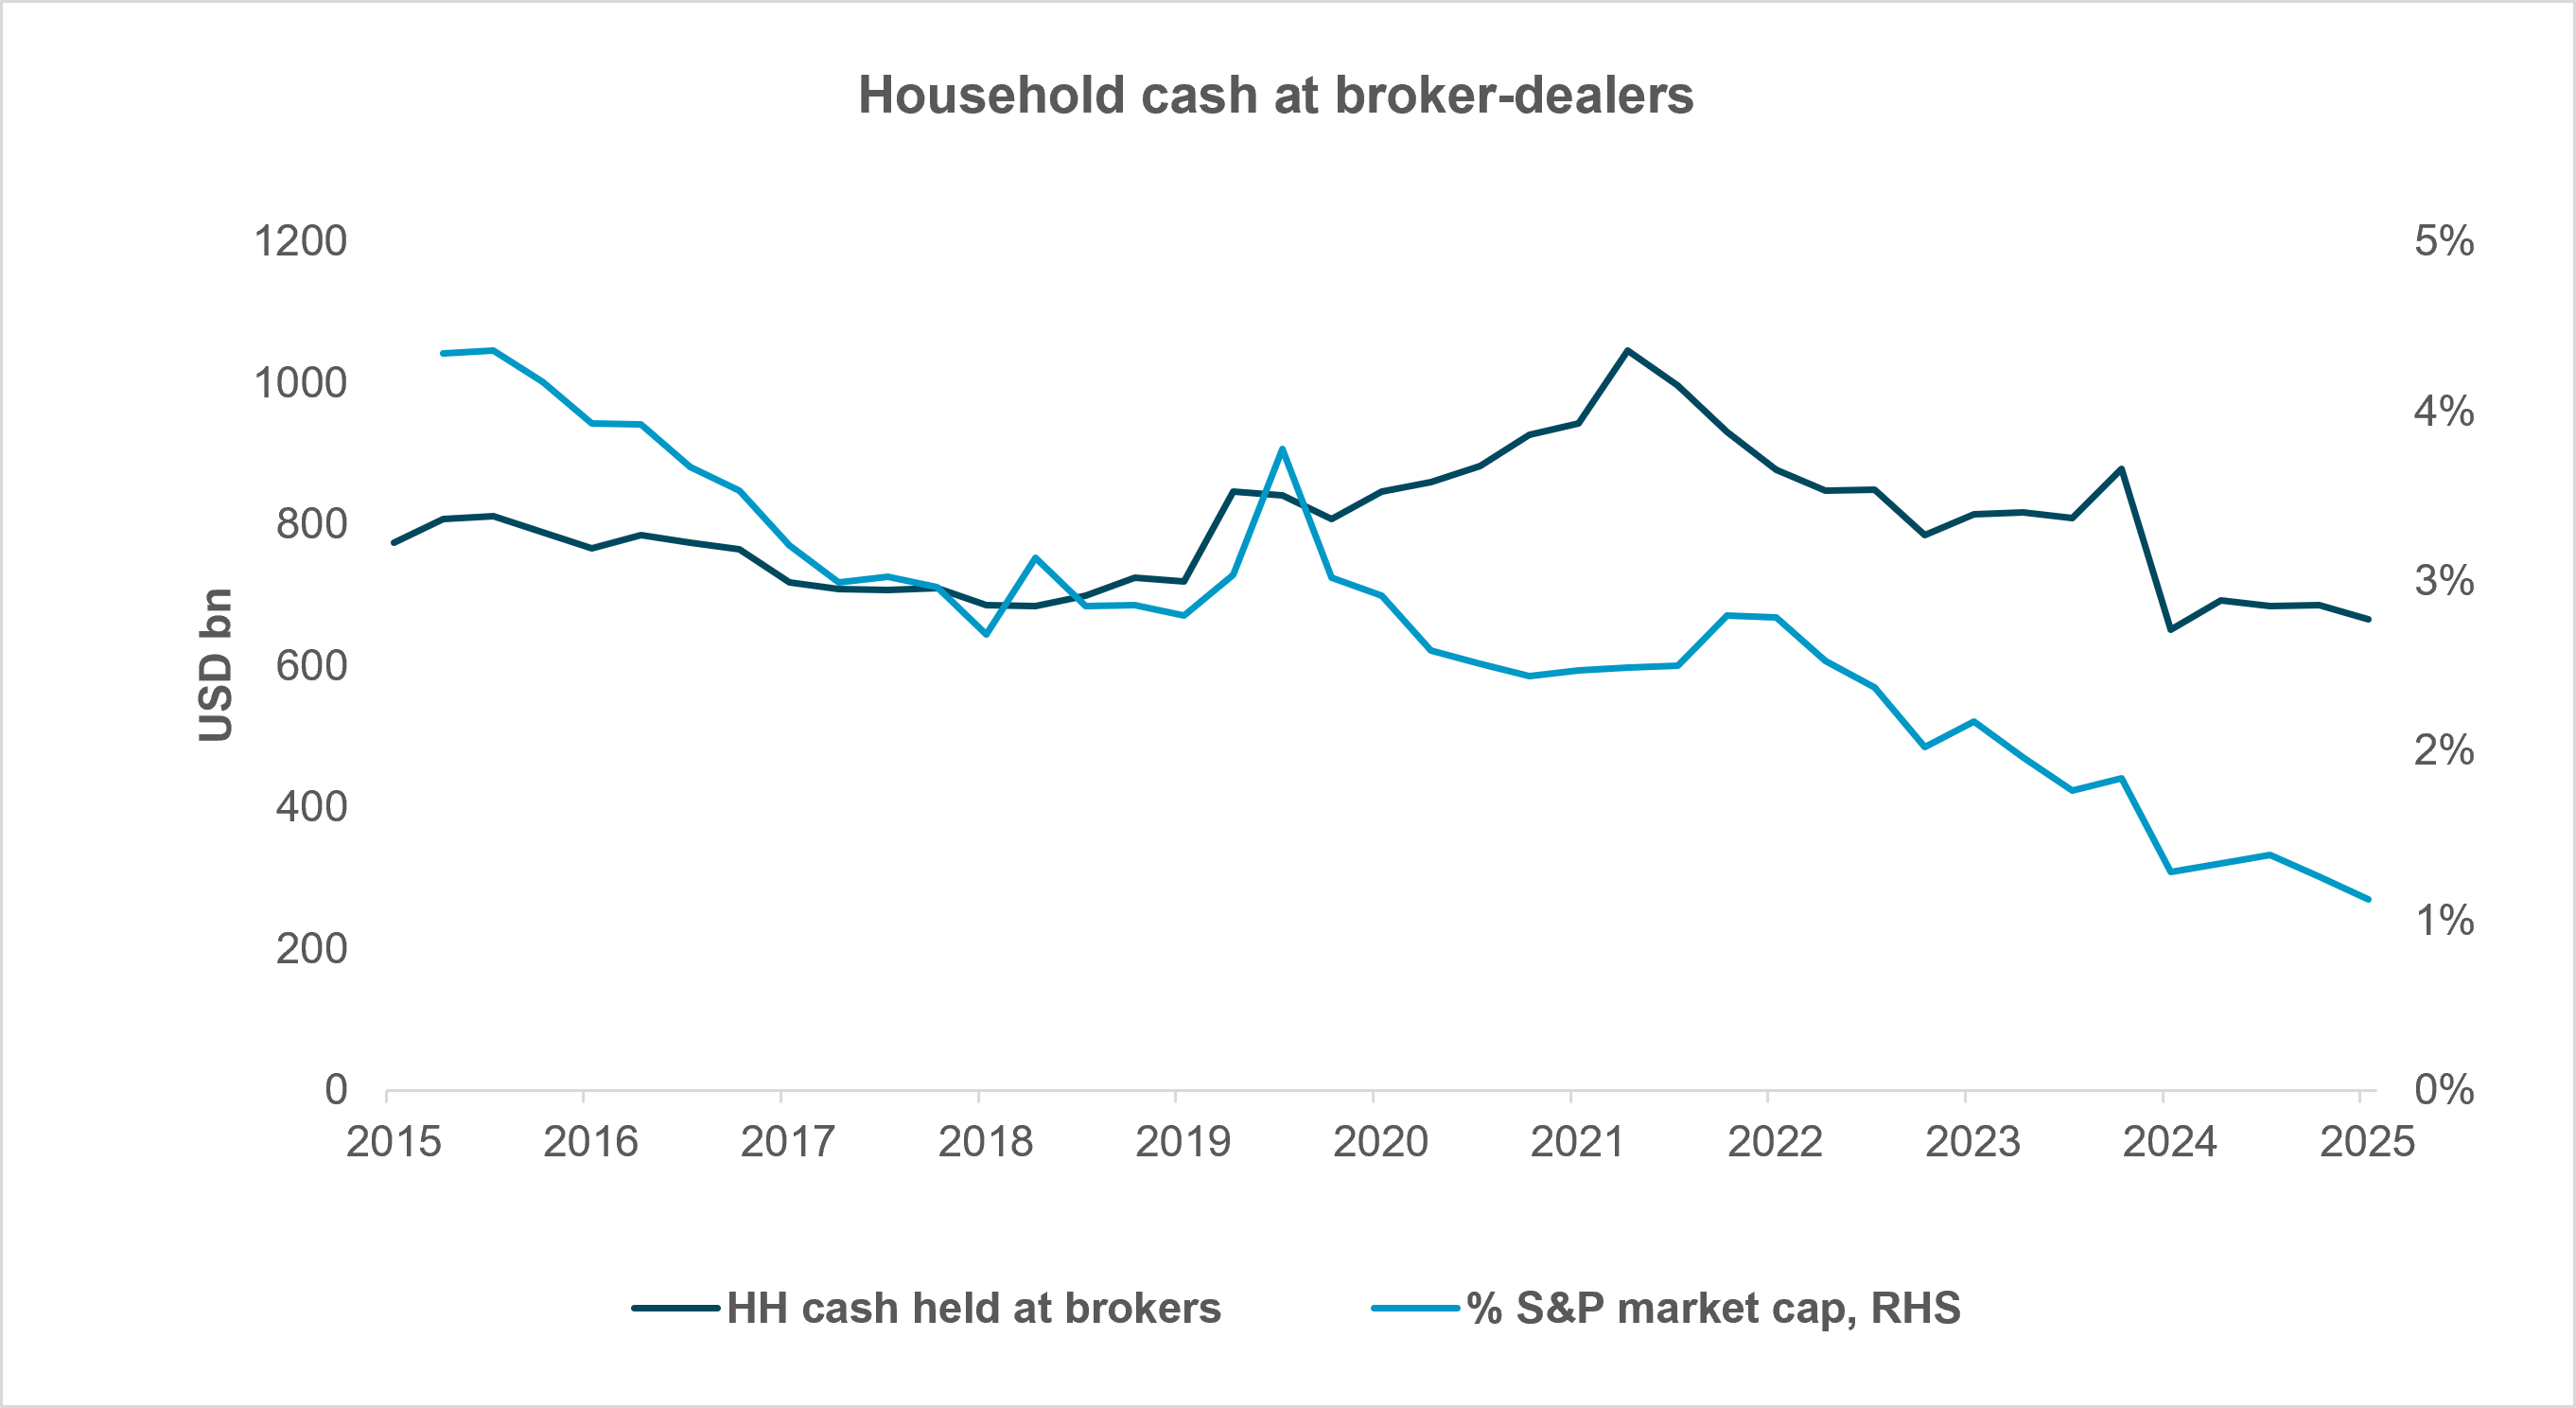
From the data, we think there could be more money coming from institutional investors than retail. Exhibit 3 tracks, from the U.S. Flow of Funds data (Financial Accounts of the United States) cash held by households at broker and dealers through Q4 2025 – the latest data available. It was not excessively high at the end of last year, either in absolute terms or relative to the size of the U.S. equity market. Furthermore, as we mentioned above, according to the Crane Data, growth in retail MMF assets has lagged significantly that for institutional funds (see Exhibit 4). While our Flow of Funds data on households’ cash holdings is several months old – the Q1 2026 report is released this Thursday – what we see in retail MMFs through the end of last week indicates no significant cash buildup to be deployed into the IPO pipeline.
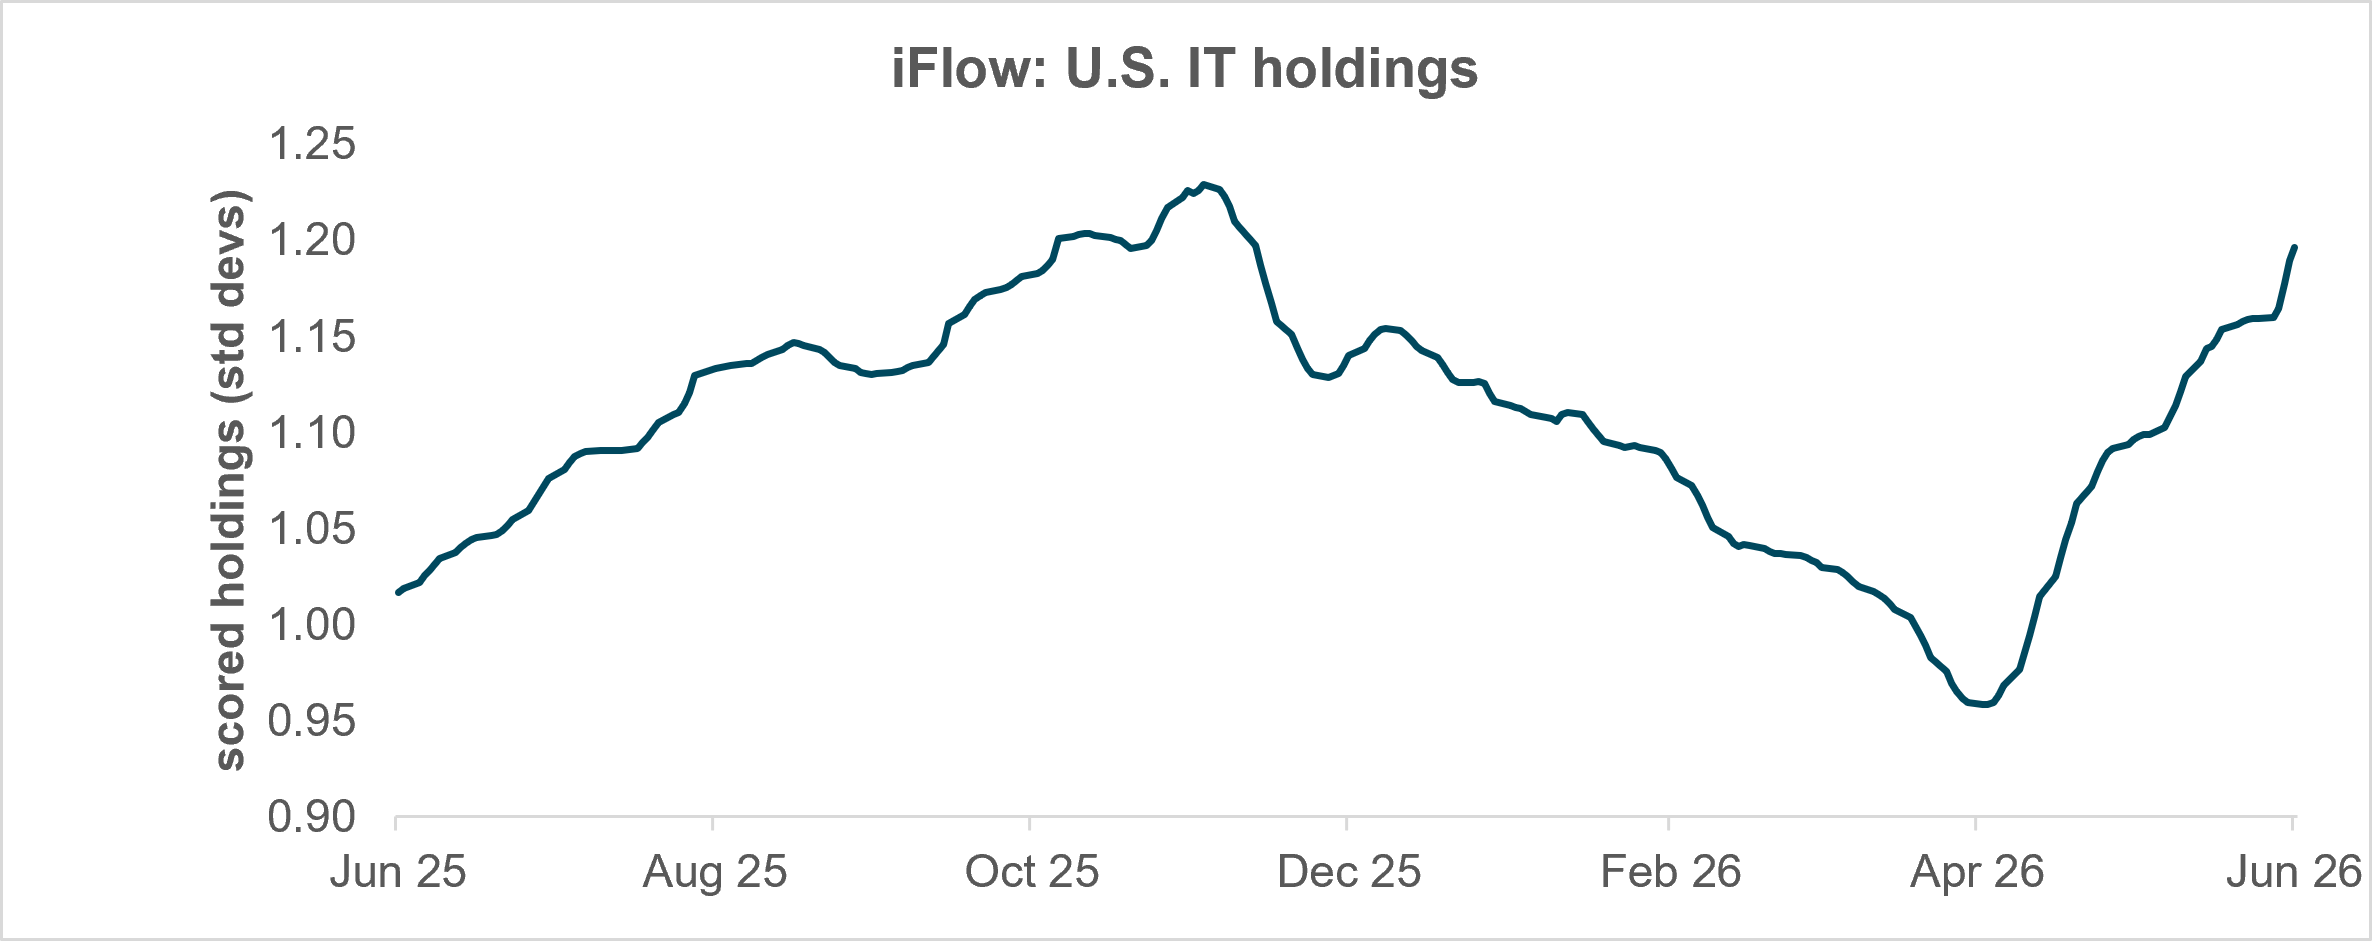
EXHIBIT #5: U.S. TECH HOLDINGS BACK TO ELEVATED LEVELS
Source: BNY Markets, iFlow
That isn’t to say that funding markets aren’t going to be impacted by the largest IPO in history at the end of this week. Liquidity will undoubtedly move from cash into markets, although the quantitative impact is difficult to assess a priori. There is a chance that much of the new money for the IPOs rotates out of other equity – particularly IT – names. Exhibit 5 shows iFlow data on IT holdings in DM Americas equities. Holdings, which had been declining since early November 2025, bottomed in early April and have been significantly rebuilt since. That’s where we should look for “dry powder” to participate in the upcoming equity placements.
Another reason to be relatively sanguine about the impact these offerings will have on funding conditions is how awash with liquidity money markets have been lately. Overnight SOFR has not closed above the Fed’s IORB rate since April, indicating ample cash in the system. The Fed’s scaling back of reserve management practices in each of the last two months indicates comfort with liquidity conditions. This week in particular, T-bill settlements should be negative, keeping funding rates soft.
The bottom line: while retail cash holdings don’t look to be particularly high as we head into the SpaceX IPO, institutional cash is quite ample and could reflect the building of cash positions to deploy for the IPOs. We don’t expect significant disruptions in funding at the end of this week, given current liquidity conditions.
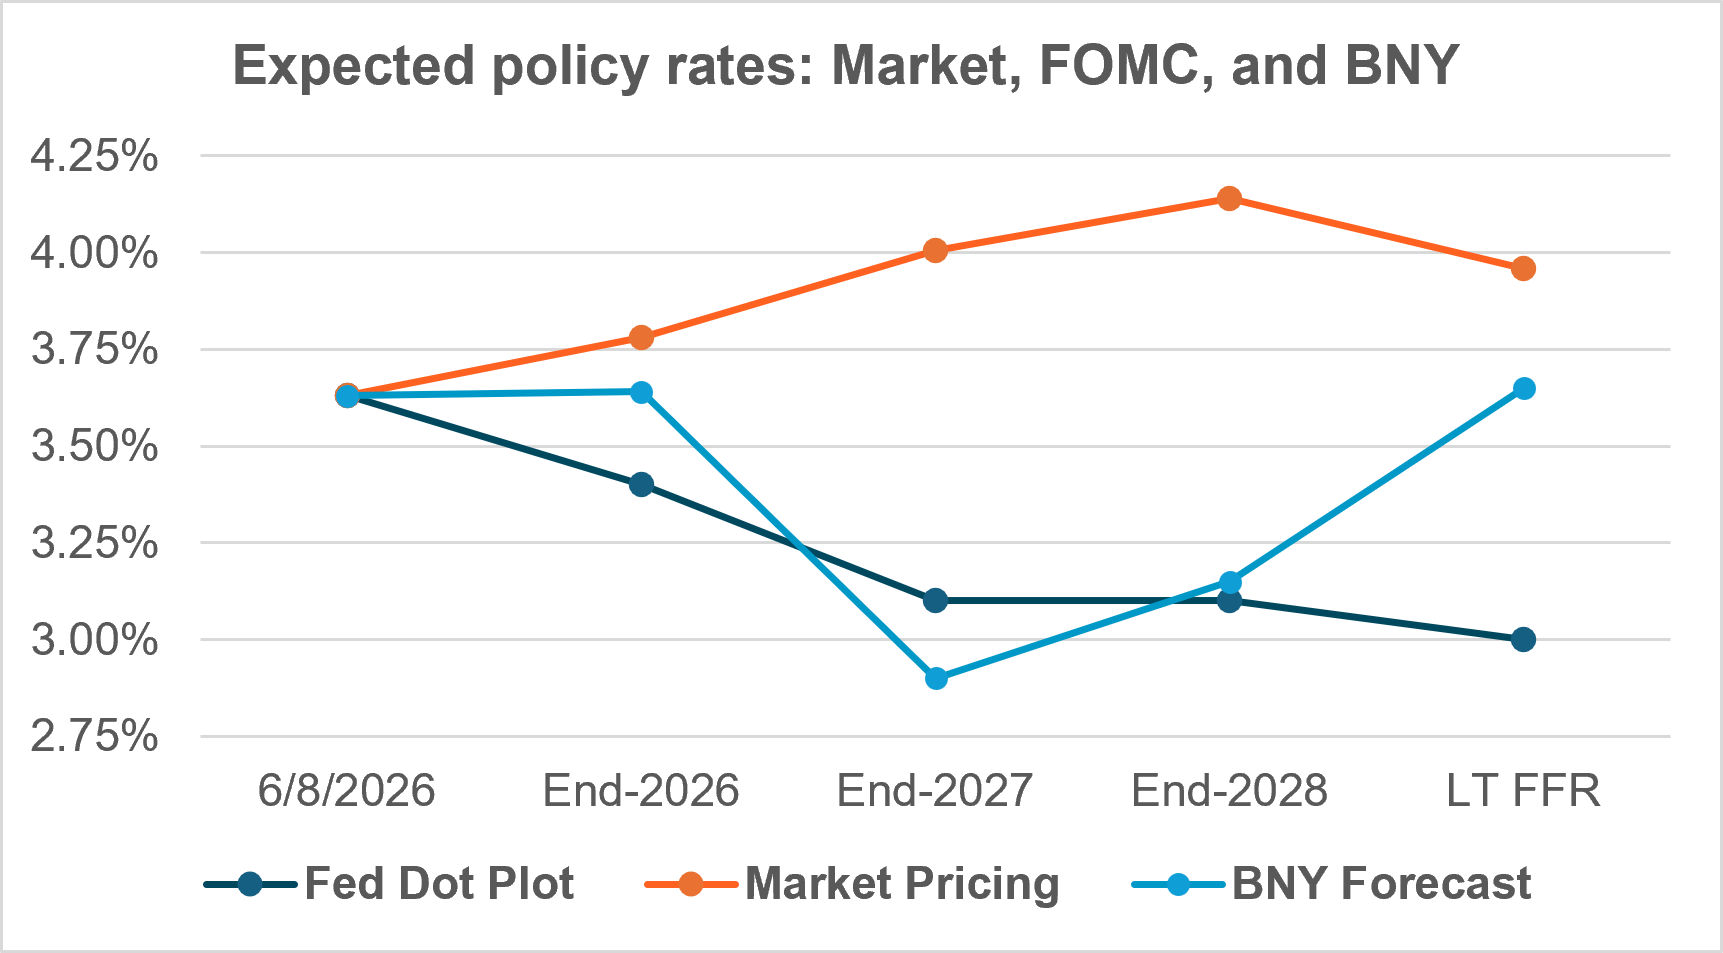
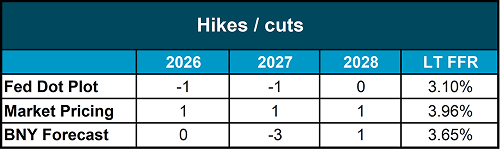
Stronger economic data – especially the impressive NFP report last Friday – have the market fully anticipating a rate hike by the end of the year. The December 2026 OIS curve currently implies a 28bp increase in the policy rate. Furthermore, the 2y10y yield slope has narrowed from over 70bp to under 40bp, as the short end has seen a bigger pickup in yields than the long end. Central bank communications, now on hold due to the Fed’s media blackout, indicate rising support for more hawkish language in the FOMC statement and have argued that hikes are as likely as cuts, and maybe more so. Most of the increase in nominal yields across the curve – especially in tenors longer than a few years – has come from real yields, and not inflation expectations, suggesting tighter policy from here on out.
There is a strong argument to be made that if aggregate demand in the economy stays strong, the labor market remains robust, and inflation doesn’t retreat (or even accelerates), then rates could rise. Our view is that we’re not there yet. We still think there will be some softening in the economy as we head into summer, making it a difficult choice for the Fed. Should the conflict wind down and the Straits of Hormuz reopen, we could see a lot of the expected tightening start to recede.
As our readers will be well aware, we had previously expected something in the Middle East to give by midsummer, but the current facts on the ground offer us extremely low visibility of that happening. While we understand current hawkish market pricing, we remain unconvinced that hikes will actually materialize. To be sure, we expect a more hawkish FOMC next Wednesday, supported by what we expect to be high CPI and PPI inflation prints later this week, and perhaps even further repricing for higher rates. Ultimately, however, we expect macro fundamentals to come back to earth over the next few months and the rate hike pressure to subside.