FOMC Preview: New Chair, big plans
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
iFlow > Short Thoughts
Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.
John Velis, David Tam
Time to Read: 4 minutes
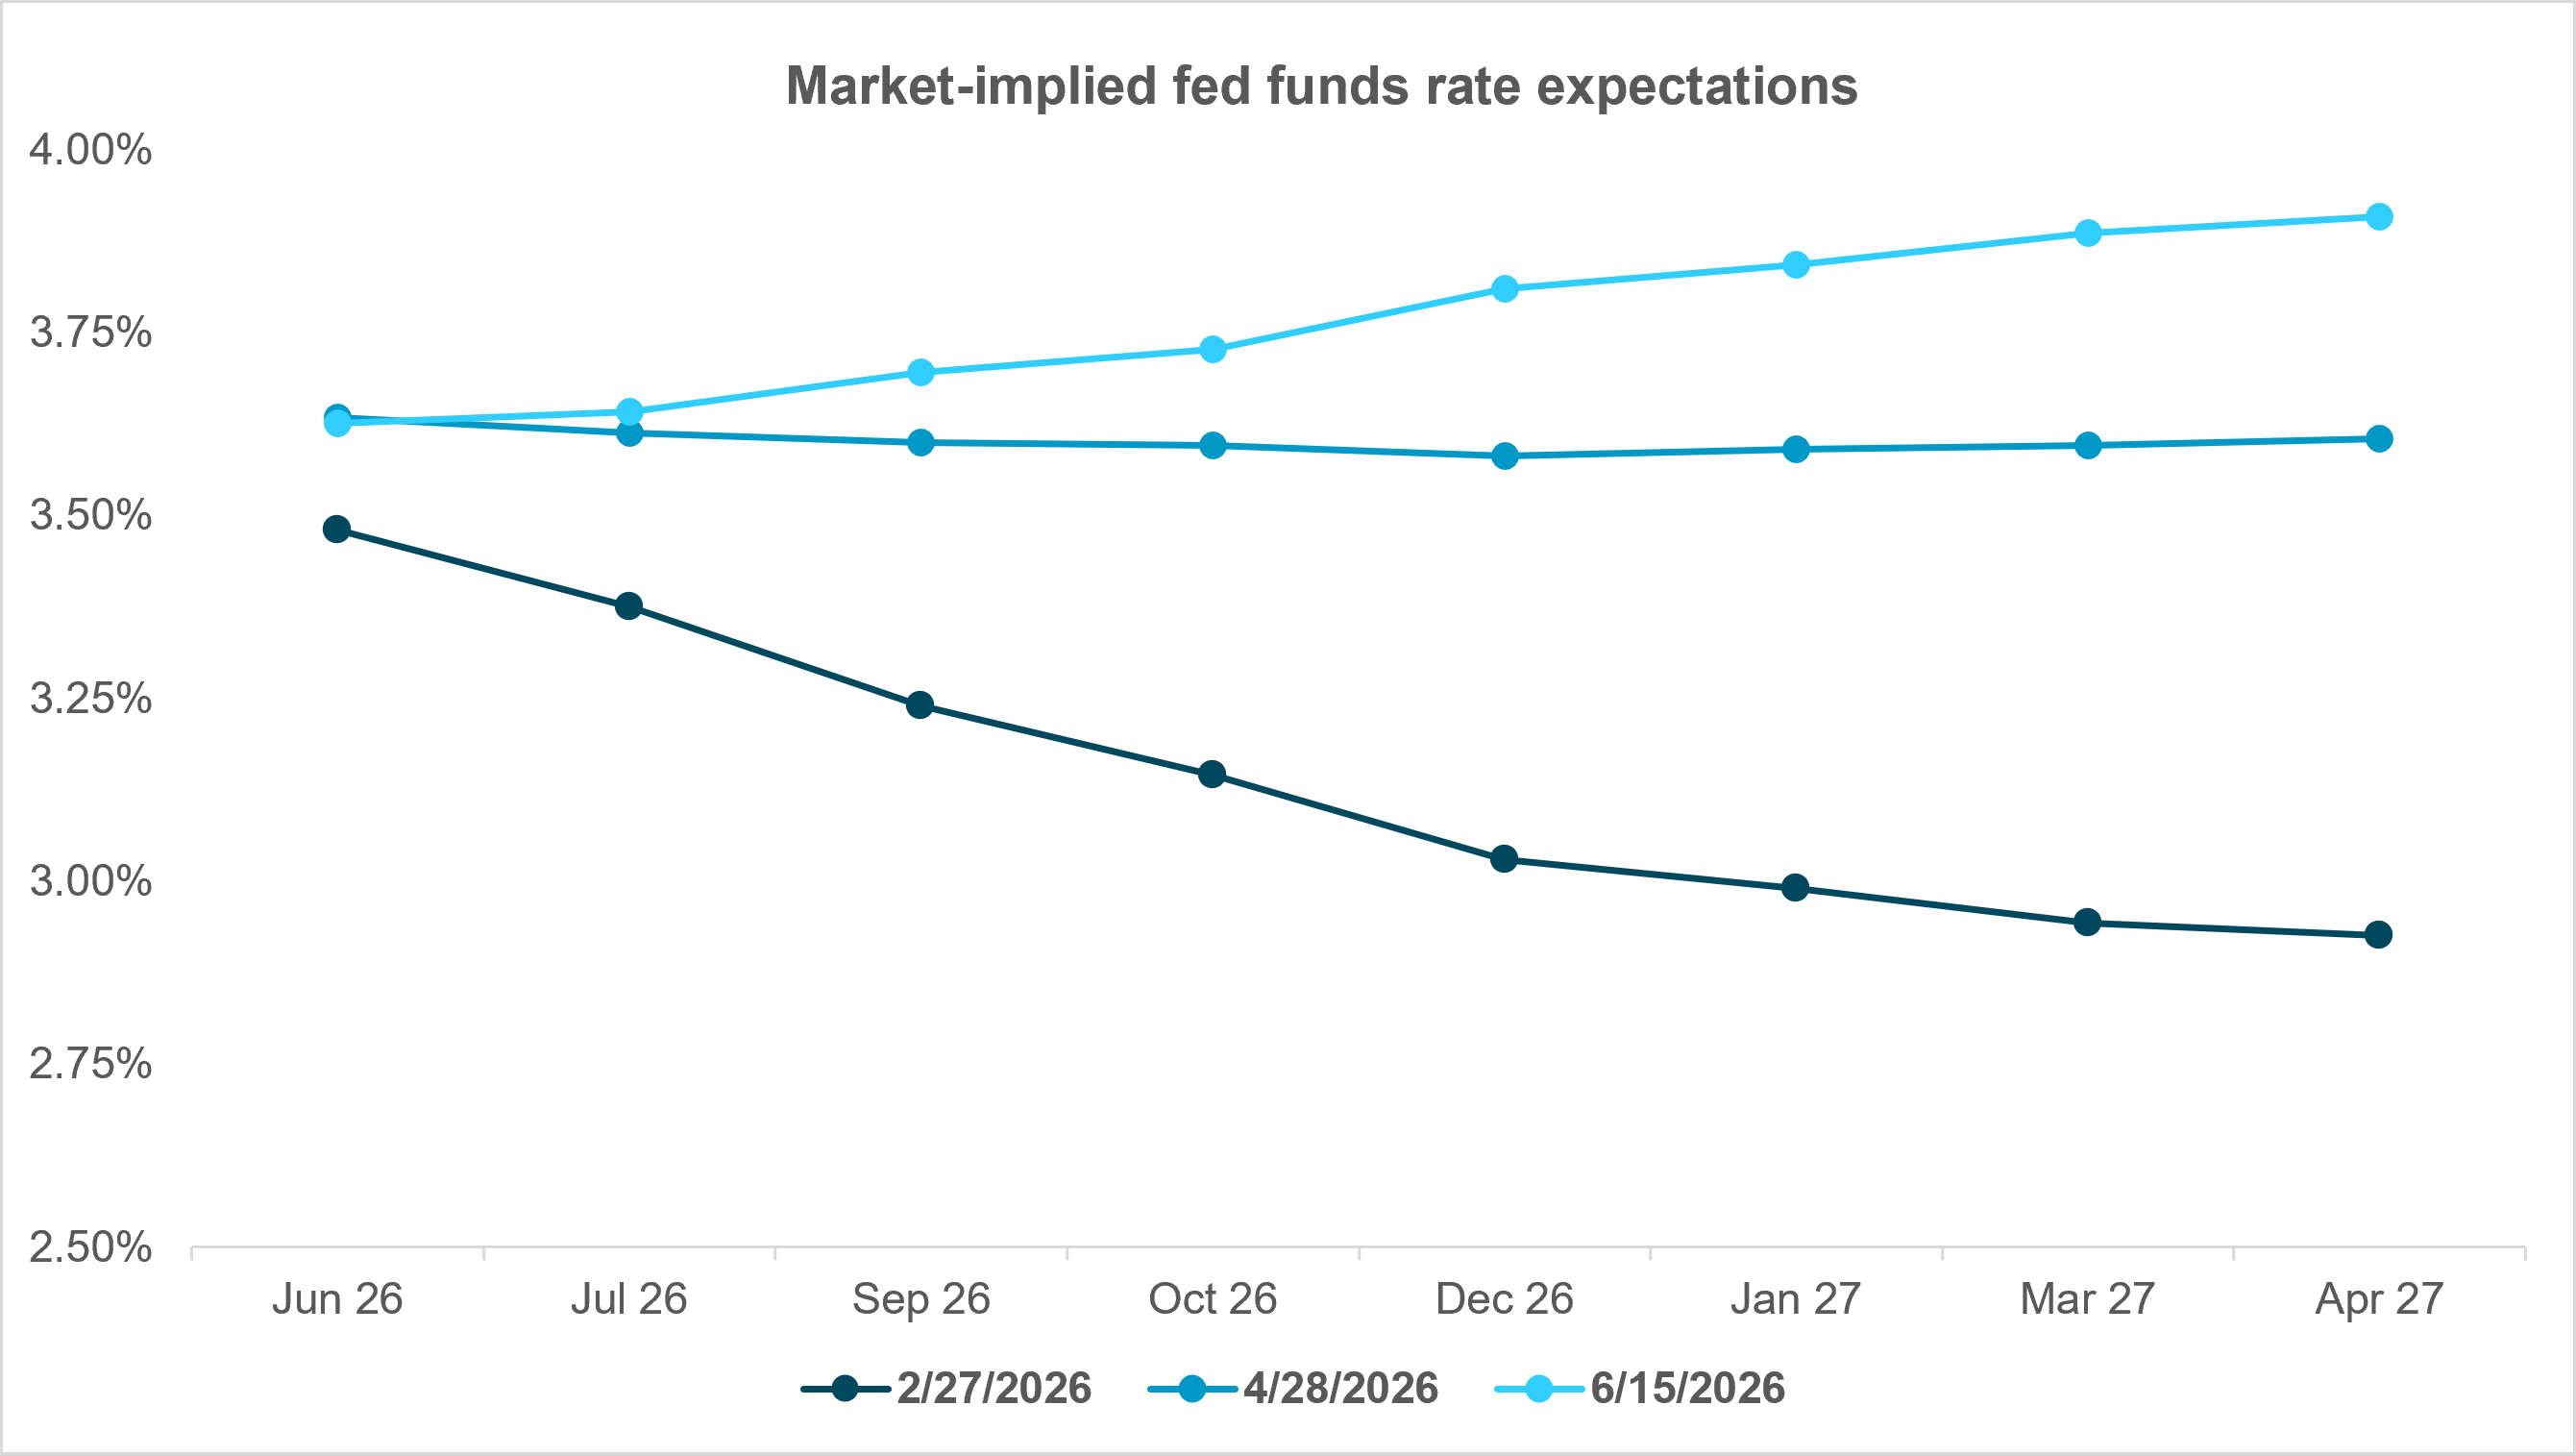
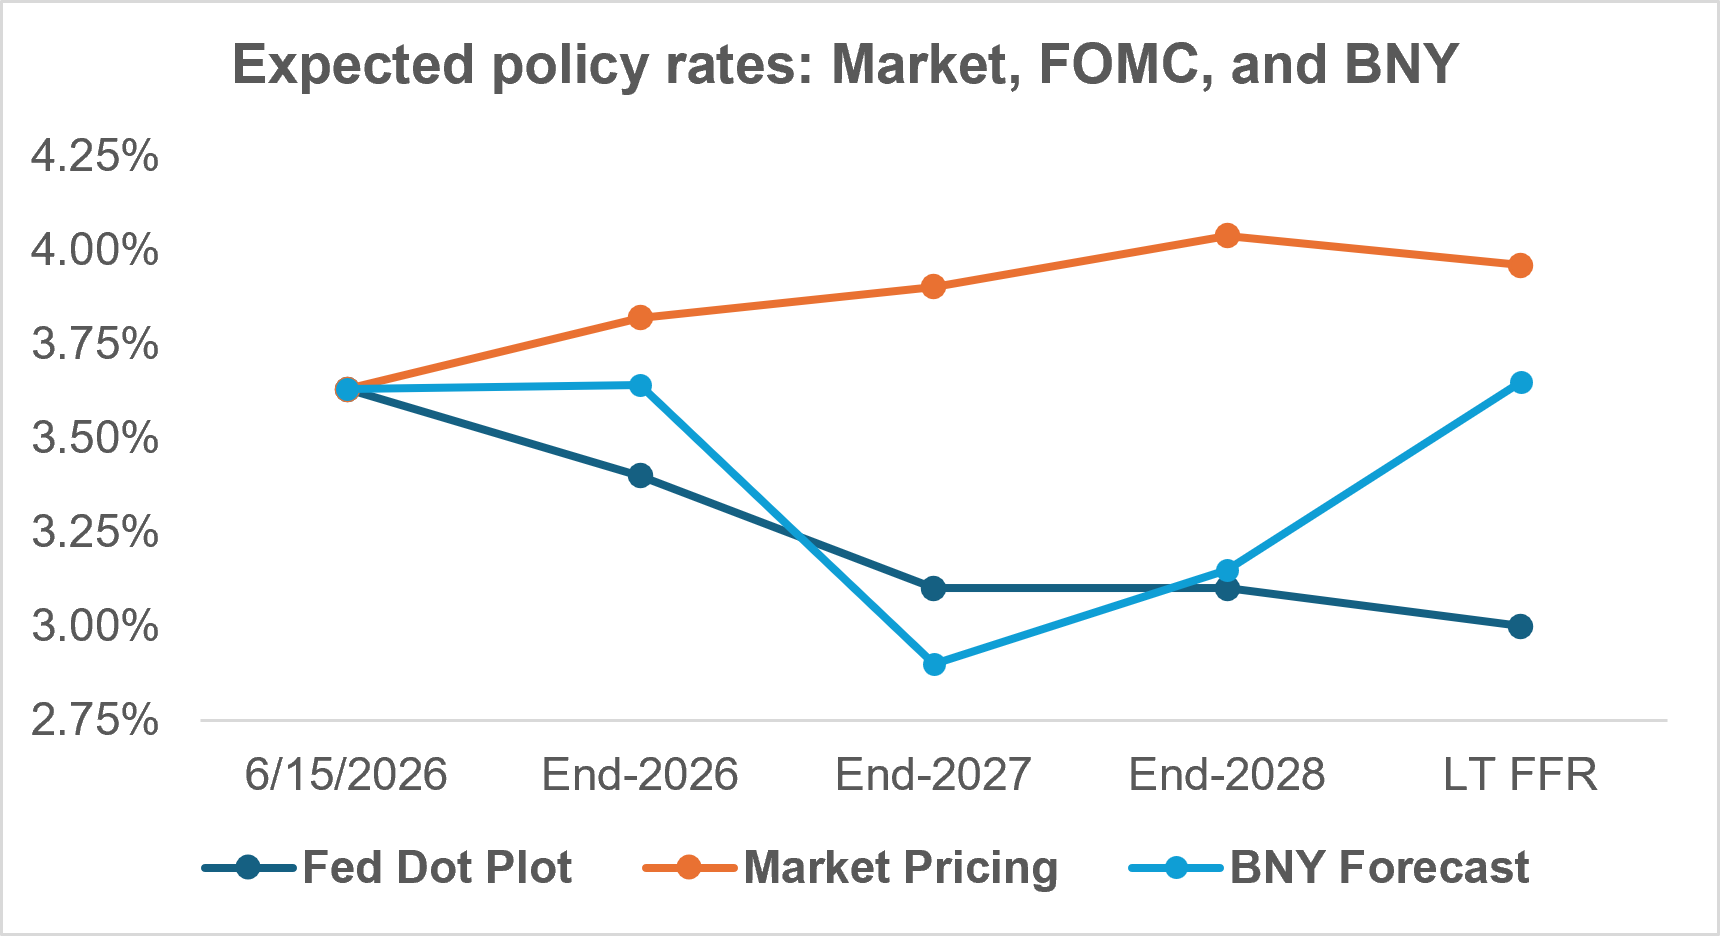
EXHIBIT #1: MODEST TIGHTENING CYCLE EXPECTED
Source: BNY Markets, Bloomberg
Incoming Federal Reserve Chair Kevin Warsh presides over the first FOMC meeting of his tenure this week, a debut that promises plenty of intrigue. Monetary policy over the next few months is an immediate concern, and the announced memorandum of understanding (MOU) between the U.S. and Iran is a potential new consideration. Beyond the immediate monetary policy decision, numerous questions remain as Warsh’s chairmanship commences.
Let’s address the monetary policy decision first. We’ll go into greater detail below in our rate outlook and the macroeconomic setup going into the second half of the year. In short, we expect the upcoming FOMC statement to indicate a clear two-way risk to rates over the short term, in line with the three hawkish dissents from the previous FOMC at the end of April. A new Summary of Economic Projections (SEP, or the dot plot) will be released, and we expect the median projection for end-2026 to eliminate the single cut that had been present for several cycles. How wide-ranging the press conference will be under the new Chair remains to be seen. He has mentioned ambitious changes he’d like to see at the central bank, including a less communicative Fed.
For starters, we know that Warsh is no fan of forward guidance, saying in his Senate confirmation hearing that “unlike many of my colleagues past and present, I don’t believe in forward guidance … I don’t believe that I should be previewing for you what a future decision might be.” This may very well mark an eventual end to the dot plot era and likely means we won’t get much information from Warsh’s press conference.
The fate of the post-FOMC meeting press conference itself could also come into question. Ben Bernanke introduced the practice in 2011, initially quarterly, coinciding with dot plot releases; Jerome Powell expanded it to every meeting in 2019. We may very well see press conferences become more infrequent or even eliminated altogether. How much impact the new Chair can have on the communications of other Committee members is an open question, but expect communications policy to come under significant review, resulting in a much more reticent central bank.
Warsh has also outlined a number of ambitious changes he intends to pursue, though without a great deal of detail. His areas of focus include the size of the Fed’s balance sheet – as discussed here and here – the structure of the Federal Reserve System itself, and relations between the Treasury Department and the central bank.
While we expect more clarity on Wednesday about Warsh’s plans to reform the Fed, one early sign could be some of his staffing choices. In particular, Warsh’s naming of Paul Winfree and Daniel Heil as interim advisors has garnered some attention. Heil is a former colleague of Warsh’s at Stanford’s Hoover Institution. Winfree, a former official in the first Trump administration, is perhaps best known as the lead author of the chapter on the Fed in the 2025 Mandate for Leadership, colloquially known as “Project 2025.”
The chapter provides a forceful critique of the modern Fed, arguing that it has amassed too much discretionary power, undermining its own political independence and monetary stability. Winfree criticizes the Fed’s current framework, arguing that it contributes to inflation – which he blames on the Fed’s dual mandate – along with moral hazard and boom-and-bust cycles caused by the Fed’s lender of last resort function. To this end, the chapter argues that the dual mandate should be eliminated in favor of a singular focus on inflation control. Similarly, the lender of last resort should be limited to encourage more prudent risk-taking in the financial system.
This is an ambitious agenda, and Warsh’s choice of Winfree and Heil indicates the seriousness with which he intends to pursue those ambitions. Many of the Project 2025 recommendations regarding the Fed haven’t been debated publicly to any degree, and we don’t think the press conference after this upcoming meeting will provide the venue for their airing. But we’ll be watching this first Warsh FOMC for a read on his style, preferences and orientation.
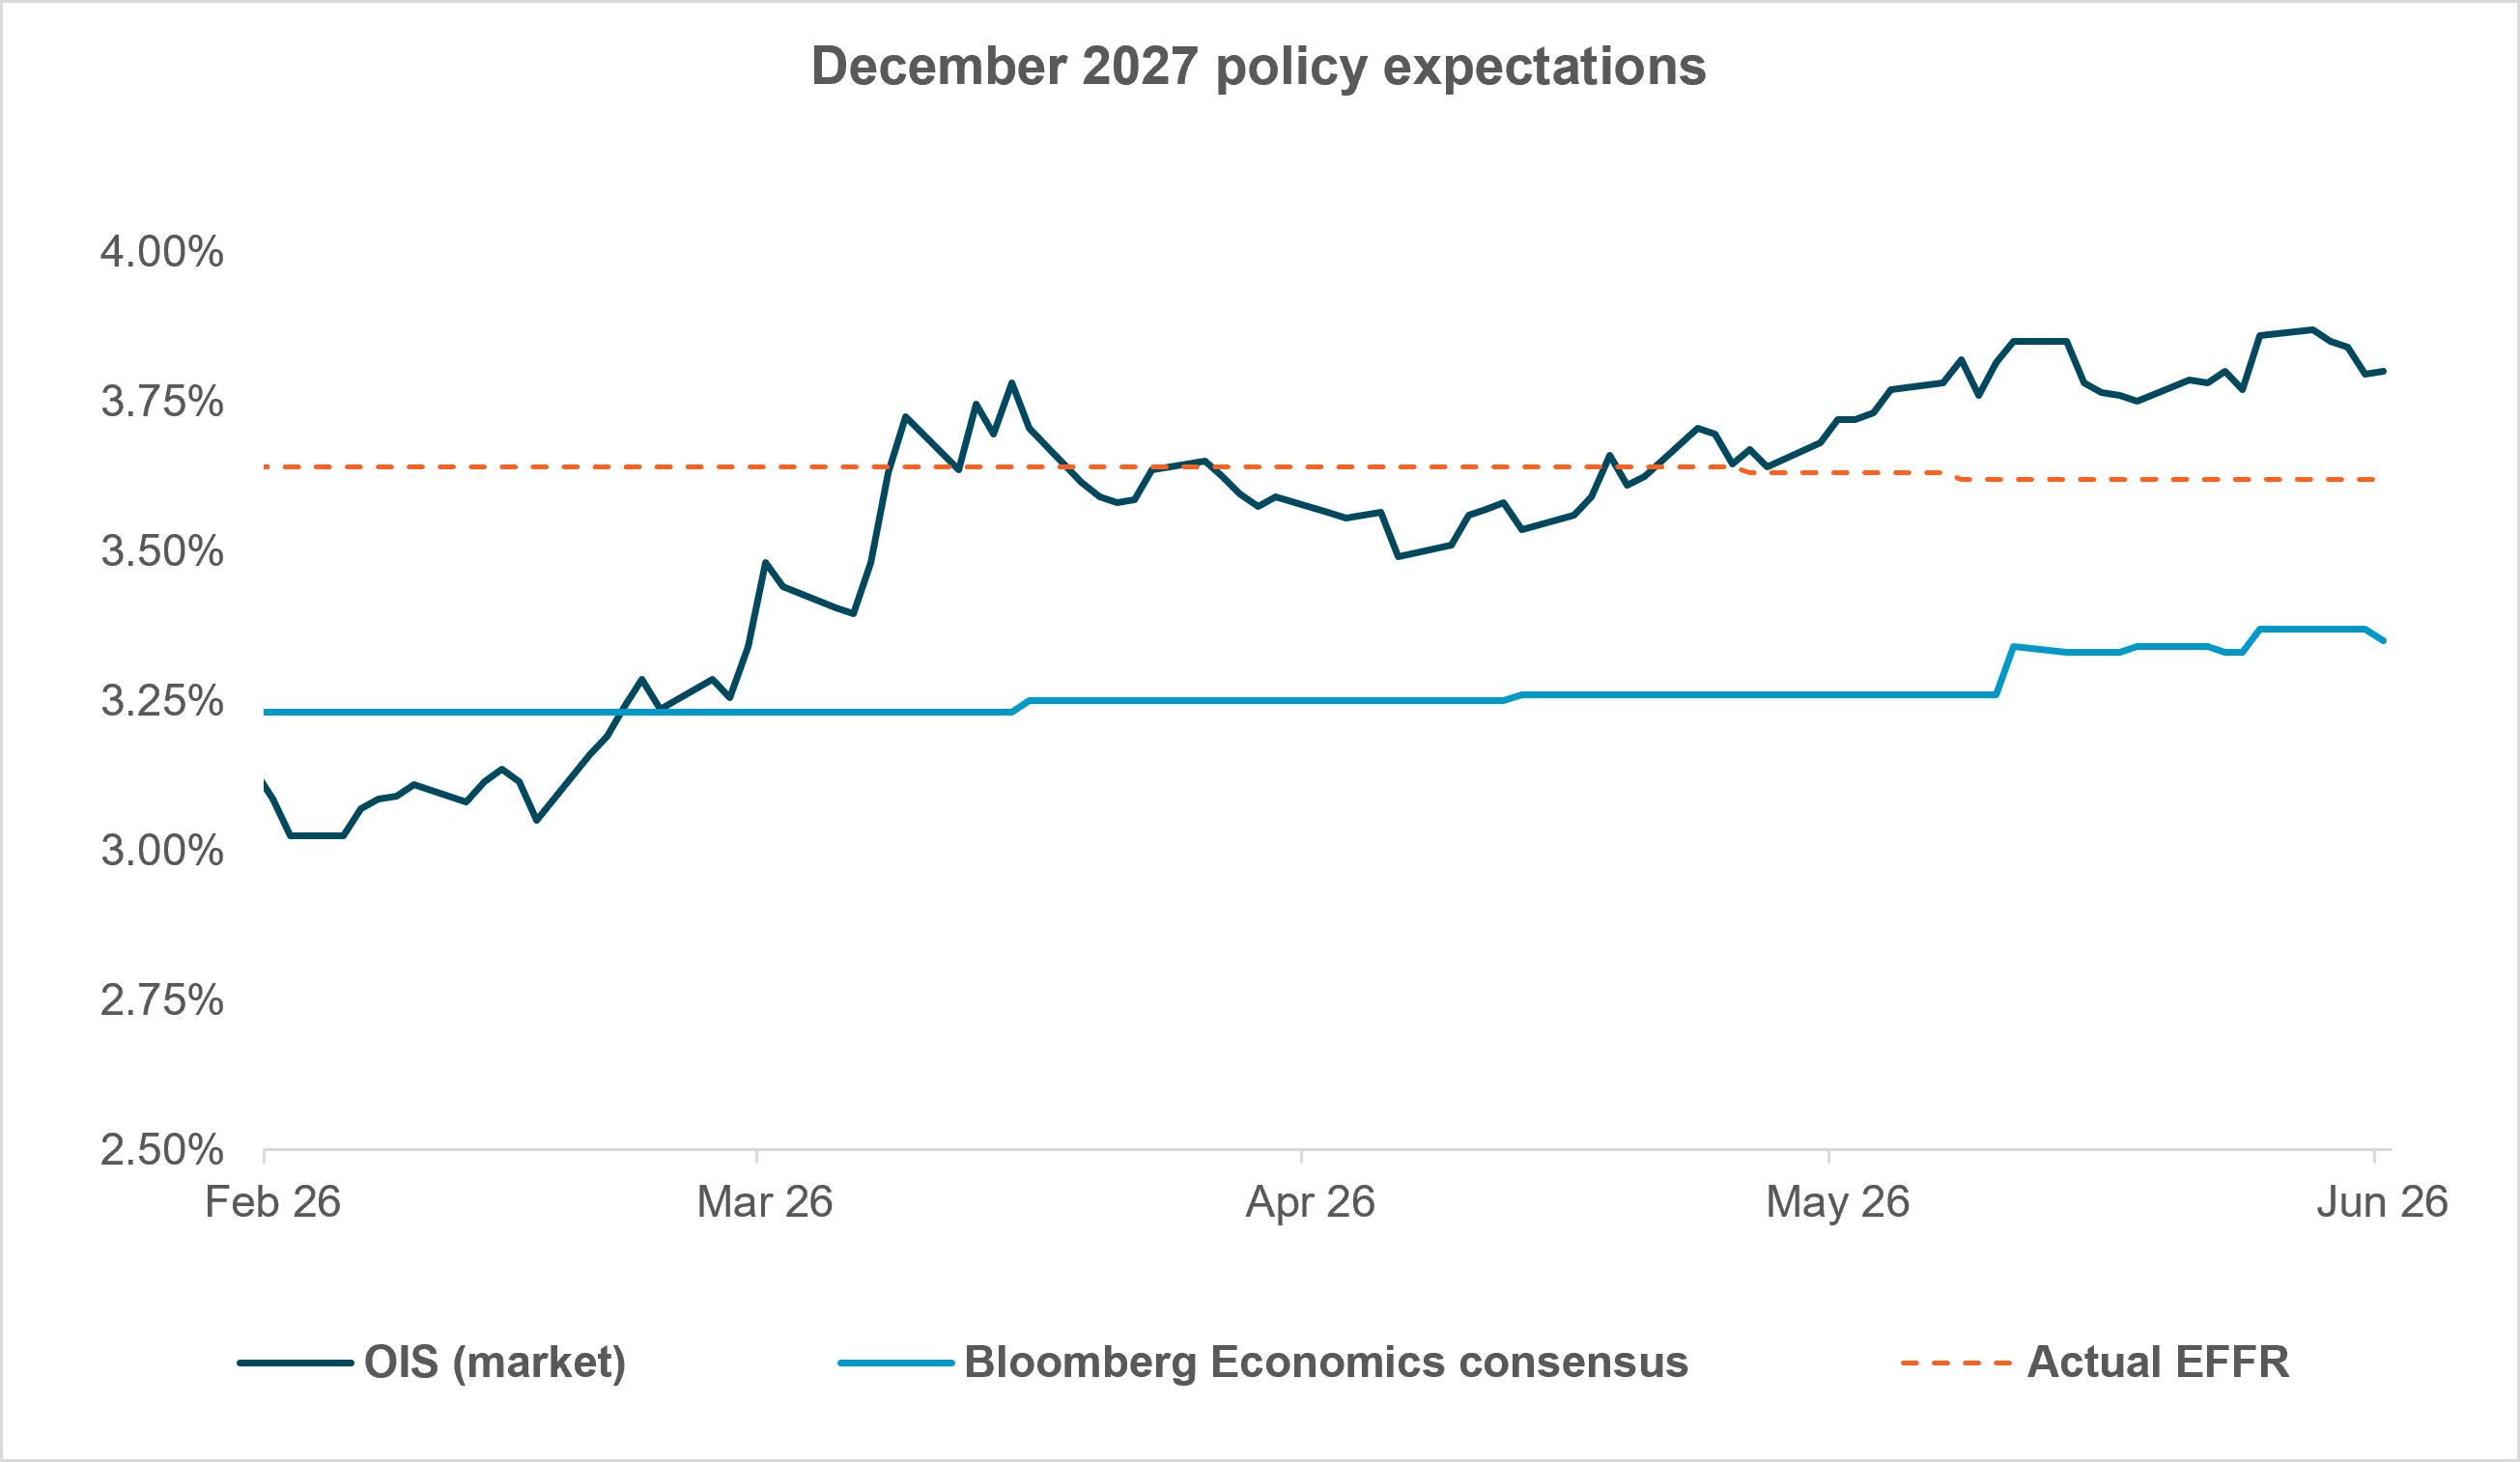
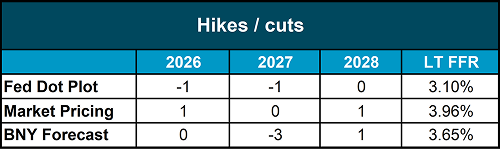
EXHIBIT #2: ECONOMISTS VS. THE MARKET – RATE HIKES OR CUTS IN 2027
Source: BNY Markets, Bloomberg
Before hostilities commenced on February 28, DEC26 futures were implying about 60bp in cuts. Following the MOU announcement, markets have seen some relief – oil prices have retreated significantly – but rates markets seem to be withholding judgment. Yields are off just slightly as we write – coupon yields across the curve are only modestly lower – and OIS-implied policy rates still show 18bp of hiking by the December 2026 meeting. If the MOU sticks, and the Strait of Hormuz reliably and sustainably reopens to shipping traffic, the decline in near-month oil futures should be sustained and could fall further. That might be too much to expect, as macroeconomic conditions have solidified and several FOMC members have become more hawkish, pointing to inflation risk and labor market robustness.
Until we changed our outlook, we had argued that if the Strait of Hormuz were to reopen this summer, the Fed would cut rates twice in Q4 this year. We changed our call given lack of visibility on the geopolitics, the change in orientation of several key Fed speakers, and the evolution of U.S. macro data (strong labor market performance, rising inflation). We now expect no policy action in either direction this year, conditional on the macroeconomy’s evolution. For rate cuts to come back on the agenda, the economy would have to display measurable slowing – something we don’t rule out but isn’t apparent in the data.
We don’t expect much light to be shed on this question Wednesday, given Warsh’s dim view of forward guidance. However, a description of the Fed’s reaction function – what might prompt cuts, a hold or hikes – isn’t out of the question. Exhibit 2 shows what we call “economists vs. the market.” As we have highlighted, the market is still expecting tighter policy, while economists persist in forecasting lower rates (according to the Bloomberg consensus forecasts) in 2027. Unsurprisingly, we line up with the economists. While the post-conflict economy reveals itself, we wouldn’t count on much guidance from the Warsh Fed.