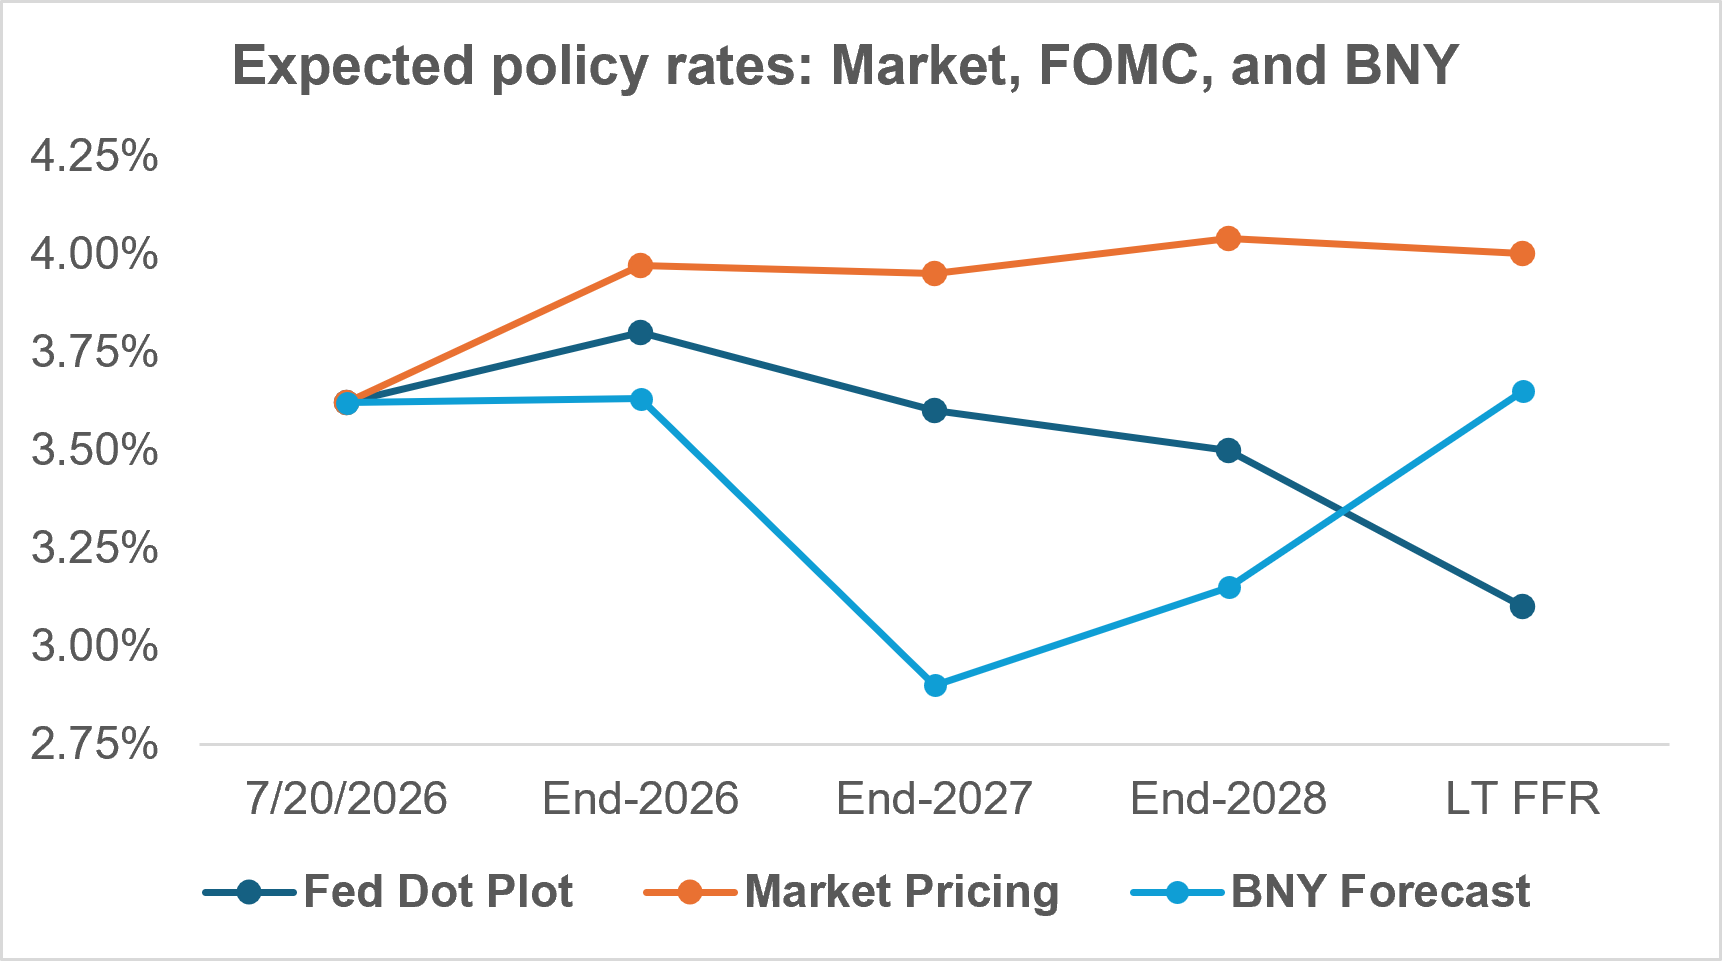
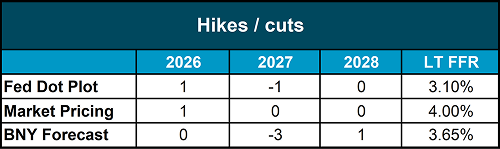
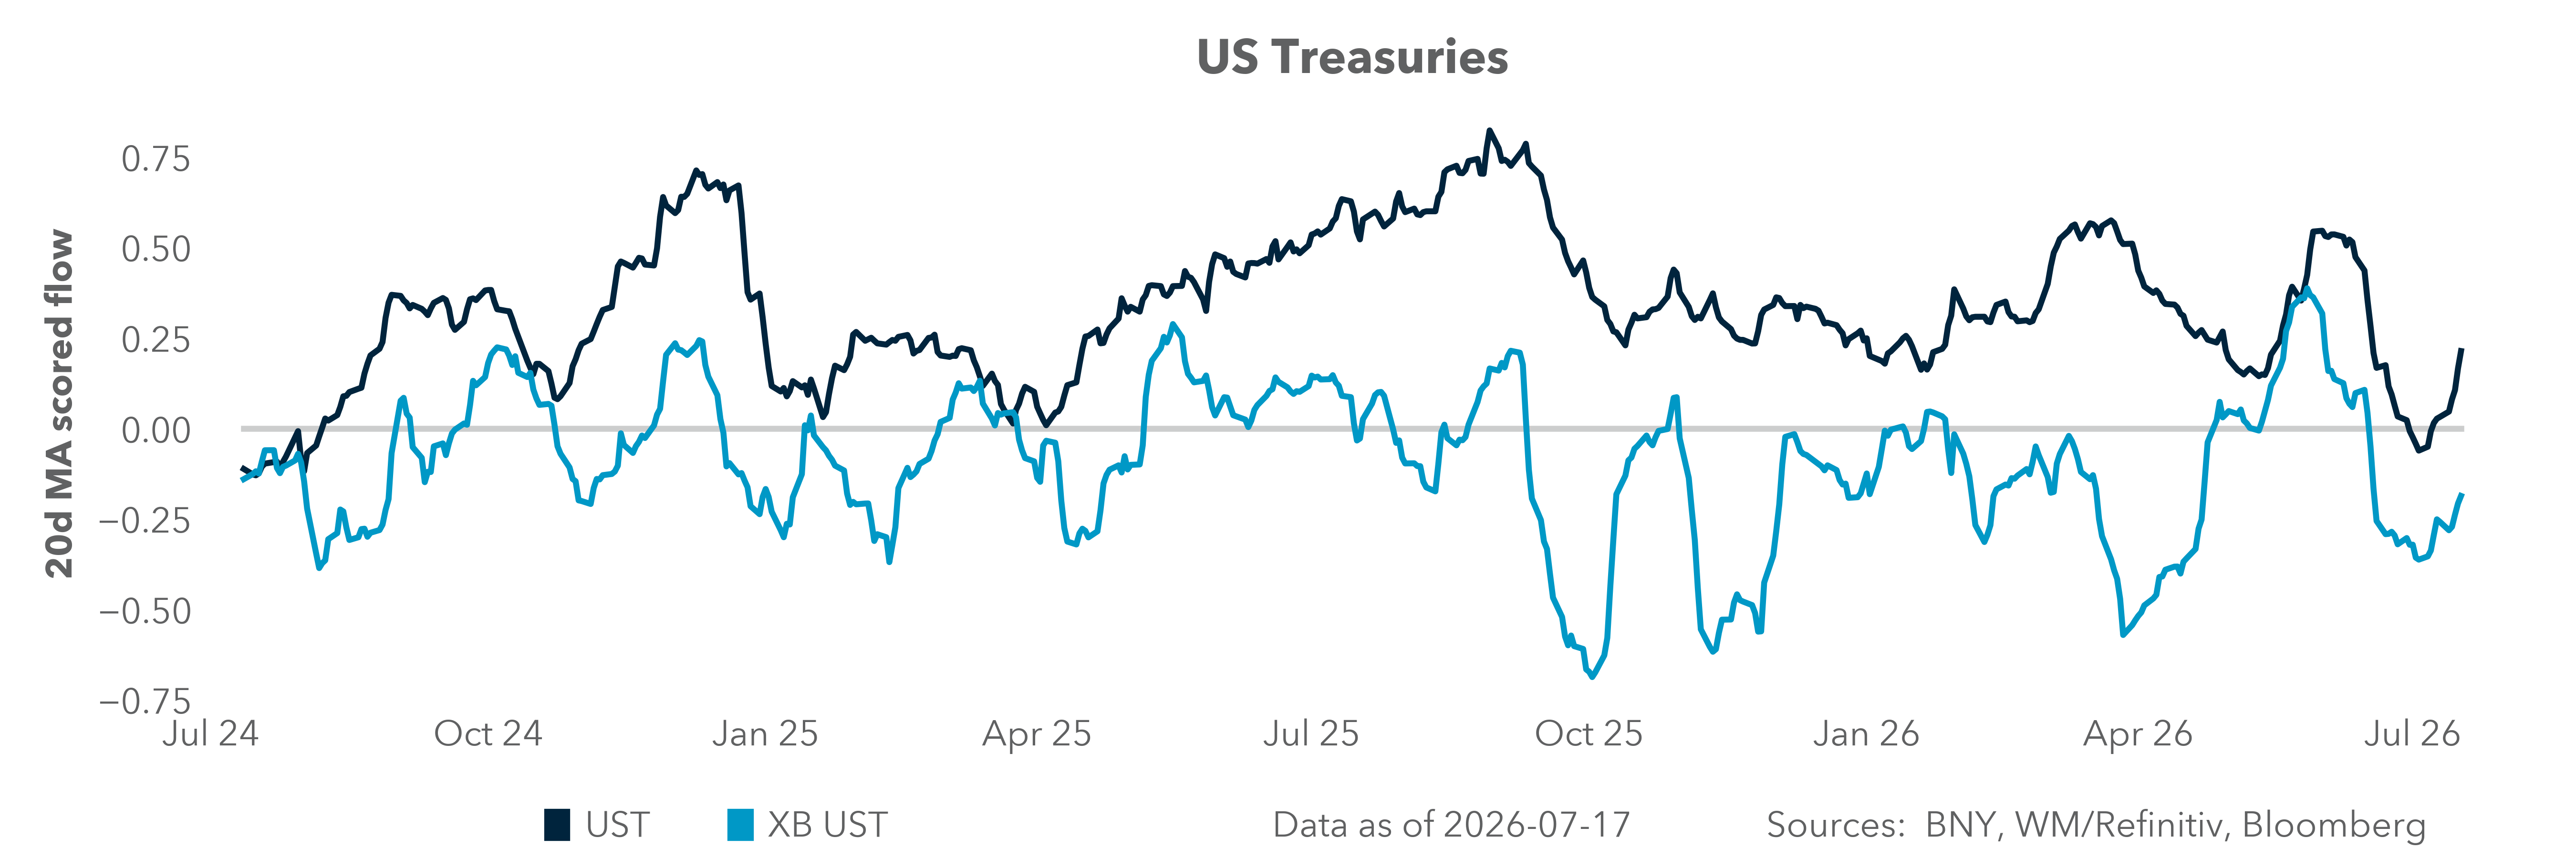
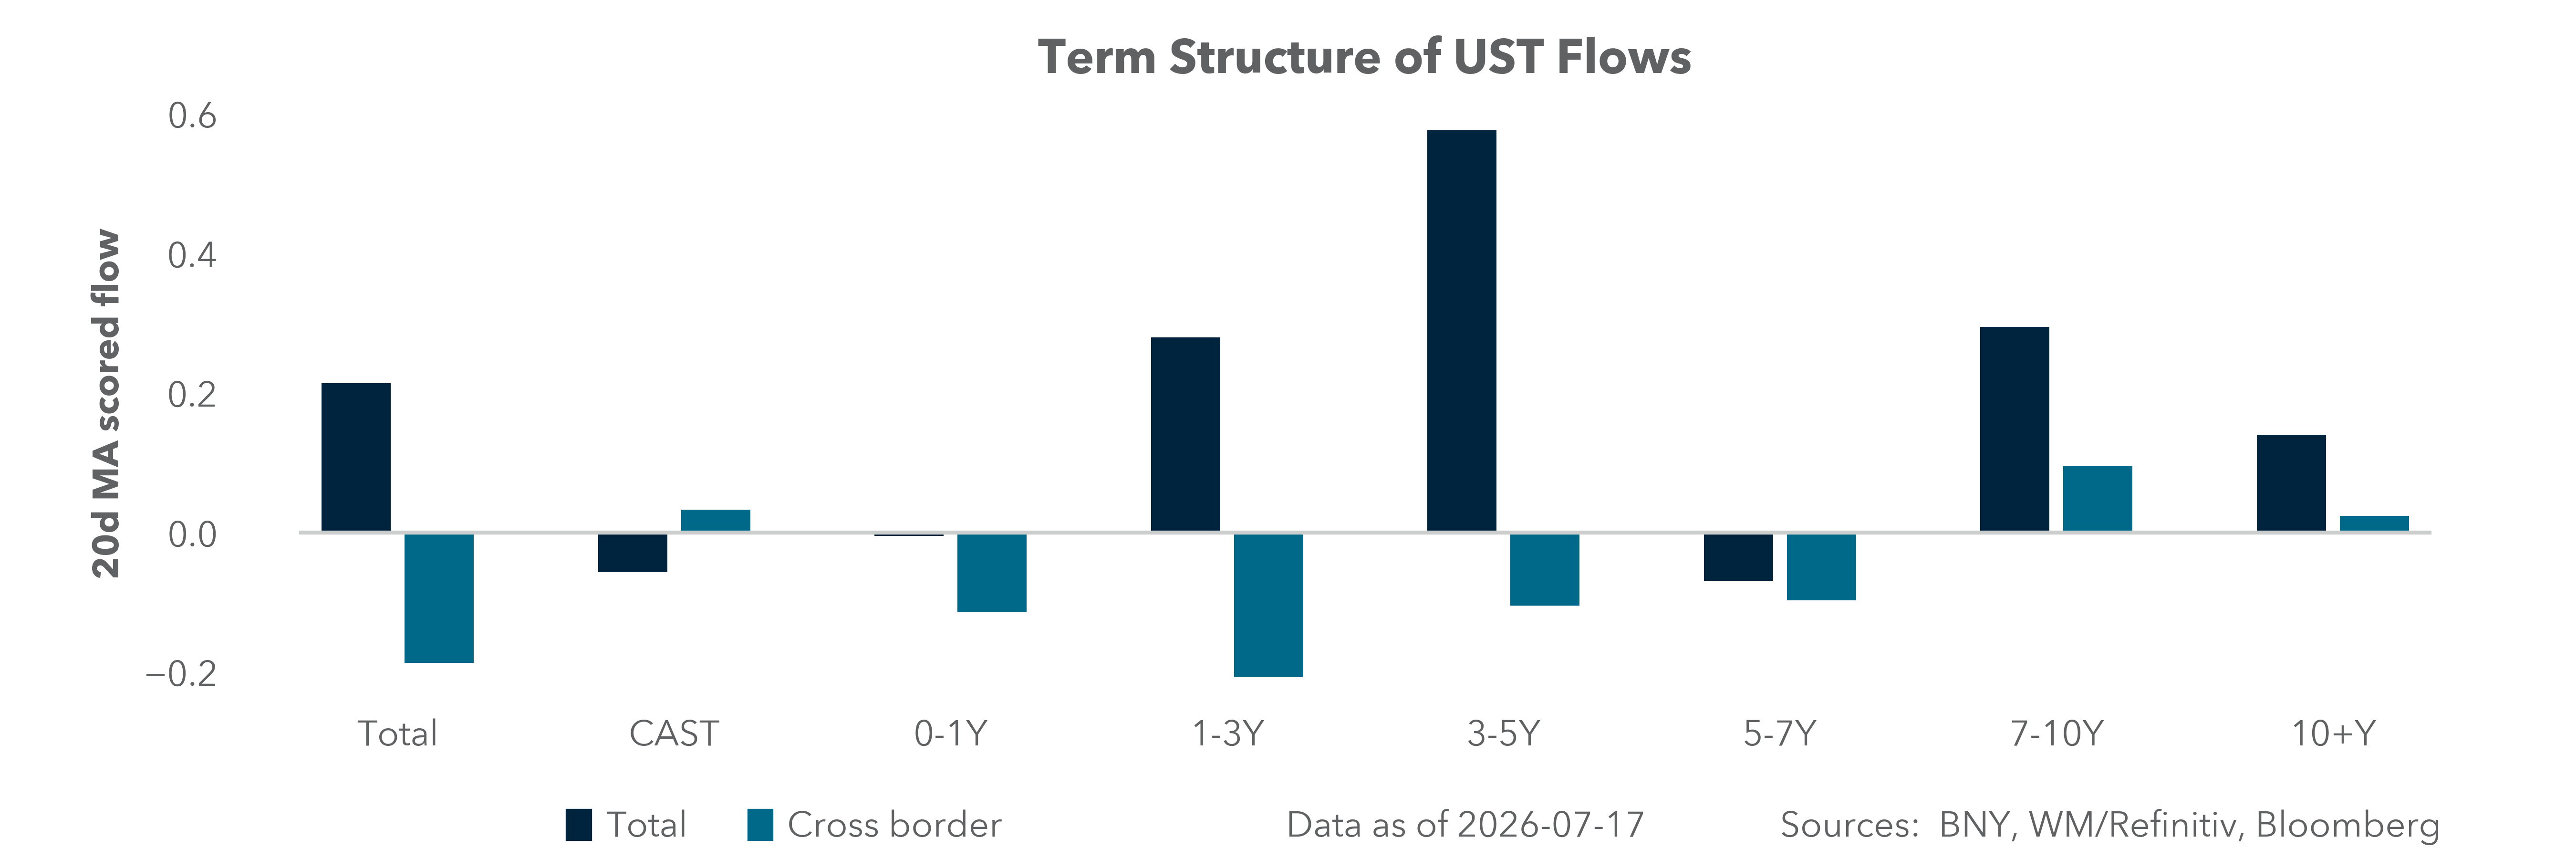
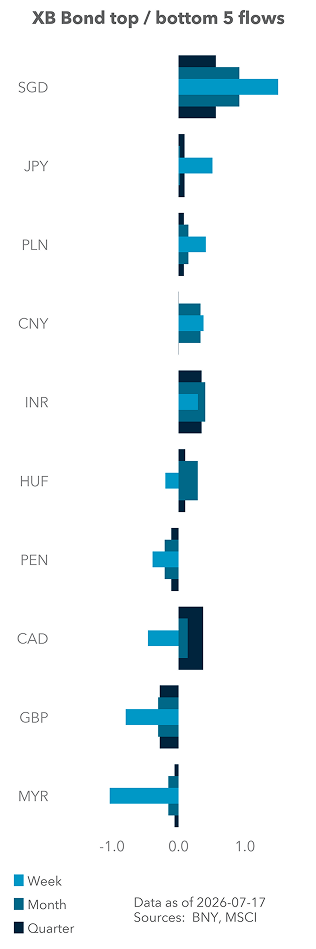
Last week was eventful regarding the rates outlook, with both hawkish and dovish developments. Nevertheless, we maintain our call for no changes to rates this year, although we acknowledge upside risk to this view. Ahead of the July FOMC next week, the probability of a hike priced by the market peaked around 40% a week ago and has since fallen to below 20%. By December, cumulative meeting probabilities still imply nearly 1.5. The forward curve has been volatile lately, so we expect more twists and turns in market expectations, especially with increasingly sparse forward guidance coming out of the Committee; increased front volatility is the natural result of this development.
Warsh delivered his first semiannual testimony to each branch of Congress, and while prescriptive remarks were largely absent, he reiterated on several occasions that the Fed would unequivocally hit its 2% inflation target.
June CPI and PPI were released last week and were both lower than expected, indicating that the U.S.–Iran memorandum of understanding had brought down oil prices and, with them, inflation. However, a resumption of hostilities at the end of the week raised the specter of a second energy shock in coming months.
Finally, several Fed speakers delivered hawkish messages, despite the CPI/PPI relief, signaling that inflation remains the main risk to the outlook. Dallas Fed President Lorie Logan even argued that rates should rise.
Taking these developments on balance, especially the impact of a second energy shock, the rates outlook is indeed trickier and will ultimately be determined by the inflation data. We remain watchful for another bout of higher prices and aren’t certain the Fed would view it as sufficient cause to raise rates. We’re actively reviewing our rates outlook, but for now maintain the no-change view. We note with surprise that Brent oil is still trading below $90 per barrel and the first oil shock earlier this year saw limited, though measurable, inflation pass-through. With rates, as with much of the market, geopolitics and the economy’s reaction to them will be the ultimate arbiter of where rates will go.