Fed Communications task force: back to the old world?

iFlow > Short Thoughts

Published on Tuesdays, Short Thoughts offers perspectives on US funding markets, short-term Treasuries, bank reserves and deposits, and the Federal Reserve's policy and facilities.

Subscribe to Our Publications

In order to start receiving iFlow, please fill out the form below.

Subscribe
arrow_forward
BNY iFlow Short Thoughts,BNY iFlow Short Thoughts

Key Highlights

  • New Fed task force leaders represent a broad mix of experience and views.
  • King, Fraga, Fisher are all skeptics of the dots and forward guidance.
  • Explaining how the FOMC works differs from telling us what it plans to do.

Tasking the task forces

EXHIBIT #1: FRONT-END VOLS SUPPRESSED AT ZERO LOWER BOUND

Source: BNY Markets, Bloomberg

Last Thursday, the Federal Reserve announced five task force leaders who include some intriguing names from academia, industry, and policymaking backgrounds. Their paper trails reveal a variety of views on the issues the working groups will address, and it’s difficult to infer any obvious partisan leanings from the group as a whole. For example, the Balance Sheet Policy task force includes Karen Dynan and Jeremy Stein, who were appointed to policymaking roles by President Barack Obama.

Not all of the task force leaders are closely involved in monetary policy per se, however, reflecting how broadly the task forces could reshape the way the Fed thinks about the economy. The Productivity and Jobs task force leaders – Marc Andreessen, a venture capitalist, Charles Jones, an academic on leave at Anthropic, and Asha Sharma, an executive at Microsoft – will quite possibly reflect Silicon Valley perspectives more than the traditional academic, Beltway or Wall Street perspectives the Fed draws from the most.

We don’t intend to draw conclusions about the task forces’ work solely from a forensic examination of their leaders’ stated views. At a high level, we think that the wide-ranging and diverse composition of the appointees could make the task force recommendations more palatable and likely to be constructively received by FOMC members as well as the market. Moreover, we don’t think the task force reports should be considered foregone conclusions – surprises could result.

With the leadership in place, we expect the volume of news around task force work to pick up. We will continue to be attentive to any appointments, research output, or findings that impact the Fed’s monetary policy implementation framework or understanding of the economy.

Over the next several weeks, we’ll examine each task force, their leadership, and the issues they’re likely to consider. Today, we’ll focus on the Communications workstream, something Chair Kevin Warsh has been very vocal about (see here and here), as evidenced by the abbreviated nature of the June policy statement and post-FOMC press conference.

Forward guidance and the dots vs. the reaction function

The Communications task force will be headed by former Bank of England (BOE) Governor Mervyn King, former Central Bank of Brazil Governor Arminio Fraga, and Peter Fisher, a BlackRock managing director with decades of Fed and U.S. Treasury experience. 

Specific considerations around Fed communications would include the future of the Summary of Economic Projections (SEP), or the dots, as well as forward guidance more generally. As the task forces kick off, much early discussion – including public comments last week from Fed Governor Christopher Waller – has centered upon the question of the Fed’s “reaction function.” How does it set policy in light of its dual mandate and (potentially) competing goals? Under which macroeconomic conditions would it lean toward the inflation vs. the employment mandate?

It has been argued lately that less guidance will lead to higher rates volatility as the market is left to its own devices in forming policy expectations. With less information for it to digest, market pricing could become much more volatile. Exhibit 1 shows the volatility (one-month rolling standard deviation) of the 2y Treasury note yield since the middle of the 1990s, back when central banks were notably reticent – indeed, the Fed didn’t even announce changes in the policy rate until 1994. It appears that rates vol was elevated through the 1990s and into the mid-2000s, spiking, not surprisingly, when the policy rate was moving either up or down. The same pattern held in the few years after the pandemic. It seems to us that rates at or near zero – accompanied by forward guidance pledging rates would stay low for an extended period – led to extraordinarily low volatility. Is this due to their level or the forward guidance around the zero lower bound? With rates now appreciably above zero and a few easing cycles after COVID, rates volatility has returned to something like 1990s levels. Is this a bad thing? 

Former BOE Governor King, for his part, has been explicitly critical of forward guidance, recommending in a recent paper to “abandon forward guidance,” calling it a “dangerous game.” He argues that “private sector expectations of future policy rates derive from the combination of a forecast of the economy and the central bank reaction function. There is no reason to assume that the private sector has the same view of the future path of the economy as the central bank.” This doesn’t mean that the central bank should offer no guidance or information, but rather emphasize and characterize the level of (probabilistic) uncertainty around expected outcomes. Don’t forget the BOE was one of the first central banks to produce a regular Monetary Policy Report (initially dubbed the Inflation Report), which famously included “fan charts” of the distribution of outcomes around a point forecast for key macroeconomic variables.

Arminio Fraga, who has a long career as an investor, brings an emerging markets and market practitioner perspective to the Committee, as well as his own experience as a central banker. As Governor of the Central Bank of Brazil, Fraga introduced an Inflation Report in 1999 (now the Monetary Policy Report), modeled on the BOE’s approach. He is in general an advocate of central bank transparency, albeit something short of the dots and explicit forward guidance. 

Peter Fisher – who served in the U.S. Treasury under George W. Bush and headed the New York Fed’s Open Market Desk in addition to his time in the private sector – has argued against forward guidance as well.

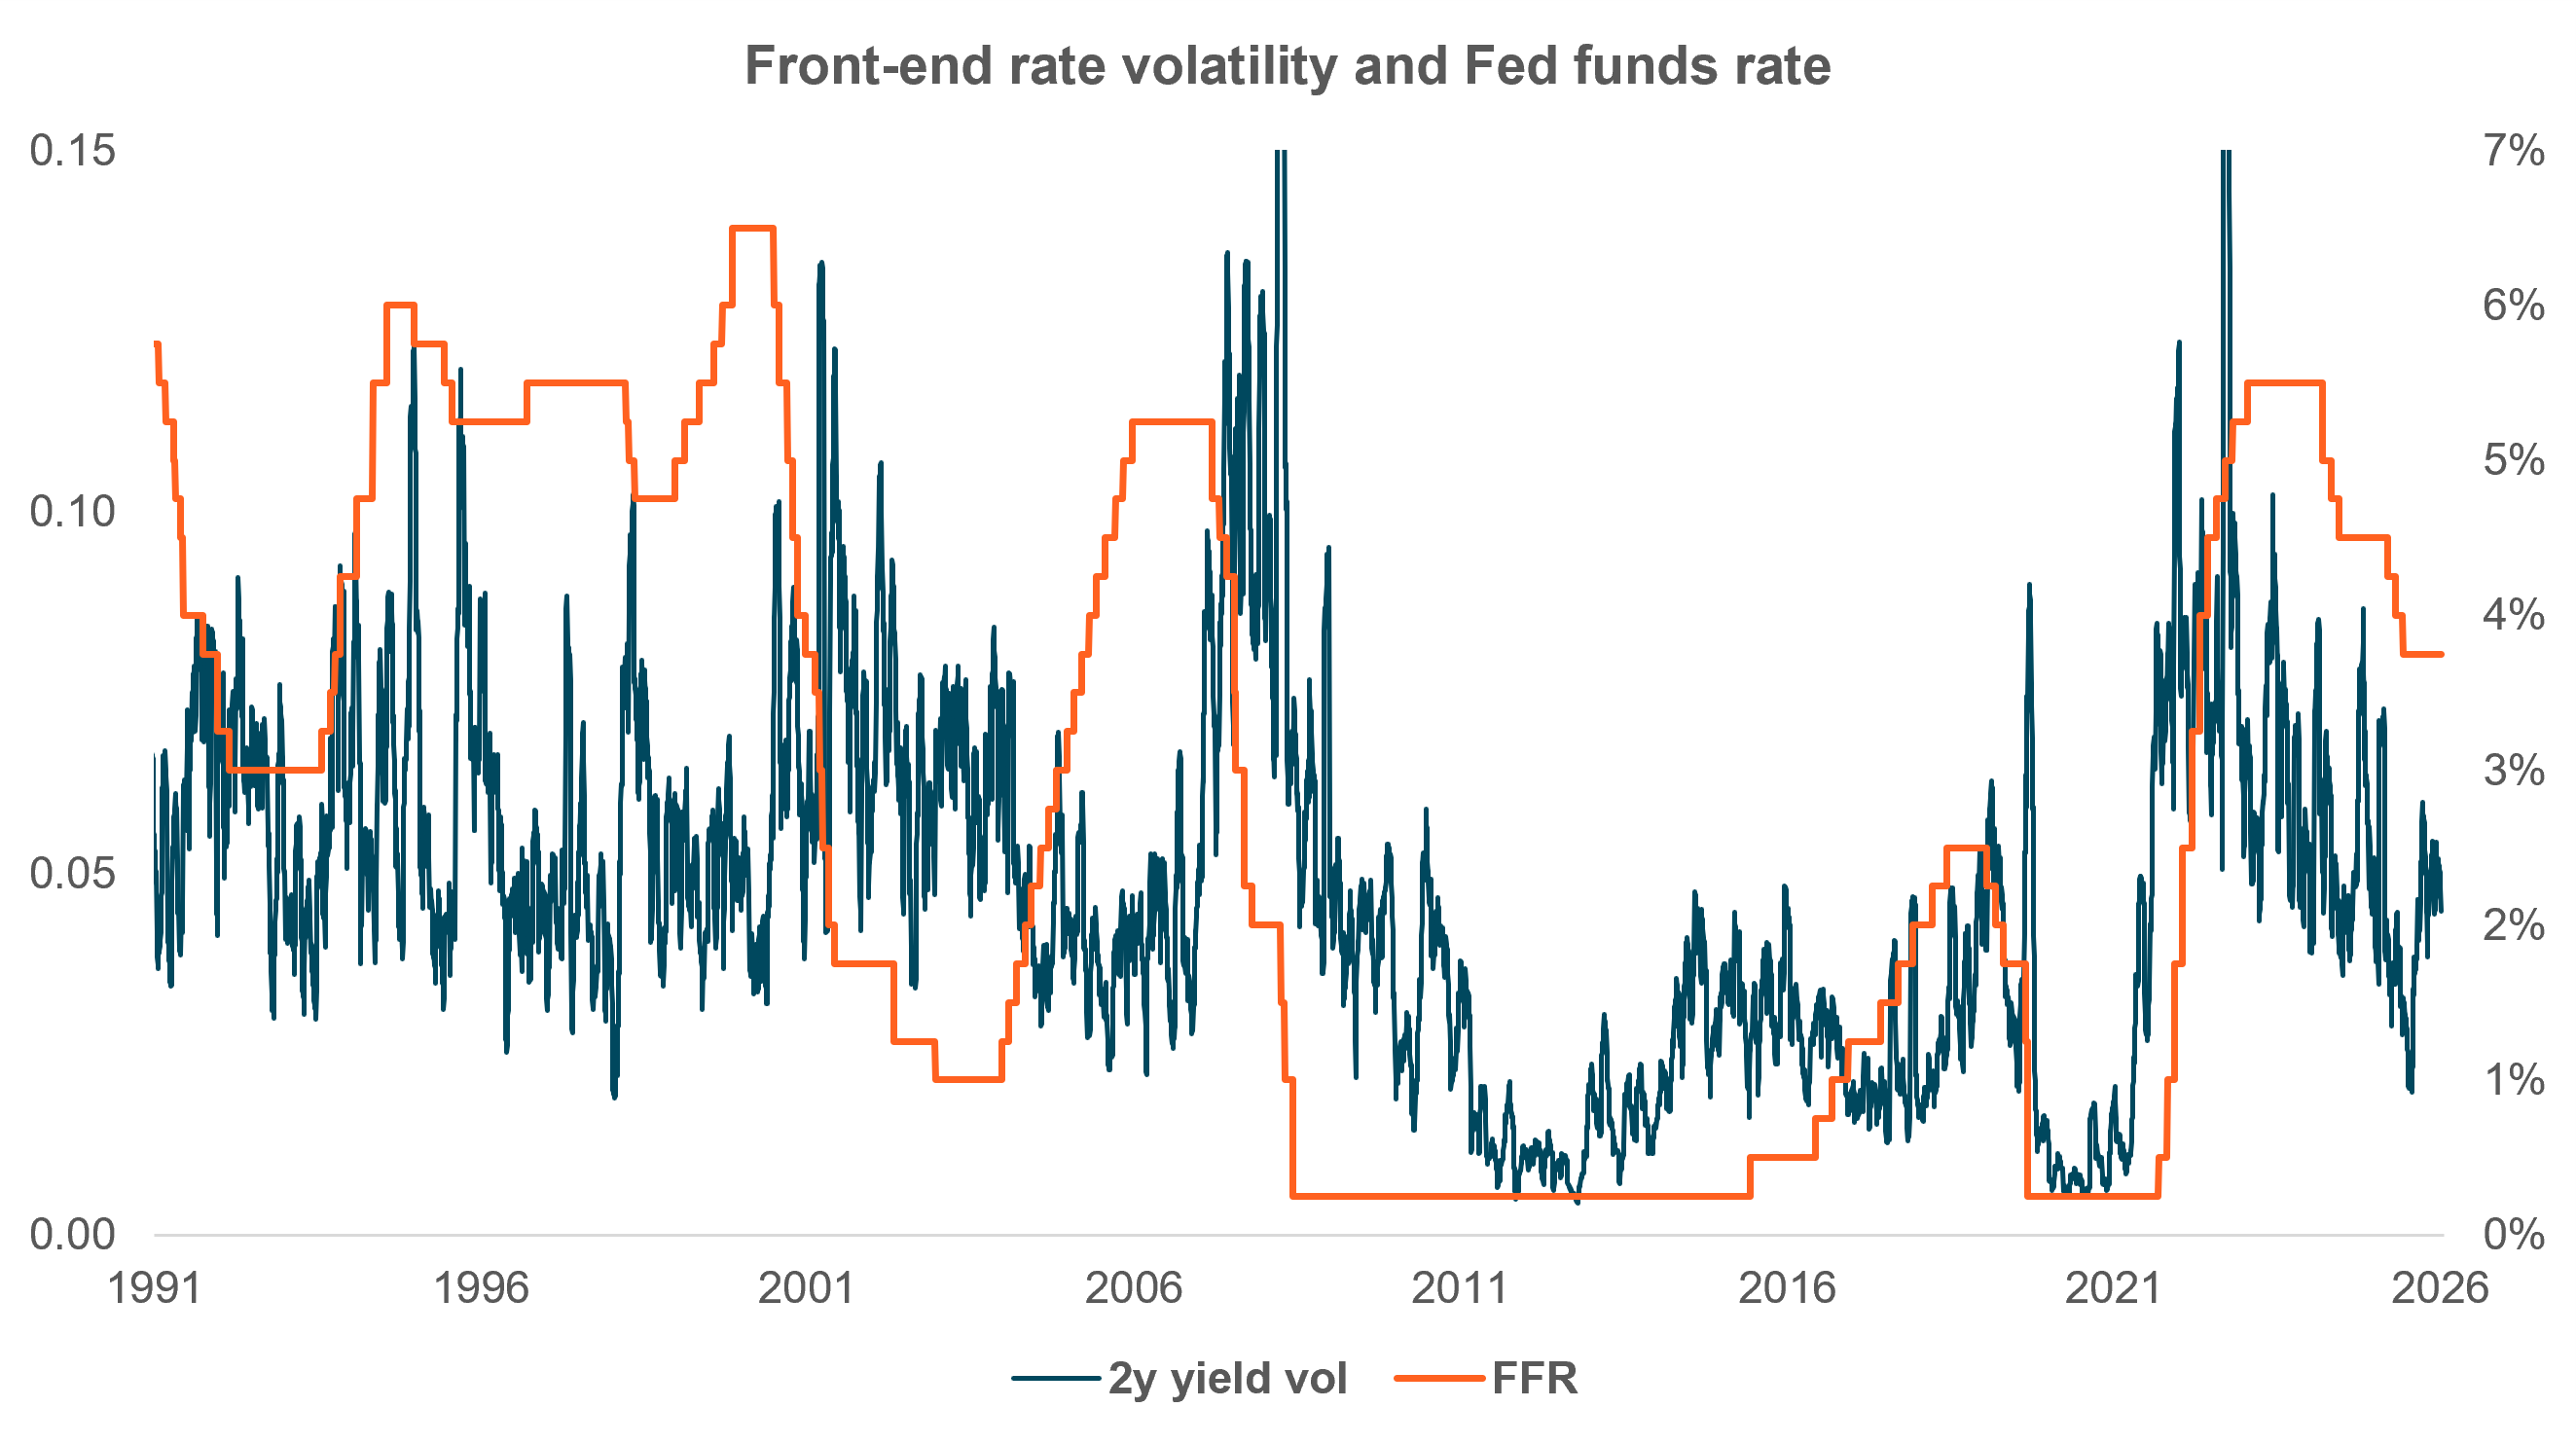
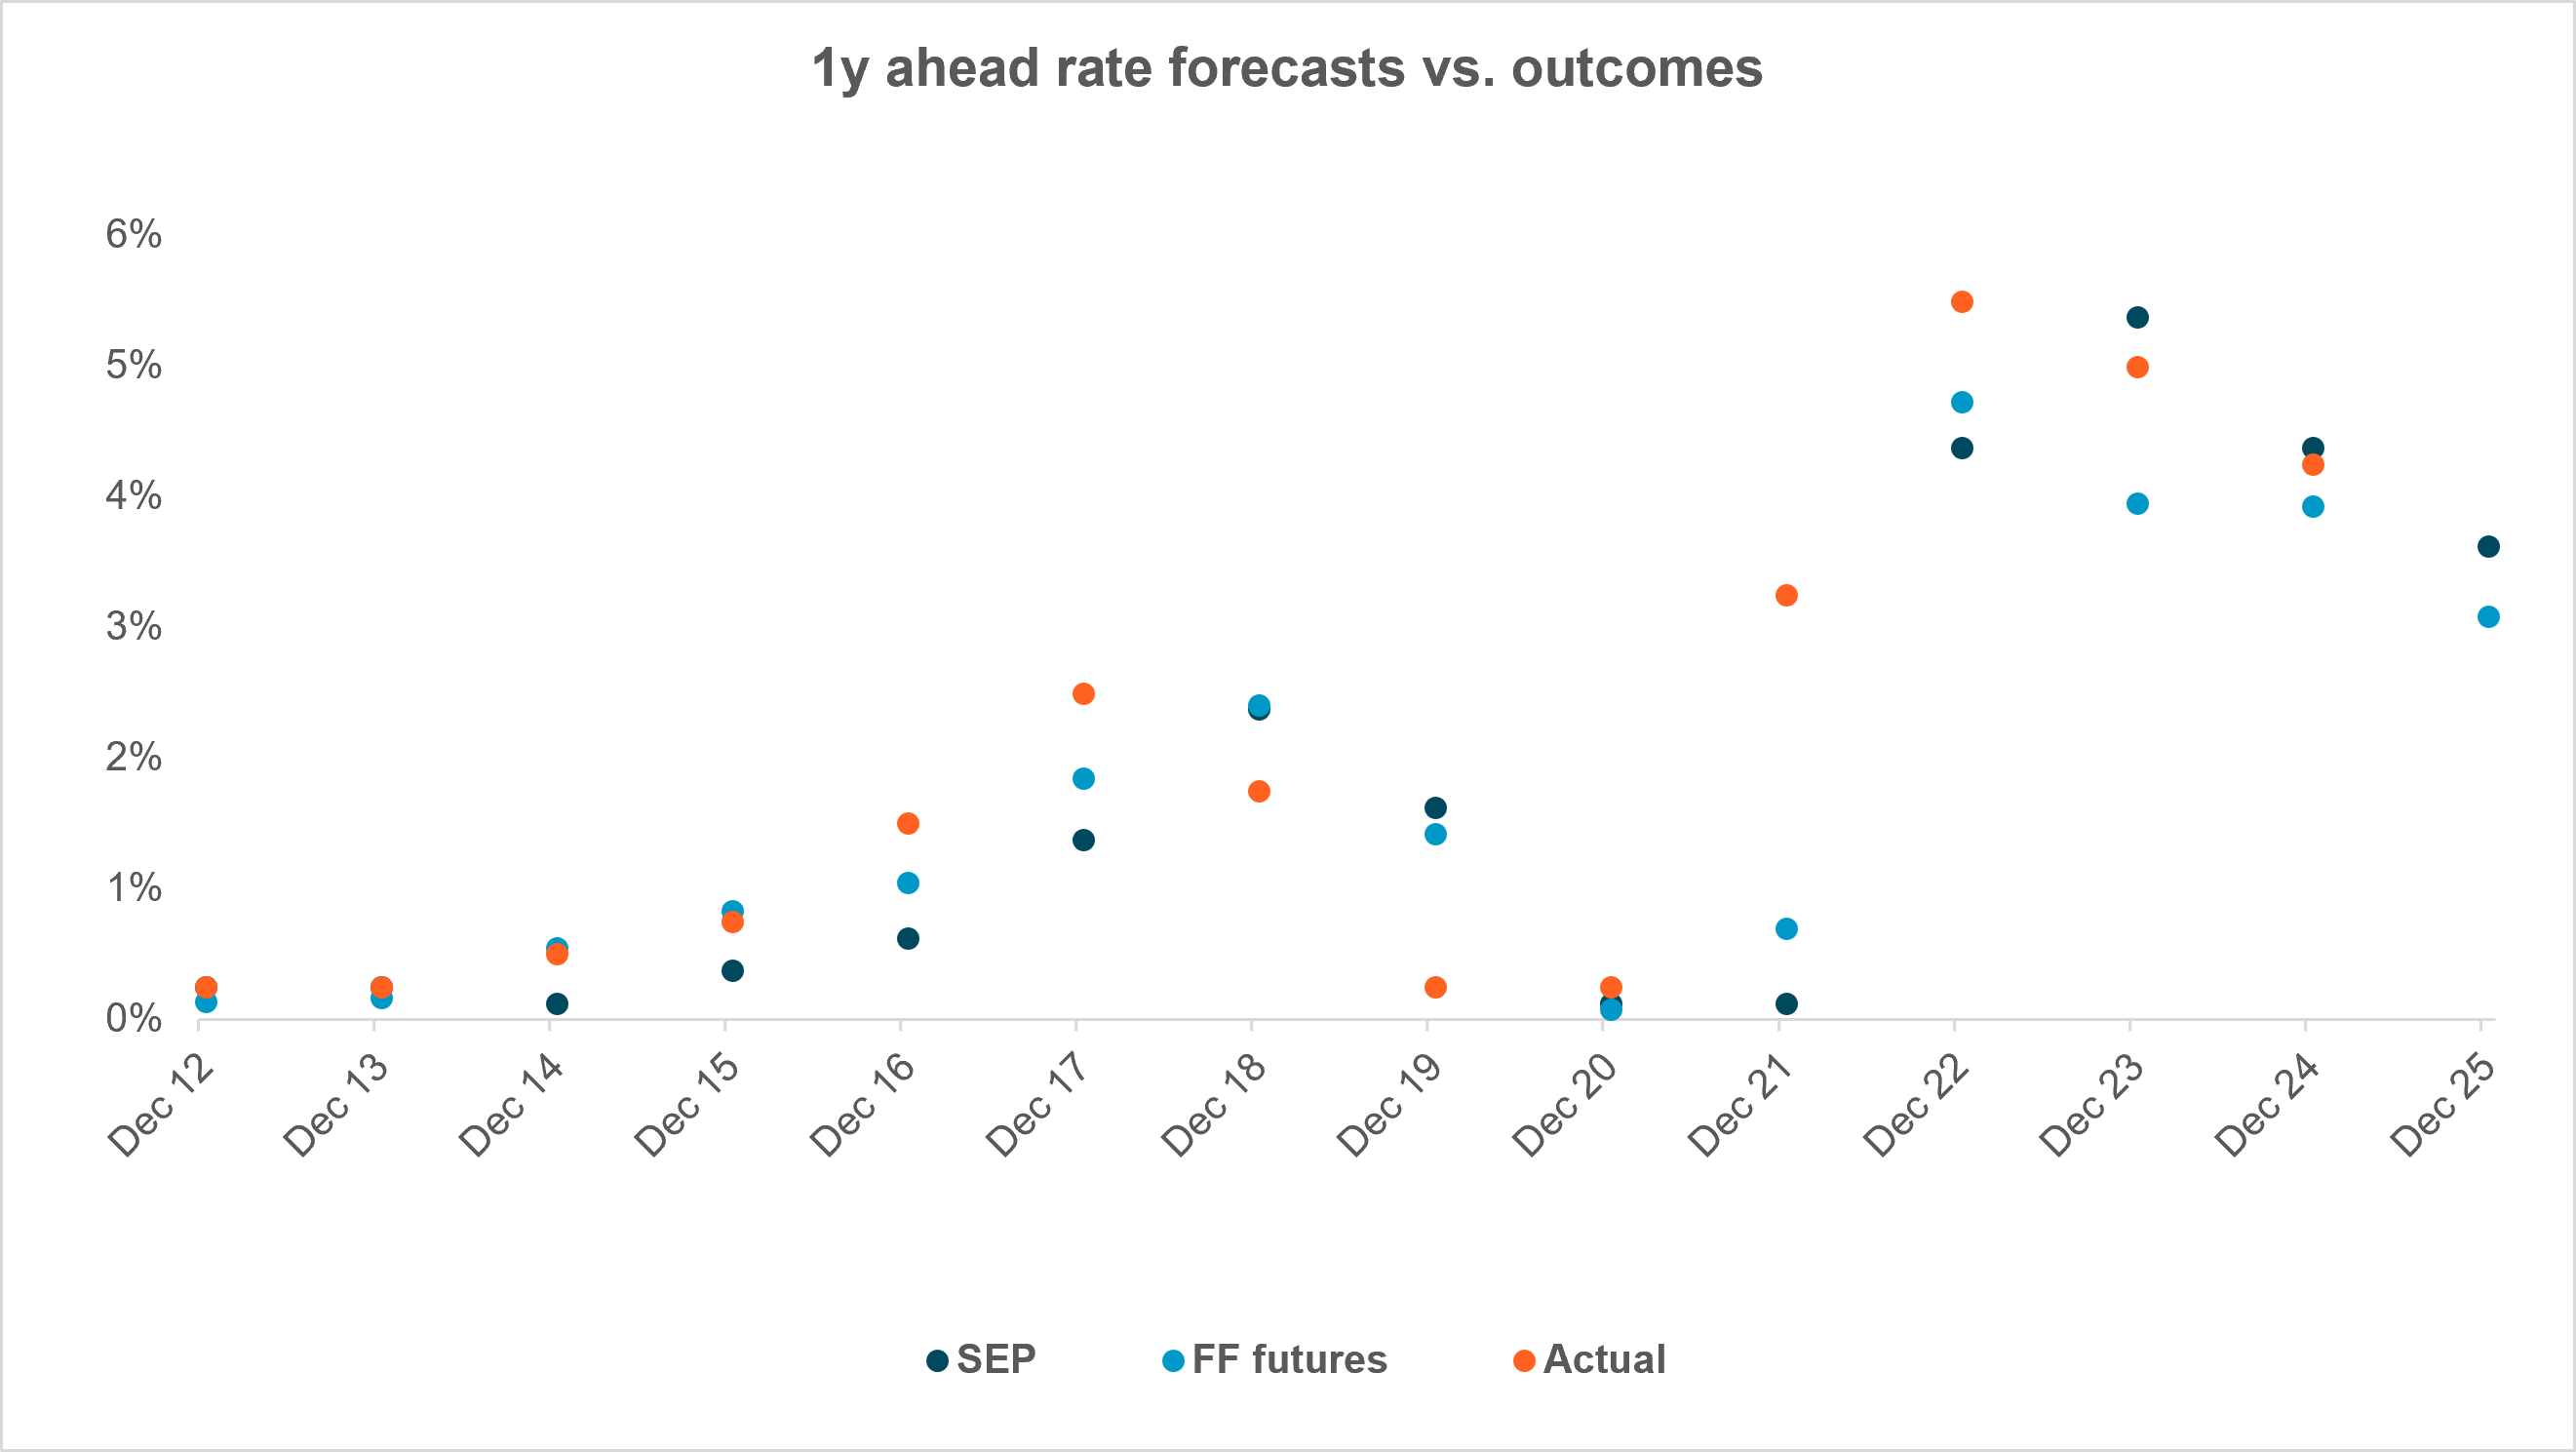
EXHIBIT #2: DOTS AND FUTURES NOT TOO BAD AT ANTICIPATING POLICY

Source: BNY Markets, Bloomberg, Federal Reserve Board of Governors

While we expect that the SEP won’t survive – at least in its current form – into 2027, we do note that as far as forward guidance goes, the dots were not a complete failure. In Exhibit 2, we plot the December dot for the following year’s policy rate and compare it with the actual outcome one year later. We also include the federal funds futures implied rate 12 months out at the end of every year. In general, both the market and the SEP have been directionally correct since 2015 – even if not perfectly accurate. The worst correspondence between forward-looking rate expectations and the actual outcome was in 2022, when both the December 2018 SEP and market projections were caught off guard by the degree of policy tightening that was ultimately required due to the post-COVID inflation shock. If we exclude that one observation, the average error between the dots and actual outcome a year later is only 15bp, less than a standard rate move, roughly in line with the futures market.

Still, while the task force is probably, in our view, going to jettison the dot plot, it probably won’t advocate for complete silence and a return to the 1990s. King and Fraga’s demonstrated preference for “fan charts” (or probabilistic risks around a central forecast) suggests that some communication will survive, even if in a different form. Understanding the Fed’s “reaction function” or how much weight it assigns to deviations from either target of the dual mandate is a different matter. This is less about telling us what the central bank might do, and more about how it will make decisions based on different assessments of the macroeconomy and its evolution. For example, Governor Waller and New York Fed President John Williams separately argued last week for this form of transparency. 

Rates Outlook: Waiting for inflation data

Later on Tuesday, the June CPI report will be released, and with the sharp decline in energy prices, markets are expecting a retreat in headline prices over the month. While we continue to struggle for clarity on access to the Strait of Hormuz, we note that recent events have pushed oil prices back higher over the past weekend, highlighting the folly of forecasting energy prices and their effect on inflation over the short term.

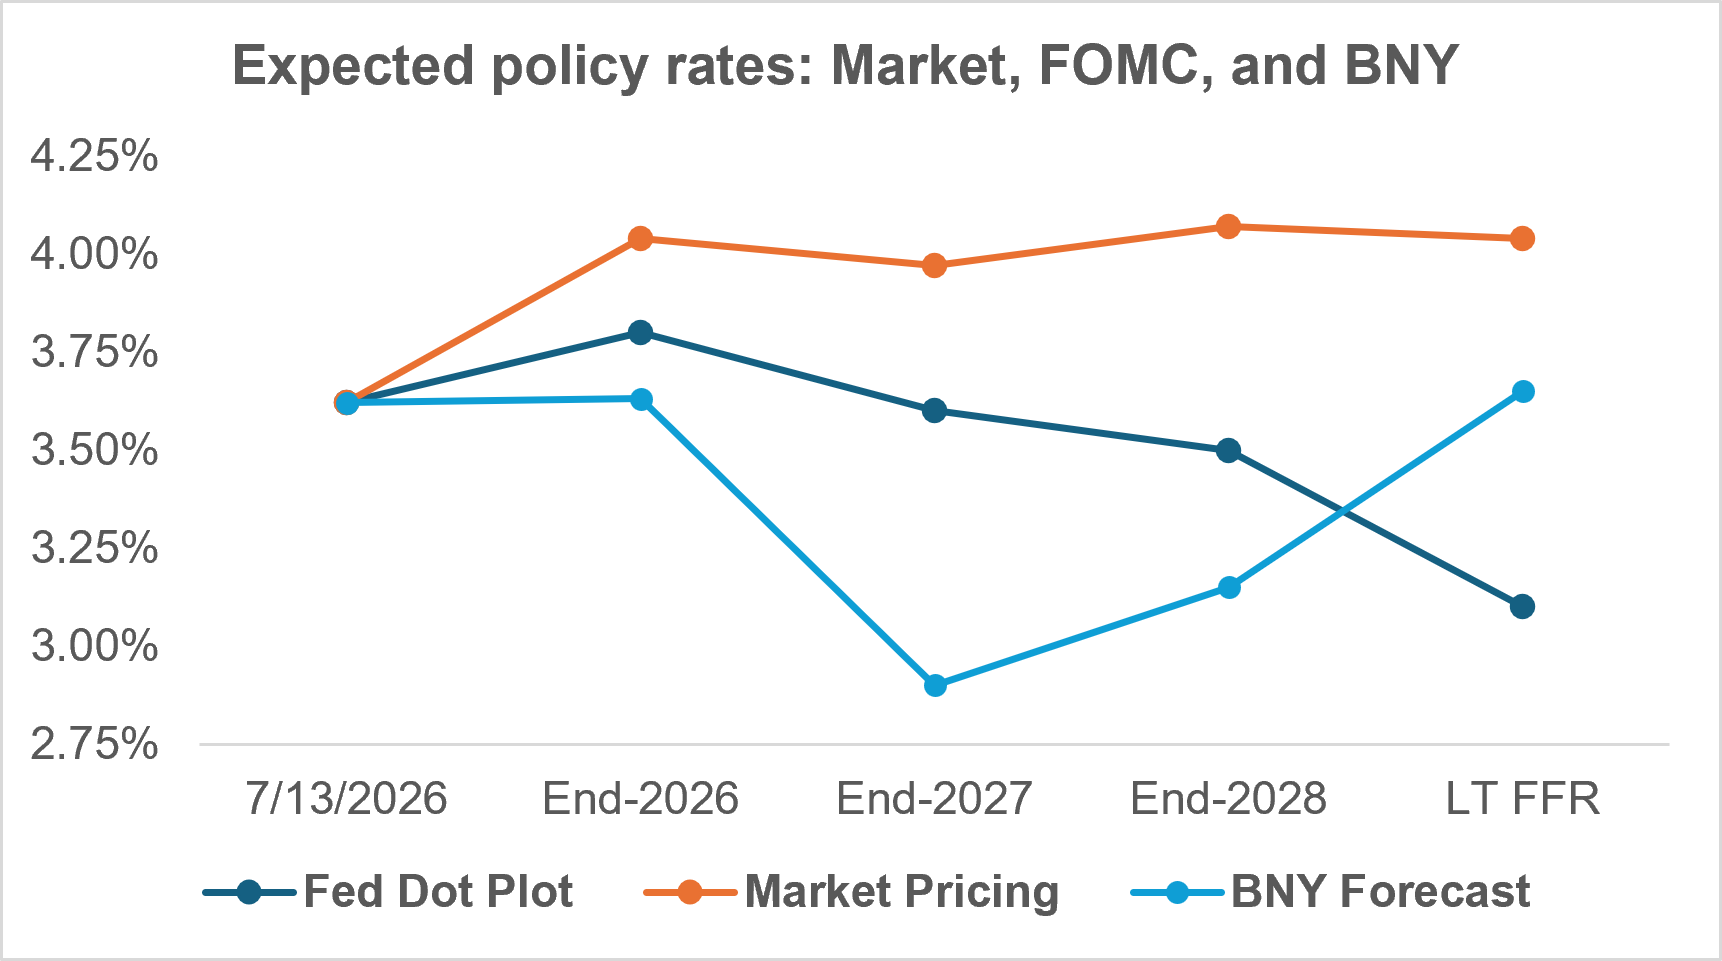
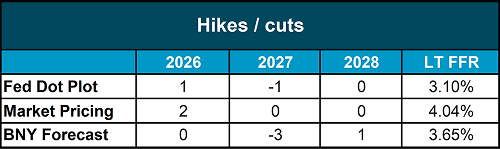
We maintain our view that the Fed will stay on the sidelines for the rest of the year, although developments on the inflation side are both key to our view and quite uncertain. Waller delivered a hawkish message on Monday, warning that rates could rise if inflation doesn’t relent. This is obvious: if prices remain hot, the Fed will have to act. The inflation data this week (including PPI later in the week) will help firm up views one way or another, but we warn the data will be volatile going forward, and very likely the markets along with them.

Chart pack

Media Contact Image
John Velis
Head of Americas Strategy
john.velis@bny.com
Media Contact Image
David Tam
U.S. Rates Strategist
david.tam@bny.com

Ready to grow your business? Speak to our team.