Market Movers: Workouts
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Bob Savage
Time to Read: 8 minutes
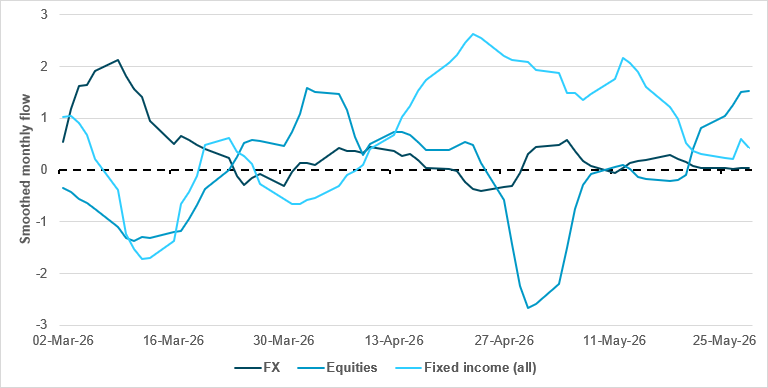
China is the only emerging market with cross-asset inflows
Source: BNY
Heading into June, the market will likely remain concerned about the direction of the conflict and very concentrated positions across markets. Equities and the AI/semiconductor trade remain the core risk, but some other co-movements or co-dependencies also warrant scrutiny, such as the aggressive pricing of rate hikes across developed markets due to inflation risk. Meanwhile, many emerging markets are struggling in the opposite direction, as the same inflationary pressures push down real rates which are crucial to flows in FX and fixed income, while higher import prices or financing costs (from central banks forced into hikes) impact equity performance.
Meanwhile, there is one emerging market where all assets are now being net-bought: China. On the face of it this is surprising, given that the latest round of anti-involution measures announced in Beijing suggest the economy is weakening again. Conversely, looking at flow trends, asset allocation does reflect these fears, as equity flows – while positive – are now retreating from their highs. In contrast, fixed income has rebounded strongly, helped by further declines in policy rates, while the currency’s very light net purchase average seems to reflect standalone CNY policy rather than domestic factors. Given input price risks and a large legacy surplus, there is capacity and a solid policy rationale to let the renminbi appreciate despite domestic pressures. However, the pace will be controlled and subject to export/economic performance, and the cautious inflows also seem to reflect such a policy stance.
The new month starts with mixed risk sentiment. The ongoing conflict between the U.S. and Iran has driven up oil prices again, while AI optimism has pushed shares up, with U.S. futures pointing higher; however, bond yields are also higher along with a stronger USD led by NZD and CHF losses. The continuing dialog over a framework for a peace deal and the ongoing vessel traffic in the Strait of Hormuz are producing shifting reactions to headlines on the conflict. For the markets, late spring brings a heavy dose of discipline: like gym visits ahead of summer, the goal is to rebalance portfolios and look good before liquidity shifts.
Bottom line: Investors are embarking on the new month looking for diversification from the energy and tech themes that dominated May. The data on the economy – from the ISM to the overnight global manufacturing bounce-back – highlight the hopes of lower oil prices in May feeding into a new growth view ahead. If it all works out well, markets will continue to be able to look through the three-month Iran conflict and inflation. Today’s data will be watched in that context. The key risk barometer will be bonds, as the U.S. 30y yields of 5% continue to look important to allocations and growth for the long summer quarter ahead.
The U.S. and Iran exchanged a fresh round of military strikes over the weekend, highlighting continued tensions around the Strait of Hormuz despite ongoing efforts to negotiate a more permanent ceasefire. U.S. Central Command said it conducted defensive strikes against Iranian radar, drone command and control facilities and air defense assets after accusing Tehran of threatening regional shipping and downing a U.S. drone. Iran’s Revolutionary Guard said it retaliated by targeting a U.S.-linked air base in the Gulf and warned of a stronger response if further attacks occur. The escalation came as negotiations on extending and formalizing the ceasefire stalled, with reports indicating disagreements over reopening the Strait of Hormuz and the future of Iran’s enriched uranium stockpiles. The renewed military exchanges underscore the fragility of the current truce and keep up the risks to global energy markets, given the strategic importance of the shipping route for oil and liquefied natural gas exports. Brent +3.073% to 93.92, WTI +3.423% to 90.35, Omani crude +3.135% to 88.18, Dubai crude +0.858% to 88.379.
Hungary will amend its constitution to remove President Tamás Sulyok, Prime Minister Péter Magyar said after meeting the head of state in Budapest, escalating a political confrontation following Magyar’s landslide election win on April 12. Magyar said he would brief lawmakers on the planned process after Sulyok refused to resign, despite a May 31 deadline, citing constitutional duties and loyalty to local and European norms. Magyar’s Tisza party won a two-thirds parliamentary majority, giving it the power to change the constitution and push ahead with removing Orbán loyalists, including top judges and prosecutors, whom Magyar accuses of failing to protect democracy. Budapest SI -0.14% to 134434, EURHUF +0.017% to 353.89, 10y HGB -12bp to 5.3%.
Colombia’s presidential election on Sunday ended without a clear first-round winner, setting up a June runoff between conservative outsider Abelardo de la Espriella and ruling coalition candidate Ivan Cepeda. De la Espriella secured 44% of the vote against Cepeda’s 41%, despite polls previously showing the government-aligned candidate in the lead. The result was widely interpreted as a challenge to the policies of outgoing President Gustavo Petro, particularly his efforts to negotiate peace agreements with armed groups. De la Espriella campaigned on a tougher security platform, drawing comparisons with regional anti-crime crackdowns and presenting himself as politically aligned with President Trump. Following the vote, Cepeda and Petro questioned the election results and called for further scrutiny of the count, alleging irregularities without presenting evidence. The runoff is expected to focus on sharply contrasting approaches to security, peace negotiations and the future direction of Colombia’s economic and social policies. COLCAP -0.26% to 2177, USDCOP +1.312% to 3688, 10y CGB -7.2bp to 13.245%.
Former Federal Reserve Chair Jerome Powell used a public speech in Boston to deliver a strong defense of Federal Reserve independence, arguing that the central bank’s credibility would be at risk if any administration gained the ability to remove policymakers over disagreements on monetary policy. Speaking after returning to his role as a Fed governor, Powell stressed that legal protections shielding Fed officials from political interference are essential to preserving confidence in U.S. monetary policy and noted that the executive branch has no role in selecting or overseeing regional Federal Reserve Bank presidents. His remarks come as the U.S. Supreme Court is expected to rule on President Trump’s attempt to remove Fed Governor Lisa Cook, a case that could have significant implications for the institution’s independence. Powell also emphasized the importance of preserving the Fed’s authority over the appointment of regional presidents, warning that institutional safeguards built over decades can be weakened quickly if political influence expands. S&P Mini +0.21% to 7612, DXY +0.05% to 98.991, 10y UST +2.4bp to 4.459%.
China has announced new outbound investment regulations effective July 1 that significantly strengthen government oversight of overseas transactions involving Chinese investors, technology, data and national security. This follows the recent order requiring Meta to unwind its acquisition of AI startup Manus. The rules establish a formal legal framework allowing authorities to review, block or even unwind completed foreign investment deals, particularly in sensitive sectors such as AI and advanced technology. The measures require approval for the transfer of restricted technologies, services and related data overseas, while also restricting cross-border talent transfers and operational relocations designed to shift sensitive activities abroad. Beijing has also given itself broader powers to conduct national security reviews, impose penalties and retaliate against foreign companies if their home countries restrict Chinese investment. The regulations form part of a wider effort to strengthen export controls, protect strategic technologies, reinforce supply chain security and increase China’s ability to respond to Western sanctions and investment restrictions. CSI 300 -0.93% to 4846, USDCNY +0.005% to 6.766, 10y CGB -1.6bp to 1.704%.
U.S. May final S&P Global Manufacturing PMI is forecast to hold at 55.3 vs. 55.3 flash.
U.S. May ISM Manufacturing is expected to rise to 53.0 vs. 52.7. ISM Prices Paid is expected to rise to 85.0 vs. 84.6. May ISM Employment is expected to rise to 48.4 vs. 46.4.
U.S. April construction spending is forecast to ease to 0.3% m/m vs. 0.6% m/m.
Canada Bloomberg Nanos Confidence is expected at 52 vs. 51.7.
Canada May S&P Global Manufacturing PMI is expected at 53.5 vs. 53.3.
Central bank speakers: The BoC’s Carolyn Rogers appears before a parliamentary committee.
U.S. Treasury sells $89bn in 13-week bills and $77bn in 26-week bills.
Mood: iFlow Mood fell to -0.317, its most risk-off reading since end-2024, driven by intensified demand for government bonds alongside persistent global equity outflows.
FX: Heavy selling was concentrated in NZD, DKK, CAD and TRY, while inflows favored EUR, JPY, AUD, ZAR and ILS. Flows across the rest of the universe were generally mixed and modest.
FI: Strong demand continued for Eurozone government bonds, Chinese government bonds and U.S. Treasurys. In contrast, LatAm, Indonesian, New Zealand and Australian government bonds saw light selling pressure.
Equities: Broad-based equity outflows persisted across all region, notably in the U.K., Japan, Mexico, Peru, Hong Kong, Indonesia and South Korea. Selective buying emerged in China, Thailand, Norway and New Zealand, while U.S. equity flows were broadly neutral. Within DM Americas, utilities, industrials and consumer discretionary attracted inflows, while materials remained under pressure.
“If you feel doubtful of your ability to endure life’s trials, exercise is the cure to unlock your full powers.” – John Soforic
“The only person you are destined to become is the person you decide to be.” – Ralph Waldo Emerson
The euro area Consumer Expectations Survey results for April showed a mixed picture for inflation, income, spending and labor market sentiment. Median perceived inflation over the past 12 months rose to 4.0% from 3.5% in March, while expectations for inflation one year ahead stayed at 4.0% and five-year expectations were unchanged at 2.4%; three-year expectations edged down to 2.9%. Consumers turned more cautious on income growth, with expectations for nominal income over the next 12 months falling to 0.8%, while expected spending growth rose to 4.3%. Growth expectations became slightly more negative at -2.2%, unemployment expectations eased to 11.2% and credit access was seen as tighter. Euro Stoxx 50 0% to 6051, EURUSD -0.018% to 1.1657, BBG AGG Euro Government High Grade EUR 0bp to 3.184%.
Euro area monetary developments for April showed a softer pace of money growth, with broad monetary aggregate M3 rising 2.7% y/y, down from 3.2% in March, while M1 slowed to 3.8% from 4.7%. Deposits by households were unchanged at 2.9%, but deposits by non-financial corporations eased to 3.8% and deposits by investment funds fell sharply. On the credit side, adjusted loans to the private sector held at 3.5%, with household lending unchanged at 3.0% and lending to non-financial corporations edging up to 3.4%. Overall, the data point to moderating money growth while corporate borrowing remained resilient.
Eurozone manufacturing PMI came in at 51.6 points in May, down from 52.2 in April. This represented a two-month low and indicated that factory activity still expanded but at a slower pace. Output also eased to 51.3 from 52.3, while new orders stagnated after a strong rebound in April, and export demand fell again. Factory employment declined for a third straight year and backlogs were reduced as firms worked through outstanding orders. At the same time, inflationary pressures intensified sharply, with input costs rising at the fastest pace since 2022 and output price growth at a three-and-a-half-year high. S&P Global said supply disruptions and higher energy costs were weighing on demand.
Euro area unemployment for April was 6.3%, unchanged from March and from a year earlier. The broader EU rate was also steady at 6.0%. Eurostat estimated that 11.075 million people in the euro area and 13.238 million in the EU were out of work, with monthly unemployment falling by 84k and 137k, respectively. Youth unemployment improved more strongly, with the euro area rate dropping to 14.7% from 15.1% in March. The data suggest a stable labor market overall, with little deterioration in the headline rate but some easing in joblessness among younger workers.
Germany’s manufacturing PMI for May came in at 50.1 points, down from 51.4 in April. This signals near-stagnation in the sector, as demand weakened and costs surged. New orders fell for the first time in 2026, while output growth eased to only a marginal pace and export sales shrank for the first time since January. Input costs jumped to the highest level in nearly four years, driven by higher energy, fuel, transport and commodity prices linked to the Middle East disruption, which prompted factory gate price increases. Employment was cut at the fastest pace since February 2025, and supply chain delays worsened, leaving business confidence subdued despite a slight recovery vs. April. DAX +0.07% to 25121, EURUSD -0.018% to 1.1657, 10y Bund +3.7bp to 2.975%.
German retail sales fell 0.3% m/m in real terms in April, matching the revised decline recorded in March, while nominal sales increased by 0.3%. Compared with April 2025, retail turnover was down 0.3% in real terms but up 1.4% in nominal terms, indicating continued pressure from inflation on consumer spending. Food retail sales provided support, rising 3.2% m/m in real terms, while non-food retail sales fell 2.2%. Internet and mail order retailing had a particularly weak month, with real sales down 4.7% vs. March, although still 0.4% higher than a year earlier. Fuel station sales were also weak, with real turnover down 4.0% m/m and 10.4% y/y, reflecting the impact of the Middle East conflict and higher energy prices. Across the first four months of 2026, total retail sales were still 0.5% higher y/y in real terms.
France’s manufacturing PMI fell to 49.7 points in May from 52.8 in April, slipping back into contraction for the first time since November as the brief April rebound faded. S&P Global said output and new orders both declined, while export demand weakened, especially from Belgium, Germany and Ukraine. Firms also cut purchases and ran down inventories as supply chain pressures worsened and delivery times lengthened. Employment fell for a fourth straight month, backlogs eased and business confidence remained subdued. Inflationary pressures strengthened, with input costs rising at a four-year high and selling prices increasing at the fastest pace in 40 months. CAC 40 +0.01% to 8184, EURUSD -0.018% to 1.1657, 10y OAT +4.5bp to 3.594%.
Italy’s manufacturing PMI for May came in at 52.9 points, up from 52.1 in April – the highest reading since April 2022. The survey showed renewed growth in new orders, including a slight pickup in export sales, which supported a stronger increase in factory output. Firms also increased their purchasing at the fastest pace since April 2022 as they sought to build safety stocks amid supply chain disruption and concerns linked to the Middle East war. Employment continued to rise, though more slowly than in April, and backlogs turned positive for the first time in nearly four years. Delivery delays worsened further, while both input costs and output charges accelerated to four-year highs, pointing to intensifying inflation pressures. FTSE MIB +0.04% to 50058, USDJPY +0.12% to 159.46, 10y BTP +4.6bp to 3.698%.
Spain’s manufacturing PMI fell to 51.2 points in May from 51.7 in April, showing only modest expansion as the sector was hit by Middle East conflict, supply disruptions and surging input costs. New orders declined for the fifth time in six months, with export demand falling for a ninth straight month, while employment also decreased for a ninth consecutive month. Output rose only marginally, and business confidence remained subdued despite a slight improvement from March. Price pressures were severe, with input inflation reaching a four-year high and selling prices rising further, though at a slower pace than in April. IBEX 35 -0.62% to 18332, EURUSD -0.018% to 1.1657, 10y Bono +4bp to 3.393%.
The U.K.’s Nationwide house price index showed a loss of momentum in the housing market in May, with seasonally adjusted house prices falling 0.6% m/m, the first m/m decline of the year. Annual house price growth slowed to 1.7% from 3.0% in April, while the average house price edged down to £278,024 from £278,880. Nationwide attributed the slowdown to increased uncertainty stemming from the Middle East conflict, higher energy prices, rising market interest rates and weaker consumer confidence, which has fallen to its lowest level since late 2023. Housing market sentiment has also softened, with new buyer inquiries remaining weak. Nevertheless, the report highlighted supportive fundamentals, including solid household balance sheets, strong income growth, relatively low debt burdens and housing affordability that remains improved compared with recent years. Nationwide expects any near-term housing market weakness to prove temporary if energy prices stabilize and broader economic conditions remain resilient. FTSE 100 -0.2% to 10388, GBPUSD +0.045% to 1.3462, 10y gilt +2.5bp to 4.837%.
U.K. manufacturing PMI came in at 53.9 points in May, up slightly from 53.7 in April, pointing to a firmer expansion in activity in the sector. Production rose for a second month in a row and new orders increased for the sixth straight month, supported by stronger domestic and export demand, while business optimism improved to a three-month high. However, the report also highlighted a less stable backdrop, with firms frontloading purchases ahead of expected price rises and supply disruptions. Input cost inflation accelerated to a near-four-year high, supply chains remained under heavy strain and average selling prices rose at the fastest pace since July 2022, suggesting ongoing pressure on margins and a risk that the recovery may prove short-lived.
Switzerland’s manufacturing PMI rose to 57.3 points in May, up 2.8 vs. April to the highest level in more than three years, pointing to a broad improvement in industrial activity. The gain was driven by stronger production and new orders, while employment was broadly stable just below the 50-point threshold. Firms reported firmer purchasing activity, longer delivery times and higher input costs, especially for oil-based products such as plastics, alongside pricier electronics and industrial metals. The services PMI also moved higher, climbing to 56.0 as business activity improved sharply and new orders and backlogs edged up. Overall, the data suggest robust momentum, though inflationary pressures remain elevated. SMI -0.65% to 13454, EURCHF +0.261% to 0.91284, 10y Swiss GB +1.2bp to 0.418%.
Swiss retail sales continued to strengthen in April, with real sales rising 1.6% y/y after a 1.3% increase in March, marking the third consecutive month of y/y growth. Excluding service stations, retail sales climbed 1.4% y/y, while non-food sales remained the main source of strength, rising 2.5%. Food, beverage and tobacco sales returned to positive territory with a 0.3% y/y increase after declines in the previous two months. On a seasonally adjusted monthly basis, total real retail sales edged up 0.1%, extending the gradual recovery seen since February. Food-related sales increased by 0.6% m/m, offsetting a slight drop in non-food sales (-0.1%). Nominal retail sales rose 0.6% y/y but fell 0.2% vs. March, suggesting that volume growth rather than price effects drove the improvement in consumer spending during April.
Switzerland’s service sector turnover rose 2.1% y/y (calendar-adjusted) in March, on growth across both trade and non-trade activities. Turnover in the broader tertiary sector excluding trade rose 1.5%, while wholesale and retail trade increased by 2.7%. Within trade, wholesale turnover rose 3.3%, supported by a 7.4% increase in raw materials wholesale activity and a 5.7% gain in other wholesale trade, while retail turnover increased by 0.7%, led by automotive fuel sales (+4.5%) and non-food retailing (+1.0%). Outside trade, transportation and storage grew by 1.9%, real estate activities by 3.8%, professional, scientific and technical services by 1.9% and administrative and support services by 3.2%. Information and communication declined by 1.4%, reflecting weakness in audiovisual and broadcasting activities (-13.5%) and computer programming and consultancy (-8.0%), partly offset by strong growth in information services (+23.3%). Accommodation and food services fell 0.8%, with accommodation down 4.8% while food services rose 1.5%.
Switzerland’s Q1 GDP grew by 0.4% q/q after adjustment for sports events, from 0.2% in Q4 2025, showing a modest pickup in the early part of the year. The industrial sector was the main driver, with manufacturing rising 1.5% and overall industrial value added up 1.3%, while chemical and pharmaceutical output weakened and goods exports fell 2.2%. Services were close to flat at 0.2%, as gains in transport and financial services were offset by declines in trade, retail and accommodation. Domestic final demand was soft, with private consumption flat, investment down and imports falling 2.4%.
Sweden’s manufacturing PMI rose to 57.3 points in May from 57.0 in April. This marks the third consecutive m/m increase and the eleventh straight month above its long-run average of 54.3, signaling continued strengthening in industrial activity. The improvement was driven primarily by stronger employment and inventory purchases, although new orders acted as a drag on the headline index. Production plans continued to improve and reached their highest levels in more than four years, indicating confidence in future manufacturing activity. At the same time, cost pressures remained elevated, with the index for raw material and input prices at 81.6, only slightly below April’s 82.0 reading and still higher than at any point since spring 2022. Survey respondents noted that rising commodity prices and supply chain disruptions linked to the Middle East conflict have so far had limited impact on production plans, but prolonged geopolitical tensions could become a significant challenge and add to inflationary pressures through higher producer prices. OMX -0.36% to 3127, EURSEK -0.023% to 10.7759, 10y Swedish GB +1.9bp to 2.827%.
Sweden’s housing market sentiment improved further in June, with the SEB Housing Price Indicator rising to 44 from 41 in May, marking a second consecutive m/m increase and returning to levels seen at the start of 2026. The survey showed that 53% of households expect home prices to rise over the next year, up from 52% previously, while the share expecting prices to fall dropped from 11% to 9%. The continued improvement in housing sentiment contrasts with weak broader consumer confidence, which has been weighed down by the Middle East conflict, higher energy prices and expectations of higher interest rates. SEB attributed the resilience in housing expectations to supportive regulatory changes, including higher loan-to-value limits and reduced amortization requirements, as well as strong household fundamentals such as rising incomes and expansionary fiscal policy. Expectations of future policy rates eased slightly, while intentions to fix mortgage rates remained largely unchanged.
Poland’s manufacturing PMI for May came in at 49.4 points, up from 48.8 in April, signaling a still-modest deterioration in business conditions but the slowest downturn in 13 months. Output rose for the second time in three months, helped by a tentative market recovery, while new orders fell for a fourteenth straight month, though at the gentlest pace since November. Input and output price inflation both eased but remained elevated. Suppliers’ delivery times lengthened sharply, and firms increased purchases to rebuild stocks. The 12-month outlook was still positive, but sentiment remained below the long-run average. WIG -0.75% to 135979, EURPLN +0.057% to 4.2337, 10y PGB +2.6bp to 5.662%.
Polish GDP rose 3.5% y/y in Q1 (preliminary estimate), accelerating from 3.2% in the same quarter of 2025. On a seasonally adjusted basis, GDP increased by 0.6% q/q and was also up 3.5% y/y. Growth was driven mainly by domestic demand, which added 3.5 percentage points, supported by final consumption and gross capital formation. Household consumption grew by 3.3%, public consumption by 6.0% and gross fixed capital formation by 2.4%. Net exports were neutral, while industry, trade and public services posted solid gains in value added.
Czechia’s manufacturing PMI came in at 52.2 points in May, down from 52.9 in April, indicating a modest but slower improvement in sector conditions. Output rose for a sixth straight month and new orders also increased, though both growth rates eased as customer hesitancy and material shortages weighed on momentum. Input buying jumped at the fastest pace in over four years as firms tried to build safety stocks and guard against further price hikes. Supply delays remained severe, while input costs were again high by historical standards elevated despite a slight cooling. Selling prices rose at the fastest pace since October 2022, employment fell further and business confidence improved on investment plans and hopes of stronger demand. Prague SE +0.17% to 2552, EURCZK +0.038% to 24.291, 10y CZGB +1.4bp to 4.791%.
Hungary’s manufacturing PMI came in at 50.2 points in May (seasonally adjusted), edging just above the 50-point threshold and signaling marginal expansion, but slower growth than in the previous month. The survey pointed to broad-based easing across most components, with new orders, output, deliveries, inventories and exports all weakening. New orders still remained in expansion territory, while production also continued to grow, albeit at a softer pace. Employment improved and moved back above 50 points, indicating a mild rebound in hiring. Purchase prices rose sharply, though the price index fell substantially vs. April, suggesting some moderation in cost pressures. Overall, the reading was below the long-term May average and ranked as one of the weakest May outcomes since 1995. Budapest SI -0.14% to 134434, EURHUF +0.017% to 353.89, 10y HGB -12bp to 5.3%.
Türkiye’s manufacturing PMI edged up to 49.8 points in May from 45.7 in April, pointing to a near-stabilization in business conditions and the strongest reading since March 2024. Output returned to growth for the first time in 26 months, helped by a renewed rise in new export orders, while total new business still softened slightly amid uncertainty, higher prices and Middle East conflict disruptions. Purchasing activity increased for the first time in just over two years as firms built safety stocks, but employment continued to fall, though at the weakest pace of 2026 so far. Input costs rose sharply and supplier delivery times lengthened further. BI 100 +0.98% to 13796, USDTRY +0.132% to 45.9135, 10y TGB -39bp to 35.26%.
Türkiye’s quarterly GDP for January-March rose 2.5% y/y, in a modest but continued expansion. On a seasonally and calendar-adjusted basis, GDP edged up 0.1% q/q, while calendar-adjusted growth was 2.6% y/y. In current prices, GDP reached TRY 17tn, equivalent to $390bn. Growth was led by information and communication, other services, agriculture, trade and construction, while industry contracted. Household consumption rose by 4.8% and investment by 3.0%, while exports fell 12.7%.
South African factory sentiment eased in May, as the Absa manufacturing PMI fell to 50.8 points from 52.6 in April. This still represented a second straight month of expansion, but only marginally. The report showed that activity and demand softened after April’s pull forward in orders faded, with the business activity index dropping into contraction at 43.5 points from 52.8 and new sales orders slipping to 44.6 from 52.9. Absa said weaker demand and higher input costs, linked to a weaker rand and elevated international oil prices, remained key pressures on manufacturers. Expectations improved, however, with the six-month business conditions index rising to 52.9 from 47.4, suggesting some optimism ahead. JSE TOP 40 -0.81% to 105961, USDZAR +0.14% to 16.2485, 10y SAGB +5.2bp to 8.621%.
China’s manufacturing PMI eased to 51.8 points in May from 52.2 in April but remained above the 50-point threshold for a sixth consecutive month, signaling continued expansion in factory activity despite some moderation in growth. New orders and output continued to rise at robust rates, with demand remaining among the strongest seen in the past five years, although export orders declined slightly. Production growth slowed from April’s 22-month high but remained solid, while backlogs increased for a fourth straight month. Employment edged lower, reflecting ongoing capacity pressures. Inflationary pressures softened, with input and output price inflation easing for the first time in six and seven months, respectively, though input costs remained elevated due to higher raw material and energy prices and supply chain disruptions. Firms stayed optimistic about the year ahead, supported by expectations of stronger demand, business expansion and new orders. CSI 300 -0.93% to 4846, USDCNY +0.005% to 6.766, 10y CGB -1.6bp to 1.704%.
Chinese May PMI data were mixed. Manufacturing stayed at 50.0, with new orders (49.9), new export orders (48.6) and imports (48.8) in the contraction zone, while input prices (60.5) and producer price (51.9) subcomponent remained elevated. High-tech manufacturing (52.9) and equipment manufacturing (52.1) were once again firmly in expansion territory, with high-tech PMI marking its 16th consecutive month above 50, highlighting the ongoing strength of China’s industrial upgrade and new-economy sectors. Non-manufacturing edged up to 50.1 from 49.4, led by services, but construction remained in contraction at 48.8. Overall, China’s recovery remains uneven, with traditional sectors facing headwinds and new-economy sectors still faring well.
Australia’s manufacturing PMI eased to 50.7 points in May from 51.3 in April, remaining marginally in expansion territory but masking weaker underlying conditions across the sector. New orders fell for a third consecutive month and at the fastest pace since October 2025, reflecting squeezed customer budgets, higher prices and subdued demand. Export orders also declined, particularly due to softer demand from Asian markets, while manufacturing output contracted for a fourth straight month. Inflationary pressures remained intense, with input costs rising at the second-fastest pace in almost four years and output price inflation accelerating to its highest level since August 2022. Supply chain disruptions persisted, with delivery times lengthening sharply due to higher fuel costs and shipping delays linked to the Middle East conflict. Employment increased modestly, while business confidence improved slightly but remained subdued amid ongoing uncertainty and weak demand conditions. ASX -0.09% to 5604, AUDUSD -0.07% to 0.718, 10y ACGB +5.1bp to 4.882%.
Australia’s Melbourne Institute monthly inflation gauge fell in May after two consecutive m/m rises. This was driven mainly by lower transport-related prices, largely due to fuel. Headline inflation was -0.3% m/m, 4.4% y/y (April: 0.6% m/m, 4.3% y/y). The trimmed mean also showed a 0.1% m/m contraction, but the annualized figure remained high at 3.6% y/y, warranting a generally vigilant stance by the RBA. The main driver was a fall in automotive fuel price inflation after a reduction in fuel excise duty, while self-funded retirees also saw a degree of reduction in their cost of living. The market is reluctant to price in more than one additional hike for the rest of the year amid further signs of caution in household sentiment, especially if housing costs continue to ease.
Australian home values were unchanged nationally in May, in the first flat m/m result since January 2025. This points to a further loss of momentum in the housing market. The slowdown was led by Sydney and Melbourne, where dwelling values fell 0.9% and 0.8%, respectively, while Canberra prices were down 0.2%. In contrast, Perth and Darwin recorded the strongest gains at 1.5%, with Brisbane and Adelaide also posting modest increases. The cooling trend reflects a combination of affordability constraints, 75bp of interest rate hikes this year, weaker consumer confidence linked to the global oil shock and proposed changes to negative gearing and capital gains tax. Sales volumes have weakened, with transactions running below both last year’s levels and the five-year average. While analysts expect further declines in home prices and investor demand, most see a gradual downturn rather than a housing market crash.
Japan’s corporate earnings strengthened markedly in the January-March quarter, with sales rising 1.1% y/y to a record ¥408.7tn and ordinary profits up 14.6% to ¥32.6tn, the second-highest Q1 level on record. Manufacturing was the main driver, with ordinary profits surging 42.9% and sales increasing by 4.5%, supported by strong gains in information and communication equipment, electrical machinery and transport equipment. Non-manufacturing profits rose by a more modest 1.4%, while sales slipped 0.3%. Capital expenditure was unchanged from a year earlier overall, as a 0.4% fall in manufacturing investment offset a 0.3% increase in non-manufacturing. Corporate balance sheets remained healthy, with the equity ratio at 44.0%, while cash holdings rose 4.0% and both short-term and long-term borrowing continued to expand. Nikkei +0.91% to 66934, USDJPY -0.113% to 159.45, 10y JGB +1.9bp to 2.686%.
Japan’s manufacturing PMI eased to 54.5 points in May from a 51-month high of 55.1 in April. Nevertheless, it remained firmly in expansion territory, marking a fifth consecutive month of improving business conditions. Output and new orders continued to grow at historically strong rates, supported by robust domestic demand, inventory building and efforts by customers to secure supplies amid disruptions linked to the Middle East conflict. Export orders increased at the fastest pace in five years, helped by stronger demand for semiconductors and oil-related products. Manufacturers also raised purchasing activity at the fastest rate in four years, while supply chain delays remained severe and among the strongest outside the pandemic period. Inflationary pressures intensified further, with both input costs and selling prices rising at rates rarely exceeded in more than 24 years of survey history. Employment growth strengthened, although business confidence remained below its historical average due to geopolitical uncertainty and elevated costs.
South Korea’s exports, measured in USD, surged 53.0% y/y in May to a record $87.8bn, marking the third consecutive month above the $80bn threshold and highlighting the strength of the semiconductor-driven export cycle. Imports rose 20.8% to $60.8bn, resulting in a trade surplus of $26.95bn. Semiconductor exports jumped 169.4% to a record $37.2bn, supported by exceptional growth in DRAM and NAND shipments amid strong global AI-related demand. Computer exports rose 290.7%, while petroleum product exports were up 46.6% on higher oil prices, despite lower shipment volumes. By destination, exports to China climbed by 80.9%, shipments to the U.S. by 59.1% and ASEAN-bound exports by 58.4%. In contrast, auto exports fell 5.9% because of supply disruptions, fewer working days, Middle East shipping challenges and the impact of U.S. tariff policies, while steel and machinery exports also shrank. KOSPI +3.68% to 8788, USDKRW -0.11% to 1505.6, 10y KTB -8bp to 4.065%.
South Korea’s manufacturing PMI rose to 54.8 points in May from 53.6 in April, the highest reading since March 2021, signaling a further strengthening in manufacturing activity. Output and new orders expanded at their fastest rates in around five years, supported by stronger domestic demand and precautionary stock building as firms and customers sought to protect against supply disruptions and rising costs linked to the Middle East conflict. However, export orders edged down marginally for the first time since November. Purchasing activity increased at the fastest pace since July 2021, while supplier delivery times lengthened sharply amid ongoing logistical disruptions. Input cost inflation remained close to the survey’s record high, driven by higher raw material and oil prices alongside currency weakness, and selling price inflation remained among the strongest on record. Employment growth accelerated to its fastest pace since March 2013, while business confidence improved to a three-month high despite persistent cost and supply chain pressures.
South Korea’s foreign portfolio flows showed a sharp divergence between the main KOSPI market and the tech-focused KOSDAQ market during May. Foreign investors recorded net sales of KOSPI-listed stocks worth ₩44.7tn, the largest monthly outflow on record and exceeding the previous peak reached in March. Overseas investors were net sellers for 16 consecutive trading sessions, the longest streak since the aftermath of the global financial crisis in 2009. The selling was largely attributed to profit-taking following strong gains in major semiconductor stocks, including Samsung Electronics and SK Hynix. In contrast, foreign investors purchased a record ₩2.8tn of KOSDAQ shares, supported by expectations surrounding the newly launched Korea National Growth Fund, which targets sectors such as AI, batteries, hydrogen and biotechnology. Domestic retail investors helped offset foreign outflows, posting a record ₩36.1tn in net purchases during the month.
South Korea’s foreign exchange market will transition to near-24-hour won/dollar trading in July. Trading hours will be extended from the current 9 a.m. to 2 a.m. schedule to continuous operation from Monday morning to Saturday morning. Under the new framework, trading will run from 6 a.m. on Monday to 6 a.m. on Saturday during New York daylight saving time, and from 7 a.m. Monday to 7 a.m. Saturday outside that period. The reform is aimed at improving market accessibility, reducing transaction costs and enhancing convenience for domestic and overseas investors, exporters and importers. Authorities view limited trading hours as a key obstacle to South Korea’s ambition of gaining developed market status in global equity benchmarks. While won/dollar trading will become nearly continuous, settlement arrangements and trading hours for other currencies will remain unchanged and the benchmark closing exchange rate will continue to be determined at 3:30 p.m. local time during the daytime session.
The Philippines’ manufacturing PMI rose to 50.8 points in May from 48.3 in April, returning to expansion territory and signaling a modest improvement in operating conditions. The recovery was driven by renewed growth in output and new orders, supported by stronger domestic demand and new customer acquisitions, while production expanded at the fastest pace in three months. However, export demand remained weak, with new export orders falling at the sharpest rate since July 2020. Supply chain pressures intensified, with delivery times lengthening significantly due to shipping delays and order consolidation. Input cost inflation accelerated to its fastest pace since August 2022, reflecting higher fuel and raw material prices linked to the Middle East conflict, prompting firms to raise selling prices sharply. Despite the improvement in demand, purchasing activity declined for a third consecutive month, inventories were reduced aggressively and employment fell at the fastest pace in two years. Business confidence nevertheless improved to its highest level in 18 months on expectations of stronger future demand. PSEi +0.53% to 5799, USDPHP -0.205% to 61.722, 10y PHGB +0.1bp to 7.364%.
Taiwan’s manufacturing PMI rose to 56.1 points in May from 55.3 in April – its highest level since August 2021 and a sixth consecutive month of expansion. Output growth accelerated to its strongest pace since July 2021, while new orders increased at the joint-fastest rate since July 2021, supported by stronger domestic and overseas demand as customers built precautionary inventories amid concerns over supply disruptions and rising prices. Export orders expanded solidly, with gains reported across the U.S., Europe, Japan and mainland China. Purchasing activity and input inventories increased sharply as firms sought to build safety stocks, while supplier delivery times deteriorated to the greatest extent since March 2022. Cost pressures remained intense, with input price inflation among the strongest recorded in more than 22 years of survey history, prompting further sharp increases in selling prices. Employment was broadly unchanged, but business confidence improved to a two-year high on expectations of stronger demand from electronics and AI-related industries. TAIEX +1.35% to 45338, USDTWD +0.067% to 31.363, 10y TGB -2bp to 1.64%.
India’s final manufacturing PMI rose to 55.0 points in May from 54.7 in April, beating the flash estimate of 54.3 and signaling the strongest improvement in factory conditions in three months. Output and new orders expanded at the fastest pace since February, supported primarily by resilient domestic demand, infrastructure activity and new business gains, while export order growth remained solid but moderated. Manufacturers stepped up their purchasing activity and inventory accumulation, suggesting continued precautionary stockpiling amid uncertainty linked to the Middle East conflict. Input cost inflation remained among the strongest seen in four years, driven by higher energy, fuel, transport and raw material costs, although output price inflation slowed and lagged cost increases, implying some pressure on profit margins. Employment continued to grow at a solid pace, finished goods inventories rose at the fastest rate in 11 years and business confidence remained positive on expectations that cost pressures will ease and demand conditions will remain supportive. SENSEX -0.11% to 74692, USDINR +0.029% to 94.9763, 10y INGB +2.7bp to 7.031%.
Indonesia’s government has announced a revised export proceeds regime effective June 1, offering a 0% income tax rate on export earnings retained in the domestic financial system to encourage exporters to keep foreign exchange revenues onshore. Finance Minister Purbaya Yudhi Sadewa said the size of the tax incentive will depend on how long exporters maintain funds in Indonesian banks, with the policy aimed at strengthening foreign exchange reserves and improving domestic liquidity. Under the new rules, oil and gas exporters must retain at least 30% of export proceeds in Indonesian banks for a minimum of three months, while exporters of other natural resource commodities must place 100% of export earnings in designated domestic accounts for at least 12 months. The government also capped conversion of export proceeds into rupiah at 50%, although exporters covered by bilateral agreements or special trade arrangements will receive certain exemptions from the stricter retention requirements. JCI -0.05% to 6127, USDIDR -0.476% to 17874, 10y IDGB +1.1bp to 6.72%.
Thailand’s business sentiment index fell to 42.5 points in May from 43.5 in April, remaining well below the neutral 50-point threshold and indicating worsening sentiment. The Bank of Thailand data showed broad-based softness, with the performance, total order book and production components all declining m/m. Investment and employment improved slightly, but production costs remained elevated, despite easing vs. March. On a y/y basis, the overall index fell to -4.2 from -3.6 in April, suggesting sentiment deteriorated further versus a year earlier. The reading was also below market expectations of 46.9, pointing to continued weakness in Thailand’s business outlook. SET -0.04% to 1568, USDTHB +0.471% to 32.542, 10y TGN -2.3bp to 2.31%.