Market Movers: Widening Divide
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 6 minutes
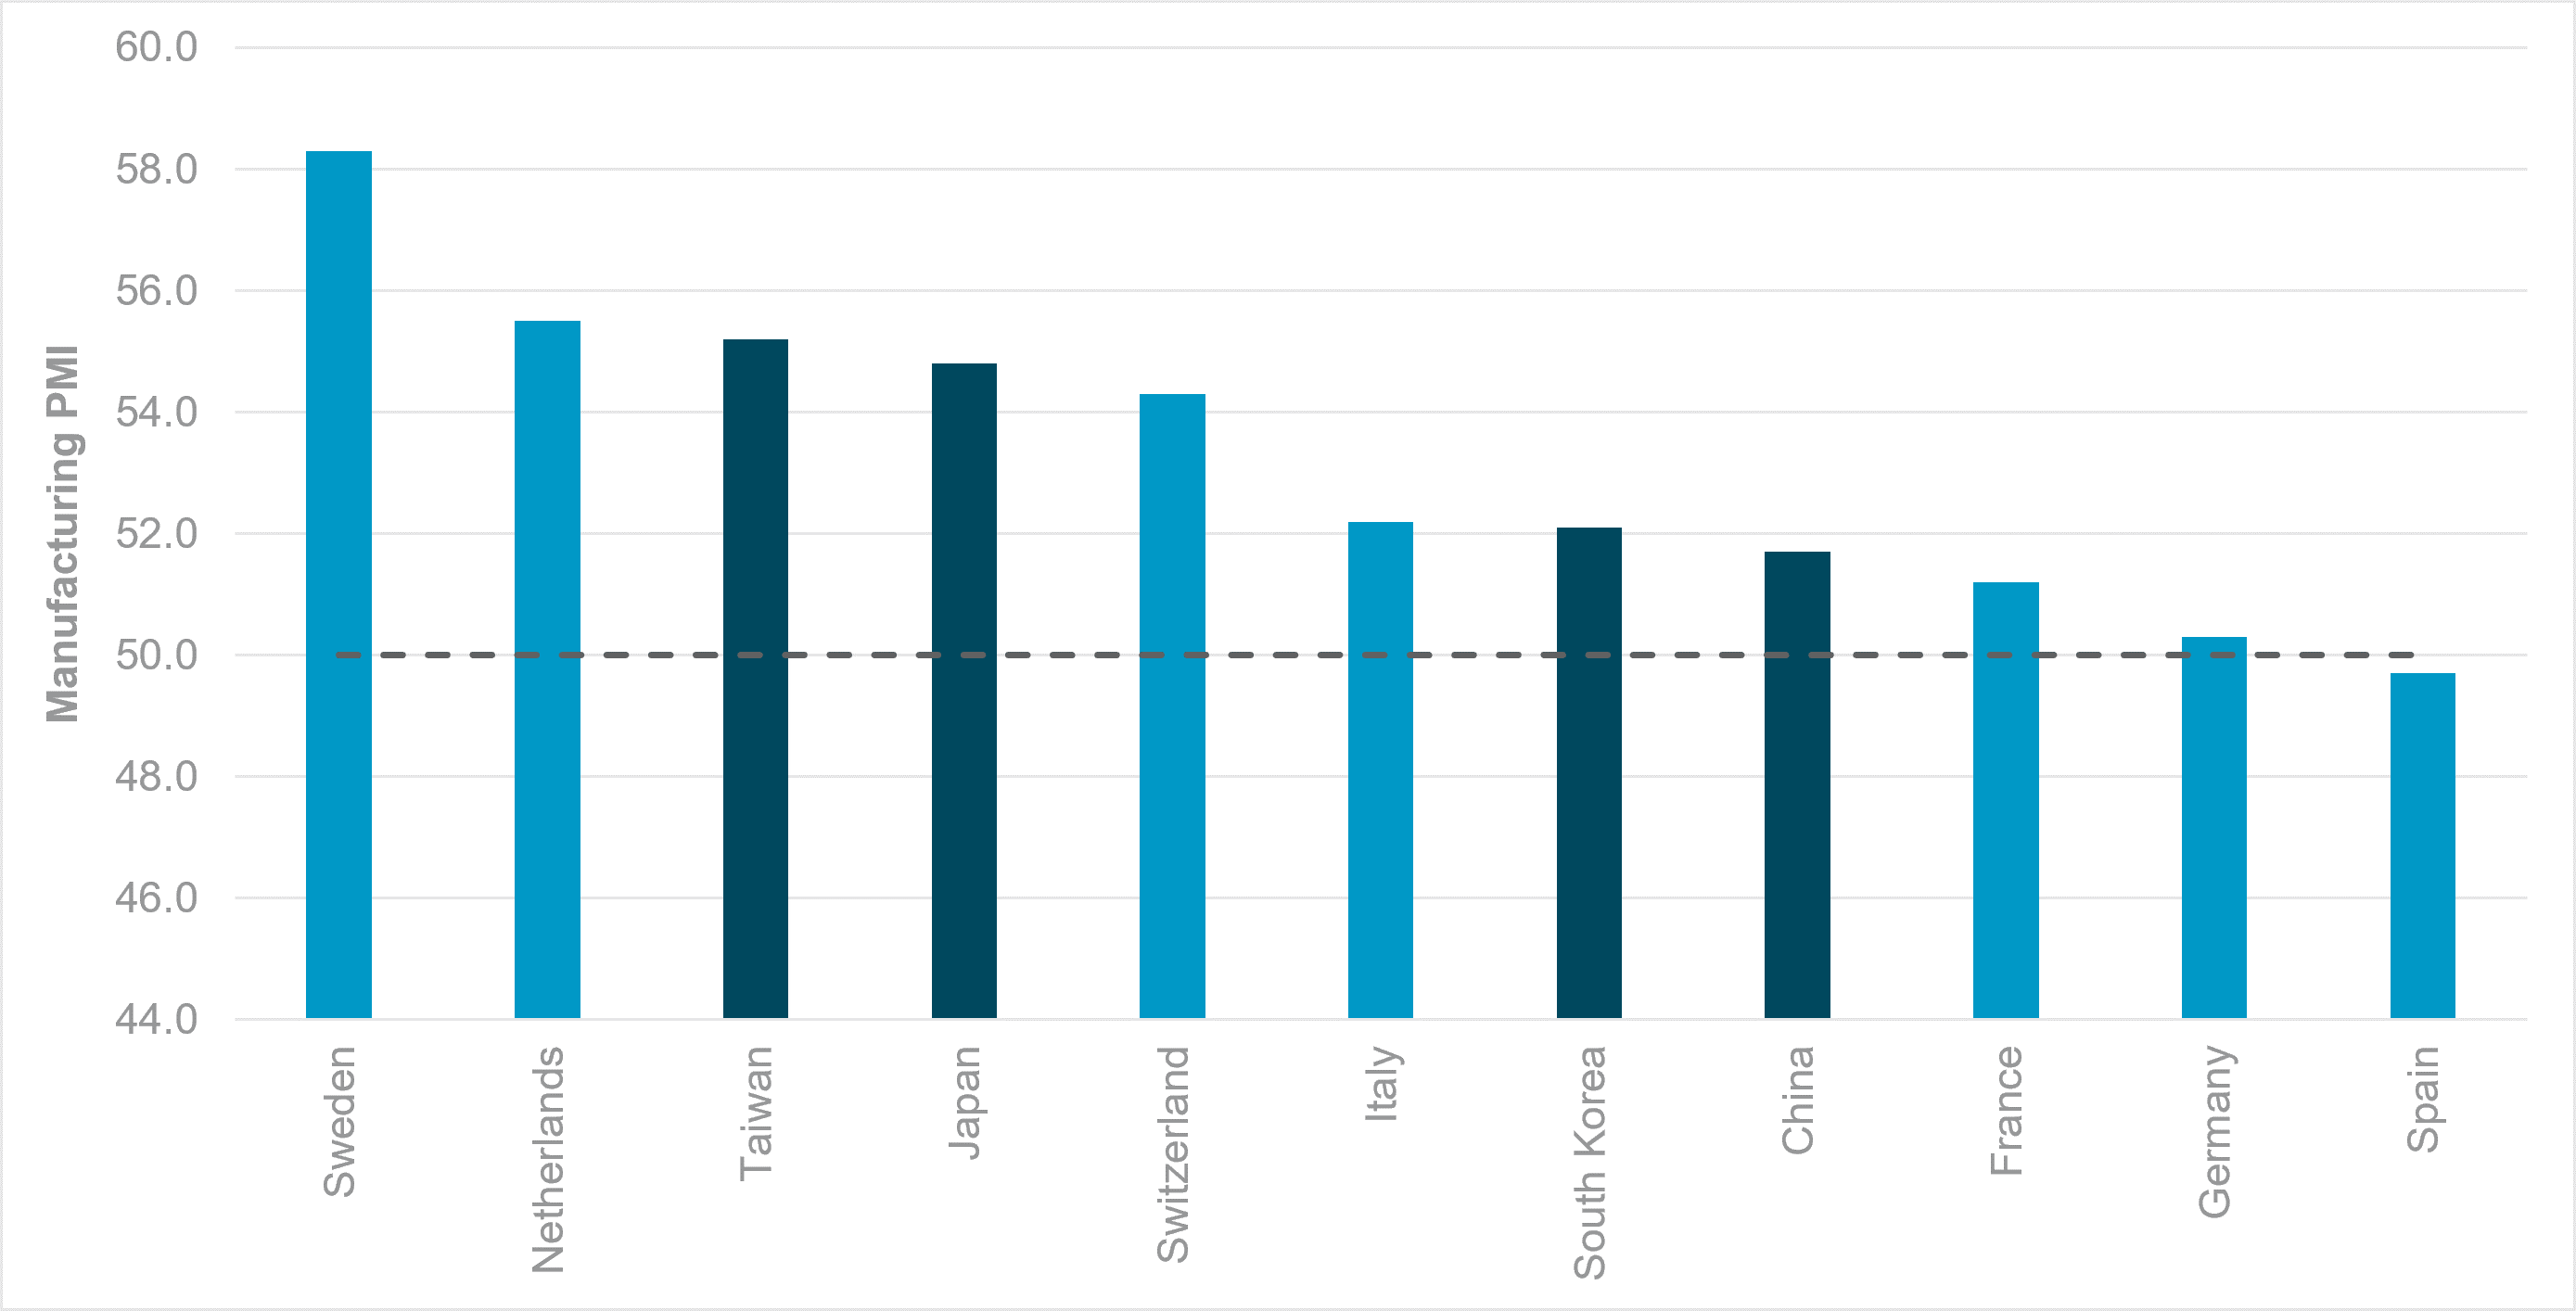
Manufacturing PMIs reveal a widening AI divide
Source: BNY
The June PMI reports for the world’s leading manufacturing economies highlight an increasingly fragmented global industrial cycle, with AI investment emerging as the key differentiator. Taiwan (55.2 points) and Japan (54.8) remain the standout performers, driven by “robust demand for AI-related technology and semiconductors.” Japan recorded its strongest quarterly performance since Q1 2014, while Taiwan posted its fastest output growth since July 2021. South Korea (52.1) continues to expand, albeit more slowly, as higher costs and softer exports weigh on momentum. China (51.7) is delivering steady, broad-based growth, supported by resilient domestic demand and easing cost pressures. Meanwhile, smaller advanced manufacturing economies – notably Sweden (58.3), the Netherlands (55.5) and Switzerland (54.3) – continue to outperform, reflecting their strength in high-value manufacturing and capital goods. AI investment is increasingly creating structural winners rather than lifting the entire global manufacturing cycle.
The euro area’s largest industrial economies present a much less convincing picture. Germany (50.3) is stabilizing rather than recovering, France’s 51.2 headline PMI masks falling output and orders, Italy’s expansion (52.2) is losing momentum as inventory support fades and Spain has slipped back into contraction (49.7). As the German PMI report noted, firms are “partly relying on backlogged orders to support output, which isn’t sustainable in the long run.” While the strain from input cost inflation and supply chain disruptions has started to ease as energy prices have softened, underlying demand remains weak.
Unlike Asia’s AI-led manufacturing upswing, much of Europe’s resilience still reflects precautionary stock-building linked to the Middle East supply shock rather than a sustained investment cycle. The Netherlands is the notable exception, where demand for semiconductor equipment has helped decouple manufacturing performance from the rest of the currency bloc.
AI investment is no longer simply supporting the technology sector: it is increasingly shaping the global manufacturing cycle itself. Economies with significant exposure to semiconductors, AI infrastructure and advanced capital goods continue to outperform, while those reliant on a broader cyclical recovery remain constrained by weak underlying demand. The latest PMI data therefore point to a structurally fragmented industrial landscape rather than the start of a synchronized global manufacturing rebound. North Asia’s leadership is well-established, but the divergence within Europe is particularly striking: the strength of the Netherlands and Sweden contrasts sharply with the subdued performances by Germany, France and Spain. This underscores that exposure to AI-driven investment has become a more important determinant of manufacturing performance than geography alone.
South Korea’s entry into the $100bn-a-month export club is also likely to intensify scrutiny of regional currency valuations. At the current pace, the country’s current account surplus is on track to move comfortably into double-digit territory as a share of GDP, implying an annual surplus well above $300bn. U.S. Treasury Secretary Scott Bessent remarked as recently as January that USD/KRW was “not in line” with South Korea’s strong economic fundamentals, but the won has weakened by more than 6% since then. Japanese FX policy head Atsushi Mimura’s overnight defense of the “effectiveness” of the country’s interventions looks less credible with each tick higher in USDJPY. U.S. interest rate dynamics, supply chain resilience and broader strategic considerations all remain important, but these external imbalances sit uneasily alongside an administration that continues to prioritize re-shoring. Sustained tolerance of KRW, TWD and JPY weakness could also complicate Washington’s criticism of China’s trade practices, particularly with the renminbi having appreciated by more than 10% against the won this year.
Attention now turns to Sintra, where Kevin Warsh joins Andrew Bailey, Christine Lagarde and Tiff Macklem for the ECB’s flagship policy panel. Given the setting, Warsh is unlikely to deviate from the Federal Reserve’s recent “talk less” communications strategy or provide fresh policy guidance. Instead, the focus will be on any assessment of the U.S. labor market and whether officials continue to view it as consistent with inflation returning sustainably to target. Recent labor market signaling remains mixed. Challenger job cuts continued to stabilize, but the report also pointed to increasingly modest hiring intentions, in a break with the post-2020 trend. For markets, the key question is not the pace of layoffs but whether softer hiring ultimately proves sufficient to cool wage growth and ease inflation pressures.
U.S. job cuts in June came in at 45,849, down 53% from May and 4% from a year earlier, according to Challenger, Gray & Christmas. That was the smallest monthly total since December 2025 and left first-half layoffs at 443,604 – still the second-highest January-June tally since 2020. The firm said layoffs cooled in line with typical summer patterns, but technology remained the main source of cuts as artificial intelligence continued to reshape staffing decisions. Tech announced 15,503 cuts in June, while AI was cited as the leading reason for job losses, accounting for 14,029 cuts in the month and 101,743 so far this year. Hiring plans also fell in June. S&P Mini -0.29% to 7526, DXY +0.15% to 101.338, 10y UST -0.6bp to 4.459%.
U.S. negotiators Jared Kushner and Steve Witkoff have reportedly held positive talks in Doha with regional leaders as indirect U.S.-Iranian negotiations continued to advance. The discussions focused on easing tensions after recent clashes had threatened a fragile ceasefire, with lower-level technical talks also making progress. However, major issues remain unresolved, including the release of Iranian assets and the future management of the Strait of Hormuz, a critical route for global energy supplies. Qatar has downplayed expectations of direct meetings, while reports suggest Washington is open to extending negotiations beyond the current deadline if needed. Brent -0.919% to 72.28, WTI -0.95% to 68.84, Omani crude +0.742% to 65.2, Dubai crude -0.186% to 68.27.
Japan’s currency chief Atsushi Mimura has said past intervention to support the yen was effective, as the currency slid to a fresh four-decade low of close to 162.70 to the dollar. This raises the inflation risks for an import-dependent economy. He said he has been in frequent contact with officials in Washington and that the U.S. has not objected to Japan’s actions, with some comments appearing supportive. Mimura indicated that intervention remains a useful tool against excessive currency moves, while stressing that Tokyo and Washington remain broadly aligned on foreign exchange policy. He also noted that softer oil prices and lower-than-expected inflation may reduce pressure on the BoJ to tighten policy further. Nikkei +0.59% to 70475, USDJPY +0.068% to 162.66, 10y JGB +2.8bp to 2.711%.
U.K. Labour Party MPs are reportedly lobbying for Work and Pensions Secretary Pat McFadden to be appointed chancellor if Andy Burnham becomes prime minister, reflecting concerns about the prospect of Energy Secretary Ed Miliband taking the role. Several MPs described McFadden as a safe and credible choice who would reassure markets and voters, while arguing that Miliband’s appointment could prove divisive and undermine Labour’s political momentum. Critics also warned that Miliband’s opposition to new North Sea oil developments could damage Labour’s prospects in Scotland. Although Miliband retains support from some trade unions, others have questioned his economic priorities and the potential impact of his net zero agenda on jobs and energy security. FTSE 100 -0.07% to 10490, GBPUSD -0.114% to 1.3247, 10y gilt +3.6bp to 4.793%.
Bundesbank President Joachim Nagel said the ECB is keeping all options open for its July and September meetings, as policymakers assess the inflation impact of geopolitical tensions in the Middle East and the recent drop in oil prices. Speaking in Sintra, he said the fall in oil prices was a surprise but its durability remains uncertain, especially given possible outcomes from U.S.-Iranian diplomacy. He stressed that he would not speculate on future rate hikes and described the policy outlook as an open race. Nagel also said he does not yet see wage second-round effects from the conflict, even as markets still expect one more hike this year. Other ECB Governing Council members were more circumspect, with Pierre Wunsch demanding evidence of “stronger second-round effects” and Martin Kocher stating that the inflation threat was “lower” but not “completely contained.” Euro Stoxx 50 -0.02% to 6327, EURUSD -0.219% to 1.1397, BBG AGG Euro Government High Grade EUR +0.3bp to 3.163%.
U.S. June ADP employment change is forecast to ease to 119k vs. 122k.
U.S. June final S&P Global Manufacturing PMI is forecast to hold at 55.7 vs. 55.7.
U.S. June ISM Manufacturing is forecast to ease to 53.9 vs. 54.0. ISM Prices Paid is forecast to ease to 77.5 vs. 82.1.
U.S. May construction spending is forecast to ease to 0.2% m/m vs. 0.4% m/m.
Central bank speakers: four central bank heads – the ECB’s Christine Lagarde, the Fed’s Kevin Warsh, the BoE’s Andrew Bailey and the BoC’s Tiff Macklem – will speak at the ECB Forum.
U.S. Treasury sells 17-week bills.
Mood: The iFlow Mood index very modestly improved to -0.114, but continued outflows from global equities kept it negative.
FX: USD, TWD and NOK saw sizable inflows, while HUF and SGD recorded outflows. CHF, which had seen inflows over the prior week, posted outflows yesterday.
FI: Global sovereign bond inflows continued, with inflows across broad developed markets. One notable exception was Norway, which saw outflows despite inflows into the krone.
Equities: Selling pressure on global equities moderated slightly but persisted, with Japan and South Korea recording continued outflows.
“The difficulty lies not so much in developing new ideas as in escaping from old ones.” – John Maynard Keynes
“The world is on a bumpy journey to a new destination.” – Mohamed El-Erian
The euro area flash inflation estimate for June came in at 2.8% y/y, down from 3.2% in May. The fall suggests price pressures eased across the bloc, with energy remaining the largest contributor at 8.7%, though this was well below May’s 10.8%. Services inflation also moderated to 3.2% from 3.5%, while food, alcohol and tobacco slowed to 1.6% from 1.9%. Non-energy industrial goods were stable at 0.9%. On a m/m basis, the headline HICP is estimated to have slipped 0.1%, indicating softer price momentum. Euro Stoxx 50 -0.02% to 6327, EURUSD -0.219% to 1.1397, BBG AGG Euro Government High Grade EUR +0.3bp to 3.163%.
Germany’s manufacturing PMI for June came in at 50.3 points, up from 50.1 in May, indicating a marginal improvement in business conditions at the end of Q2. Output rose modestly, supported by a slight increase in new orders and a continued drawdown of backlogs, while export sales also returned to marginal growth. Cost pressures eased vs. May, with input and output inflation both slowing to their weakest pace in three months as some oil-related relief fed through. Supply delays improved to a four-month low, but employment fell again, taking its sequence of decline to three years. Business expectations edged higher, though sentiment remained subdued overall. DAX +0.37% to 25088, EURUSD -0.219% to 1.1397, 10y Bund +1.9bp to 2.879%.
France’s manufacturing PMI for June came in at 51.2 points, up from 49.7 in May, indicating a return to marginal growth after two months of weakness. S&P Global said output and new orders still fell, with export demand particularly soft, but the pace of decline eased. Firms reported the worst delivery delays in nearly four years, suggesting supply chains remained under strain, while inventories and purchasing were scaled back as companies used existing stock. Employment edged higher, and business confidence improved to a 12-month high. Price pressures also cooled, with input cost and output price inflation easing, which points to some relief for manufacturers and possibly broader inflation. CAC 40 -0.28% to 8380, EURUSD -0.219% to 1.1397, 10y OAT +2.7bp to 3.679%.
U.K. house prices rose 2.2% y/y in June, accelerating from 1.7% in May, while the seasonally adjusted monthly change was broadly flat at 0.0% and the average price eased to £277,484 from £278,024. Nationwide said the market had softened recently amid Middle East uncertainty, higher energy prices and firmer market interest rates, which weighed on confidence and mortgage approvals. However, it noted that lower-than-expected inflation and easing oil prices could reduce pressure on the BoE. By region, all areas posted y/y gains in Q2, led by Northern Ireland at 8.6%, while the Outer South East was weakest at 0.1%. FTSE 100 -0.07% to 10490, GBPUSD -0.114% to 1.3247, 10y gilt +3.6bp to 4.793%.
The U.K. June manufacturing PMI was 52.5 points, easing from 53.9 in May but still indicating expansion and an eighth straight month above 50. The sector ended Q2 on a positive note as output growth accelerated to a 21-month high, helped by client stockpiling, better confidence and promotions. However, new order growth slowed to its weakest since December 2025, suggesting momentum is fading. Export demand rose only modestly, while employment increased for a third month at a subdued pace. Input cost inflation remained elevated but eased, and factory selling price inflation also moderated. Overall, the survey points to improving activity but a still-cautious outlook.
Swiss June PMI data showed the economy remaining in expansion. The procure.ch manufacturing PMI fell 3 points to 54.3 but stayed comfortably above the 50-point threshold, while the services PMI rose to 59.8, its strongest level in more than four years. In manufacturing, output stayed near a four-year high at 57.0 and order books remained firm, though momentum eased vs. May. Input prices and delivery times continued to rise, but more slowly, and some firms reported lower petroleum-related prices after weaker oil markets. Services growth was broad-based, led by stronger new orders and backlogs, though employment softened further, suggesting mixed labor demand. SMI -0.05% to 14186, EURCHF -0.041% to 0.92286, 10y Swiss GB +1.2bp to 0.302%.
Sweden’s manufacturing PMI for June rose to 58.3 points from 57.4 in May, marking a fourth straight m/m increase and the strongest reading of the year. The survey pointed to a broadening industrial recovery, led by a sharp pickup in new orders and supported by higher production, while employment and planned output also remained firmly in expansion territory. At the same time, supplier delivery times remained elevated, signaling ongoing supply chain strain. The report also highlighted persistent cost pressures, with input price inflation holding near multi-year highs at 81.3, suggesting rising industrial inflation risks if global raw material costs and geopolitical disruptions remain elevated. OMX -0.21% to 3196, EURSEK +0.209% to 11.1042, 10y Swedish GB +2.3bp to 2.694%.
Japan business sentiment improved in the June Tankan survey, with the headline diffusion index for all firms rising to 18 points from 11 in March. Manufacturers and non-manufacturers both strengthened. Large firms saw manufacturing sentiment climb to 22 and non-manufacturing to 37, while the all-industry reading reached 29. Looking ahead, most gauges point to some softening, but levels remain positive. Price indicators remained elevated, with selling price and input price judgments both high, while business plans showed solid growth in sales, profits and investment. Large firms are planning higher capital spending, and software and research outlays remain firm. Employment conditions were still tight, though slightly less severe than before. Nikkei +0.59% to 70475, USDJPY +0.068% to 162.66, 10y JGB +2.8bp to 2.711%.
The Japanese manufacturing PMI for June was 54.8 points, up from 54.5 in May, signaling a sixth straight month of expansion and the strongest quarterly performance since Q1 2014. The survey showed solid gains in production and the fastest rise in total new orders since early 2022, supported by stronger underlying demand and some client stockpiling amid Middle East war-related supply disruptions. Export orders also increased, though more slowly than total sales. Supply chain strain remained severe, with vendor shortages and shipping delays extending lead times. Input and output price inflation remained elevated, while employment rose at a brisk pace and backlogs continued to build.
Australian dwelling approvals fell 1.1% m/m in May to 17,019, while remaining 5.3% higher than a year earlier. The decline was driven by a 10.4% drop in private sector dwellings excluding houses after an April rebound, as apartment approvals softened sharply. In contrast, private sector house approvals rose 2.8% to 10,537, the highest level since September 2021 and the fourth straight month above 10,000. The total building value climbed 13.6% to a record AU$21.07bn, led by a surge in non-residential approvals, especially large data center projects in New South Wales and Victoria. ASX -0.01% to 5635, AUDUSD -0.376% to 0.6893, 10y ACGB +6.5bp to 4.787%.
South Korea’s manufacturing PMI for June came in at 52.1 points, down from 54.8 in May, signaling a still-expanding but softer improvement in factory activity. Output growth eased to a five-month low, and new orders rose at the slowest pace so far this year, with export orders falling for a second straight month. Producers cited higher raw material costs, supply chain delays, shortages and a weaker won as key constraints. Employment declined for the first time in four months, backlogs rose strongly and business optimism fell to a seven-month low on concerns over domestic demand and persistent price pressures. KOSPI -2.04% to 8303, USDKRW +0.359% to 1554.8, 10y KTB -7bp to 4.07%
South Korean exports totaled $102.25bn in June. This took the country into the world’s $100bn/month export club for the first time, becoming only the fourth nation to do so. Shipments rose 70.9% y/y, driven overwhelmingly by semiconductors, which jumped 199.5% to $44.8bn and made up 43.8% of total exports. Almost all major export categories expanded, while the trade balance stayed in surplus for a 17th straight month and the record surplus exceeded $30bn. First-half exports also hit a new high of $496.7bn, up 48.4% y/y, although officials warned that the second half remains uncertain.
China’s RatingDog general manufacturing PMI for June came in at 51.7 points, down slightly from 51.8 in May. This still represented a seventh straight month of expansion and the strongest Q2 showing since Q4 2020. Output continued to rise, although at a three-month low, while total new orders increased for the thirteenth consecutive month and employment grew at the fastest pace since August 2023. Input cost inflation eased to a five-month low, helping to temper cost pressures, even as output prices rose modestly. Export orders softened again and business confidence slipped to its weakest level since January, suggesting a still-resilient but more cautious manufacturing outlook. CSI 300 -0.41% to 4959, USDCNY +0.093% to 6.7933, 10y CGB +1.1bp to 1.74%.