Market Movers: Vigilantes
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoff Yu
Time to Read: 6 minutes
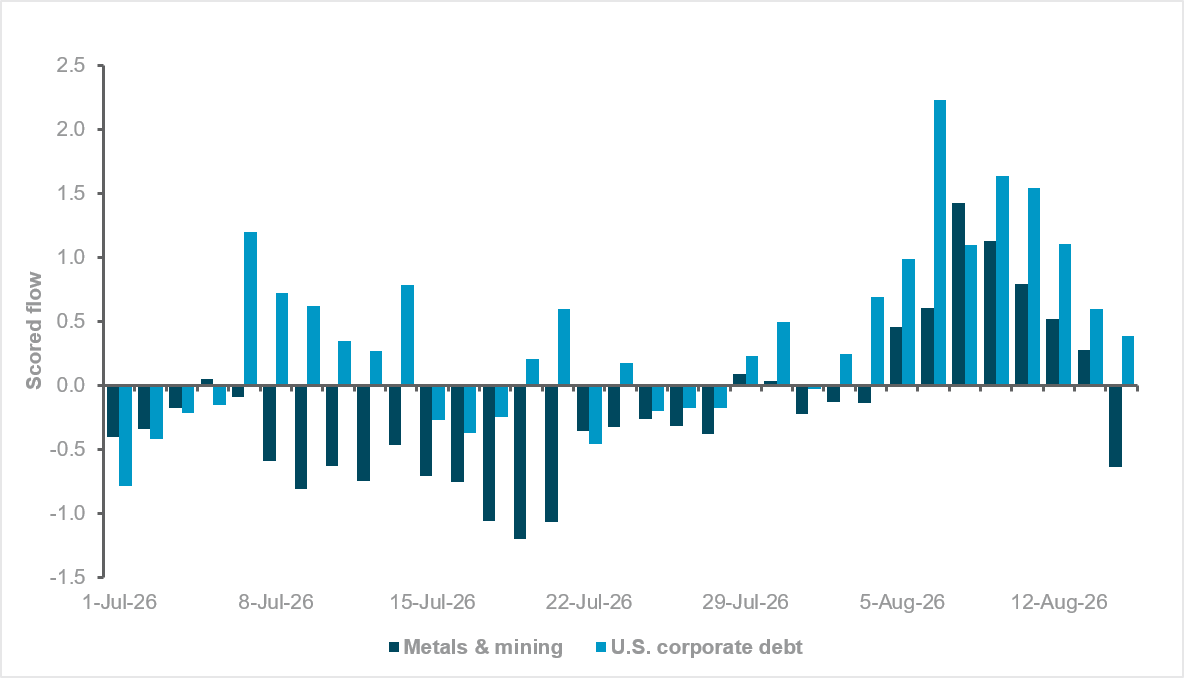
Gold and U.S. corporate bonds benefit from inflation fear
Source: BNY
Gold and corporate bonds have emerged as the surprising winners from the latest rise in inflation risk, even as the traditional cross-asset inflation trade remains fractured. Gold is providing the clearest expression of inflation concern: the global Metals & Mining flow proxy (GICS level 3) has surged over the past two weeks, with the July FOMC marking a decisive shift from selling into strong August buying. That contrasts sharply with commodity FX and broader duration, where flows remain weak or inconclusive. Investors therefore appear to prefer explicit inflation protection through gold rather than positioning for a broader reflationary upswing. However, with yields moving sharply higher, the metal could struggle in the near term, unless monetary policy remains far more dovish than expected.
More unexpectedly, U.S. corporate bonds have also attracted strong inflows, including maturities beyond three years. Demand accelerated after the July Fed meeting and has remained robust, suggesting that fears of issuance-driven indigestion – particularly from tech and AI – remain contained. Yet this is not simply a risk-on signal. Wider spreads further out the curve indicate investors are demanding greater compensation for both duration and credit exposure. Corporate bonds are therefore benefiting from a combination of higher yields, additional spread compensation and still-healthy underlying demand, making credit an unusual beneficiary of rising inflation uncertainty and potentially a cleaner indicator than government bonds of where investors are willing to absorb higher risk premia.
Treasury signal: Bond prices are sending warnings. The 30y U.S. Treasury yield has moved above 5.3%, its highest since 2007. The long end is increasingly managing financial conditions even as U.S. data suggest the Fed may need to behave differently. Fiscal supply, term premium and inflation risk are increasingly setting the price. Persistent Middle East tensions are keeping crude elevated, adding another supply-driven inflation risk to already stretched long-end markets.
European pressure: The selloff is global. German borrowing costs are at multi-year highs, with the long end trading around levels last seen in 2011, while the 30y gilt yield remains within touching distance of 6%. Higher term premia are tightening financial conditions independently of the ECB or BOE, neither of which appears eager to respond with additional rate cuts.
Japan tested: JGBs remain another pressure point. The 10y yield is approaching 3%, its highest in three decades, as markets weigh inflation against fiscal expansion, weak growth and a constrained central bank. Japan increasingly shows what happens when investors demand a larger premium before policymakers are willing to act.
Reflation risk: China has so far been an important disinflationary force for the global economy, but Beijing is strengthening its language on growth after another weak set of activity data. The late-August legislative session will test whether rhetoric turns into stronger support. Reflation would be welcome domestically, but less helpful for global bonds if stronger Chinese demand weakens the disinflationary impulse from goods prices.
Bottom line: The vigilantes aren’t waiting for central banks – and central banks don’t appear eager to follow them. Long-end yields are tightening conditions, while policy rates remain comparatively anchored. Add fiscal supply, oil and the risk of Chinese reflation, and the burden increasingly falls on governments to convince bondholders that current yields offer enough compensation.
Brent crude rose as much as 1.1% to $91.85/bbl on Tuesday, its highest level in more than three weeks, as hopes for a rapid reopening of the Strait of Hormuz faded. President Trump said he will not seek to revive the expired U.S.–Iran truce, leaving the conflict and control of the vital shipping route unresolved. Washington is demanding unrestricted passage through the strait, while Iran says traffic should be managed jointly with Oman. Shipping activity remains heavily disrupted and fresh attacks near the strait have reinforced supply concerns. Trump said U.S. leverage over Iran remains substantial and claimed back channels are open, though Tehran disputed this. The unresolved standoff keeps oil vulnerable to renewed escalation and prolonged disruption. Brent +0.408% to $91.24, WTI +0.9% to $85.26, Omani Crude +0.423% to $90.24, Dubai Crude +2.052% to $87.058.
Global long-term bond yields have surged to multi-year or multi-decade highs as investors demand more compensation for inflation risk, heavy government borrowing, rising corporate issuance and a changing buyer base. The 30y Treasury yield reached around 5.32%, its highest since 2007, while long-dated French, German, U.K. and Japanese yields also climbed sharply. The selloff reflects more than just inflation expectations: real yields and term premia are rising as governments issue more debt, pension demand weakens, and private investors become more price-sensitive. Record corporate borrowing, especially to fund AI investment, is adding further duration supply. The broader implication is a structurally higher cost of long-term financing for governments, companies and households, with fewer reliable buyers absorbing supply. S&P 500 E-Mini -0.54% to 7,727, DXY +0.03% to 99.666, 10y UST +1.2bp to 4.734%, 30y UST +1.2bp to 5.321%.
The U.K. government is examining the economic and security risks of Britons losing access to frontier AI models, according to people familiar with the matter. The Cabinet Office has asked the Department for Business and Trade and the Department for Science, Innovation, and Technology to assess the potential damage to growth, business productivity, cybersecurity and national resilience if access to new models is restricted, with the review due within weeks. The concern intensified after Trump’s June directive raised the prospect of limited foreign access to Anthropic’s Claude Fable 5 model. Officials said Britain is also investing in domestic capability through its AI hardware plan and sovereign AI fund. FTSE 100 -0.13% to 10,706, GBPUSD -0.119% to 1.3528, 10y gilt +2.3bp to 5.083%.
German business closures rose sharply in 2025, with almost 190,000 firms ceasing operations, up about 10% from the previous year and marking a second straight annual increase, according to calculations by ZEW and Creditreform. The report points to a widening economic strain in Germany, driven by insolvencies and skilled worker shortages, high costs, and a growing inability to find successors as owners retire. ZEW said the pressure on companies to adapt has intensified, while Creditreform noted that many small- and medium-sized firms are quietly disappearing. The closures were broad based, affecting industry, hospitality, and health care, underscoring weakness beyond the auto sector. DAX -0.57% to 26,188, EURUSD -0.061% to 1.1573, 10y Bund +3bp to 3.251%.
U.S. ADP Weekly Employment Change, 8.25k prior.
U.S. August New York Fed Services Business Activity, 8.7 in July.
U.S. July Import Price Index is forecast at 0.1% m/m, 6.7% y/y vs. 0.3% m/m, 7.1% y/y in June. U.S. July Import Price Index ex Petroleum is forecast to ease to 0.1% m/m vs. 0.5% m/m. U.S. July Export Price Index is forecast at 0.0% m/m vs. -0.6% m/m in June.
U.S. July Housing Starts is forecast to ease to 1345k vs. 1427k.
U.S. July preliminary Building Permits is forecast to hold at 1374k.
U.S. July Industrial Production is forecast to rise to 0.3% m/m vs. 0.1% m/m.
U.S. July Manufacturing Production is forecast to rise to 0.2% m/m vs. 0.0% m/m.
U.S. July Capacity Utilization is forecast to rise to 76.3% vs. 76.1%.
U.S. July Pending Home Sales, -5.4% m/m in June.
Canada July Existing Home Sales, 0.5% m/m prior.
Canada July Housing Starts is forecast to rise to 250.0k vs. 239.0k.
Central bank speakers: ECB’s Philip Lane speaks in Dublin.
U.S. Treasury sells $95bn in 6-week bills.
Mood: Risk sentiment improved as demand strengthened for both core sovereign bonds and global equities. iFlow Mood stood at -0.127, with bond demand leading.
FX: Strong LatAm currency demand contrasted with mixed-to-negative flows elsewhere. JPY and CNY outflows persisted.
FI: Demand was broad for major government bonds, led by U.K. gilts, Eurozone sovereigns and U.S. Treasurys. Chinese and Peruvian government bonds saw the heaviest selling.
Equities: Regional divergence remained pronounced. EM APAC led inflows, particularly Taiwan and Malaysia. G10 and EMEA flows were mixed, with strong buying in U.S., Polish and Turkish equities versus selling in Australia. LatAm equities saw outflows.
“John Bull can stand many things, but he cannot stand two per cent.” – Walter Bagehot
“In economics, interest rates act as gravity behaves in the physical world.” – Warren Buffett
U.K. labor market data for April to June 2026 showed a softer tone, with payrolled employees falling by 86,000, or 0.3%, from a year earlier and by 37,000 over the quarter, while the early July 2026 estimate was down 94,000 y/y to 30.3 million. The employment rate for people aged 16 to 64 edged up to 75.1% on the quarter but was down 0.2 percentage points on the year, and unemployment rose to 4.9%, with inactivity broadly unchanged at 20.9%. Vacancies fell to 707,000, and claimant count declined to 1.665 million in July. Pay growth remained positive, with regular earnings up 3.5% and real regular pay up 0.5%. FTSE 100 -0.13% to 10,706, GBPUSD -0.119% to 1.3528, 10y gilt +2.3bp to 5.083%.
ZEW German investor sentiment rose for a fourth consecutive month in August, with the expectations index climbing to 34.2 from 26.3 in July and beating the 30.0 consensus forecast. The improvement suggests confidence is continuing to recover as the economy absorbs some of the shock from the Iran war, supported by strong corporate earnings, robust exports and expectations of additional support from government infrastructure spending. Sentiment nevertheless remains below its February level, before the first U.S. and Israeli strikes on Iran, indicating that geopolitical damage has not fully reversed. Germany's economy grew 0.2% in Q2, better than initially feared, but record-low Rhine water levels now present a fresh downside risk by disrupting shipping and industrial activity. DAX -0.57% to 26,188, EURUSD -0.061% to 1.1573, 10y Bund +3bp to 3.251%.
Australia’s August consumer sentiment improved, with the Westpac–Melbourne Institute Consumer Sentiment Index rising 6% to 88.9 from 83.9 in July. The gain was driven mainly by households with mortgages after the Reserve Bank of Australia’s (RBA) decision to hold rates, while renter sentiment slipped slightly overall. Despite the uplift, sentiment remains pessimistic and below last year’s levels, with pessimists still outnumbering optimists, especially on current finances. Forward-looking views improved less than current-condition measures, suggesting uncertainty – including about the Middle East – is still weighing on consumers. Unemployment expectations rose above the long-run average, partly reversing July’s decline, while house price expectations fell as the market weakened. Most respondents still expect further mortgage rate rises, though fewer were unsure after the RBA meeting. ASX +0.12% to 5,794, AUDUSD -0.309% to 0.7103, 10y ACGB +5.5bp to 5.097%.
New Zealand’s central bank data show foreign investors held 58.9% of government bonds in July 2026, up from 57.7% in June. Nonresident holdings rose to NZ$122.47bn from NZ$115.53bn, while non-resident repo holdings edged down to NZ$11.02bn from NZ$11.09bn. The NZD itself is now trading slightly above the rolling 12-month average, but we continue to doubt the current market pricing of interest rates expectations, where two more Reserve Bank of New Zealand (RBNZ) hikes are expected by year end. Domestic activity remains robust, but inflation expectations remain relatively well-anchored. Nontradables inflation is relatively stable, and if the RBNZ looks past headline price risks, the domestic case for tightening softens considerably. NZX 50 +1.05% to 13,866, NZDUSD -0.744% to 0.5877, 10y NZGB +2.5bp to 4.742%.