Market Movers: Value
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
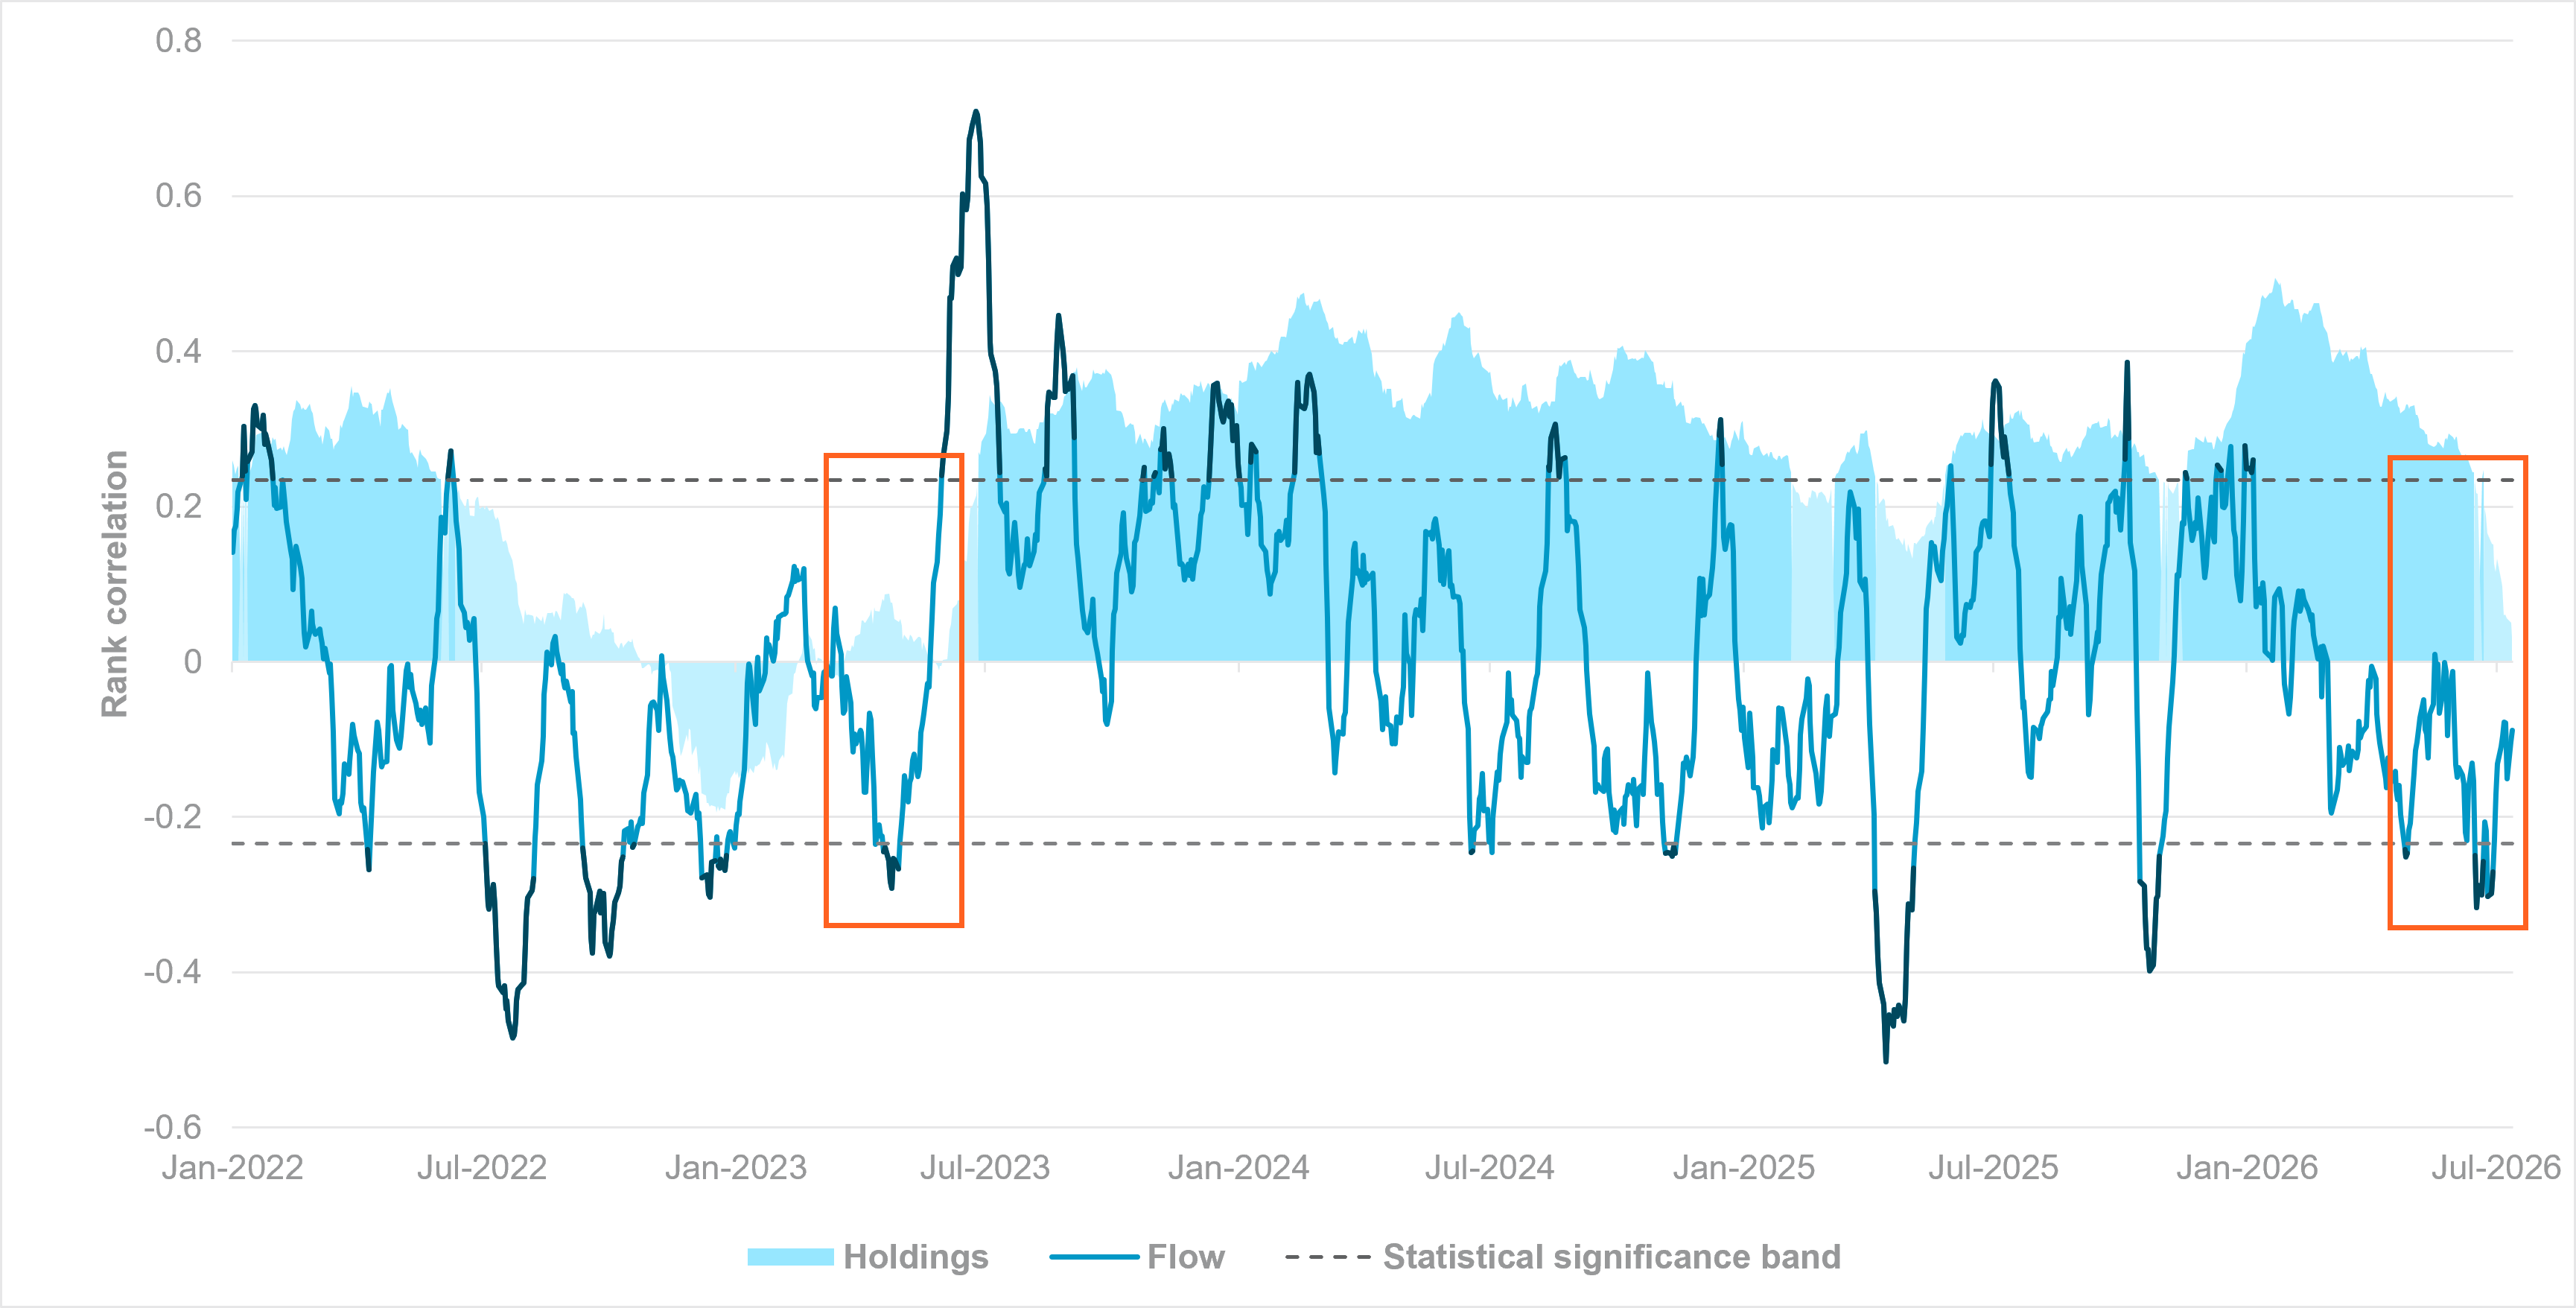
iFlow Carry setup now resembling beginning of carry trade surge in 2023
Source: BNY, GPIF
iFlow Carry resembles the heyday of 2023. In June, we highlighted that iFlow Carry had moved into statistically significant negative territory, which could signal improved risk appetite ahead. That analysis was based purely on flows, and we continue to take the view that a period of positive significance, where flows align with yield, is possible. Strikingly, the June carry sell-off also pushed carry holdings toward neutral for the first time since Q2 2023, confirming the setup.
Neutral holdings create room for carry to rebuild. Because carry currencies offer high yields relative to funders, including the dollar, their holdings stance usually remains in positive statistical significance. The group rarely stays neutral for long unless risk conditions are exceptional. Flat holdings provide an “amplification” effect for carry performance because positioning barriers are low. This was the exact setup for iFlow Carry in 2023, before the indicator rose to a historical record of almost 0.80. The global policy cycle is different now, but there should be comparatively limited resistance to rebuilding these positions.
Putting this view into practice means that carry can broaden beyond Latin America FX – the only region which has held onto positive holdings through the year. We favor selective EM APAC high-yielders where balance-of-payments relief provides support for real rates, and use EMEA duration as the cleaner expression where FX remains constrained.
Value has not disappeared, but verified growth is getting harder to buy cheaply. Warren Buffett’s point about “everybody gambling” is simple: when too many investors are chasing risk, genuine bargains become harder to find. That tallies with the current setup: the strongest growth engines are still delivering, but the cost of owning them has risen.
Earnings are constructive. U.S. banks and TSMC confirm that the core AI-led growth story remains intact, with resilient capital markets activity, stable client demand and strong AI-linked semiconductor demand. This is not a market built only on hope. However, confirmation is arriving only after investors have already crowded into the same winners. Good news validates the narrative but does not automatically create fresh value.
Risks are also still being discounted too easily. Middle East escalation is not dominating cross-asset pricing because energy markets absorbed the initial shock. But that resilience has relied on softer demand, alternative supply and inventory buffers. If those supports fade, the market’s relaxed treatment of geopolitical risk could look complacent. South Korea is sending a similar warning: policymakers accept the AI and chip story and have hiked rates to reflect stronger growth, but they are moving to limit speculative leverage around it.
Growth is being verified, FX carry is working and earnings are supporting the cycle. On the flipside, geopolitical risks are underpriced, speculative leverage is drawing policy attention and the best assets are already trading at a premium. We do not dispute the pro-risk market, but scrutiny should be increased: confirmation is not the same as cheapness. Today’s retail sales figures will test whether U.S. household demand is also part of the growth story.
White House senior trade adviser Peter Navarro has called on Europe and other western governments to take tougher action against Chinese automakers, arguing in a Politico Europe commentary that Chinese firms are making aggressive gains abroad while the West responds too weakly. He said the U.S. remains the only major auto market that has kept BYD out, but warned that the company is pressing at U.S. borders. Navarro framed the issue as an industrial contest with Beijing, saying current tariffs and policies have not stopped Chinese brands from expanding in Europe, even as legacy carmakers including Volkswagen and BMW have cut jobs and trimmed earnings guidance. Euro Stoxx 50 -0.24% to 6251, EURUSD +0.027% to 1.1466, BBG AGG Euro Government High Grade EUR +0.7bp to 3.366%.
IEA Executive Director Fatih Birol has warned that the global economy could face renewed stress if the Strait of Hormuz crisis is not resolved within weeks. He said markets are “nervous” and facing “big uncertainty” as escalating attacks threaten shipments of oil, fertilizer, natural gas and other cargoes through the key waterway. Birol stressed the strait must be “fully open, unconditionally open,” warning that prolonged disruption would hurt global economies, with developing nations and Asia most exposed. He specifically highlighted vulnerability in countries such as Bangladesh, Pakistan and India, while noting that South Korea and Japan are already affected by disruptions to Gulf energy and feedstock deliveries. He also pointed to thinning traffic, falling Saudi loadings and continued danger for commercial shipping. HH natural gas -0.684% to 2.904, Dutch TTF natural gas +0.078% to 54.395.
Asian semiconductor stocks slumped after a sharp selloff in U.S. chipmakers, with the weakness driven by profit-taking and renewed caution over lofty AI-related valuations rather than any clear deterioration in fundamentals. SK Hynix fell 11.5% in Seoul after recent extreme volatility, while Samsung Electronics dropped more than 8% and other South Korean chip names also declined. In Japan, Advantest, SoftBank Group, Tokyo Electron and Renesas Electronics all fell sharply. The move followed overnight losses in Micron, Intel, Lam Research and AMD. Market commentary pointed to negative sentiment around data center plans and memory prices, although demand for AI infrastructure and high-bandwidth memory remains strong. KOSPI -6.37% to 6821, USDKRW +0.785% to 1479.1, 10y KTB -0.8bp to 4.332%.
The BoK has raised its base rate by 25bp to 2.75% in a unanimous 7-0 decision, citing stronger-than-expected growth, sticky inflation and rising financial stability risks. The board struck a more hawkish tone, signaling that further hikes remain under consideration. It said GDP is likely to be considerably higher than forecast in May, when it was seen at 2.6%. Inflation is expected to remain elevated for a prolonged period despite lower oil prices, with core inflation now projected to exceed the May forecast of 2.4%, while headline inflation is expected to hold at 2.7%. The central bank highlighted robust semiconductor-led exports, firm investment and improving domestic demand, alongside faster house price gains, higher household debt and exchange rate volatility.
U.S. July Philadelphia Fed Business Outlook is forecast to rise to 13.0 vs. 10.3.
U.S. June retail sales advance are forecast to ease to 0.2% m/m vs. 0.9% m/m, retail sales ex auto are forecast to drop to -0.1% m/m vs. 0.8% m/m, retail sales ex auto and gas are forecast to ease to 0.4% m/m vs. 0.5% m/m.
U.S. initial jobless claims are forecast to rise to 217k vs. 215k.
U.S. July NAHB Housing Market Index is forecast to hold at 35.0 vs. 35.0.
U.S. May business inventories are forecast to ease to 0.3% m/m vs. 0.5% m/m.
U.S. June pending home sales are forecast at -0.2% m/m vs. 3.8% m/m in May.
Canada June housing starts are forecast to ease to 255.0k vs. 261.4k.
Central bank speakers: The Fed’s Lorie Logan speaks on the economy and monetary policy; the Fed’s Jeffrey Schmid speaks at Kansas City Fed Economic Forum.
U.S. Treasury sells $110bn in 4-week bills and $100bn in 8-week bills.
Mood: iFlow Mood stabilized at -0.145 after last week’s sharp deterioration. Underlying sentiment remained constructive, with continued buying of both global equities and core sovereign bonds.
FX: Flows diverged across regions. G10 currencies attracted broad inflows, while EM FX saw moderate selling, led by HUF, ZAR and KRW.
FI: Demand remained concentrated in developed markets, led by Eurozone government bonds, JGBs and U.S. Treasurys. Poland and India also attracted inflows, while selling persisted across much of APAC and Chile.
Equities: APAC led global equity inflows, driven by India and Thailand, with additional buying in Chile and Türkiye. G10 equities recorded modest outflows.
“It’s tough to find values when everybody is preferring gambling.” – Warren Buffet
“Price is what you pay; value is what you get.” – Warren Buffett, citing Benjamin Graham
Italian consumer prices were flat m/m and rose 3.0% y/y in June, down from 3.2% in May, matching the final estimate. The slowdown mainly reflected softer prices for unprocessed food, recreational and personal services, and transport services, while energy prices accelerated further, especially regulated energy. Core inflation eased marginally to 1.6% from 1.7%, and inflation excluding energy fell to 1.9% from 2.1%. Goods inflation slowed slightly to 3.3% and services to 2.6%. Using the EU’s harmonized measure, CPI also rose 3.0% y/y, and the 2026 carryover inflation rate remained at 2.6%. FTSE MIB -0.57% to 52114, EURUSD +0.43% to 1.1465, 10y BTP +2.5bp to 3.933%.
U.K. GDP rose 0.7% in the three months to May vs. the three months to February, extending a sixth straight three-month gain and matching the earlier pace of recovery. Growth was driven mainly by services, which increased by 0.7%, while construction advanced by 1.6% and production edged up 0.1%. On a m/m basis, GDP climbed 0.1% in May after a 0.1% fall in April and 0.3% growth in March. The May rise reflected a 0.3% increase in services, partly offset by declines of 0.5% in production and 0.8% in construction. FTSE 100 -0.55% to 10458, GBPUSD +0.903% to 1.3521, 10y gilt +3.5bp to 4.972%.
U.K. trade in goods figures for May showed imports rising modestly while exports increased more strongly. The value of goods imports increased by £0.5bn, or 0.8%, as higher purchases from non-EU countries more than offset a drop in imports from the EU. Goods exports rose by £1.5bn, or 4.5%, supported by gains in sales to both non-EU and EU markets. Over the three months to May, the total goods and services trade deficit widened by £4.4bn to £9.1bn, while the goods deficit widened to £60.9bn and the services surplus narrowed to £51.8bn.
The minutes from the SNB’s June decision showed the Governing Board judged monetary conditions to be appropriate and price stability not to be currently at risk. It noted that Swiss monetary conditions had eased since March as the franc depreciated, while lending and broad money growth had remained solid. Inflation was 0.6% in May, driven by imported energy costs, and the bank expected inflation to stay within the range consistent with price stability over the forecast horizon. The SNB also highlighted elevated geopolitical uncertainty and said it remained ready to intervene in foreign exchange markets if needed. SMI -0.82% to 14191, EURCHF +0.071% to 0.92491, 10y Swiss GB +0.2bp to 0.448%.
Swedish unemployment fell in June, with 344,357 people registered as unemployed and the rate falling to 6.4% from 6.9% a year earlier. The Swedish Public Employment Service said the decrease was in line with its earlier forecast and reflected broad improvement across the country and most demographic groups. Youth unemployment also eased to 7.3%, while long-term unemployment fell to 148,497. Open unemployment and activity support participation both decreased, and fewer people were newly registered as jobseekers or given redundancy notices. Norrbotten again had the strongest labor market, while Skåne, Södermanland and Västmanland recorded the highest unemployment rates. OMX -0.92% to 3122, EURSEK +0.298% to 11.022, 10y Swedish GB +0.1bp to 2.951%
Japanese household inflation expectations have reached their highest level since 2006, according to the BoJ quarterly survey released on Thursday, reinforcing expectations that the central bank will continue raising interest rates. Households now see annual inflation averaging 10.8% over the next five years, while the median expectation was unchanged at 5%. The report also showed a record 24% of households believe interest rates are already too high. Speaking in parliament earlier, BoJ Executive Director Koji Nakamura said upside price risks remain elevated and that delaying policy adjustment could hurt the economy. The BoJ benchmark rate is 1%, and traders are pricing in a 66% chance of another hike by October, ahead of the July 31 policy meeting. Nikkei -2.79% to 66836, USDJPY +0.136% to 162.11, 10y JGB +2.4bp to 2.719%.
South Korea’s authorities have announced supplementary measures on single-stock leveraged ETF/ETN products. The move is aimed at curbing overheating, strengthening investor protection and reducing the risk of further volatility in memory chip names amid rapid growth in these products since launch. New listings of single-stock products, including inverse and covered call variants, will be temporarily suspended until markets stabilize, and advertising and event marketing will be banned. Risk controls will be tightened through lower LP deviation thresholds, tougher penalties, faster designation of risky products, expanded pre-investor education and automated risk alerts. Entry requirements will also be raised, with the minimum cash deposit lifted to ₩30mn and securities no longer counted toward the requirement. Domestic trading units will be increased to 20 lots. KOSPI -6.37% to 6821, USDKRW +0.785% to 1479.1, 10y KTB -0.8bp to 4.332%.
The U.S. Treasury (USTR) has announced final action under Section 301 of the Trade Act of 1974, imposing a 25% tariff on certain goods from Brazil. The move follows a year-long investigation, which found that Brazilian measures on digital trade and electronic payment services, preferential tariffs, anti-corruption enforcement, intellectual property protection, ethanol market access and illegal deforestation are unreasonable and restrict U.S. commerce. The USTR said the issues have hurt American farmers, workers, innovators and exporters and that extensive talks and two public hearings had failed to resolve concerns. Ambassador Jamieson Greer said the tariff is intended to defend U.S. economic interests and create a level playing field, while keeping the door open for continued negotiations with Brazil over the identified trade practices. IBOVESPA -0.36% to 176011, USDBRL +0.115% to 5.0781, 10y BGB +5.5bp to 14.455%.