Market Movers: Validation
Market Movers highlights key activities and developments before the U.S. market opens each morning.
Market Movers highlights key activities and developments before the U.S. market opens each morning.

Geoffrey Yu
Time to Read: 5 minutes
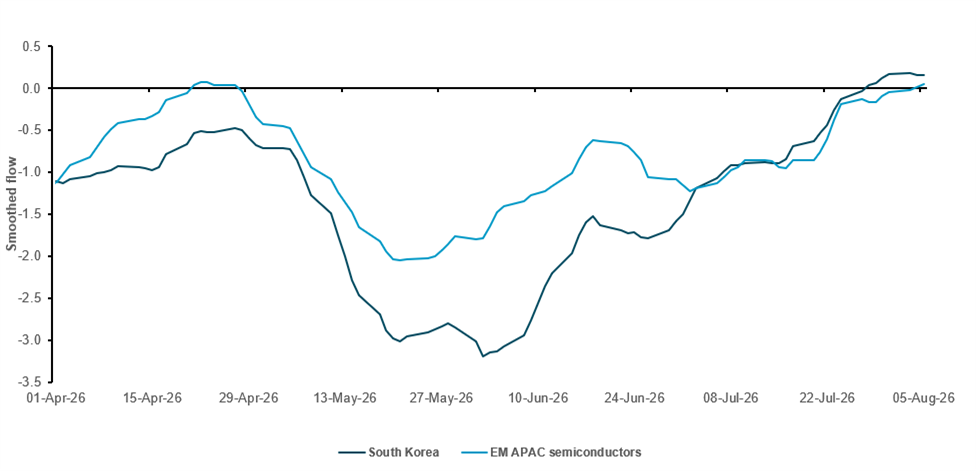
Institutional flows into South Korea and EM APAC semiconductors back to neutral
Source: BNY
Institutional South Korean equity have turned positive on a monthly smoothed basis for the first time since mid-April. Domestic purchases are leading the way. A similar signal has been established in the emerging market Asia-Pacific Semiconductor industry group (GICS level 2). The flow improvement appears to reflect three factors. First, the forced selling linked to leveraged ETFs and hedge fund deleveraging is largely complete, removing a major technical drag. The regulatory measures designed to limit retail leverage have had a clear impact. Second, foreign investors have started buying again after heavy selling earlier in the year, including several unusually large purchase sessions. Third, the semiconductor outlook has improved. Strong U.S. technology earnings, rising AI investment and better demand for memory chips have supported Samsung Electronics and SK Hynix. Reports that major producers have already sold much of their 2027 DRAM and high-bandwidth memory capacity also point to strong forward demand. However, caution is necessary as South Korean equity holdings are still very high, at the 93rd percentile of the historical range (dating back to January 2021). Institutions have not meaningfully reduced their South Korean positions despite months of net selling pressure, and the flow series is now mean-reverting toward neutral. iFlow indicates that retail participation remains strong, which may contribute to institutional caution.
Payrolls validation: Today’s non-farm payrolls report (consensus: +80k) is the clearest test of the Fed’s stance. A strong print would strengthen the case of the three FOMC dissenters and could pull markets toward pricing in two hikes this year, reopening questions around policy credibility. A weaker report would validate the Fed’s less assertive approach and reinforce the argument that market-led tightening is already doing some of the work.
Gold validates inflation vigilance: Gold has pushed back through $4,300/oz for the first time since mid-June, while central bank accumulation continues. China is again adding materially to its reserves. Gold is not a pure Fed signal, but persistent official-sector demand and renewed investor interest are reinforcing the value of inflation, currency and geopolitical hedges. That strengthens the case for the Fed to remain vigilant on price stability.
Intervention limits validated: The yen has already surrendered a substantial share of its intervention gains. Meanwhile, reports that the ECB was not informed until after the event that the U.S. Treasury sold euros to buy yen have exposed strains in policy coordination. More importantly, the subsequent reversal validates Treasury Secretary Scott Bessent’s argument that intervention is a signal, not a substitute for fundamentals. The ball is firmly back in Japan’s court.
De-escalation validated: The Iran-Oman Hormuz framework remains complicated, including potential restrictions on U.S. and Israeli shipping. Oil has rebounded on those concerns today but remains set to finish the week lower. Markets are still assigning greater probability to eventual de-escalation than to renewed full-scale disruption.
Bottom line: Today is about whether the data will validate policy or challenge it. Strong payrolls would strengthen the hawkish case; weakness would vindicate patience. Elsewhere, gold, the yen and oil show that markets are already passing judgment on policy credibility, fundamentals and diplomacy.
U.S. Senate leaders are trying to strike a deal to fund the government through to December 11 and begin the August recess, but the agenda is caught between Democratic demands to limit additional votes and Republican pressure to keep advancing President Trump’s priorities. Majority Leader John Thune wants to confirm a large package of nominees, pass the stopgap funding bill and confirm Todd Blanche as attorney general, while Democrats are offering procedural cooperation if Republicans drop votes on crypto market reform and a budget resolution tied to Iran war funding and election rules. Trump allies still want the budget process opened before the summer recess, but GOP support appears uncertain. The risk is that failure to agree could keep the Senate in session until the weekend or longer. S&P Mini +0.12% to 7744, DXY +0.051% to 99.98, 10y UST -0.6bp to 4.672%.
The U.S. decision to sell euros and buy yen in last week’s intervention has created friction with the ECB, which was reportedly informed only after the trade had already been executed. The move was unusual because Washington would typically use dollars in a joint effort with Japan to support the yen; however, selling dollars could have conflicted with the Treasury’s strong-dollar messaging. European officials viewed the euro sale as a breach of longstanding consultation norms between western monetary authorities, raising concerns about trust and coordination. The intervention helped lift the yen from near multi-decade lows, though the currency has since surrendered half of its intervention-related gains. The broader issue is whether currency policy is becoming more unilateral just as Japan, U.S. yields and inflation risks are all under pressure. Euro Stoxx 50 +0.3% to 6522, EURUSD -0.018% to 1.1523, BBG AGG Euro Government High Grade EUR -1.2bp to 3.37%.
China’s central bank has extended its gold buying streak to 21 months, adding 640,000 ounces, or around 20 tons, to reserves in July as prices touched $4300/oz overnight. The PBoC remains one of the largest official-sector buyers and has stepped up purchases after earlier price declines, reinforcing the view that China is still diversifying reserves despite higher bullion levels. Gold was on track for its biggest gain in more than six months, driven more by dip-buying and technical support than by Middle East tensions. Chinese institutional demand through local gold-backed ETFs has also strengthened. The main near-term headwind remains U.S. rate risk, with markets still pricing in a meaningful chance of a September hike. Gold +1.573% to 4306.08, silver +4.586% to 64.3636, platinum +2.599% to 1771.36.
Japan’s GPIF has reported a record quarterly gain as equity rallies overwhelmed bond weakness. This highlights the fund’s exposure to global and domestic risk assets rather than any shift toward supporting Japanese government bonds. The pension fund gained ¥24.1tn, or $152bn, in the quarter to June, an 8.2% return, lifting assets to ¥317.76tn. Foreign equities delivered the strongest return at 16.9%, while Japanese stocks rose 14.5%; foreign bonds gained 3.1%, but domestic bonds lost 1.1% as yields rose. The result comes as the government is encouraging greater domestic investment, but the GPIF’s allocation still broadly tracks its balanced model, with roughly one-quarter each in domestic bonds, domestic equities, foreign bonds and foreign equities. The share of domestic assets fell to 50.07% from 50.72% in Q1. Nikkei -0.12% to 65607, USDJPY -0.032% to 158.38, 10y JGB +1.7bp to 2.805%.
U.S. non-farm payrolls for July are forecast to improve to 80k from 57k in June. The unemployment rate is expected to remain at 4.2%, and average hourly earnings to increase by 0.3% m/m.
U.S. consumer credit is expected to jump to $11.85tn, reversing a contraction of $182bn in June.
Canadian payrolls are expected to show a net increase of 20k in July from 18.2k previously. The unemployment rate is expected to remain at 6.5%, with wage growth falling to 3.4% y/y.
Mood: iFlow Mood continued to improve thanks to further equity inflows, though it remained in risk-off territory.
FX: FX flows diverged substantially in both the G10 and EM spaces. Within the G10, EUR and GBP saw inflows while JPY and USD saw outflows. In EM, MXN and SGD saw strong inflows while CNY and BRL faced selling pressure.
FI: Globally, fixed income flows were skewed toward outflows: Norwegian, Philippine and Peruvian sovereign bonds saw outflows while Indian bonds recorded inflows.
Equities: Equity inflows were broad-based, with a large part of the moves taking place in EMs. Equities in Poland, India, Taiwan and South Africa all saw inflows. Canadian, Hungarian and Mexican equities experienced outflows.
“Nothing ever comes to one, that is worth having, except as a result of hard work.” – Booker T. Washington
“Work that amounts to anything will never be easy.” – Henry Ford
France’s Q2 unemployment rate rose to 8.3% from 8.1%, reaching its highest level since late 2020 and coming in above the 8.2% consensus estimate. The data point to a further deterioration in the labor market, reversing part of the earlier improvement seen during President Emmanuel Macron’s first term, when falling unemployment supported the government’s full-employment ambitions. The setback reflects a weaker macro backdrop after successive energy shocks, first from Russia’s invasion of Ukraine and more recently from the Iran war, which have weighed on activity and hiring. Politically, the rise in joblessness may sharpen scrutiny of Macron’s pro-business reforms and tax cuts ahead of next year’s presidential transition, especially among candidates arguing that earlier labor market gains are now fading. CAC 40 +0.21% to 8718, EURUSD -0.018% to 1.1523, 10y OAT +0.6bp to 3.939%.
Norway’s industrial production rose 0.7% q/q in Q2, with the production index at 107.4 points versus 106.7 in Q1, continuing the upward trend in place since early 2024. The gain was broad-based across sectors, led by petroleum-related supplier industries, where output rose 3.4%, and the metal industry, up 4.6%. However, the quarterly increase was dampened by weaker activity in computer and electrical equipment (-0.3%) and furniture and other manufacturing (-1.8%). Excluding petroleum-related supplier industries, industrial production rose 0.8%. Monthly data were softer, with industrial production falling 1.1% from May to June, led by machinery repair and installation, basic metals, and machinery and equipment. OSE +0.15% to 2023, EURNOK -0.243% to 10.9694, 10y NGB +1.4bp to 4.424%.
Hungary’s CPI rose 1.2% y/y in July, while prices fell 0.1% m/m, showing very subdued headline inflation despite still-firm services pressure. Food prices fell 1.1% y/y, or 4.4% excluding food and beverage-serving services, with declines in canned meat, butter, pork, fruit, cheese, vegetables, sugar and milk offsetting higher catering-related items. Energy was also disinflationary, with electricity, gas and other fuels down 4.3% y/y, led by a 10.9% fall in gas prices. Services remained the main source of inflation, rising 4.7% y/y, with strong gains in entertainment, communications, healthcare, repairs and recreation. On the month, food fell 1.0%, fuel dropped 1.3% and clothing fell 2.1%, but services rose 1.6%. Budapest SI +0.78% to 147707, EURHUF +0.4% to 366.82, 10y HGB -2bp to 5.38%.
China’s trade data for July showed exports rising nearly 24% y/y, down from 27% in June, while imports increased by 27.5%, also slower than June’s 36% gain. The trade surplus narrowed to $112.5bn from $125.6bn, suggesting that momentum eased but remained very strong by historical standards. Typhoon-related port disruption likely weighed on trade volumes, but demand for high-tech electronics, machinery, vehicles and green technology remained robust. Exports of high-tech goods rose nearly 41% in January-July, vehicle shipments jumped 55%, and electronics and machinery exports increased by 26%. The data reinforce China’s shift from low-cost manufacturing toward advanced industrial supply chains. Exports to the U.S. rose by just 2.6%, while shipments bound for the EU and Southeast Asia increased much faster. CSI 300 +0.93% to 4694, USDCNY -0.04% to 6.7486, 10y CGB -0.2bp to 1.705%.
Taiwan’s trade figures for July, measured in USD, showed exports rising 32.9% y/y to $75.30bn, while imports climbed 37.4% to $58.13bn, leaving a surplus of $17.17bn. The data point to still-strong external demand, though export growth slowed from June’s 40.3% pace. The strength remained concentrated in technology, with information, communication and audio-video products up 29.5% y/y and electronic parts up 50.5%, together accounting for almost 80% of exports. Imports also reflected the tech cycle, with electronic parts up 61.5% and ICT products up 68.6%. By destination, exports rose across major markets, led by Europe (+57.6%), South Korea (+50.8%), Japan (+41.4%), Mainland China and Hong Kong (+33.4%) and the U.S. (+25.2%). TAIEX -0.38% to 44226, USDTWD +0.174% to 32.304, 10y TGB -1bp to 1.95%.
The Philippines’ GDP grew 2.3% y/y in Q2, with activity supported mainly by services and agriculture, while industry contracted. The largest sector contributions came from wholesale and retail trade (+4.6%), education (+12.7%) and manufacturing (+2.6%). By major sector, services expanded by 4.5% and agriculture, forestry and fishing rose 2.7%, but industry fell 2.4%, pointing to a weaker production backdrop. On the demand side, household consumption grew by 2.8%, government consumption by 8.3%, exports by 12.2% and imports by 5.5%, while gross capital formation fell sharply (-9.2%). Gross national income increased by 2.2%, with net primary income from abroad up 1.0%. PSEi +0.2% to 6290, USDPHP +0.16% to 60.91, 10y PHGB +6.6bp to 7.212%.